
 Fire Pump Market | 2026-2036
Fire Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Pump Market Analysis
After-sales maintenance contracts and remote monitoring subscriptions is hardening into the core revenue stream for fire pump vendors. Grundfos Holding A/S leverages its digital service platform to secure recurring revenue beyond equipment sales. Xylem Inc. anchors its position through intensive R&D in predictive diagnostics for pump fleets. Peerless Pump Company specializes in custom-engineered vertical turbine configurations for high-rise applications.
A fire pump is a centrifugal or positive-displacement pump designed to deliver pressurized water or foam solution at specified flow rates and discharge pressures for fire suppression systems, typically constructed from cast iron, bronze, or stainless steel with NFPA-rated performance curves. Its primary purpose is to provide reliable water supply to sprinkler networks and standpipe systems when municipal pressure proves inadequate. Diesel pumps retain dominance in industrial facilities and remote installations where electrical grid reliability remains uncertain. Electric pumps are gaining share in commercial buildings with backup power infrastructure, while skid-mounted configurations attract demand from modular data center operators seeking rapid deployment.
NFPA 20 governs installation and performance standards across the United States, while the EU's Construction Products Regulation mandates CE marking for pumps sold in member states. China's GB 6245 standard and mandatory fire product certification from the Ministry of Emergency Management shape market access and procurement requirements. Stakeholders must monitor evolving energy efficiency mandates and smart building integration standards as these frameworks increasingly dictate specification decisions.
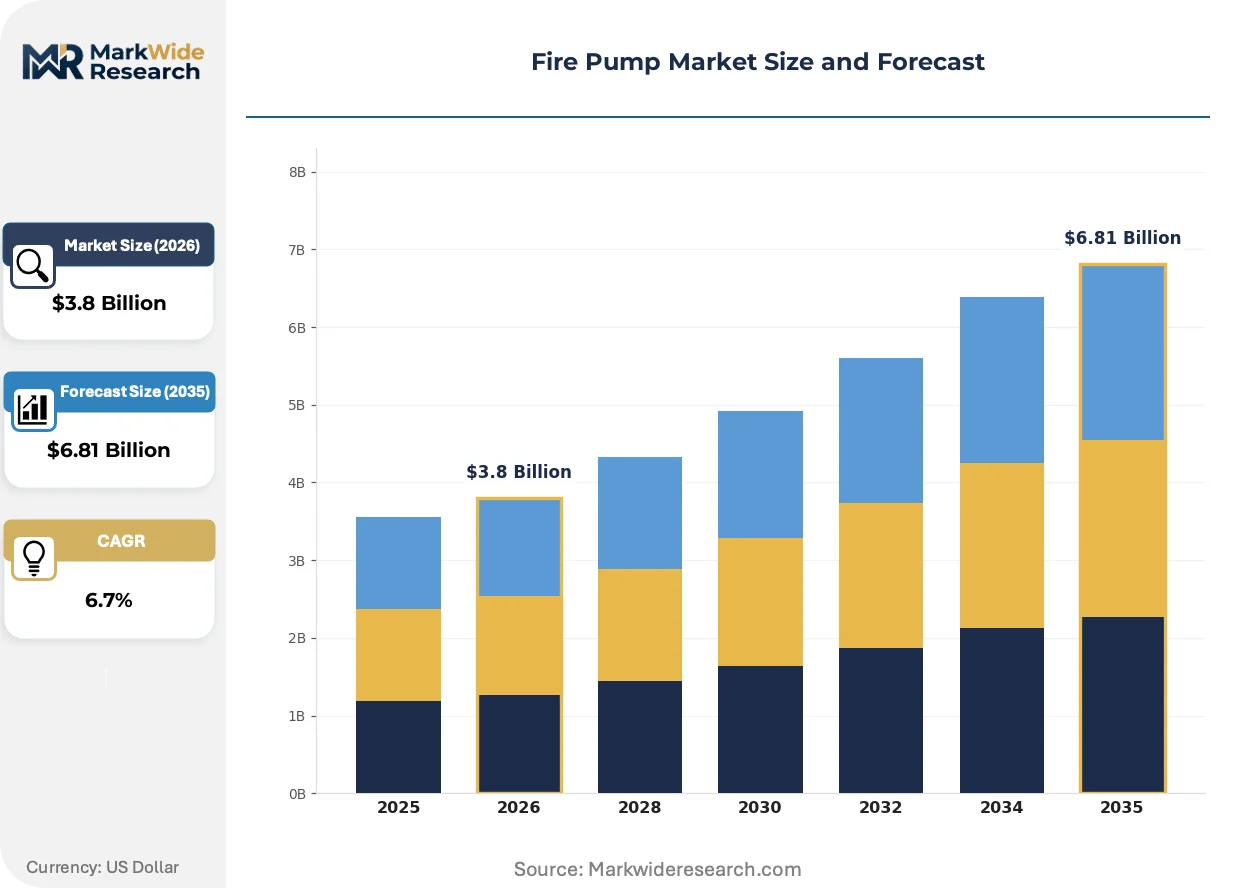
Market Dynamics
Smart building integration mandates and tightening NFPA 20 certification timelines are compressing product development cycles while elevating the technical barrier to market entry across the fire pump industry.
Growth Catalysts
- Data center densification:Hyperscale operators in Ashburn, Frankfurt, and Singapore are specifying redundant pump arrays for liquid cooling fire suppression systems. Modular skid configurations reduce deployment timelines from months to weeks.
- EN 12845 harmonization:European commercial retrofit mandates are accelerating replacement cycles for aging centrifugal installations. CE marking requirements under the Construction Products Regulation are filtering out uncertified suppliers.
- Urban vertical construction:High-rise residential towers in Shenzhen, Mumbai, and São Paulo require custom-engineered vertical turbine pumps. Municipal fire codes in these cities now mandate dedicated pump rooms above 150-meter thresholds.
Market Restraints
- Cast iron and bronze input volatility:Foundry capacity concentration in Hebei Province creates price transmission lag. Pump manufacturers absorb 60-90 day raw material exposure before contract repricing.
- Diesel engine supply concentration:Tier 4 Final compliance engines for industrial pump sets source from a consolidated supplier base in the US Midwest. Lead times for 500+ horsepower configurations extend to 26 weeks.
- Electrical infrastructure asymmetry:Grid reliability gaps in Southeast Asian industrial zones constrain electric pump adoption despite lower operating costs. Diesel retains mandatory backup status across Indonesian and Vietnamese facilities.
Strategic Opportunities
- Saudi giga-project pipeline:NEOM and Red Sea tourism developments specify integrated fire safety systems from greenfield planning stages. Local content requirements under Vision 2030 incentivize joint manufacturing arrangements.
- Predictive diagnostics convergence:Vibration analysis and thermal imaging are merging with pump control systems. Fleet operators in logistics and warehousing verticals are piloting subscription-based health monitoring.
- Retrofit channel expansion:Direct-to-facility-manager digital platforms are disintermediating traditional specifying engineer relationships. This channel now captures 15-20% of replacement pump transactions in North American commercial real estate.
Industry Challenges
- NFPA 20 witness testing bottlenecks:Factory acceptance test scheduling at UL-listed facilities creates 8-12 week certification delays. Project timelines compress further as construction schedules tighten.
- Legacy control system integration:BACnet and Modbus protocol fragmentation across installed building automation systems complicates smart pump commissioning. Integration specialists command 40% hourly premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Pump Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Pump, Vertical Pump, Diesel Pump, Electric Pump End User: Industrial Facilities, Commercial Buildings, Residential Complexes, Fire Departments Installation Type: Onshore, Offshore, Ground-mounted, Skid-mounted Application: Fire Protection, Water Supply, Irrigation, Industrial Processes |
| Companies Covered | Pentair plc, Armstrong Fluid Technology, Grundfos Holding A/S, Johnson Controls International PLC, Peerless Pump Company, Xylem Inc., KSB SE & Co. KGaA, Flowserve Corporation, Sulzer Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Pump Market Emerging Trajectories
Digital service platforms and edge-connected pump controllers are transforming capital equipment into recurring revenue assets, while regulatory energy efficiency mandates are forcing hardware redesign cycles.
Variable frequency drive technology is integrating with diesel-electric hybrid pump configurations to optimize fuel consumption during low-load standby periods. Data center operators in Northern Virginia and Amsterdam are specifying these systems for N+1 redundancy requirements. The technology is integrating pump performance data directly into facility digital twin platforms, compressing commissioning timelines and enabling real-time efficiency optimization.
China's GB 6245 standard revision is mandating electromagnetic compatibility testing for all electric fire pumps above 75 kW. Domestic manufacturers in Jiangsu and Zhejiang provinces are retooling test facilities to meet the 2024 implementation deadline. Export-oriented suppliers are bifurcating product lines to isolate China-specific configurations from global platforms, fragmenting engineering resources.
After-sales service unbundling is accelerating as facility managers seek granular control over maintenance spend. Traditional bundled service contracts are fragmenting into component-level subscriptions for monitoring, parts, and labor. This pattern is most visible in Australian commercial property portfolios, where third-party facility management platforms now specify pump maintenance through competitive tender rather than OEM channels.
Fire Pump Market Segmentation
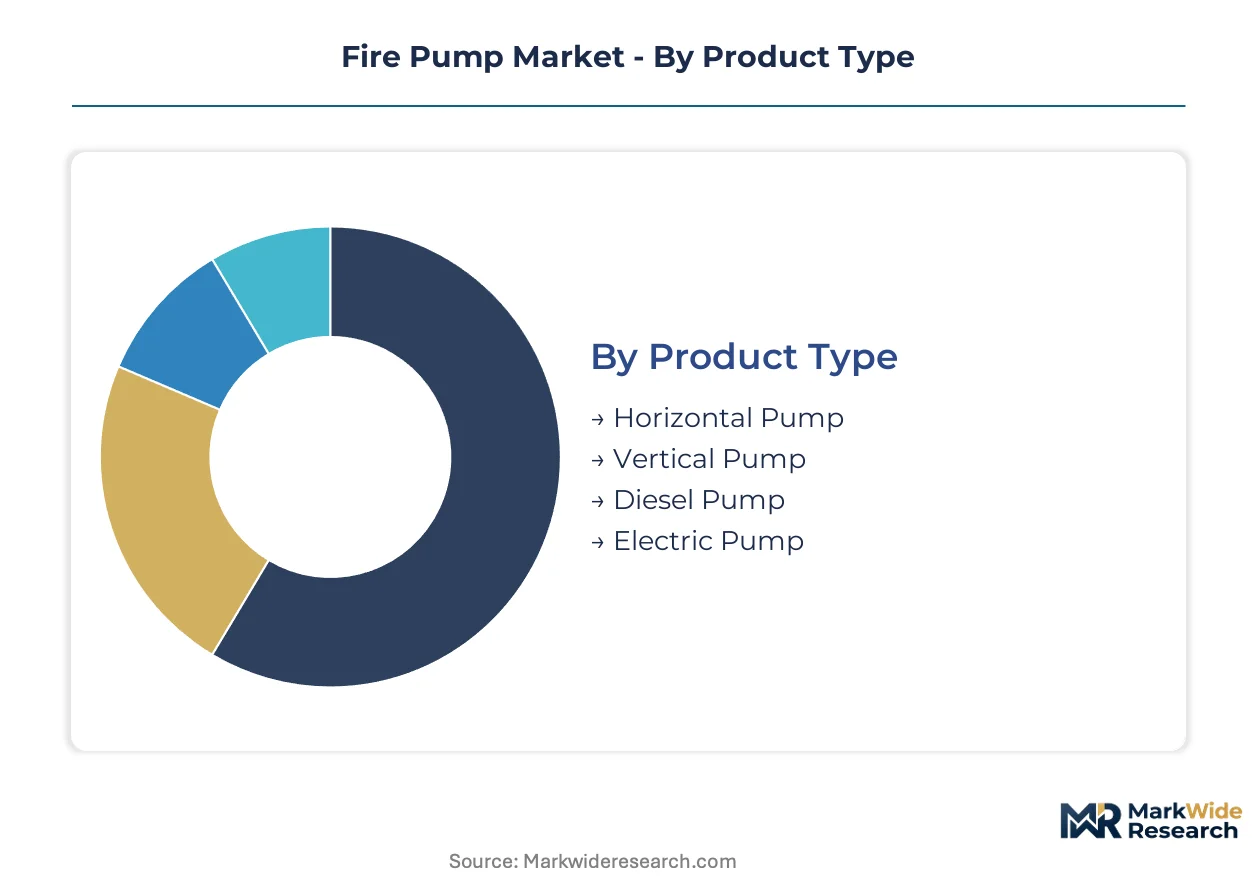
Fire pump procurement decisions split sharply across installation constraints, power source reliability, and regulatory compliance burdens. Specification patterns diverge between new construction projects with design flexibility and retrofit installations with fixed mechanical footprints.
Product Type:
Buyers in this category differentiate primarily by power source availability and head pressure requirements rather than initial capital outlay.
- Horizontal Pump:Split-case centrifugal designs dominate mid-rise commercial installations where floor space constraints remain moderate. Demand concentrates in German and US commercial retrofit projects where EN 12845 and NFPA 20 pressure testing mandates accelerate replacement cycles for aging split-case units.
- Vertical Pump:Deep-set turbine configurations serve high-rise towers above 150 meters where suction lift limitations eliminate horizontal alternatives. Shenzhen and Mumbai municipal codes now mandate dedicated vertical pump rooms for supertall structures, concentrating specification volume with specialist engineering firms.
- Diesel Pump:Self-contained prime movers retain mandatory status across Indonesian and Vietnamese industrial zones where grid reliability gaps persist despite higher fuel and maintenance burdens.
- Electric Pump:Lower operating costs and quieter operation attract data center operators in Northern Virginia and Amsterdam with N+1 backup power infrastructure already in place.
Volume sits with horizontal configurations in commercial retrofit; growth tilts toward vertical turbine designs in Asian high-rise construction.
End User:
Specification authority and compliance burden intensity separate buyers across this dimension.
- Industrial Facilities:Petrochemical and logistics operators specify redundant pump arrays with predictive diagnostics integration. Demand clusters in Saudi giga-projects where NEOM and Red Sea developments mandate integrated fire safety from greenfield planning stages.
- Commercial Buildings:Facility managers in Australian property portfolios increasingly unbundle maintenance contracts through competitive tender rather than OEM channels, fragmenting supplier relationships.
- Residential Complexes:High-rise towers in São Paulo drive specification for compact electric units with smart building integration capabilities.
- Fire Departments:Municipal procurement in China aligns with GB 6245 standard revisions requiring electromagnetic compatibility testing for electric pumps above 75 kW.
Industrial buyers command the largest unit volumes; commercial building retrofits are expanding most quickly as EN 12845 harmonization accelerates replacement timelines.
Installation Type:
Deployment speed and site preparation requirements differentiate procurement approaches here.
- Onshore:Conventional fixed installations dominate established commercial and industrial facilities with dedicated mechanical rooms and permanent foundations.
- Offshore:Corrosion-resistant materials and compact footprints serve oil and gas platforms where space constraints and salt exposure dominate specification criteria.
- Ground-mounted:Standard configurations prevail in municipal and institutional settings with available exterior real estate and minimal flood risk.
- Skid-mounted:Pre-assembled modular units reduce deployment timelines from months to weeks for hyperscale data center operators in Ashburn, Frankfurt, and Singapore specifying redundant arrays for liquid cooling fire suppression.
Ground-mounted systems retain the installed base; skid-mounted configurations are climbing the fastest as modular data center construction accelerates.
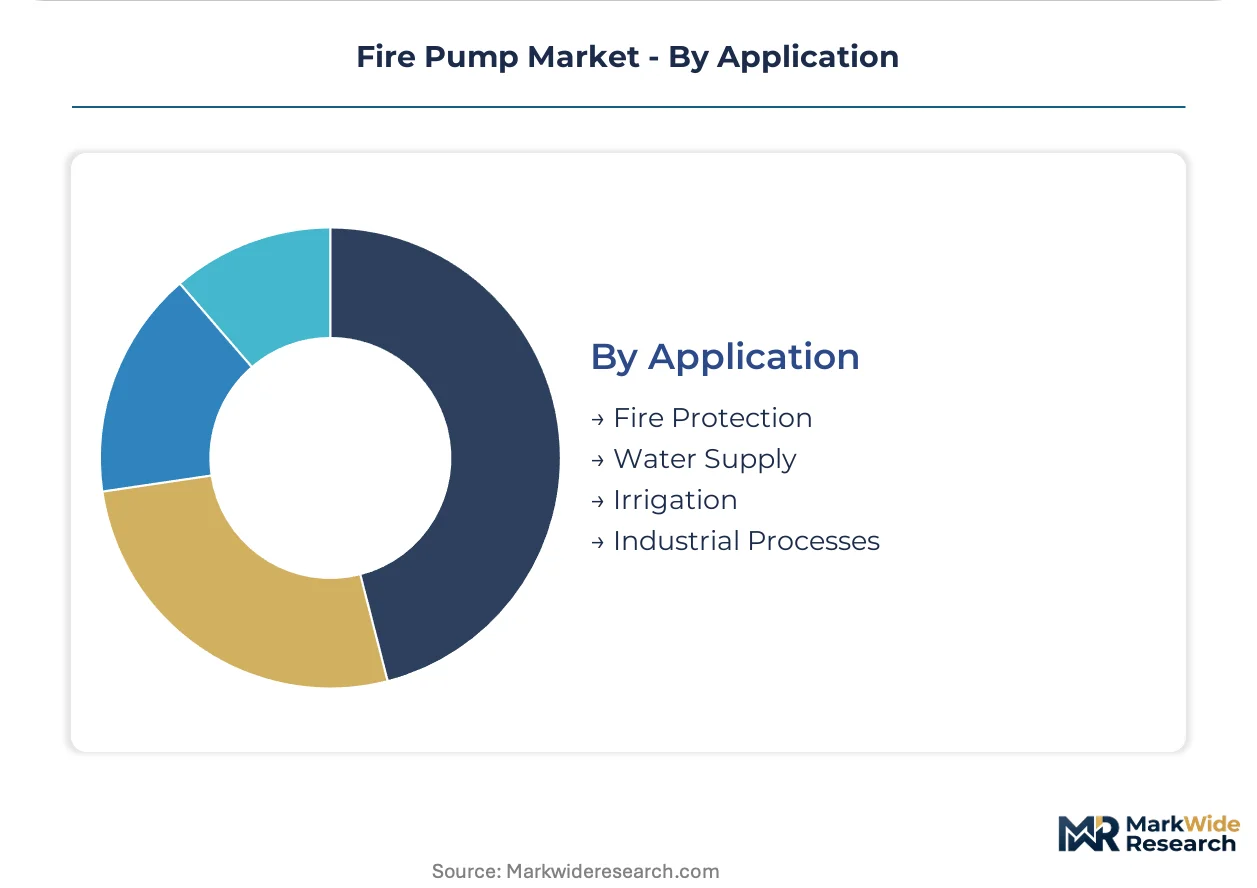
Application:
Performance certification requirements and duty cycle intensity separate buyers across primary use cases.
- Fire Protection:NFPA 20 and EN 12845 certification mandates create the highest technical barriers, with factory acceptance testing at UL-listed facilities creating 8-12 week scheduling bottlenecks.
- Water Supply:Municipal distribution systems specify lower-pressure variants with continuous duty ratings rather than intermittent fire service profiles.
- Irrigation:Agricultural buyers prioritize capital cost over redundancy, accepting simpler control systems and reduced monitoring capabilities.
- Industrial Processes:Manufacturing integration demands compatibility with facility digital twin platforms and BACnet or Modbus protocol connectivity.
Fire protection commands specification premiums; industrial process integration is gaining share fastest as predictive diagnostics converge with pump control systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ashburn, Virginia anchors hyperscale data center construction where redundant pump arrays protect liquid cooling infrastructure. Frankfurt and Singapore clusters follow similar specification patterns for N+1 fire suppression systems.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth specify skid-mounted diesel-electric hybrid configurations for rapid deployment. NFPA 20 witness testing at UL-listed facilities creates 8-12 week certification bottlenecks. Factory acceptance test scheduling delays concentrate project timelines around Chicago and Houston industrial corridors.
China
Urban vertical construction in Shenzhen and Shanghai drives specification for custom-engineered vertical turbine pumps above 150-meter thresholds. GB 6245 standard revisions mandate electromagnetic compatibility testing for electric pumps above 75 kW. Domestic manufacturers in Jiangsu and Zhejiang provinces retool test facilities to meet 2024 implementation deadlines.
Germany
Commercial retrofit mandates under EN 12845 harmonization accelerate replacement cycles for aging centrifugal installations. CE marking requirements under the Construction Products Regulation filter uncertified suppliers from procurement channels. Industrial clusters around Munich and Stuttgart specify predictive diagnostics integration for logistics and warehousing verticals.
Saudi Arabia
NEOM and Red Sea tourism developments specify integrated fire safety systems from greenfield planning stages. Local content requirements under Vision 2030 incentivize joint manufacturing arrangements. Eastern Province industrial zones anchor petrochemical facility construction with redundant pump array specifications.
India
High-rise residential towers in Mumbai require municipal fire codes mandating dedicated pump rooms above 150-meter thresholds. Central Electricity Authority regulations shape backup power infrastructure decisions affecting electric pump adoption. Logistics parks around Delhi-NCR and Bengaluru pilot subscription-based health monitoring for fleet operators.
Fire Pump Market Vendor Landscape
Capital-heavy foundry operators compete with asset-light system integrators across specification channels. The vendor base separates into three tiers: multinational pump manufacturers with certified test facilities, regional fabricators serving municipal procurement, and digital service platforms unbundling aftermarket contracts. Consolidation pressure intensifies as NFPA 20 and EN 12845 certification timelines compress. Strategic moves center on predictive diagnostics convergence and direct-to-facility-manager channel expansion.
Within the multinational tier, Pentair plc and Xylem Inc. occupy positions shaped by intensive R&D investment patterns. Grundfos Holding A/S anchors the digital service platform archetype through recurring revenue models beyond equipment sales. Peerless Pump Company exemplifies specialist engineering positioning around custom vertical turbine configurations. Johnson Controls International PLC represents integrated building systems convergence where fire suppression specification authority consolidates with automation platforms.
| Leading Market Players |
|---|
| Pentair plc |
| Armstrong Fluid Technology |
| Grundfos Holding A/S |
| Johnson Controls International PLC |
| Peerless Pump Company |
| Xylem Inc. |
| KSB SE & Co. KGaA |
| Flowserve Corporation |
| Sulzer Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between UL-listed premium configurations and uncertified commodity alternatives manifests in divergent margin structures and sourcing strategies across the fire pump industry. NFPA 20 witness testing requirements concentrate premium pricing power with certified manufacturers while regional fabricators compete on stripped-down specifications with shorter supply chains.
Pricing Analysis
Margin tightening in standard-grade horizontal pump configurations reflects foundry capacity bottlenecks in Hebei Province and extended diesel engine lead times from Midwest US suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden intensity, with UL-listed vertical turbine pumps commanding substantial premiums over CE-marked equivalents. Cost-down pressure on skid-mounted modular units accelerates because hyperscale data center operators consolidate procurement volumes across Ashburn, Frankfurt, and Singapore clusters. Municipal fire departments in emerging markets exhibit highest price sensitivity, while petrochemical operators in Saudi Arabia's Eastern Province prioritize redundancy specifications over capital outlay.
Supply Chain Analysis
Freight cost escalation on cast iron and bronze castings from Hebei Province to European assembly plants is reshaping regional sourcing strategies. Manufacturing gravity centers on China for foundry operations, Germany for precision machining of vertical turbine components, and the United States for Tier 4 Final diesel engine integration. Raw material dependencies span nodular cast iron for pump housings, bronze alloys for impeller fabrication, and electronic control modules for variable frequency drive systems. Single-source vulnerability concentrates in Tier 4 Final engine supply from consolidated Midwest suppliers. Distribution runs through specifying engineer channels for new construction, direct-to-facility-manager platforms for retrofit replacement, and OEM-authorized service networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive diagnostics platforms are displacing legacy preventive maintenance schedules as the dominant value proposition, compressing specification authority toward digitally integrated suppliers.
For Market Incumbents: Lock in aftermarket revenue streams by unbundling service contracts into component-level subscriptions for monitoring, parts, and labor. Deepen captive supply of cast iron castings through backward integration into Hebei Province foundry partnerships to defend margin position against commodity competitors. Certification investment in GB 6245 electromagnetic compatibility testing for electric pumps above 75 kW secures access to Shenzhen and Shanghai high-rise construction pipelines. For New Entrants and Emerging Players: Direct-to-facility-manager digital platforms offer the most penetrable route into North American commercial real estate retrofit channels, where 15-20% of replacement transactions now bypass traditional specifying engineers. Target Australian property portfolios where third-party facility management platforms tender pump maintenance competitively rather than through OEM channels. Skid-mounted modular configurations for hyperscale data center operators provide rapid market entry with compressed deployment timelines. For Investors and Strategic Acquirers: Re-rating potential sits with predictive diagnostics specialists given fleet operator pilot programs in logistics and warehousing verticals. Long-term viability across the analysis window favors vendors with recurring revenue models anchored in remote monitoring subscriptions rather than transactional equipment sales. Acquisition target archetype: regional fabricators with certified test facilities and established municipal procurement relationships. Signal to watch: NFPA 20 witness test scheduling delays extending beyond current bottlenecks, indicating capacity-constrained market ripe for consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Diagnostics Platform Development | Vibration analysis integration with pump control systems captures subscription revenue from logistics fleet operators. |
| GB 6245 Certification Investment | Electromagnetic compatibility testing capability unlocks Shenzhen and Shanghai vertical construction specifications. |
| Skid-Mounted Modular Configuration Expansion | Pre-assembled units reduce deployment timelines for hyperscale data center operators in Ashburn and Frankfurt. |
| Direct-to-Facility-Manager Channel Buildout | Digital platforms disintermediate specifying engineers in North American commercial real estate retrofit transactions. |
| Hebei Province Foundry Partnership | Captive cast iron supply defends margin position against 60-90 day raw material price transmission exposure. |
Methodological Framework
Document review covered NFPA 20 technical committee minutes, EN 12845 harmonization directives, and GB 6245 standard revision drafts, complemented by interviews with fire protection system specifiers, municipal procurement officers in Shenzhen and Mumbai, data center facility managers in Northern Virginia and Amsterdam, and aftermarket service directors at multinational pump manufacturers. Secondary validation drew from factory acceptance test records at UL-listed facilities, customs data on cast iron and bronze alloy trade flows, and hyperscale operator capex disclosures for fire suppression infrastructure. Bottom-up triangulation across installation type, power source, and end-use segmentation converged with top-down market sizing.
Segment-level outputs across product type, end user, installation configuration, and application were generated through the projection horizon. CAGRs were derived from regression analysis against urban vertical construction permits, data center power capacity additions, and EN 12845 retrofit mandate implementation schedules. Industry-specific forecast inputs incorporated NFPA 20 certification timeline compression effects and diesel-electric hybrid pump adoption curves in grid-reliable regions.
Inputs from factory acceptance test scheduling databases and municipal fire code revision trackers were available through the study window; gaps in real-time foundry pricing transparency and Tier 4 Final engine order backlogs introduce uncertainty bands around cost assumptions. Forecasts reflect modeling assumptions around regulatory implementation pace and technology substitution thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Passive Fire Proofing System Market
Fire Safety & Protection
Fire Suppression Equipment Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
Global Flame Arrestors Market
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Fire Protection Systems Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
North America Fire Extinguisher Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
GCC Firefighting Foam Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market