
 Europe Adenomyosis Drugs Market | 2026-2036
Europe Adenomyosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Adenomyosis Drugs Market Foresight
European pharmaceutical manufacturing capacity for hormonal therapies is rebalancing after pandemic-era supply disruptions. Bayer AG leverages its established GnRH agonist portfolio to sustain market presence across Germany and France. AbbVie Inc. specializes in advanced hormonal formulations that address unmet needs in severe adenomyosis cases. Sanofi competes through broad distribution networks that reach specialty clinics in Southern and Eastern Europe.
Adenomyosis drugs encompass pharmaceutical agents designed to manage the benign invasion of endometrial tissue into the myometrium, typically formulated as oral tablets, injectable depots, or intrauterine delivery systems that modulate estrogen-progesterone signaling to reduce dysmenorrhea and menorrhagia. Hormonal therapy dominates prescription volumes due to its efficacy in suppressing endometrial proliferation, while GnRH agonists command premium positioning for patients refractory to first-line interventions. The intrauterine route of administration is gaining traction among gynecologists seeking localized drug delivery with minimized systemic exposure.
EMA's centralized marketing authorization procedures govern new molecular entities entering the European adenomyosis landscape, while national regulators such as ANSM in France and BfArM in Germany interpret reimbursement eligibility for off-label hormonal applications. REACH compliance shapes excipient selection and manufacturing site qualifications for sustained-release formulations. Stakeholders must monitor how the EU pharmaceutical strategy for critical medicines reshapes API sourcing requirements and batch-release testing protocols across member states.
Market Dynamics
EMA's evolving guidance on GnRH agonist cardiovascular safety profiles is forcing gynecology departments across France, Germany, and Italy to restructure hormonal therapy protocols. This regulatory pressure is concentrating prescribing authority in specialized endometriosis centers and accelerating the shift toward localized intrauterine delivery systems that minimize systemic exposure.
Growth Catalysts
- REACH compliance frameworks:The EU's chemical safety regulation is standardizing excipient quality for sustained-release hormonal formulations, enabling cross-border manufacturing scale-up.
- Western European reimbursement pools:France's ANSM and Germany's BfArM have expanded chronic gynecological condition coverage, unlocking patient access to second-line GnRH therapies.
- Intrauterine drug delivery:This localized administration route is reducing systemic side-effect profiles and attracting gynecologists seeking outpatient treatment alternatives.
Market Restraints
- API sourcing concentration:Active pharmaceutical ingredient production for synthetic progestins clusters in a limited set of contract manufacturers, creating supply vulnerability.
- EMA cardiovascular safety requirements:Extended monitoring mandates for GnRH agonists are lengthening clinical trial timelines and raising development costs.
- Hormonal therapy substitution:Non-pharmacological interventions including MRI-guided focused ultrasound are capturing select patient segments in premium reimbursement markets.
Strategic Opportunities
- Eastern European access expansion:Poland, Hungary, and the Czech Republic present underpenetrated demand where specialty clinic networks remain nascent.
- CSRD sustainability reporting:The EU's corporate sustainability directive is creating procurement preference for hormonal therapies with verified green chemistry supply chains.
- Telemedicine channel integration:Remote gynecological consultations are enabling direct-to-patient prescription fulfillment for maintenance hormonal regimens.
Industry Challenges
- Specialized formulation expertise:Sustained-release depot manufacturing requires rare combination skills in polymer science and sterile processing.
- MDR compliance timelines:The EU Medical Device Regulation's reclassification of drug-device combination products is creating certification bottlenecks for intrauterine systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Adenomyosis Drugs Market |
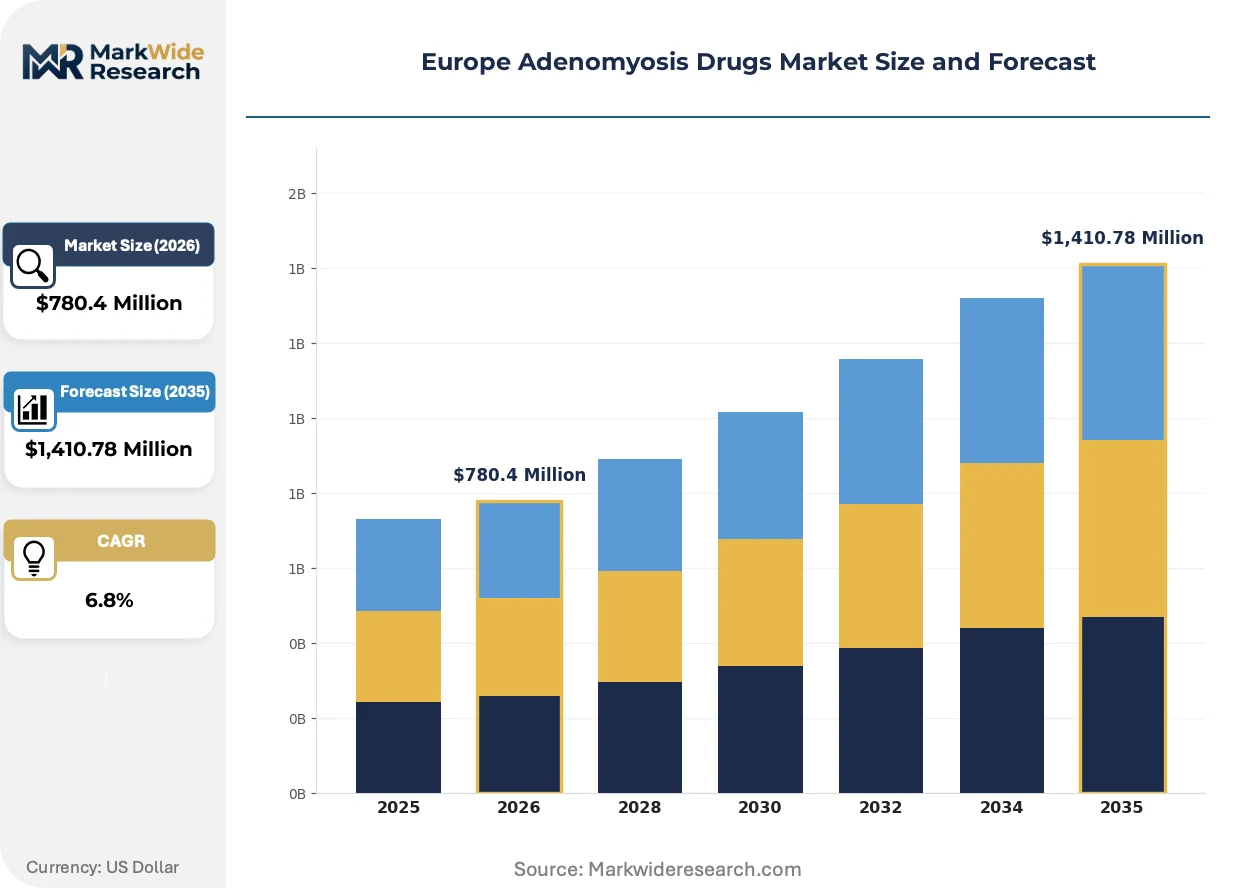
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,410.78 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Non-Steroidal Anti-Inflammatory Drugs, Hormonal Therapy, GnRH Agonists, Danazol Route of Administration: Oral, Injectable, Transdermal, Intrauterine End User: Hospitals, Specialty Clinics, Homecare Settings, Pharmacies Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Others |
| Companies Covered | Bayer AG, F. Hoffmann-La Roche Ltd, Novartis AG, Johnson & Johnson, Pfizer Inc., AbbVie Inc., Sanofi, Ferring B.V., Merck KGaA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Adenomyosis Drugs Market Shifts & Advancements
Pharmaceutical delivery architectures are fragmenting as clinicians demand precision targeting over systemic exposure. This shift is compressing the dominance of oral hormonal tablets and elevating localized administration technologies that align with outpatient care models.
Intrauterine levonorgestrel-releasing systems are decentralizing treatment delivery from hospital-based infusion centers to ambulatory gynecology practices. Community clinics in the Netherlands and Belgium are adopting these devices for same-day insertion protocols. The technology is decentralizing patient flow management and reducing specialist consultation backlogs across Northern European healthcare networks.
REACH authorization procedures for novel excipients in sustained-release matrices are tightening purity specifications for European manufacturing sites. The regulation is forcing reformulation investments among depot injection producers. German and French contract manufacturers are responding by consolidating batch-release testing capabilities under single qualified site structures.
Patient-managed switching between hormonal modalities is shortening therapy lifecycle expectations. Gynecology practices in Spain and Portugal are unbundling treatment phases into discrete prescription episodes rather than continuous care relationships. This behavioral shift is most visible in Southern European markets where public health system fragmentation has already accustomed patients to provider mobility.
Europe Adenomyosis Drugs Market Segmentation
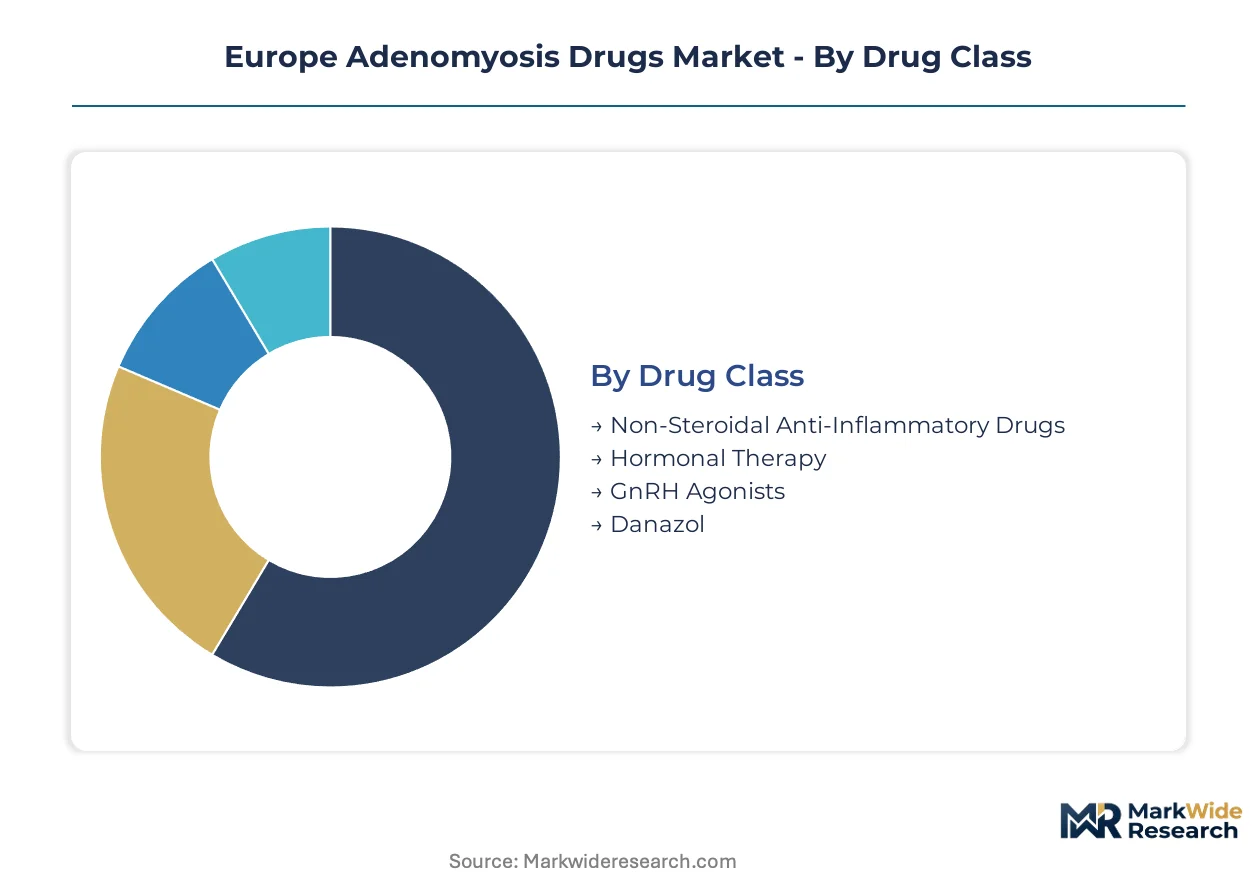
Adenomyosis treatment protocols fragment across four structural dimensions that determine prescribing authority, reimbursement pathways, and manufacturing investment requirements. Each segmentation axis carries distinct capital intensity profiles and regulatory compliance burdens that shape competitive positioning.
Drug Class:
Hormonal therapy and GnRH agonists demand the heaviest upfront investment in sterile manufacturing infrastructure and long-term cardiovascular safety surveillance mandated by EMA guidance.
- Hormonal Therapy:Synthetic progestins and combined oral contraceptives modulate estrogen-progesterone signaling to suppress endometrial proliferation. Demand concentrates in France and Germany where ANSM and BfArM reimbursement frameworks cover chronic gynecological conditions; the segment faces substitution pressure from MRI-guided focused ultrasound in premium markets.
- GnRH Agonists:Depot formulations of leuprorelin and goserelin achieve medical menopause through pituitary desensitization. Italian and Spanish gynecology departments are expanding protocols for severe refractory cases despite EMA cardiovascular monitoring requirements that lengthen clinical development timelines.
- Non-Steroidal Anti-Inflammatory Drugs:First-line dysmenorrhea management with ibuprofen and naproxen requires minimal specialized manufacturing.
- Danazol:Androgen derivative with limited contemporary use due to virilizing side-effect profiles and restricted formulary access.
Hormonal therapy absorbs the bulk of installed capacity; GnRH agonists are expanding most quickly as specialized endometriosis centers consolidate prescribing authority.
Route of Administration:
Injectable depots and intrauterine systems carry the steepest formulation complexity and polymer science expertise requirements, creating capability scarcity among European contract manufacturers.
- Intrauterine:Levonorgestrel-releasing systems enable localized endometrial suppression with minimized systemic exposure. Dutch and Belgian community clinics are adopting same-day insertion protocols that decentralize patient flow from hospital infusion centers.
- Injectable:Sustained-release depots require rare combinations of sterile processing and biodegradable polymer matrix expertise. German and French manufacturers are consolidating batch-release testing under single qualified site structures to meet REACH purity specifications.
- Oral:Tablet formulations dominate prescription volumes but face compression as clinicians prioritize precision targeting over systemic exposure.
- Transdermal:Patch delivery systems remain niche due to variable absorption kinetics and limited gynecologist familiarity.
Oral administration retains the largest patient base; intrauterine delivery is climbing the fastest as ambulatory care models spread across Northern Europe.
End User:
Hospital-based administration demands the most intensive regulatory compliance infrastructure, while homecare and pharmacy channels require lighter capital deployment but fragmented logistics networks.
- Specialty Clinics:Concentrated expertise in endometriosis and adenomyosis management drives protocol standardization. Networks in France, Germany, and Italy are restructuring hormonal therapy pathways in response to EMA safety guidance.
- Hospitals:Academic medical centers handle complex refractory cases and GnRH agonist initiation. Southern European public health system fragmentation has shortened therapy lifecycle expectations into discrete prescription episodes.
- Homecare Settings:Self-administered oral regimens and telemedicine-integrated maintenance protocols are expanding in Spain and Portugal.
- Pharmacies:Dispensing functions are fragmenting across retail, hospital, and online channels with varying reimbursement mechanics.
Hospitals anchor the highest-acuity treatment volume; specialty clinics are gaining share fastest as prescribing authority concentrates in dedicated endometriosis centers.
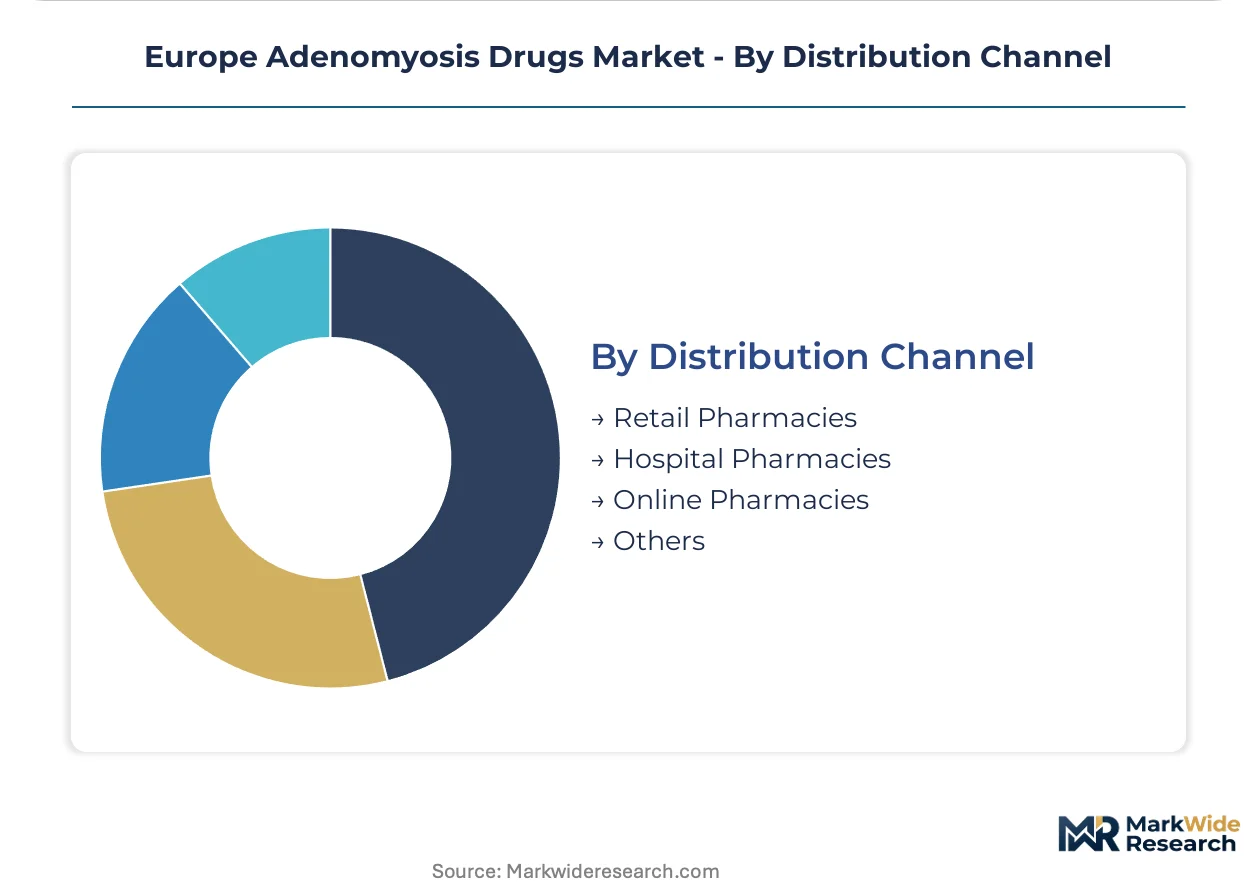
Distribution Channel:
Hospital pharmacy integration requires the most substantial cold-chain and controlled-substance infrastructure investment, while online channels demand lighter physical assets but intensive digital compliance frameworks.
- Hospital Pharmacies:Captures GnRH agonist and intrauterine system dispensing tied to procedural reimbursement. ANSM and BfArM frameworks in France and Germany channel chronic gynecological therapies through institutional procurement.
- Retail Pharmacies:Dominates oral hormonal therapy fulfillment with established patient counseling protocols. Eastern European markets in Poland and Hungary present underpenetrated demand where specialty clinic networks remain nascent.
- Online Pharmacies:Telemedicine channel integration is enabling direct-to-patient prescription fulfillment for maintenance regimens in Northern European markets.
- Others:Includes specialty distributor arrangements for rare disease protocols and clinical trial supply chains.
Hospital pharmacies handle the most complex therapy categories; online channels are expanding most quickly as remote gynecological consultations normalize across the continent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic progestin API production clusters in Northern Italy and the Rhine-Ruhr corridor anchor pharmaceutical supply security for hormonal therapies across the continent.
Germany
BfArM reimbursement frameworks for chronic gynecological conditions sustain patient access to second-line GnRH therapies. The country's national pharmaceutical regulator interprets EMA cardiovascular safety guidance for depot formulation prescribing. The Rhine-Ruhr manufacturing corridor hosts sterile processing facilities consolidating batch-release testing under REACH-compliant site structures.
France
ANSM expanded coverage pools for adenomyosis management drive demand concentration in Île-de-France and Auvergne-Rhône-Alpes. The national drug safety agency channels chronic hormonal therapies through hospital pharmacy procurement networks. Lyon-based specialty clinic networks are restructuring protocols in response to evolving EMA guidance on GnRH agonist safety profiles.
Italy
Lombardy and Emilia-Romagna gynecology departments are expanding hormonal therapy protocols for severe refractory cases. The national pharmaceutical regulator, AIFA, coordinates with EMA on centralized marketing authorization procedures for new molecular entities. Milan's academic medical centers anchor prescribing authority concentration as specialized endometriosis centers consolidate regional patient flows.
Netherlands
Community clinics in Randstad cities are adopting same-day intrauterine system insertion protocols that decentralize patient flow from hospital infusion centers. The Dutch national pharmaceutical regulator, CBG-MEB, aligns with EMA on drug-device combination product classification under MDR timelines. Utrecht's ambulatory care networks exemplify the Northern European shift toward localized drug delivery with minimized systemic exposure.
Poland
Warsaw and Krakow present underpenetrated demand where specialty clinic networks for adenomyosis management remain nascent. The national pharmaceutical regulator, URPL, interprets EMA guidance for off-label hormonal applications in emerging markets. Regional distributors are building reach into hospital pharmacies as Western European reimbursement models extend eastward.
Europe Adenomyosis Drugs Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and distribution reach in the Europe adenomyosis drugs landscape. The vendor base organizes into three tiers: integrated pharmaceutical conglomerates with GnRH agonist portfolios, mid-cap hormonal therapy specialists, and regional distributors with clinic network relationships. Dominant competitive moves include M&A activity targeting sustained-release manufacturing capabilities and strategic partnerships securing API supply continuity.
Among Germany-based integrated pharmaceutical groups, Bayer AG and Merck KGaA exemplify the scale-driven archetype with established European distribution infrastructure. AbbVie Inc. represents the specialty biopharmaceutical positioning focused on advanced hormonal formulations. These three anchors illustrate how competitive positioning fragments across manufacturing scale, therapeutic specialization, and geographic coverage depth.
| Leading Market Players |
|---|
| Bayer AG |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Johnson & Johnson |
| Pfizer Inc. |
| AbbVie Inc. |
| Sanofi |
| Ferring B.V. |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Intrauterine system manufacturing is consolidating sterile polymer processing capabilities in Germany and France, compressing production economics for localized hormonal delivery while elevating cost barriers for depot injection competitors. This technological shift simultaneously rewards REACH-compliant excipient sourcing and penalizes oral tablet producers facing margin erosion from generic substitution.
Pricing Analysis
Service bundling separates GnRH agonist prescribing from intrauterine device insertion protocols, with hospital pharmacy procurement in France and Germany absorbing procedural reimbursement while retail channels handle unbundled oral therapies. Three-tier pricing structure across premium depot formulations, standard oral regimens, and economy generic progestins reflects EMA cardiovascular certification tiers and batch-release testing intensity. Cost compression in oral hormonal segments runs through ANSM and BfArM generic substitution mandates. Price-sensitive patient populations cluster in Southern European public health systems, while Northern European private clinic networks exhibit lower elasticity for same-day insertion services.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr corridor and Northern Italy anchor hub-and-spoke patterns reaching hospital pharmacies across Western Europe. Active pharmaceutical ingredient production for synthetic progestins concentrates in Italy, Germany, and Switzerland, drawing from norethisterone and levonorgestrel precursor streams. Single-source vulnerability in biodegradable polymer matrices for sustained-release depots creates exposure to REACH authorization delays. Distribution runs through specialty pharmaceutical wholesalers with cold-chain capabilities serving academic medical centers and endometriosis clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe adenomyosis drugs market is becoming a vertical-integration race, with manufacturers capturing sterile formulation expertise and API supply continuity as the decisive upstream lever.
For Market Incumbents: Lock in sustained-release manufacturing capabilities through consolidation of batch-release testing sites under REACH-compliant structures in Germany and France. Defend against MRI-guided focused ultrasound substitution by embedding intrauterine system insertion protocols within specialty clinic networks. Channel control through hospital pharmacy procurement relationships in ANSM and BfArM reimbursement frameworks remains the priority defensive position. For New Entrants and Emerging Players: Enter via telemedicine-integrated maintenance regimens for oral hormonal therapies in Spain and Portugal, where public health system fragmentation has accustomed patients to provider mobility. Eastern European markets in Poland and Hungary present the most penetrable white-space, with nascent specialty clinic networks and extending Western reimbursement models. A direct-to-patient prescription fulfillment angle bypasses entrenched hospital pharmacy gatekeepers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated pharmaceutical conglomerates seeking GnRH agonist portfolio expansion. The five-to-ten-year viability window favors targets with verified green chemistry supply chains under CSRD sustainability reporting frameworks. Acquisition target archetype: mid-cap hormonal therapy specialists with sterile depot manufacturing capabilities and established EMA regulatory relationships. Watch EMA cardiovascular safety guidance evolution as the inflection signal for GnRH agonist development timelines and valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Consolidated batch-release testing under single REACH-qualified sites reduces regulatory compliance overhead for depot producers. |
| Regulatory Approval Pathway | EMA centralized marketing authorization procedures govern new molecular entities entering the European adenomyosis landscape. |
| Backward Integration | Captive supply of synthetic progestin APIs mitigates concentration risk among Northern Italian contract manufacturers. |
| Strategic Partnership | Telemedicine channel integration enables direct-to-patient prescription fulfillment for maintenance hormonal regimens. |
| Reimbursement Strategy | ANSM and BfArM framework alignment unlocks patient access to second-line GnRH therapies in France and Germany. |
Research Methodology
Independent corroboration across EMA submission databases, hospital procurement records, and REACH authorization filings underwrites the qualitative findings. Primary interviews with drug development executives, regulatory affairs leads, hospital pharmacy procurement managers, and payer access specialists informed prescribing pattern analysis. Secondary validation drew from ClinicalTrials.gov cardiovascular safety disclosures, ANSM and BfArM reimbursement bulletins, and Cefic chemical industry reports. Bottom-up patient flow modeling and top-down pharmaceutical market sizing triangulated volume estimates across the analysis window.
Comparable-period anchoring tied the projection horizon to historical GnRH agonist adoption curves and intrauterine system insertion rate trajectories. The analytical framework segmented by drug class, route of administration, end user, and distribution channel, with regional regulatory clusters as an additional modeled dimension. CAGRs were derived from therapy lifecycle expectations and patient-managed switching behavior patterns. Forecast inputs incorporated EMA cardiovascular monitoring mandate compliance timelines and CSRD sustainability reporting adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA safety guidance revision scenarios or API supply disruption events. Outputs reflect documented assumptions regarding reimbursement framework stability and specialty clinic network expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Global Anti Epileptic Drugs for Pediatrics Market
Pharmaceuticals
Global Peptide Cancer Vaccine Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Global HER2 Antibodies Market
Pharmaceuticals
Global Onychomycosis Treatment Market
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Flunarizine Hydrochloride Market
Pharmaceuticals
Oligonucleotide Therapeutics Market
Pharmaceuticals
Global Pharmerging Market