
 Topical Drugs CDMO Market | 2026-2036
Topical Drugs CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Topical Drugs CDMO Market Analytics
The topical drugs CDMO sector is restructuring around a sharp split between premium complex-formulation services and commodity semi-solid manufacturing. High-barrier transdermal and sustained-release programs command pricing multiples that basic cream and ointment production cannot match. Piramal Pharma Solutions leverages integrated formulation and analytical capabilities across multiple continents. DPT Laboratories, LTD anchors U.S.-based capacity for semi-solid and liquid dosage forms. Cambrex Corporation differentiates through specialized potent compound handling and containment infrastructure.
Topical drugs CDMOs provide outsourced development and manufacturing of semi-solid and transdermal pharmaceutical products, encompassing formulation design, process scale-up, and commercial production of creams, ointments, gels, and lotions with defined rheological profiles and skin-permeation targets. Their primary purpose is to enable pharmaceutical and biotech companies to bring dermatology, pain management, and wound care therapies to market without investing in dedicated semi-solid manufacturing assets. The therapy area dimension shows dermatology and pain management segments carrying the deepest margin pools due to chronic-use prescribing and premium pricing dynamics, while sustained-release delivery modes represent the fastest-expanding technical frontier as developers pursue improved patient adherence. Creams and ointments remain the most mature product type category, with gels capturing growing share in cosmetically oriented patient populations.
FDA enforces stringent Q1/Q2 sameness requirements for topical generic approvals under its ANDA pathway, compelling CDMOs to invest in sophisticated analytical method development. EMA's MDR and REACH frameworks govern excipient safety and device-drug combination classifications across European development programs. ISO 13485 and ICH Q10 standards further shape quality management expectations for transdermal patch manufacturing. Stakeholders must monitor how evolving bioequivalence guidance for complex generics reshapes CDMO selection criteria and capacity allocation decisions.
Market Dynamics
FDA's Q1/Q2 sameness requirements for topical generic bioequivalence are forcing CDMOs to rebuild analytical capabilities around rheological fingerprinting and in vitro release testing, compressing margins for undifferentiated semi-solid manufacturers while rewarding partners with validated complex-formulation platforms.
Growth Catalysts
- Specialty dermatology pipeline expansion:Boston-area biotechs and New Jersey-based legacy pharma firms are accelerating outsourcing of transdermal programs to partners with proven scale-up capabilities.
- EMA MDR excipient safety mandates:European device-drug combination classifications are pushing developers toward CDMOs with established containment infrastructure for combination products.
- Sustained-release delivery innovation:Chronic-use pain management therapies require advanced matrix formulation expertise that captive manufacturing lacks.
Market Restraints
- High-purity excipient supply concentration:Pharmaceutical-grade polymer and permeation enhancer supply chains concentrate among limited German and Swiss chemical suppliers.
- Containment infrastructure capex intensity:Potent compound handling requires dedicated isolator technology and facility hardening that locks capital for extended depreciation cycles.
- REACH framework compliance friction:ECHA's evolving substance restrictions create registration bottlenecks for novel excipients entering European development programs.
Strategic Opportunities
- Indian CDMO capacity buildout:CDSCO's streamlined approval pathways for topical ANDAs attract investment in high-volume semi-solid manufacturing for export markets.
- Wound care biologic-device convergence:Antimicrobial peptide incorporation into hydrogel matrices opens formulation partnerships between CDMOs and advanced therapy developers.
- ISO 13485 certification arbitrage:Transdermal patch manufacturers with dual pharmaceutical and medical device quality systems capture combination product programs.
Industry Challenges
- Rheological method development expertise scarcity:Qualified analytical scientists capable of validating IVRT and IVPT protocols command premium compensation in tight labor markets.
- Legacy equipment integration complexity:Continuous manufacturing adoption for semi-solids requires retrofitting batch-oriented facilities without disrupting validated commercial production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topical Drugs CDMO Market |
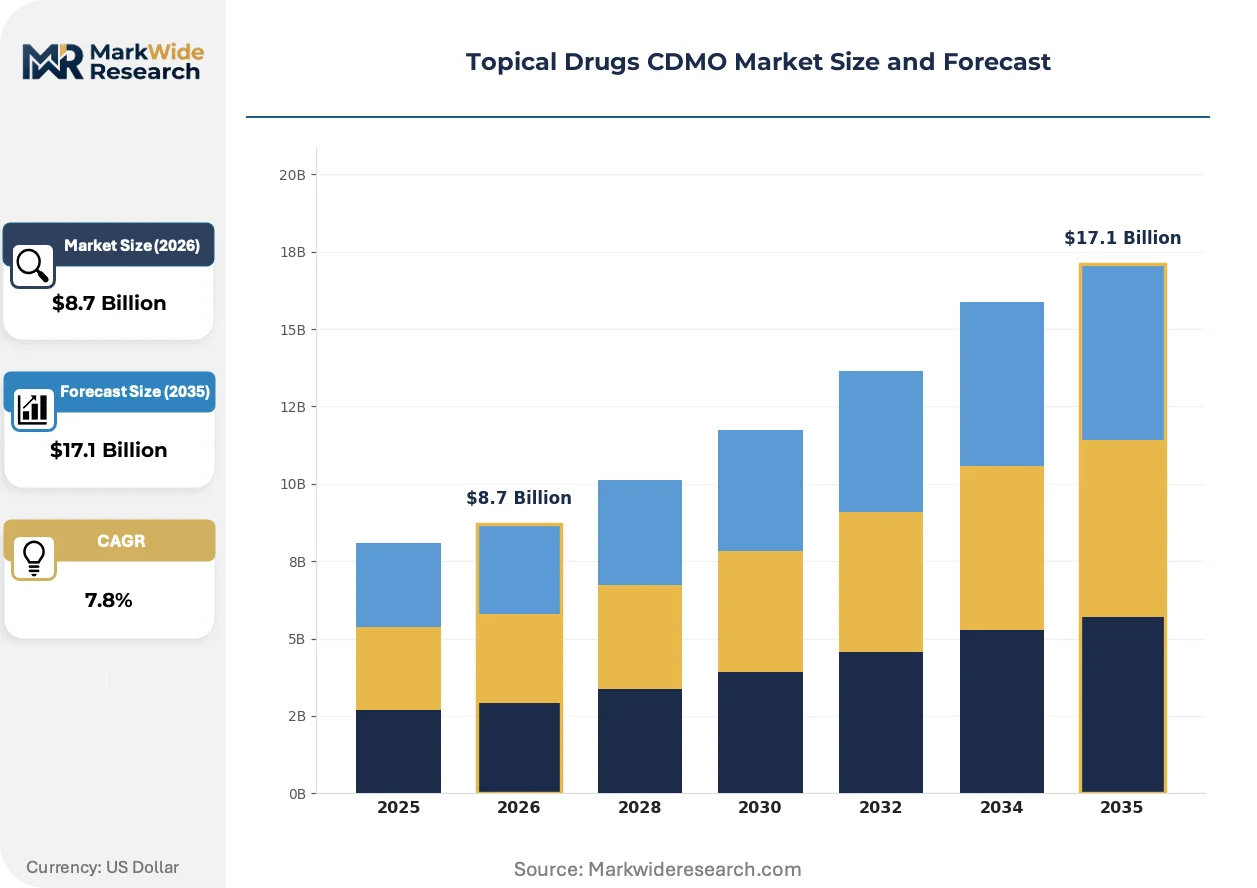
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Ointments, Gels, Lotions Delivery Mode: Transdermal, Topical, Intradermal, Sustained Release End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Manufacturers Therapy Area: Dermatology, Pain Management, Oncology, Wound Care |
| Companies Covered | Bora Pharmaceutical CDMO, Pierre Fabre group, Lubrizol Life Science, DPT Laboratories, LTD, Piramal Pharma Solutions, Cambrex Corporation, Ascendia Pharmaceuticals, MedPharm Ltd, Contract Pharmaceuticals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topical Drugs CDMO Market Evolving Landscape
Topical drug development is converging around three vectors: analytical sophistication for regulatory defense, manufacturing modality flexibility for portfolio breadth, and patient-centric delivery design for commercial differentiation. Each vector reshapes CDMO capability requirements and capital allocation priorities.
Microfluidic formulation technology is unifying process development and scale-up for complex emulsions and lipid-based systems. Mid-sized biotech sponsors in dermatology and pain management are adopting microfluidic platforms to compress development timelines from twelve to six months. This technology is unifying formulation and manufacturing stages into single continuous workflows that eliminate batch-to-batch variability and reduce tech transfer risk.
EMA's updated MDR guidance on drug-device borderline determinations is reclassifying many transdermal systems as combination products requiring dual technical documentation. CDMOs must now maintain parallel pharmaceutical and medical device quality management systems under ISO 13485 and ICH Q10 simultaneously. European development programs face the steepest compliance burden as notified body consultation timelines extend for novel delivery mechanisms.
Biotech procurement teams are consolidating vendor panels around partners offering integrated formulation-through-commercial services rather than discrete development or manufacturing-only contracts. This pattern displaces project-based fee-for-service relationships with multi-year platform agreements spanning entire pipelines. United States-based sponsors exhibit the fastest consolidation pace as venture-backed dermatology companies prioritize speed-to-IND over unit cost optimization.
Topical Drugs CDMO Market Segmentation
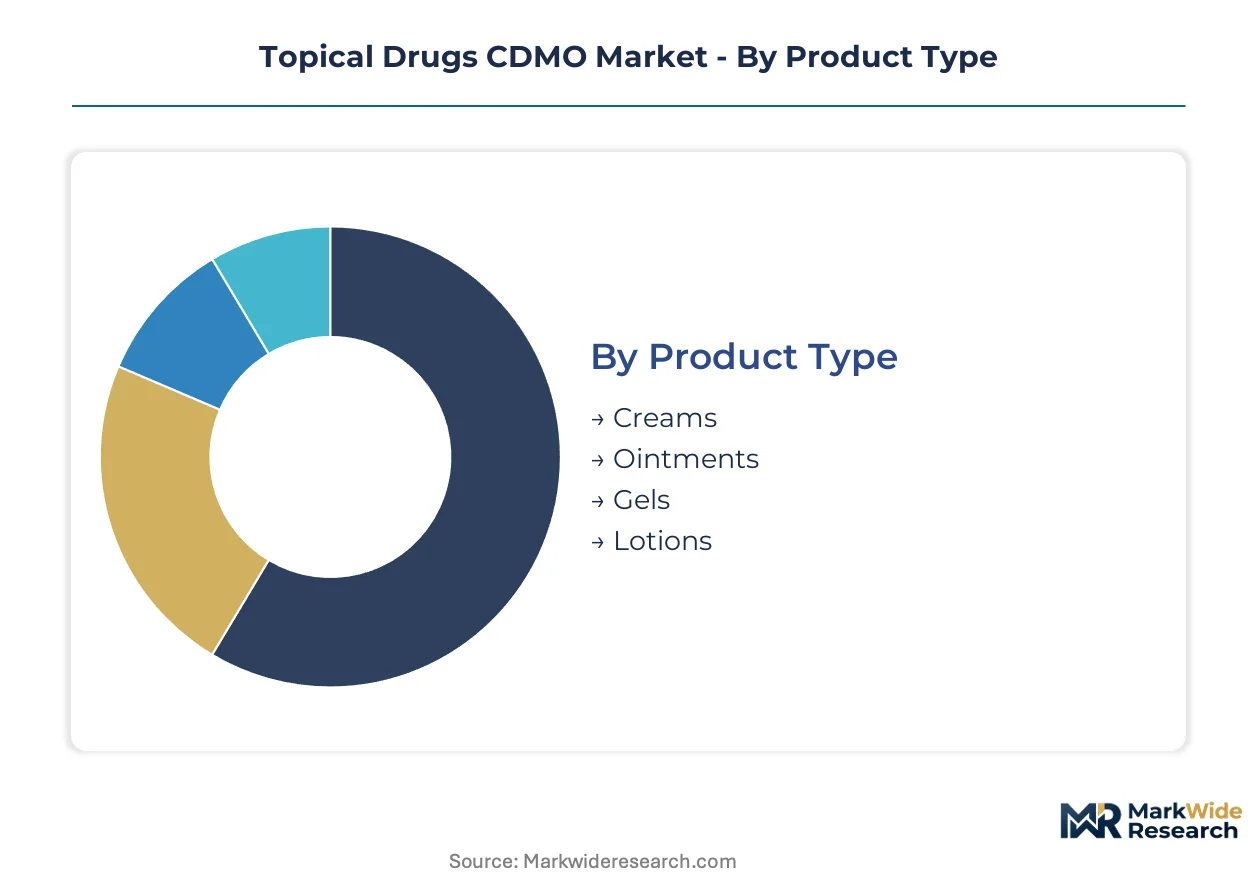
Topical CDMOs configure facility investments and analytical capabilities around specific product physics and regulatory pathways. Segment-level capital requirements and margin profiles determine which service lines attract capacity expansion versus commodity competition.
Product Type:
Creams and ointments demand the heaviest emulsification and homogenization infrastructure, while gels and lotions require specialized rheology control systems that lock up capital differently.
- Creams:Oil-in-water emulsions with defined droplet size distributions and viscosity profiles. Demand clusters around United States dermatology sponsors seeking FDA Q1/Q2 sameness validation for generic ANDA filings. Containment requirements for potent APIs drive facility hardening costs.
- Ointments:Hydrocarbon-based semi-solids with occlusive properties and thermal stability challenges. European pain management developers under EMA MDR device-drug classifications favor partners with validated process analytical technology. High-purity white petrolatum supply chains concentrate among German refiners.
- Gels:Aqueous or alcoholic matrices with shear-thinning behavior for cosmetic acceptance. Biotech sponsors in Boston and New Jersey prioritize rapid formulation iteration over unit cost.
- Lotions:Low-viscosity pourable systems requiring specialized filling lines and stability programs. Volume demand tracks mass-market over-the-counter portfolios.
Creams absorb the bulk of installed capacity; gels are expanding most quickly.
Delivery Mode:
Regulatory classification complexity and clinical validation burden separate premium service tiers from basic manufacturing.
- Transdermal:Patch-based systems with rate-controlled permeation through intact skin. United States sponsors dominate pipeline activity, with FDA combination product designations requiring ISO 13485 dual quality systems.
- Sustained Release:Matrix or reservoir formulations extending drug delivery over 12-72 hours. Pain management developers in New Jersey and Massachusetts outsource to partners with hot-melt extrusion and solvent casting capabilities.
- Topical:Conventional semi-solid application to skin or mucous membranes. High-volume commodity manufacturing concentrates in Indian CDMOs serving export markets.
- Intradermal:Microneedle and microprojection systems breaching the stratum corneum. EMA notified body consultation timelines extend development programs for European sponsors.
Topical delivery commands the greatest volume base; sustained release claims the steepest expansion trajectory.
End User:
Procurement sophistication and technical specification intensity vary sharply across sponsor types.
- Pharmaceutical Companies:Legacy firms with established quality systems and multi-site manufacturing networks. New Jersey-based operations anchor United States outsourcing demand for commercial-scale semi-solid production.
- Biotech Firms:Venture-backed dermatology developers prioritizing speed-to-IND over cost optimization. Boston-area clusters exhibit the fastest consolidation around integrated CDMO partnerships.
- Research Institutions:Academic medical centers with limited GMP manufacturing experience. Demand concentrates on early-phase formulation feasibility and preclinical supply.
- Contract Manufacturers:CDMOs subcontracting specialized capabilities or overflow capacity. Relationships deepen around shared containment infrastructure for potent compounds.
Pharmaceutical companies lock in the longest-term capacity commitments; biotech firms are gaining share fastest.
Therapy Area:
Clinical endpoint requirements and pricing dynamics shape CDMO selection criteria and contract structures.
- Dermatology:Chronic inflammatory and aesthetic indications with repeat prescribing patterns. United States sponsors drive demand for complex emulsion and lipid-based formulations with defined bioequivalence pathways.
- Pain Management:Opioid-sparing and NSAID-based therapies requiring sustained-release matrix expertise. EMA excipient safety mandates under REACH framework complicate European development programs.
- Oncology:Potent cytotoxic compounds demanding isolator technology and dedicated facility zones. Containment infrastructure capex intensity limits viable supplier pools.
- Wound Care:Biologic-device convergence with antimicrobial peptide incorporation and hydrogel matrices. Partnerships between CDMOs and advanced therapy developers are proliferating.
Dermatology holds the deepest margin pools; wound care is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors global topical drug development activity, with Kendall Square and Seaport District biotechs outsourcing transdermal programs to specialized manufacturing partners. New Jersey's legacy pharmaceutical corridor complements this cluster with commercial-scale semi-solid production demand.
United States
FDA's Q1/Q2 sameness requirements for topical ANDA filings drive sponsor demand for validated analytical partnerships. The IRA's drug pricing provisions accelerate generic topical development timelines. Greater Boston biotechs concentrate formulation outsourcing around integrated CDMO platforms.
Germany
EMA's REACH framework and MDR device-drug classifications shape excipient safety mandates for European topical programs. High-purity white petrolatum supply chains concentrate among German refiners. Frankfurt-Rhine-Main chemical clusters supply pharmaceutical-grade polymers to CDMO formulation networks.
India
CDSCO's streamlined ANDA approval pathways attract investment in high-volume semi-solid manufacturing for export markets. PLI scheme incentives support containment infrastructure buildout for potent compound handling. Hyderabad and Ahmedabad CDMO clusters scale cream and ointment capacity for North American and European clients.
Switzerland
Swissmedic's stringent quality expectations elevate analytical method development standards for complex transdermal submissions. Basel's pharmaceutical innovation corridor sustains demand for specialized formulation partnerships. Swiss CDMOs leverage dual ISO 13485 and ICH Q10 certifications for combination product programs.
United Kingdom
MHRA's post-Brexit regulatory autonomy creates parallel bioequivalence pathway complexity for topical generics. London-Oxford-Cambridge biotech clusters pursue wound care biologic-device convergence partnerships. UK sponsors prioritize CDMOs with validated IVRT and IVPT protocols for regulatory defense.
Topical Drugs CDMO Market Competitive Landscape
Capital-heavy producers compete with asset-light design houses across a tiered service structure. Integrated formulation-through-commercial operators command premium pricing against discrete development-only shops. Three archetypes dominate: multi-continent platform CDMOs, regional semi-solid specialists, and niche transdermal technology licensors. Consolidation accelerates through strategic partnerships and ISO 13485 certification arbitrage for combination product access.
Within the integrated platform tier, Piramal Pharma Solutions and Cambrex Corporation exemplify capital-intensive operators with validated complex-formulation capabilities spanning multiple continents. DPT Laboratories, LTD anchors the U.S.-based regional specialist position. These three represent distinct strategic postures: global scale with analytical depth, potent compound containment infrastructure, and domestic semi-solid manufacturing concentration respectively.
| Leading Market Players |
|---|
| Bora Pharmaceutical CDMO |
| Pierre Fabre group |
| Lubrizol Life Science |
| DPT Laboratories, LTD |
| Piramal Pharma Solutions |
| Cambrex Corporation |
| Ascendia Pharmaceuticals |
| MedPharm Ltd |
| Contract Pharmaceuticals Limited |
| Others |
Value Network & Pricing Analysis
EMA REACH substance restrictions gate qualified excipient supply and premium-tier pricing access for European topical programs, forcing sponsors to pay containment-validated premiums or accept extended registration timelines that compress development budgets. This environmental-safety mandate stratifies the vendor base between REACH-compliant premium operators and export-oriented commodity manufacturers.
Pricing Analysis
Outcome-validated pricing anchors complex-formulation partnerships, with CDMOs commanding premiums proportional to FDA Q1/Q2 sameness validation depth and EMA MDR combination product certification. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485 dual-certified transdermal specialists from basic semi-solid manufacturers and high-volume Indian exporters. Cost compression in commodity creams and ointments is intensifying because CDSCO streamlined ANDA pathways attract capacity buildout for export markets. Venture-backed Boston biotechs exhibit lowest price sensitivity, prioritizing speed-to-IND over unit economics, while mass-market OTC sponsors drive hardest bargain negotiations.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive topical batches remain underdeveloped, forcing write-offs of stability-failed semi-solids that lack refurbishment pathways for API recovery. High-purity pharmaceutical-grade polymers concentrate among German and Swiss chemical suppliers, with white petrolatum refining anchored in German industrial clusters. Permeation enhancers and specialized emulsifiers draw from limited European specialty chemical networks. Single-source vulnerability permeates the excipient tier where REACH registration costs deter multi-sourcing. Distribution runs through validated cold-chain logistics partners serving FDA-inspected facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
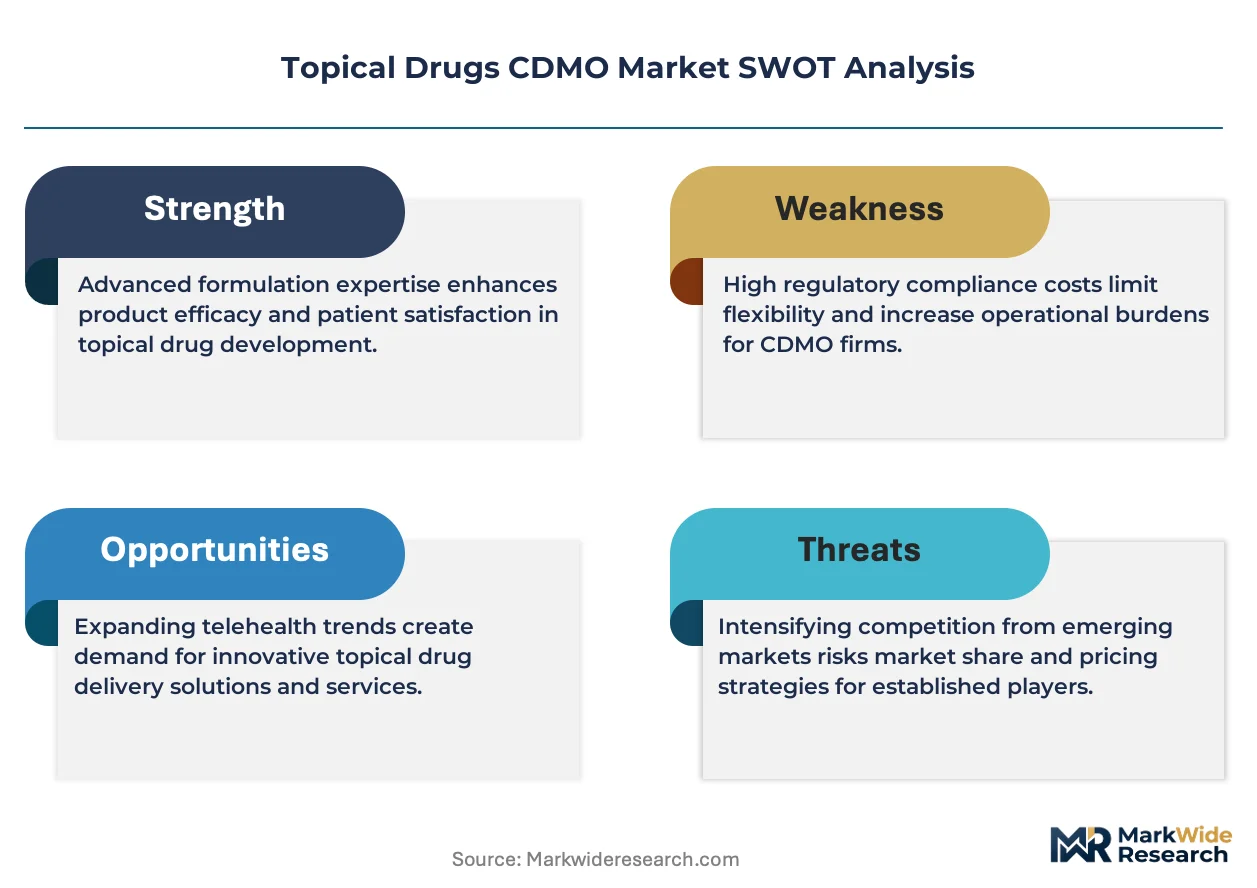
This market reads as a cost-of-compliance story where FDA Q1/Q2 sameness requirements and EMA MDR device-drug classifications erect barrier-to-entry moats favoring CDMOs with validated analytical platforms and dual quality systems.
For Market Incumbents: Extend analytical service depth into rheological fingerprinting and IVRT/IVPT method development to capture generic ANDA filing partnerships that emerging entrants cannot replicate. Add isolator-equipped capacity in Hyderabad or Ahmedabad to match Indian CDMO cost positions for export-market semi-solid manufacturing. Consolidation around ISO 13485 certification arbitrage defends against European combination product specialists. For New Entrants and Emerging Players: Mid-sized Boston dermatology biotechs represent the most penetrable buyer archetype, as these sponsors prioritize integrated formulation-through-commercial partnerships over discrete manufacturing contracts. Wound care biologic-device convergence offers white-space formulation partnerships with advanced therapy developers seeking hydrogel matrix expertise. Position around microfluidic platform capabilities to compress development timelines that captive manufacturing cannot match. For Investors and Strategic Acquirers: CDSCO approval pathway acceleration for topical ANDAs is the leading indicator that Indian export-oriented capacity will consolidate around scaled operators with containment infrastructure. The five-to-ten-year viability window favors acquisition targets with validated Q1/Q2 sameness data packages and established FDA inspection histories. Monitor EMA notified body consultation timeline extensions for novel transdermal mechanisms as the signal for European regulatory burden intensification.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Arbitrage | Dual pharmaceutical and medical device quality systems capture EMA MDR combination product programs. |
| Microfluidic Platform Integration | Continuous formulation workflows compress Boston biotech development timelines from twelve to six months. |
| Containment Infrastructure Buildout | Isolator technology investments in Hyderabad serve FDA-inspected export markets for potent compounds. |
| Rheological Method Development | Validated IVRT and IVPT protocols defend against FDA Q1/Q2 sameness scrutiny for generic ANDA filings. |
| Backward Integration into Excipients | Upstream control over high-purity polymer supply reduces German and Swiss supplier concentration risk. |
Research Methodology
Document review covered FDA ANDA filings, EMA MDR submissions, ClinicalTrials.gov topical program registrations, and CDSCO approval databases, complemented by interviews with drug development executives at Boston-area biotechs, regulatory affairs leads managing Q1/Q2 sameness submissions, and procurement directors at New Jersey-based legacy pharmaceutical firms. Secondary validation drew from SEC 10-K CDMO disclosures, customs export data for semi-solid pharmaceutical preparations, and containment equipment vendor order backlogs. Bottom-up capacity modeling and top-down sponsor pipeline triangulation anchored market sizing.
Cross-referencing historical capacity utilization against panel input from CDMO commercial officers and sponsor outsourcing managers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type physics, delivery mode regulatory complexity, therapy area margin profiles, and sponsor archetype procurement sophistication. CAGRs derived from sponsor pipeline velocity analysis and capacity expansion announcement tracking. Forecast inputs incorporated FDA bioequivalence guidance evolution and EMA notified body consultation timeline trends.
Revisions become necessary when FDA issues revised Q1/Q2 guidance for complex generics, ECHA expands REACH substance restrictions affecting novel excipients, or CDSCO alters ANDA approval pathway timelines. Forecasts reflect assumptions regarding regulatory stability and sponsor outsourcing propensity. Practitioners should monitor FDA draft guidance publication schedules and EMA MDR borderline determination updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Europe Contraceptives Market
Pharmaceuticals
Africa Generic Pharmaceutical Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Atorvastatin API Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market