
 Antiandrogens Market | 2026-2036
Antiandrogens Market Size, Share, and Industry Trends Forecast 2026-2036
Antiandrogens Market Outlook
Hospital procurement of antiandrogen therapies is fragmenting as specialty pharmacy networks and direct-to-clinic distribution channels gain share against traditional wholesale models. Pfizer leverages its oncology infrastructure to sustain institutional contracts across major health systems. Astellas Pharma anchors its position through deep integration with urology-focused distribution networks. Bayer AG differentiates via manufacturing scale that supports consistent supply to centralized hospital pharmacies.
Antiandrogens constitute a class of steroidal and non-steroidal compounds that competitively inhibit androgen receptor binding or suppress androgen synthesis, with enzalutamide representing a second-generation non-steroidal agent engineered for higher receptor affinity than first-generation alternatives. These agents serve primarily to arrest androgen-driven proliferation in hormone-sensitive malignancies and dermatological conditions. Enzalutamide commands the largest revenue pool among product types due to its established efficacy in metastatic castration-resistant prostate cancer, while oral administration routes dominate volume because of patient compliance advantages over intravenous alternatives. Subcutaneous formulations represent the fastest-growing administration segment as manufacturers invest in depot delivery technologies that reduce clinic visit frequency.
FDA oncology drug designations and EMA centralized marketing authorizations shape clinical trial investment and commercial launch sequencing for antiandrogen developers, with both agencies tightening evidentiary standards for progression-free survival endpoints. The EPA and OSHA frameworks govern active pharmaceutical ingredient manufacturing emissions and worker exposure limits at production facilities in the United States. Stakeholders must monitor evolving FDA Real-Time Oncology Review pilot expansions and EMA accelerated assessment criteria to time regulatory submissions against competitive entry windows.
Market Dynamics
Second-generation non-steroidal antiandrogens are compressing first-generation market share as enzalutamide and apalutamide establish dominance in metastatic castration-resistant prostate cancer protocols across major hospital systems.
Growth Catalysts
- FDA Real-Time Oncology Review pilot:Accelerated submission pathways for progression-free survival endpoints compress regulatory timelines for novel hormone therapy developers.
- Depot delivery technologies:Subcutaneous formulations reduce clinic visit frequency for prostate cancer patients, improving compliance metrics in long-term treatment regimens.
- United States hospital network consolidation:Centralized pharmacy procurement at major health systems concentrates demand for oral antiandrogen therapies under institutional contracts.
Market Restraints
- Active pharmaceutical ingredient concentration:Steroidal precursor synthesis depends on concentrated manufacturing bases in China and India, exposing supply chains to export restriction risks.
- EMA evidentiary tightening:Progression-free survival endpoints now require more robust overall survival correlation data, extending clinical trial duration for new entrants.
- Generic enzalutamide entry:Patent expiration timelines accelerate price erosion in oral antiandrogen segments, compressing originator revenue pools.
Strategic Opportunities
- Combination immunotherapy protocols:Antiandrogen and checkpoint inhibitor pairings in hormone-sensitive prostate cancer represent underexploited clinical trial white space.
- Specialty pharmacy direct distribution:Bypassing wholesale intermediaries captures margin and patient data for adherence monitoring programs.
- IRA Medicare price negotiation provisions:Selected drug provisions create strategic positioning windows for therapies outside initial negotiation lists.
Industry Challenges
- Androgen receptor splice variant expertise:Resistance mechanism research requires rare translational oncology skill sets concentrated at academic medical centers.
- cGMP manufacturing scale-up:Non-steroidal synthesis complexity demands capital-intensive continuous flow reactor investments for commercial supply security.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiandrogens Market |
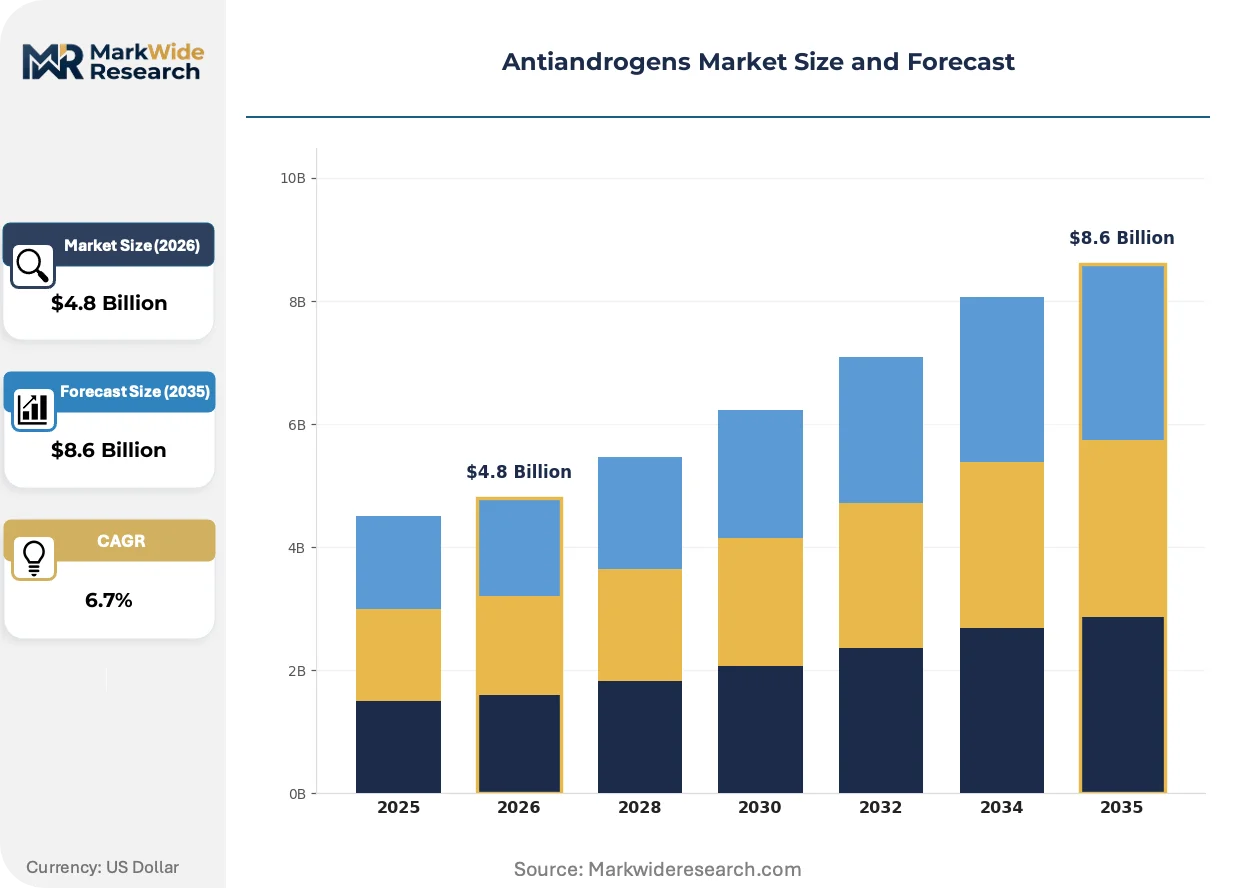
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzalutamide, Flutamide, Nilutamide, Bicalutamide Therapy Area: Prostate Cancer, Hirsutism, Acne, Alopecia Administration Route: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Clinics, Homecare, Pharmaceutical Companies |
| Companies Covered | Pfizer, Astellas Pharma, F. Hoffmann-La Roche, AstraZeneca, Johnson & Johnson, Bayer AG, Takeda Pharmaceutical Company, Genentech, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiandrogens Market Strategic Shifts
Antiandrogen development is pivoting toward precision hormone modulation as resistance mechanisms and patient stratification biomarkers reshape clinical trial design and commercial positioning across oncology portfolios.
Next-generation androgen receptor degraders is migrating from exploratory discovery into Phase I pipelines as pharmaceutical developers target acquired resistance to competitive antagonists. Academic medical centers in the United States and Germany are prioritizing these agents for investigator-sponsored trials. The shift is compressing reliance on single-mechanism competitive inhibition and opening combination therapy design spaces.
EMA centralized marketing authorization requirements for oncology products now mandate real-world evidence collection commitments as post-approval conditions. This policy shift forces developers to build patient registry infrastructure prior to launch rather than retrofitting compliance. Small and mid-cap biotech firms without existing pharmacovigilance systems face partnership pressure to meet these obligations.
Hospital pharmacy buyers are consolidating formulary decisions through centralized oncology committees that evaluate total cost of care rather than drug acquisition cost alone. Specialty distributors with integrated patient support services are displacing traditional wholesale relationships in this segment. The United States exhibits the most advanced concentration of this purchasing transformation, with similar committee structures emerging in France and Japan.
Antiandrogens Market Segmentation
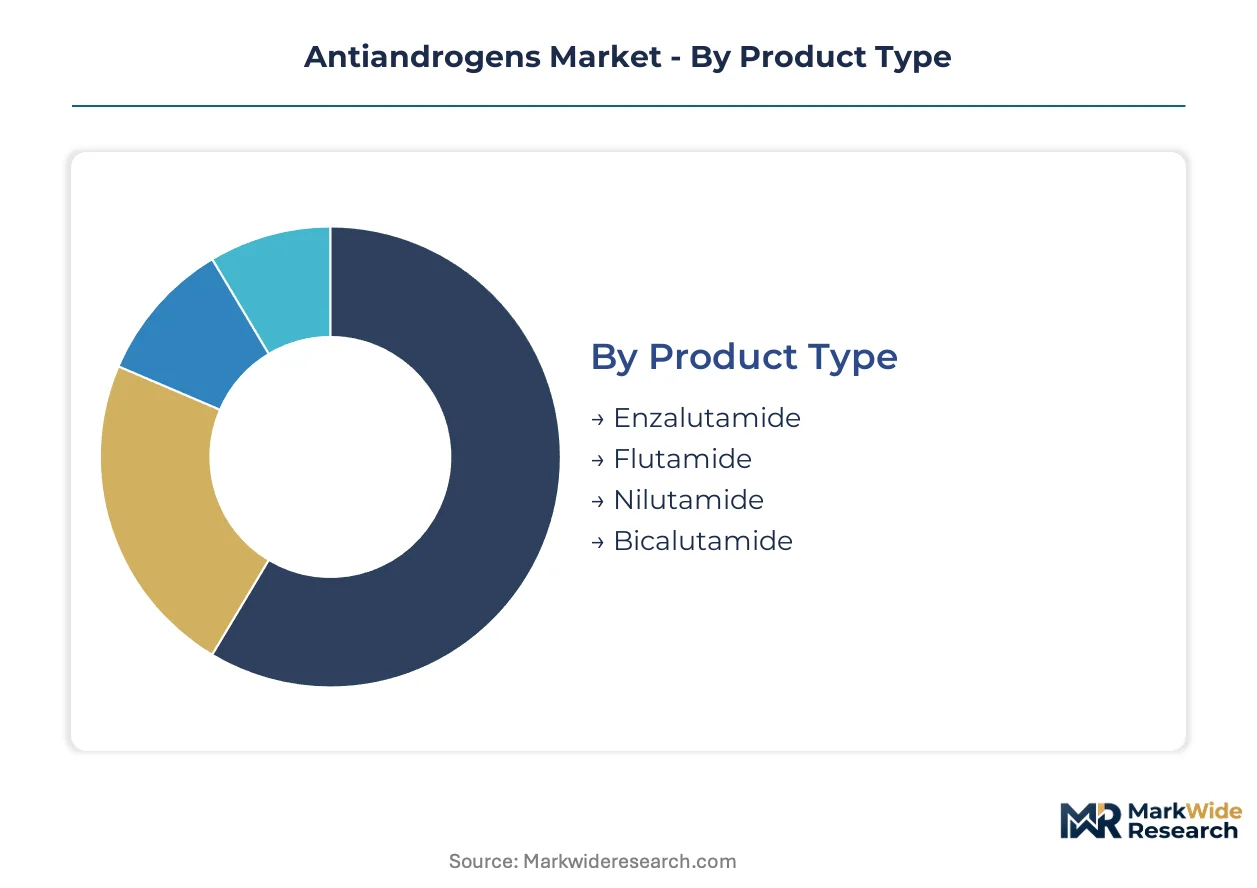
Antiandrogen market segmentation reveals distinct commercial dynamics across molecular generations, therapeutic applications, and care delivery settings. Each dimension carries implications for pricing power, regulatory pathway complexity, and distribution channel selection.
Product Type:
Cost tier stratification separates second-generation non-steroidal agents from legacy steroidal compounds across hospital formularies and procurement negotiations.
- Enzalutamide:Engineered for higher androgen receptor affinity than first-generation alternatives, this non-steroidal agent binds the receptor ligand-binding domain to inhibit nuclear translocation and DNA binding. Demand concentrates in metastatic castration-resistant prostate cancer protocols at major United States hospital systems, where progression-free survival data drives institutional adoption despite premium pricing.
- Bicalutamide:A first-generation non-steroidal antiandrogen with competitive antagonist properties at the androgen receptor, offering generic availability that compresses acquisition costs. Volume clusters in earlier-stage prostate cancer and combination regimens where cost constraints limit access to second-generation agents.
- Flutamide:First-generation non-steroidal compound requiring more frequent dosing schedules.
- Nilutamide:Steroidal-derived agent with limited current utilization in post-surgical adjuvant settings.
Enzalutamide holds installed capacity. Bicalutamide is rotating up the share rankings.
Therapy Area:
Application maturity varies sharply between oncology indications with robust clinical evidence and dermatological uses where off-label utilization persists.
- Prostate Cancer:Hormone-sensitive and castration-resistant disease states constitute the primary revenue pool, with antiandrogens serving as backbone therapy in combination with androgen deprivation therapy. Patient volume aggregates at academic medical centers and community oncology practices in the United States, Germany, and Japan, where urology-oncology integration supports protocol standardization.
- Hirsutism:Excess androgen-driven hair growth in women responds to antiandrogen modulation, though regulatory approvals lag behind oncology applications. Demand localizes in endocrinology and dermatology clinics across European markets with stronger reimbursement for hormonal interventions.
- Acne:Sebaceous gland androgen sensitivity creates a mechanistic rationale for off-label use in severe cases.
- Alopecia:Androgenetic pattern hair loss represents an emerging exploratory application with limited formal trial infrastructure.
Prostate cancer anchors revenue concentration. Hirsutism is climbing the fastest among non-oncology applications.
Administration Route:
Patient compliance requirements and care setting economics drive divergence between oral convenience and parenteral precision.
- Oral:Tablet and capsule formulations dominate prescription volume due to self-administration feasibility and elimination of infusion center dependency. Procurement flows through specialty pharmacy networks and hospital outpatient pharmacies in consolidated United States health systems, where prior authorization protocols favor oral agents for maintenance therapy.
- Subcutaneous:Depot injection technologies enable sustained release over weeks or months, reducing clinic visit burden for prostate cancer patients on chronic therapy. Manufacturing investments from Pfizer and Astellas Pharma target this modality as a differentiation vector against oral generic competition.
- Intravenous:Reserved for acute care settings and specific combination protocols.
- Topical:Localized delivery for dermatological applications with limited systemic exposure.
Oral maintains volume leadership. Subcutaneous is gaining share fastest through depot technology advances.
End User:
Customer type determines contracting complexity, with institutional purchasers exercising consolidated leverage against fragmented retail channels.
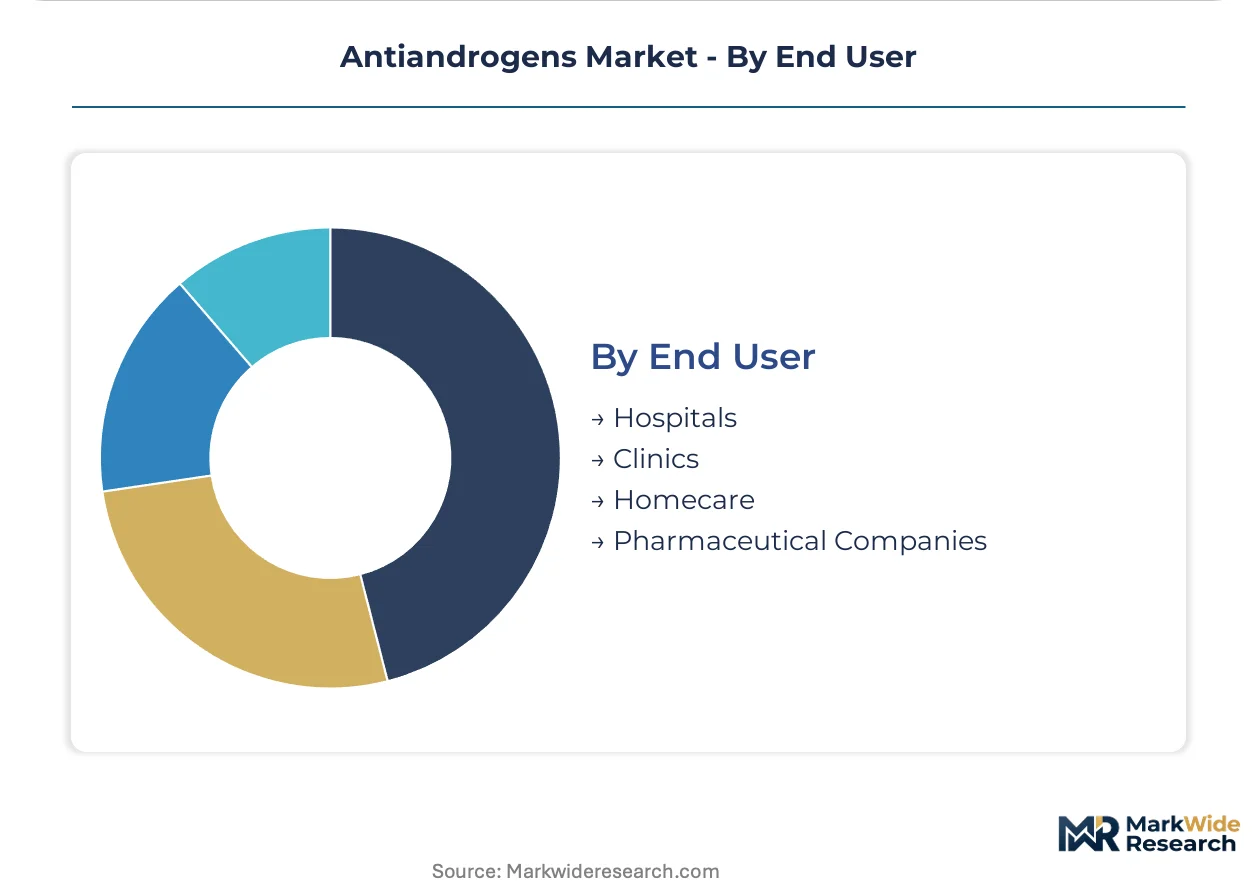
- Hospitals:Inpatient and outpatient oncology departments at integrated delivery networks command the largest procurement volumes, leveraging centralized pharmacy and therapeutics committees to standardize antiandrogen selection across affiliated sites. Formulary decisions in the United States increasingly incorporate total cost of care analytics rather than drug acquisition cost alone.
- Pharmaceutical Companies:Active pharmaceutical ingredient and finished dosage form sourcing for clinical trial supply and commercial manufacturing creates B2B demand distinct from patient-facing channels. Contract manufacturing organizations in India and China serve this segment with steroidal precursor synthesis capabilities.
- Clinics:Community urology and oncology practices with limited infusion infrastructure.
- Homecare:Subcutaneous administration enabling patient-managed therapy outside clinical settings.
Hospitals hold installed capacity. Pharmaceutical companies are rotating up the share rankings through API outsourcing concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds European benchmarks by substantial margins, while manufacturing cost advantages concentrate in Asian production clusters. Hospital procurement consolidation and regulatory pathway complexity create divergent competitive dynamics across major national markets.
United States
Academic medical centers in Boston and Houston drive protocol standardization for metastatic prostate cancer, anchoring demand for second-generation non-steroidal agents. FDA Real-Time Oncology Review pilot programs compress submission timelines for hormone therapy developers. The Mayo Clinic Rochester campus and MD Anderson Cancer Center in Texas concentrate investigator-sponsored trial activity for next-generation androgen receptor degraders.
Germany
University hospitals in Munich and Heidelberg integrate urology-oncology departments that standardize antiandrogen selection across regional networks. EMA centralized marketing authorization requirements mandate real-world evidence collection commitments as post-approval conditions. The Rhine-Main cluster around Frankfurt anchors pharmaceutical manufacturing investment for active pharmaceutical ingredient synthesis.
Japan
PMDA oncology review divisions prioritize progression-free survival endpoints with stricter overall survival correlation requirements than Western counterparts. METI industrial policy supports domestic manufacturing scale-up for hormone therapy production. The Kansai region around Osaka concentrates contract manufacturing organization capacity for steroidal precursor synthesis.
India
CDSCO accelerated approval pathways for oncology products attract multinational clinical trial investment to Mumbai and Bangalore hospital networks. PLI scheme incentives for pharmaceutical manufacturing support domestic production of generic bicalutamide formulations. The Hyderabad-Visakhapatnam corridor anchors active pharmaceutical ingredient export capacity for steroidal intermediates.
China
NMPA oncology drug designations prioritize domestic innovation in hormone-sensitive malignancy protocols at Beijing and Shanghai cancer centers. National reimbursement drug list negotiations compress pricing for imported antiandrogen therapies. The Yangtze River Delta around Shanghai concentrates biopharmaceutical manufacturing investment for oral formulation capacity.
Antiandrogens Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in active pharmaceutical ingredient synthesis and finished dosage manufacturing. The market structure concentrates around diversified pharmaceutical conglomerates with oncology infrastructure, mid-cap biotech firms with single-mechanism assets, and contract manufacturing organizations with steroidal chemistry expertise. Competitive positioning depends on regulatory submission timing, hospital formulary penetration, and manufacturing scale. M&A activity targets resistance mechanism intellectual property; strategic partnerships bridge pharmacovigilance infrastructure gaps for post-approval compliance.
Among diversified pharmaceutical conglomerates, Pfizer, Astellas Pharma, and Bayer AG occupy positions reflecting distinct competitive archetypes. Pfizer exemplifies the platform integrator with institutional contract depth across United States health systems. Astellas Pharma represents the urology-focused specialist with distribution network integration. Bayer AG anchors the manufacturing-scale tier with supply security positioning for centralized hospital pharmacies.
| Leading Market Players |
|---|
| Pfizer |
| Astellas Pharma |
| F. Hoffmann-La Roche |
| AstraZeneca |
| Johnson & Johnson |
| Bayer AG |
| Takeda Pharmaceutical Company |
| Genentech |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Chinese and Indian steroidal precursor manufacturers determines both the premium commanded by second-generation non-steroidal agents and the three-tier sourcing structure that hospital buyers navigate. FDA and EMA regulatory chokepoints amplify pricing power for originator products with approved progression-free survival endpoints while compressing margins for generic first-generation alternatives.
Pricing Analysis
The customization-premium spread separates configured-to-order subcutaneous depot formulations from standard oral tablet procurement. Three-tier pricing structure across premium enzalutamide, standard bicalutamide, and economy flutamide levels reflects patent status and receptor-binding affinity differentiation. Price erosion runs through oral segments as generic enzalutamide entry accelerates, with hospital pharmacy committees exercising greatest sensitivity to acquisition cost in maintenance therapy populations while academic medical centers demonstrate lowest sensitivity for novel mechanism assets in metastatic settings.
Supply Chain Analysis
Export-control regime scrutiny over concentrated steroidal chemistry capabilities limits technology transfer to alternative manufacturing sites. Active pharmaceutical ingredient synthesis draws from China, India, and Germany, with steroidal precursor feedstocks resting on diosgenin extraction from Mexican yam cultivars and soy phytosterol processing. Single-source vulnerability concentrates at Hyderabad-Visakhapatnam corridor facilities subject to DGFT export restriction risks. Distribution runs through specialty pharmacy networks with direct-to-clinic bypass capabilities displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Translational oncology expertise in androgen receptor splice variant biology represents the scarcest capability layer, with fewer than two dozen academic medical centers globally possessing integrated resistance-mechanism research programs. This concentration shapes competitive durability for developers targeting next-generation degraders.
For Market Incumbents: Insulate formulation portfolios against oral generic compression by accelerating subcutaneous depot investments and securing exclusive distribution partnerships with specialty pharmacy networks possessing integrated adherence monitoring infrastructure. Deepen backward integration into steroidal precursor synthesis through captive supply arrangements with Indian contract manufacturing organizations to mitigate DGFT export restriction exposure. For New Entrants and Emerging Players: Mid-tier hospital systems in the United States South and Midwest represent the most penetrable entry point for biosimilar bicalutamide formulations, as these institutions lack centralized oncology committee standardization and demonstrate higher price sensitivity than coastal academic medical centers. Investigator-sponsored trial partnerships with German university hospitals in Munich and Heidelberg offer regulatory credibility for novel mechanism assets prior to FDA submission. For Investors and Strategic Acquirers: Mid-cap biotech firms with Phase I androgen receptor degrader pipelines and existing pharmacovigilance infrastructure constitute the highest-conviction acquisition archetype, as EMA post-approval real-world evidence commitments force partnership pressures on smaller developers lacking registry capabilities. Watch for FDA Real-Time Oncology Review pilot expansion announcements as inflection indicators for accelerated regulatory timeline premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Progression-free survival endpoint validation at MD Anderson and Mayo Clinic anchors institutional adoption. |
| Manufacturing Scale-Up | Continuous flow reactor investment in the Rhine-Main cluster secures commercial supply security for non-steroidal synthesis. |
| Regulatory Approval Pathway | EMA accelerated assessment criteria timing determines competitive entry windows against first-mover enzalutamide. |
| Licensing Agreement | Specialty pharmacy direct distribution partnerships capture margin and patient adherence data streams. |
| Pipeline Diversification | Combination immunotherapy protocols with checkpoint inhibitors open underexploited hormone-sensitive prostate cancer design space. |
Study Parameters
Desk research of FDA oncology drug designations, EMA centralized marketing authorization databases, and ClinicalTrials.gov enrollment records preceded structured interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists. Secondary validation drew from SEC 10-K oncology segment disclosures, hospital procurement databases, and GPO contract repositories. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Assumptions held fixed include FDA and EMA evidentiary standards for progression-free survival endpoints, while variables included generic enzalutamide entry timing and IRA Medicare price negotiation list expansion. The analytical framework modeled treatment line, administration route, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from patient population epidemiology, protocol penetration curves, and pricing trajectory scenarios with continuous flow reactor adoption rates and depot formulation uptake curves as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in reimbursement policy, hospital network consolidation velocity, or active pharmaceutical ingredient trade flows would shift the trajectory. Material shifts in androgen receptor splice variant resistance prevalence or next-generation degrader clinical efficacy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Benzodiazepine Drugs Market
Pharmaceuticals
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market