
 Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market | 2026-2036
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market Analytics
The CDMO sector is rebalancing as high-complexity biologics manufacturing splits from commoditized small-molecule production on price, capability, and regulatory intensity. Lonza dominates mammalian cell culture through its Swiss and US sites, leveraging decades of biologics scale-up expertise. Samsung Biologics anchors massive single-use bioreactor capacity in South Korea, competing on speed-to-clinic for monoclonal antibodies.
Pharmaceutical Contract Development and Manufacturing Organizations provide integrated drug substance and drug product services spanning cell line development, process characterization, cGMP manufacturing, and commercial fill-finish, operating under ICH Q7, Q9, and Q10 quality guidelines to ensure batch consistency and regulatory compliance. Active Pharmaceutical Ingredient manufacturing remains the largest revenue pool, though Biotechnology services represent the fastest-expanding margin segment as gene therapies and antibody-drug conjugates require novel platform technologies. Finished Dosage Forms constitute a mature, volume-driven category where cost efficiency and packaging differentiation determine contract awards.
FDA inspections, EMA's MDR framework, and China's NMPA biologics licensing pathways collectively determine market access timelines and capital deployment decisions for CDMO operators. The EU AI Act and FDA's emerging guidance on AI-enabled process analytics are beginning to reshape validation protocols for continuous manufacturing. Stakeholders must monitor which regulatory jurisdictions harmonize first on digital submission standards, as this will dictate where new manufacturing investments flow.
Market Dynamics
The CDMO sector is bifurcating as biologics manufacturing demands specialized mammalian cell culture capabilities while small-molecule production commoditizes, forcing operators to choose between capital-intensive biologics scale-up and high-volume chemistry efficiency.
Growth Catalysts
- EMA's revised GMP Annex 1:Sterile manufacturing standards for advanced therapy medicinal products are accelerating facility upgrades across European CDMOs, creating captive demand for aseptic processing expertise.
- Antibody-drug conjugate pipelines:Oncology biotechs are outsourcing linker-payload conjugation to specialists with cytotoxic handling capabilities, expanding the addressable service perimeter beyond conventional biologics.
- Switzerland:The country's concentrated cluster of biologics manufacturing infrastructure, anchored by Basel-region expertise, is attracting US and EU biopharma headquarters to co-locate development programs.
Market Restraints
- Platinum-group metal catalyst costs:Small-molecule API synthesis remains exposed to palladium and rhodium price volatility, compressing margins on legacy chemistry contracts without price-adjustment clauses.
- Single-use bioreactor supply concentration:Three suppliers control film and bag assembly capacity, creating vulnerability for mammalian cell culture operators dependent on just-in-time resin and tubing deliveries.
- FDA Quality Management Maturity program:Voluntary excellence standards are raising the compliance floor, forcing mid-tier CDMOs into costly quality system overhauls without immediate revenue offset.
Strategic Opportunities
- South Korea:The country's biologics manufacturing tax incentives and MFDS accelerated approval pathways are drawing gene therapy sponsors seeking parallel development in Asian and Western markets.
- Continuous manufacturing integration:Real-time release testing combined with process analytical technology is enabling smaller-footprint facilities with faster batch turnaround for orphan drug programs.
- EU AI Act compliance services:CDMOs with validated AI-enabled process control systems can capture premium positioning as biopharma sponsors seek manufacturing partners with pre-cleared algorithmic quality frameworks.
Industry Challenges
- Cell line development scientists:The specialized talent pool for clone selection and stability testing is contracting relative to biologics pipeline expansion, extending program initiation timelines.
- Multi-product facility qualification:Campaign changeover validation for antibody, viral vector, and cell therapy production in shared suites demands complex cleaning verification protocols that consume operational bandwidth.
- Gene therapy CMC packages:Regulatory filing complexity for novel viral vectors and plasmid supply chains is outstripping standard contract structures, requiring bespoke regulatory strategy staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market |
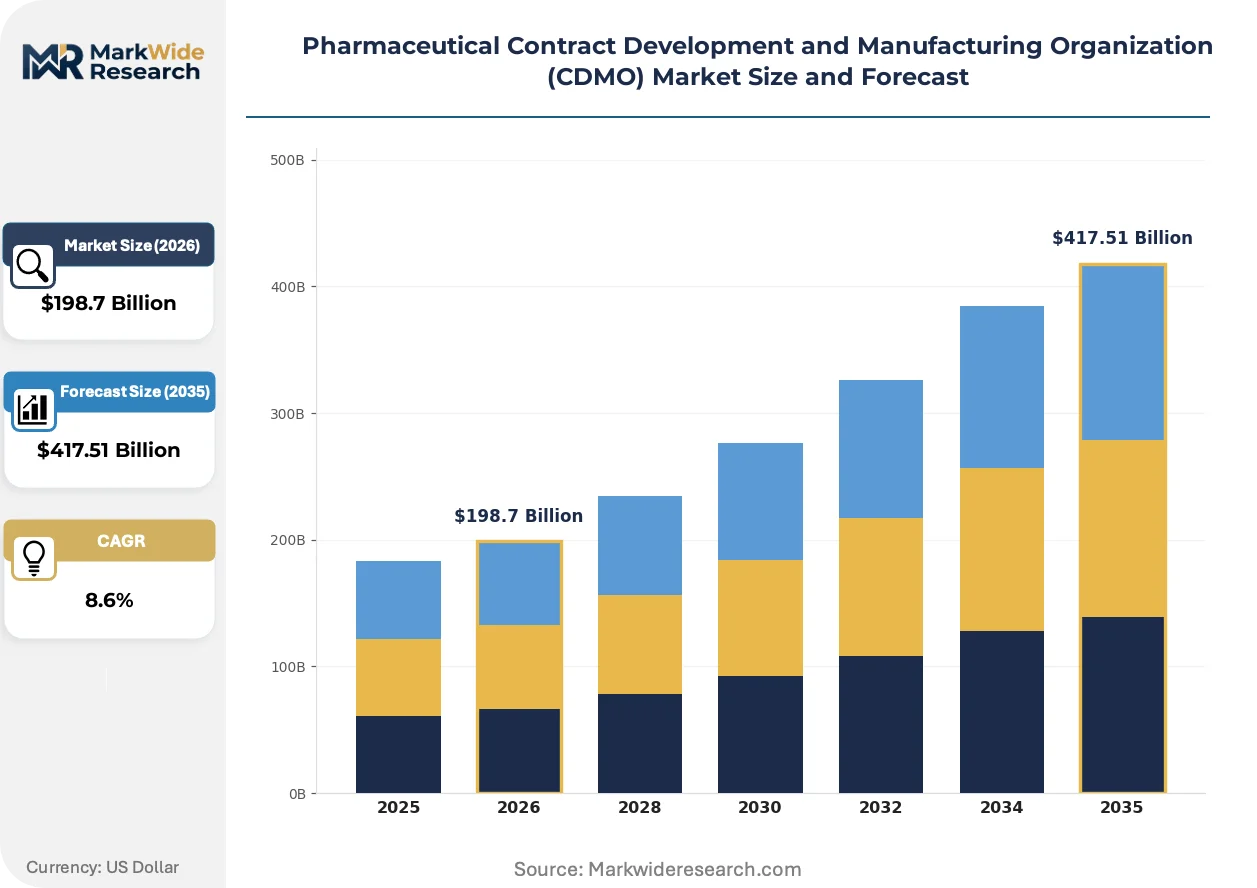
| Market Size in 2026 | $198.7 Billion |
| Market Size in 2035 | $417.51 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Formulation Development, Active Pharmaceutical Ingredient, Finished Dosage Forms, Packaging Services Client Type: Biopharmaceutical Companies, Generic Manufacturers, Virtual Pharma, Academic Institutions Technology: Biotechnology, Small Molecule Manufacturing, Fill and Finish, Analytical Services End User: Pharmaceutical R&D, Biotechnology Firms, Contract Research Organizations, Health Systems |
| Companies Covered | Lonza, Thermo Fisher Scientific, Catalent, Samsung Biologics, WuXi Biologics, WuXi AppTec, Siegfried Holding AG, Cambrex Corporation, Recipharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market Evolving Landscape
Process intensification and digital manufacturing architectures are compressing development timelines while regulatory bodies harmonize validation expectations for novel modalities, reshaping how CDMOs compete on speed versus flexibility.
Single-use bioreactor systems are modularizing facility design by eliminating stainless-steel cleaning validation requirements and enabling rapid product changeover. Mid-size biotech sponsors are adopting these platforms for Phase III campaigns to preserve capital for commercial launch. This technology is modularizing the traditional build-own-operate model, allowing CDMOs to reconfigure production suites within weeks rather than months.
The FDA's emerging guidance on AI-enabled process analytics is establishing validation frameworks for machine learning-driven quality control. Continuous manufacturing sponsors must demonstrate algorithmic interpretability and change-control protocols to inspectors. Biologics fill-finish operations with real-time particulate monitoring are most affected, with operators investing in explainable AI documentation systems ahead of formal rulemaking.
Biopharma procurement functions are consolidating vendor panels and demanding integrated drug substance-to-drug product contracts with unified quality agreements. This disintermediates standalone API manufacturers and favors CDMOs with end-to-end capabilities. The shift is most visible among US-based rare disease sponsors seeking single accountability for accelerated approval timelines.
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market Segmentation
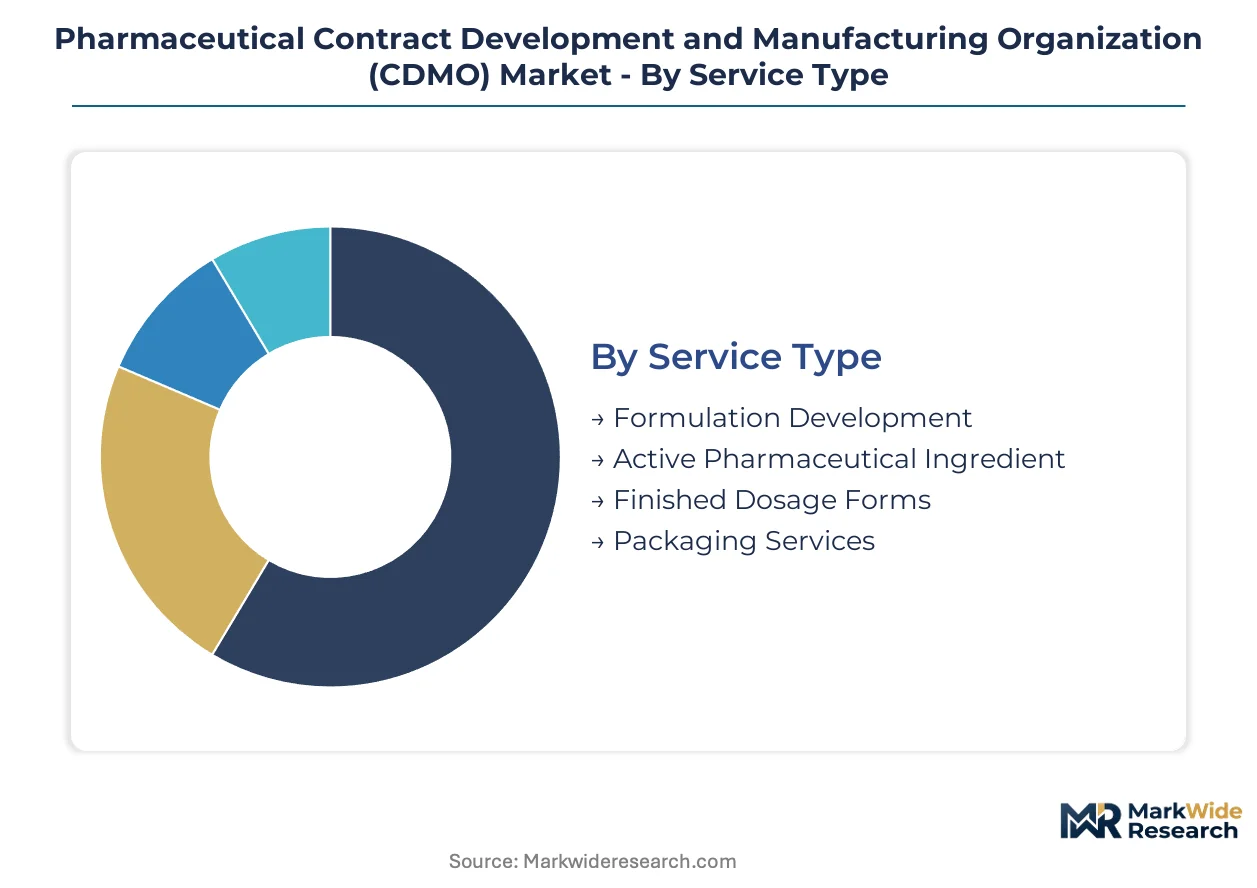
CDMO procurement decisions split across service complexity, client sophistication, and regulatory exposure. Contract structures vary materially by whether sponsors seek integrated programs or discrete manufacturing steps.
Service Type:
Technology intensity and regulatory burden separate high-margin development services from volume-driven manufacturing.
- Active Pharmaceutical Ingredient:Chemical synthesis and biologics drug substance production demand specialized reactor trains and containment infrastructure. Switzerland and Ireland anchor mammalian cell culture capacity for monoclonal antibodies, while catalytic hydrogenation expertise concentrates in German and Indian chemistry clusters.
- Formulation Development:Preclinical through Phase III dosage design requires rapid prototype iteration and bioavailability optimization. Virtual pharma sponsors in Boston and South San Francisco drive demand for integrated formulation-analytical packages with accelerated timelines.
- Finished Dosage Forms:Commercial-scale tablet, capsule, and sterile injectable manufacturing.
- Packaging Services:Serialization, cold-chain distribution, and patient-centric dosing formats.
Mature deployment sits with Finished Dosage Forms. Newer deployment is concentrated in Formulation Development.
Client Type:
Sponsor scale and internal capability determine outsourcing depth and contract duration.
- Biopharmaceutical Companies:Large pharma sponsors with approved portfolios outsource capacity-constrained modalities and geographic expansion. Gene therapy divisions at established firms seek viral vector manufacturing partners with EMA and FDA dual-site inspections.
- Virtual Pharma:Asset-light biotechs without manufacturing infrastructure rely entirely on CDMOs for CMC execution. South Korean tax incentives attract these sponsors seeking parallel Asian-Western development paths.
- Generic Manufacturers:Cost-competitive API sourcing and high-volume solid dose production.
- Academic Institutions:Early-stage translational research with limited GMP requirements.
Contract value concentrates with Biopharmaceutical Companies. Program velocity is fastest with Virtual Pharma.
Technology:
Platform selection locks in facility design, workforce specialization, and regulatory filing strategy for decade-long commitments.
- Biotechnology:Mammalian, microbial, and cell therapy production systems require single-use bioreactor suites and aseptic processing isolation. Samsung Biologics and Lonza have scaled 20,000L+ stainless steel and disposable trains, respectively, creating divergent capital efficiency models for sponsors.
- Small Molecule Manufacturing:Continuous flow chemistry and batch synthesis of oral solid dosage forms. Catalytic cross-coupling and high-potency API handling remain concentrated among European and North American specialists with containment legacy.
- Fill and Finish:Sterile injectable, lyophilization, and prefilled syringe assembly.
- Analytical Services:Method development, stability testing, and release testing.
Capacity expansion is most aggressive in Biotechnology. Margin compression is deepest in Small Molecule Manufacturing.
End User:
Downstream integration requirements shape CDMO selection criteria and quality agreement complexity.
- Pharmaceutical R&D:Discovery-phase through Phase III drug substance and product supply with flexible batch sizing. Early-stage sponsors prioritize speed over cost, accepting premium pricing for dedicated project teams and rapid slot access.
- Biotechnology Firms:Cell and gene therapy developers with novel viral vectors and plasmid supply chains. FDA's emerging guidance on real-time release testing is forcing these sponsors toward CDMOs with validated process analytical technology.
- Contract Research Organizations:Integrated discovery-to-IND service providers seeking manufacturing partners.
- Health Systems:Hospital pharmacy compounding and regional distribution networks.
Quality system requirements are most stringent for Biotechnology Firms. Contract flexibility is highest for Pharmaceutical R&D.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel anchors the highest concentration of biologics manufacturing infrastructure worldwide, with Swissmedic's regulatory framework drawing sponsor headquarters to co-locate development programs across the Rhine corridor.
United States
FDA's Quality Management Maturity program and accelerated approval pathways drive demand for aseptic processing capacity. The agency's emerging guidance on AI-enabled process analytics is reshaping validation protocols for continuous manufacturing sponsors. Greater Boston and South San Francisco clusters concentrate virtual pharma outsourcing decisions.
Switzerland
Specialized mammalian cell culture expertise and containment infrastructure for high-potency biologics attract global sponsor investment. Swissmedic maintains alignment with EMA standards while offering parallel inspection pathways. The Basel region hosts concentrated biologics scale-up capabilities spanning drug substance through commercial fill-finish.
South Korea
MFDS accelerated approval pathways and biologics manufacturing tax incentives draw gene therapy sponsors seeking dual-market development. Incheon and Songdo free economic zones anchor massive single-use bioreactor deployments. Samsung Biologics exemplifies the speed-to-clinic competition for monoclonal antibody contracts.
Germany
EMA's revised GMP Annex 1 sterile manufacturing standards accelerate facility upgrades for advanced therapy medicinal products. Catalytic hydrogenation and high-potency API handling expertise concentrates in Frankfurt-Rhine-Main and Bavarian chemistry clusters. Heidelberg and Munich regions anchor cell therapy process development capabilities.
India
CDSCO's biologics licensing pathway expansion and PLI scheme incentives for active pharmaceutical ingredients reshape contract sourcing patterns. Hyderabad and Bangalore manufacturing corridors concentrate on small-molecule API synthesis and formulation development. Pune anchors injectable fill-finish capacity for Western generic sponsors.
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as facility ownership separates from pipeline development risk. The sector structures around three tiers: integrated end-to-end operators with mammalian cell culture scale-up, specialized cytotoxic handling and ADC conjugation boutiques, and high-volume small-molecule chemistry houses. Consolidation pressures concentrate among mid-tier players lacking biologics platform credentials. Dominant competitive moves include capacity expansion in single-use bioreactor trains and strategic partnerships for gene therapy viral vector manufacturing.
Among Swiss-anchored biologics specialists, Lonza and Siegfried Holding AG exemplify divergent capital efficiency models for mammalian cell culture scale-up. Samsung Biologics occupies a position at the scale-driven end of the Asian manufacturing tier, representing the tax-incentive-driven Korean cluster competing on speed-to-clinic timelines for monoclonal antibody sponsors.
| Leading Market Players |
|---|
| Lonza |
| Thermo Fisher Scientific |
| Catalent |
| Samsung Biologics |
| WuXi Biologics |
| WuXi AppTec |
| Siegfried Holding AG |
| Cambrex Corporation |
| Recipharm |
| Others |
Value Network & Pricing Analysis
Virtual pharma sponsors in Boston and South San Francisco anchor demand for flexible, project-based CDMO contracts where pricing reflects development milestone achievement rather than pure manufacturing throughput. This buyer concentration reinforces value-based pricing structures that tie fees to regulatory submission success and speed-to-clinic performance.
Pricing Analysis
Yield-guaranteed pricing anchors high-complexity biologics contracts, with sponsors paying premium rates for validated mammalian cell culture platforms that de-risk Phase III scale-up. Price differentiation separates FDA-inspected facilities from emerging-market alternatives, while single-use bioreactor supply constraints compress margins on legacy small-molecule chemistry. Cost compression in commoditized API synthesis is intensifying because Indian and Chinese manufacturers compete on volume scale. Virtual pharma sponsors exhibit highest price sensitivity, accepting premium positioning only for accelerated regulatory timelines.
Supply Chain Analysis
Regional distribution centers in Switzerland, South Korea, and Ireland anchor hub-and-spoke patterns for temperature-sensitive biologics drug product. Raw material dependencies center on platinum-group catalysts for small-molecule synthesis, single-use bioreactor films from three dominant suppliers, and viral vector plasmid banks for gene therapy production. Single-source vulnerability in bioreactor bag assembly creates exposure for mammalian cell culture operators. Distribution runs through qualified cold-chain logistics networks with validated serialization tracking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use bioreactor capacity constraints prop pricing power for qualified mammalian cell culture operators, creating a supply-constrained environment favoring incumbent expansion.
For Market Incumbents: Deepen mammalian cell culture platform credentials through Swissmedic and FDA dual-site inspections to defend against emerging Asian scale competitors. Prioritize gene therapy viral vector capacity additions in Basel-region clusters to capture ADC and cell therapy sponsor demand. Lock in long-term single-use bioreactor supply agreements to mitigate resin and tubing delivery volatility. For New Entrants and Emerging Players: Virtual pharma sponsors with orphan drug designations represent the most penetrable buyer archetype, as these asset-light biotechs lack internal CMC capabilities and prioritize speed over established relationships. Target South Korean tax incentive zones for parallel Asian-Western development paths. Differentiate through EU AI Act-compliant process analytical technology platforms that preempt regulatory validation requirements. For Investors and Strategic Acquirers: The window for entry favors CDMOs with validated continuous manufacturing infrastructure and pre-cleared algorithmic quality frameworks. Long-term viability hinges on regulatory harmonization speed for digital submission standards. Monitor FDA Quality Management Maturity program adoption rates as the inflection signal for quality system investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA's revised GMP Annex 1 compliance accelerates facility upgrade investments across European CDMOs. |
| Manufacturing Scale-Up | Single-use bioreactor deployments in South Korean free economic zones compress monoclonal antibody timelines. |
| Pipeline Diversification | Antibody-drug conjugate capabilities expand addressable service perimeter beyond conventional biologics manufacturing. |
| Licensing Agreement | Gene therapy viral vector partnerships with MFDS-registered sites enable parallel Asian-Western market development. |
| Clinical Trial Advancement | Real-time release testing integration supports orphan drug programs requiring rapid batch turnaround. |
Research Methodology
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and MFDS biologics licensing pathways, complemented by interviews with drug development executives, regulatory affairs leads, CDMO procurement managers, and formulary directors. Secondary validation drew from SEC 10-K disclosures, customs and trade data, and industry association reports. Bottom-up capacity assessments and top-down market sizing were triangulated against primary field intelligence.
Segment-level outputs across the analysis window reflect modeled trajectories for service type, client sophistication tier, technology platform, and regional regulatory cluster. CAGRs were derived from facility capacity expansion schedules, sponsor pipeline conversion rates, and inspection outcome probabilities. Forecast inputs incorporated single-use bioreactor supply constraints and Quality Management Maturity program adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization timing, platinum-group metal price volatility, and gene therapy CMC standardization. Outputs reflect documented assumptions about sponsor outsourcing depth and facility qualification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Inhalation and Nasal Spray Generic Drugs Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
Global Pediatric Vaccines Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Latin America Biguanide Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Global Blood Plasma Derivatives Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Medical Grade Sodium Hyaluronate Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Myocardial Infarction Drugs Market