
 China Business Income Insurance Market | 2026-2036
China Business Income Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
China Business Income Insurance Market Insights
China's dual carbon goals is repositioning business income insurance toward climate-resilience underwriting. Ping An Insurance leverages its proprietary risk-engineering platforms to embed carbon-transition exposure assessments within standard business interruption policies. People's Insurance Company of China anchors its market presence through state-backed infrastructure coverage mandates that bundle income protection with property policies. ZhongAn Online P&C Insurance differentiates via algorithmic claims triage that compresses indemnity cycles for digitally native SMEs.
Business income insurance indemnifies operating profit loss triggered by insured physical damage to commercial property, with policies typically specifying a 72-hour deductible period and maximum indemnity durations of 12 to 24 months. The coverage type dimension stratifies across property loss, revenue loss, extra expense, and rental income segments, with revenue loss riders commanding premium multiples due to their direct linkage to enterprise cash flow volatility. Within the industry vertical segmentation, manufacturing and construction lines absorb disproportionate capacity as supply-chain localization policies elevate contingent business interruption exposure across tier-one supplier networks.
SAMR enforces solvency-aligned product filing requirements that constrain speculative coverage extensions, while NMPA-aligned disclosure standards mandate granular risk-factor documentation for policies sold to pharmaceutical and medical device manufacturers. The CEA coordinates catastrophe reserve requirements that shape pricing adequacy for natural-peril-triggered business interruption covers. Stakeholders must monitor how evolving GB standards for business continuity management integrate with policy trigger definitions to determine coverage scope disputes.
Market Dynamics
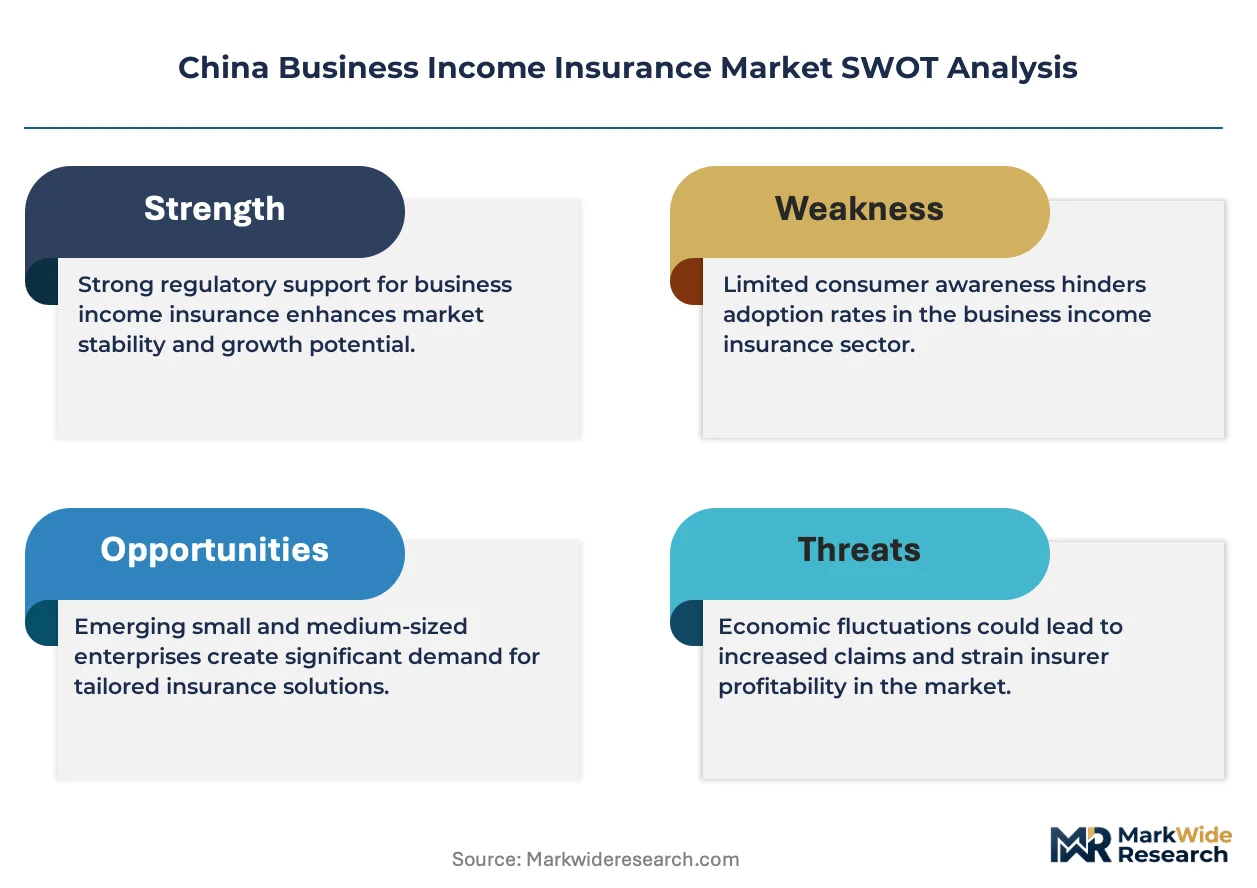
China's dual carbon goals are compressing business income insurance demand into manufacturing clusters facing mandatory operational continuity audits, while SAMR solvency rules constrain product innovation cycles.
Growth Catalysts
- Dual carbon compliance mandates:Jiangsu and Zhejiang manufacturing enterprises must secure revenue loss riders to satisfy MEE environmental audit requirements for production suspension coverage.
- Supply chain localization policies:Tier-one supplier networks are expanding contingent business interruption exposure as domestic sourcing quotas elevate interdependency risks.
- Algorithmic underwriting platforms:Risk-engineering systems embedding carbon-transition assessments are accelerating policy issuance velocity for medium enterprises.
Market Restraints
- Catastrophe reserve adequacy:CEA-coordinated requirements for natural-peril-triggered covers are compressing pricing flexibility during peak demand periods.
- GB standard integration delays:Business continuity management standards remain misaligned with policy trigger definitions, generating coverage scope disputes.
- Actuarial talent scarcity:Shortage of climate-risk modelers limits carrier capacity to underwrite complex carbon-transition exposures at scale.
Strategic Opportunities
- Digital native SME penetration:Algorithmic claims triage platforms can capture underserved digitally native enterprises in coastal manufacturing zones.
- NMPA-aligned disclosure convergence:Pharmaceutical and medical device manufacturers face mandatory granular risk-factor documentation, creating specialized product demand.
- Revenue loss rider unbundling:Direct-to-enterprise distribution channels can disintermediate traditional broker networks for cash-flow-sensitive buyers.
Industry Challenges
- Legacy policy administration integration:Carriers struggle to embed carbon-transition exposure modules into existing property policy infrastructure.
- Indemnity cycle compression:72-hour deductible periods and 12-24 month maximum durations require real-time loss verification systems that most carriers lack.
- Cross-provincial regulatory fragmentation:SAMR filing requirements vary across provincial bureaus, delaying product launches in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Business Income Insurance Market |
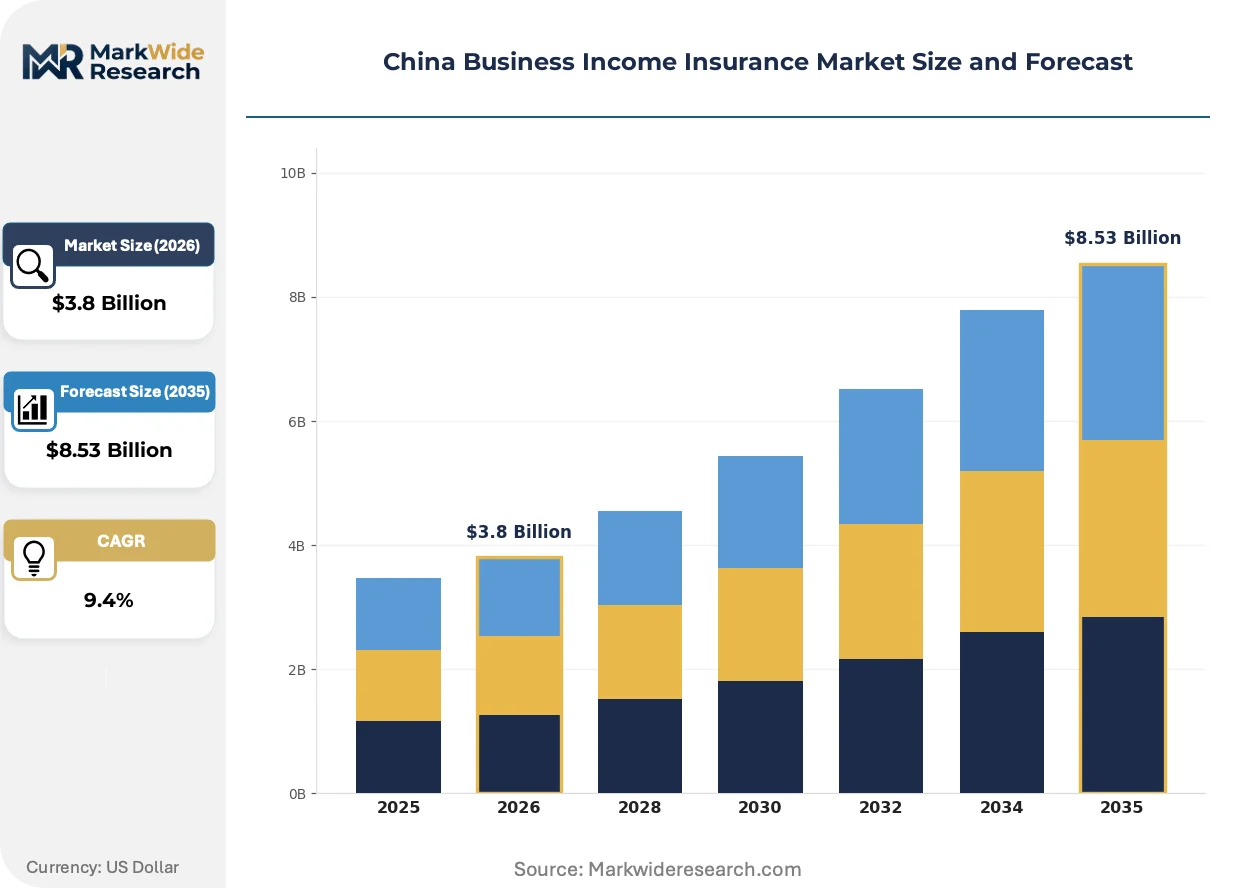
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Named Peril, Time Element, Business Interruption Industry Vertical: Manufacturing, Retail, Hospitality, Construction Coverage Type: Property Loss, Revenue Loss, Extra Expense, Rental Income Client Type: Small Enterprises, Medium Enterprises, Large Corporations, Franchise Operations |
| Companies Covered | Ping An Insurance (Group) Company of China, Ltd., China Life Insurance Co., Ltd., People's Insurance Company of China Co., Ltd., China Pacific Insurance (Group) Co., Ltd., New China Life Insurance Co., Ltd., Taikang Insurance Group, China Post Life Insurance Co., Ltd., ZhongAn Online P&C Insurance, Huatai Property & Casualty Insurance Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Business Income Insurance Market Trends and Innovations
China's business income insurance market is experiencing fundamental restructuring as carbon-transition risk quantification converges with algorithmic underwriting and regulatory disclosure mandates.
Proprietary risk-engineering platforms is rewriting how carriers assess operational continuity exposure. These systems integrate carbon-transition scenario modeling with traditional property damage triggers. Manufacturing enterprises in Jiangsu province are adopting these assessments at the fastest pace. The technology is compressing underwriting cycles from weeks to days while elevating precision in revenue loss projections.
SAMR solvency-aligned product filing requirements are tightening coverage extension parameters. Insurers must now demonstrate capital adequacy for each speculative rider before market release. Pharmaceutical manufacturers face the strictest scrutiny as NMPA disclosure standards cascade into insurance documentation. Carriers are responding by narrowing policy wordings and elevating premium multiples for complex exposures.
Medium enterprises are abandoning bundled property-income packages in favor of named peril policies with unbundled revenue loss components. Direct digital channels are displacing traditional broker intermediation for this segment. The shift is most visible in Zhejiang province where manufacturing density supports self-service policy configuration platforms. Buyers now demand 24-hour quote-to-bind cycles with transparent deductible structures.
China Business Income Insurance Market Segmentation
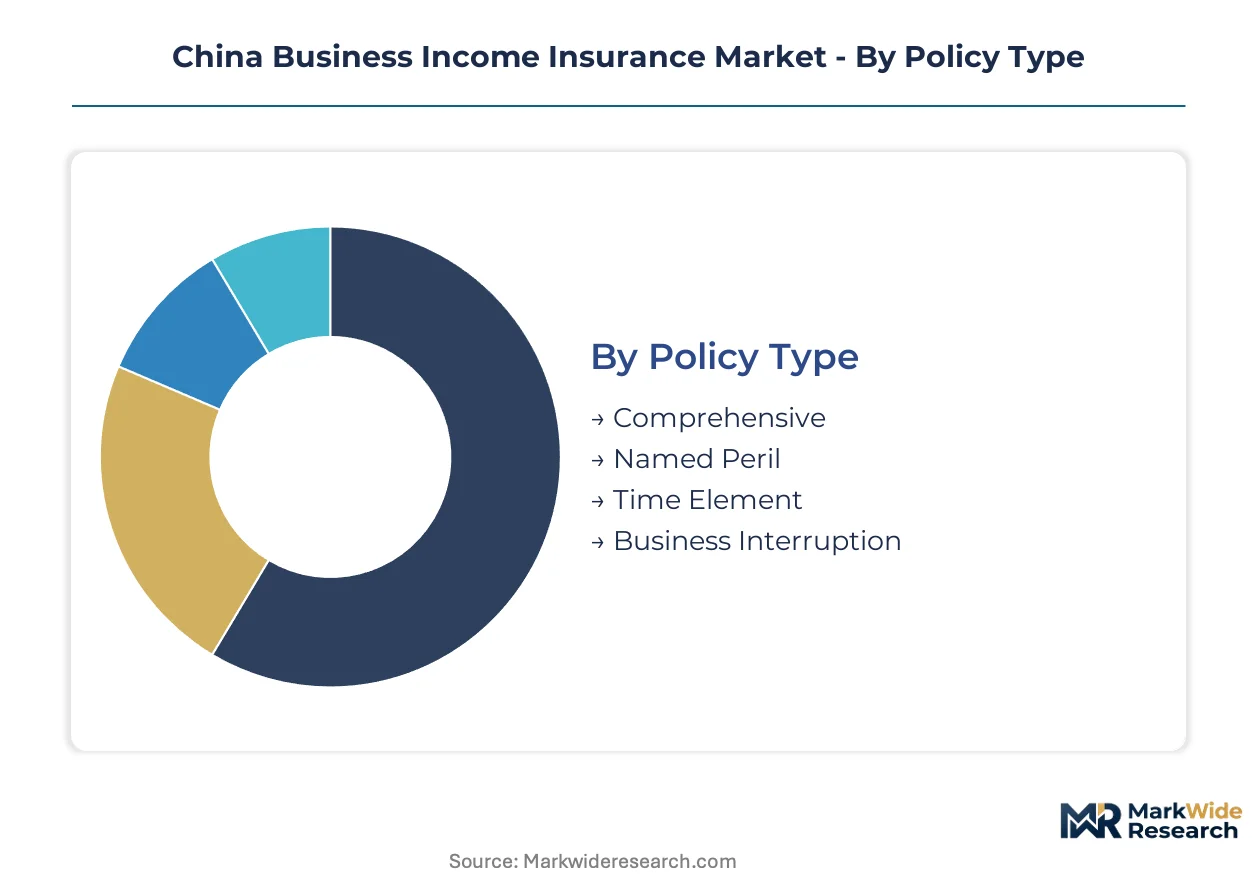
China's business income insurance segmentation reflects divergent regulatory compliance burdens across policy structures and buyer profiles. SAMR filing requirements and MEE environmental audit mandates create tiered certification complexity that reshapes carrier product strategies and enterprise procurement patterns.
Policy Type:
Comprehensive policies carry the heaviest SAMR solvency demonstration requirements, while Named Peril products face streamlined filing pathways for medium enterprise distribution.
- Comprehensive:Bundled property and income protection requiring granular capital adequacy documentation per SAMR solvency-aligned rules. Jiangsu manufacturing clusters absorb disproportionate capacity as dual carbon compliance mandates elevate operational continuity audit requirements.
- Named Peril:Restricted trigger definitions that narrow coverage scope but accelerate quote-to-bind velocity through reduced underwriting friction. Zhejiang province manufacturers favor these policies for revenue loss rider unbundling via direct digital channels.
- Time Element:Duration-specified indemnity structures calibrated to 12-24 month maximum periods with 72-hour deductible protocols.
- Business Interruption:Traditional physical-damage-triggered coverage facing legacy policy administration integration challenges with carbon-transition exposure modules.
Leading the category by volume: Comprehensive. Growing fastest: Named Peril.
Industry Vertical:
Manufacturing commands premium multiples due to supply chain localization policies, while Construction faces contingent business interruption exposure from tier-one supplier network interdependencies.
- Manufacturing:Dominant vertical absorbing carrier capacity as domestic sourcing quotas elevate revenue loss rider demand. Jiangsu and Zhejiang enterprises lead procurement velocity under tightening MEE environmental audit frameworks.
- Retail:Inventory-heavy operations seeking extra expense coverage for alternative location costs during physical damage recovery periods.
- Hospitality:Seasonal cash flow volatility driving demand for rental income segments with compressed deductible structures.
- Construction:Project-based revenue recognition patterns complicating indemnity period calibration against GB standard business continuity management requirements.
Highest margin concentration: Manufacturing. Steepest expansion trajectory: Construction.
Coverage Type:
Revenue Loss segments command premium multiples due to direct cash flow linkage, while Property Loss maintains baseline penetration through bundled infrastructure mandates.
- Property Loss:Foundational coverage anchoring state-backed infrastructure policy bundles. SAMR filing requirements treat this as core capital adequacy demonstration tier.
- Revenue Loss:Unbundled rider components attracting medium enterprise demand through transparent deductible structures and 24-hour digital quote-to-bind platforms.
- Extra Expense:Cost reimbursement for mitigation actions during insured suspension periods, critical for pharmaceutical manufacturers under NMPA-aligned disclosure standards.
- Rental Income:Commercial landlord protection segment facing misalignment between GB standard business continuity definitions and policy trigger documentation.
Premium concentration peaks at: Revenue Loss. Algorithmic underwriting penetration deepest in: Extra Expense.
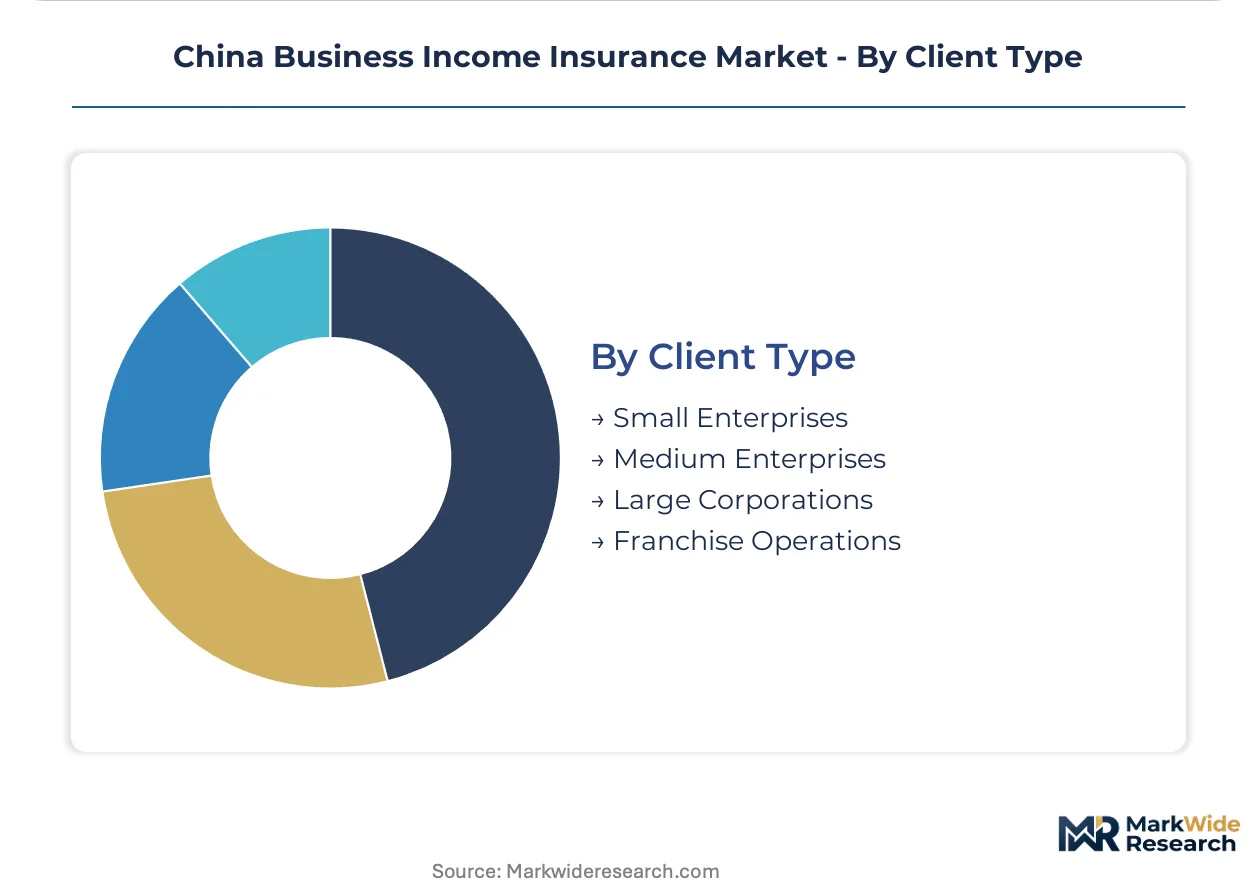
Client Type:
Medium Enterprises drive product innovation as algorithmic platforms displace broker intermediation, while Large Corporations absorb regulatory scrutiny concentration for complex multi-site programs.
- Small Enterprises:Price-sensitive buyers concentrated in coastal manufacturing zones seeking basic property loss coverage with minimal rider extensions.
- Medium Enterprises:Primary growth segment abandoning bundled packages for named peril policies with unbundled revenue loss components. Zhejiang province density supports self-service configuration platforms.
- Large Corporations:Multi-site programs requiring cross-provincial SAMR filing coordination that delays product launches and elevates compliance documentation burdens.
- Franchise Operations:Standardized coverage templates across networked locations facing indemnity cycle compression demands for real-time loss verification systems.
Carrier investment priority: Medium Enterprises. Regulatory filing complexity concentrates at: Large Corporations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province's manufacturing corridor anchors China's business income insurance expansion, with Suzhou and Wuxi industrial clusters driving policy issuance velocity under tightening environmental audit frameworks.
Jiangsu Province
Manufacturing enterprises in Suzhou and Wuxi are expanding coverage purchases as MEE environmental audit requirements mandate revenue loss riders for production suspension scenarios. SAMR solvency-aligned filing requirements treat comprehensive policies from this cluster as core capital adequacy demonstration tiers. The Yangtze River Delta manufacturing belt concentrates carrier capacity allocation due to supply chain localization policy interdependencies.
Zhejiang Province
Medium enterprises in Hangzhou and Ningbo are abandoning bundled property-income packages for named peril policies with unbundled revenue loss components. Direct digital channels displace traditional broker intermediation as self-service configuration platforms achieve 24-hour quote-to-bind cycles. The province's manufacturing density supports algorithmic underwriting penetration for cash-flow-sensitive buyers.
Beijing-Tianjin-Hebei
State-backed infrastructure coverage mandates bundle income protection with property policies across capital region construction and logistics operations. NMPA-aligned disclosure standards cascade into insurance documentation for pharmaceutical manufacturers in the Beijing biotech corridor. GB standard business continuity management requirements generate coverage scope disputes for rental income segments.
Guangdong Province
Pearl River Delta manufacturing hubs face contingent business interruption exposure as domestic sourcing quotas elevate tier-one supplier network interdependencies. CEA-coordinated catastrophe reserve requirements shape pricing adequacy for natural-peril-triggered covers across Shenzhen and Dongguan industrial zones. Cross-provincial SAMR filing variations delay product launches for multi-site programs.
Sichuan-Chongqing
Western China manufacturing expansion is compressing actuarial talent scarcity constraints as climate-risk modeler shortages limit carrier capacity for carbon-transition exposures. MEE environmental audit frameworks are extending to Chengdu and Chongqing industrial parks. Algorithmic claims triage platforms target digitally native SMEs in this emerging manufacturing belt.
China Business Income Insurance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across proprietary risk-engineering capability and algorithmic underwriting velocity. The market structures around three tiers: state-backed incumbents with infrastructure mandate access, digital-native specialists with compressed indemnity cycles, and mid-tier carriers with regional filing advantages. Strategic archetypes include carbon-transition risk engineers, direct-channel disintermediators, and compliance-documentation specialists. Competitive moves concentrate on M&A for risk-engineering platforms and strategic partnerships for algorithmic claims infrastructure.
Within the state-backed tier, People's Insurance Company of China and China Pacific Insurance exemplify carriers leveraging infrastructure coverage mandates to anchor market presence. Among digital-native specialists, ZhongAn Online P&C Insurance occupies a position representing algorithmic claims triage platforms that compress indemnity cycles for SME segments. These three companies represent the dominant competitive archetypes reshaping product distribution and underwriting velocity across provincial manufacturing clusters.
| Leading Market Players |
|---|
| Ping An Insurance (Group) Company of China, Ltd. |
| China Life Insurance Co., Ltd. |
| People's Insurance Company of China Co., Ltd. |
| China Pacific Insurance (Group) Co., Ltd. |
| New China Life Insurance Co., Ltd. |
| Taikang Insurance Group |
| China Post Life Insurance Co., Ltd. |
| ZhongAn Online P&C Insurance |
| Huatai Property & Casualty Insurance Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
State-backed carriers with infrastructure mandate access anchor supply-side concentration, while private risk-engineering specialists discipline pricing through proprietary carbon-transition assessment platforms. SAMR solvency-aligned filing requirements create tiered capital adequacy barriers that stratify premium multiples across carrier archetypes.
Pricing Analysis
Value-based pricing anchored to operational continuity outcomes dominates comprehensive policy structures, with revenue loss riders commanding premium multiples due to direct cash flow volatility linkage. Price differentiation centers on SAMR solvency demonstration burden and NMPA-aligned disclosure granularity, with pharmaceutical manufacturers facing the steepest certification premiums. Pricing pressure stems from CEA-coordinated catastrophe reserve adequacy requirements compressing natural-peril-triggered cover flexibility. Medium enterprises exhibit highest price sensitivity, abandoning bundled packages for unbundled named peril components.
Supply Chain Analysis
Single-source vulnerability sits with proprietary risk-engineering platform providers concentrated in Beijing and Shanghai technology corridors. Algorithmic underwriting infrastructure draws from cloud computing resources, actuarial talent pools, and carbon-transition scenario databases. Supply chain risk centers on actuarial climate-risk modeler scarcity limiting carrier capacity expansion. Distribution runs through direct digital channels displacing traditional broker intermediation for medium enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where SAMR solvency-aligned product filing requirements erect capital adequacy moats favoring carriers with established regulatory documentation infrastructure.
For Market Incumbents: To counter algorithmic underwriting velocity from digital-native specialists, deepen proprietary risk-engineering platform investment with embedded carbon-transition scenario modules. Secure cross-provincial SAMR filing coordination capabilities to accelerate product launches in secondary markets. For New Entrants and Emerging Players: NMPA-aligned disclosure standards in China's pharmaceutical corridor open a window for specialized compliance-documentation products targeting medical device manufacturers. Penetrate the underserved digitally native SME segment in Zhejiang province through self-service policy configuration platforms with transparent deductible structures. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier carriers with regional SAMR filing advantages in Jiangsu and Zhejiang manufacturing belts. Long-term viability hinges on algorithmic claims infrastructure ownership. Watch for MEE environmental audit framework extensions as inflection indicators for revenue loss rider demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Risk-Engineering Platform Acquisition | Ping An's carbon-transition assessment capabilities compress underwriting cycles from weeks to days for manufacturing clients. |
| Algorithmic Claims Infrastructure Partnership | ZhongAn's triage platforms reduce indemnity cycles for digitally native SMEs in coastal manufacturing zones. |
| Cross-Provincial SAMR Filing Coordination | Multi-site program launches accelerate when carriers navigate provincial bureau variation in solvency documentation. |
| NMPA-Aligned Disclosure Product Development | Pharmaceutical manufacturers face mandatory granular risk-factor documentation creating specialized coverage demand. |
| Direct Digital Channel Expansion | Self-service platforms in Zhejiang achieve 24-hour quote-to-bind cycles displacing traditional broker intermediation. |
Research Methodology
Document review covered SAMR product filing databases, CEA catastrophe reserve disclosures, and GB standard business continuity frameworks, complemented by interviews with underwriting executives at state-backed carriers, risk-engineering platform specialists, and MEE environmental audit consultants. Secondary validation drew from NMPA regulatory circulars, provincial insurance bureau annual reports, and manufacturing cluster operational continuity assessments. Bottom-up policy issuance data triangulated against top-down carrier capacity allocation estimates.
Cross-reference between historical premium growth patterns and expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include policy type, industry vertical, coverage type, and client size tier, with provincial regulatory cluster variations incorporated. CAGRs derived from trend extrapolation adjusted for dual carbon compliance mandate acceleration and supply chain localization policy impacts. Carbon-transition exposure quantification methods and algorithmic underwriting penetration rates served as industry-specific forecast inputs.
Caveats apply where MEE environmental audit framework revisions or GB standard business continuity management alignment delays could materially shift the outlook. Forecasts reflect assumptions around SAMR solvency rule stability and catastrophe reserve adequacy calibration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Cyber Insurance Market
Insurance
Group Health Insurance Market
Insurance
GCC Health Insurance Market
Insurance
Aviation Insurance Market
Insurance
GCC Bancassurance Market
Insurance
China Parametric Insurance Market
Insurance
India Dental Insurance Market
Insurance
Agricultural Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
United Kingdom Car Insurance Market
Insurance
Europe Extended Warranty Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
Agriculture Insurance Market
Insurance
Asia-Pacific Family Floater Health Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market