
 GCC Health Insurance Market | 2026-2036
GCC Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Health Insurance Market Intelligence
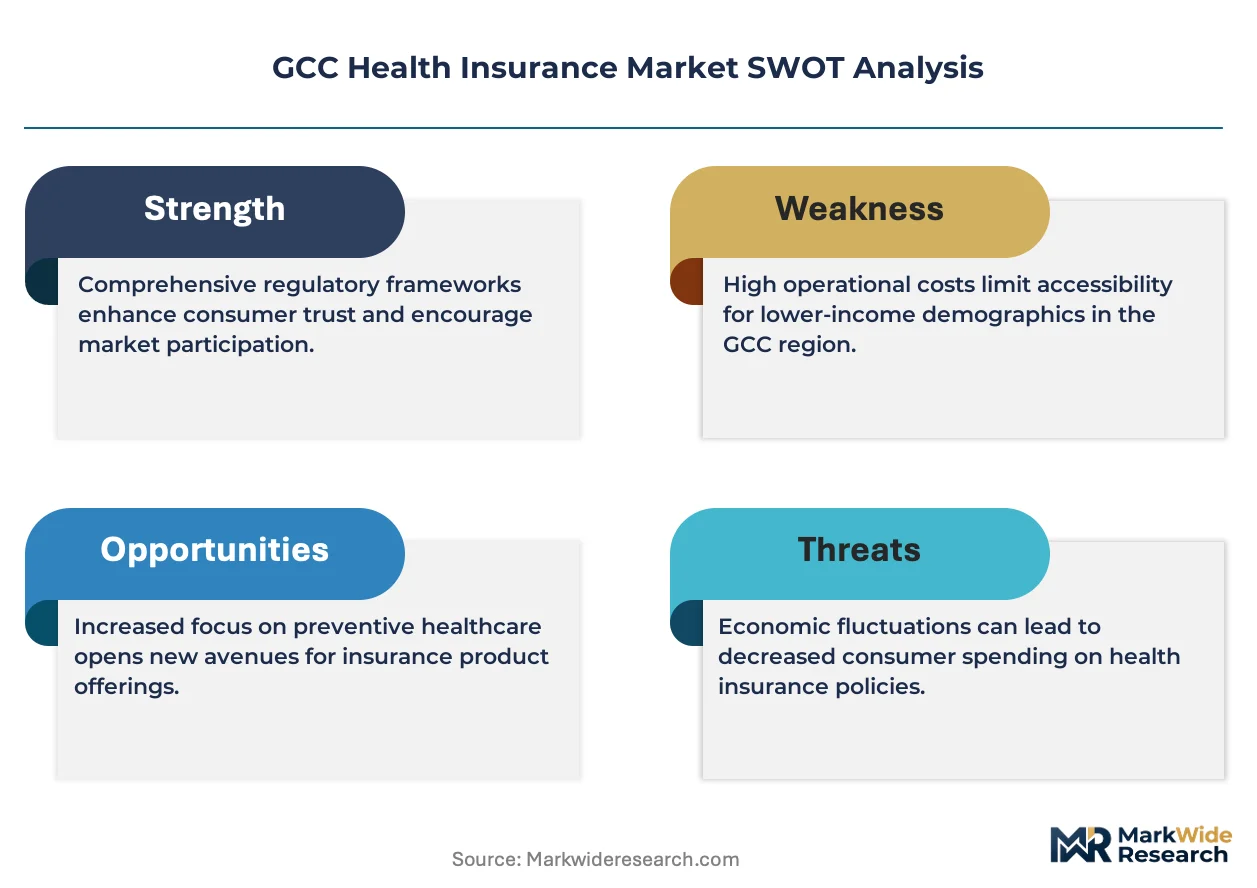
Comprehensive coverage tiers is bifurcating the GCC health insurance landscape into basic-mandatory and premium-voluntary segments. Tawuniya leverages its dominant position in Saudi group coverage to anchor large employer portfolios. Daman Health Insurance differentiates through direct provider networks in Abu Dhabi, sustaining membership retention. Bupa Global competes on international portability, serving mobile executive segments across multiple Gulf jurisdictions.
GCC health insurance constitutes risk-pooling financial instruments designed to cover medical expenditure through premium contributions, with actuarial reserves regulated by central bank solvency ratios and minimum capital adequacy requirements. Its primary purpose is to transfer individual health cost volatility onto collective balance sheets while ensuring provider network access. Group plans command the deepest enrollment pools, while critical illness coverage represents the fastest-growing margin segment as cardiovascular and oncology prevalence rises. Individual plans remain concentrated among high-net-worth expatriates and self-employed professionals seeking portable benefits.
The UAE Insurance Authority, Saudi Central Bank, and Dubai Health Authority collectively enforce mandatory enrollment thresholds, network adequacy standards, and premium rate oversight across the Gulf. These frameworks compel insurers to maintain minimum loss ratios and localized provider contracts, elevating operational barriers for foreign entrants. Stakeholders must monitor regulatory divergence between Saudi price-cap regimes and UAE liberalized competition zones as compliance architecture becomes a primary competitive differentiator.
Market Dynamics
Mandatory health insurance regulations across Saudi Arabia, the UAE, and Qatar are compressing enrollment timelines while elevating compliance costs for insurers operating across multiple Gulf jurisdictions.
Growth Catalysts
- Expatriate workforce expansion:Large-scale infrastructure projects in Saudi Arabia and Qatar are importing skilled labor pools that require group coverage under employer sponsorship mandates.
- Thiqa program integration:Abu Dhabi's government-funded scheme for UAE nationals is channeling additional volume through authorized private insurers, deepening public-private collaboration.
- Cardiovascular prevalence:Rising diabetes and heart disease rates across Gulf populations are elevating demand for critical illness riders and specialized care networks.
Market Restraints
- Medical inflation volatility:Pharmaceutical import dependence and specialist physician shortages in secondary Gulf cities are compressing loss ratios below sustainable thresholds.
- Reinsurance capacity concentration:Regional risk carriers rely disproportionately on London and Singapore reinsurance markets, exposing pricing to hard-market cycles beyond local control.
- Provider network adequacy gaps:Rural Saudi Arabia and northern Emirates lack sufficient accredited hospitals to satisfy DHA and SFDA network density requirements.
Strategic Opportunities
- Oman market liberalization:The sultanate's gradual shift from state-dominated provision creates entry points for private insurers willing to build localized provider infrastructure.
- Telehealth integration:Remote consultation platforms are converging with traditional indemnity models, enabling first-mover insurers to differentiate through virtual primary care access.
- Kuwaiti mandatory transition:Pending implementation of compulsory private coverage for expatriates represents a captured expansion window before regulatory saturation.
Industry Challenges
- Actuarial talent scarcity:Gulf-based insurers face acute shortages of professionals credentialed in both Islamic takaful principles and international reserving standards.
- Legacy system integration:Policy administration platforms from 1990s-era deployments resist API connectivity with modern health information exchanges mandated by Dubai Health Authority.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Health Insurance Market |
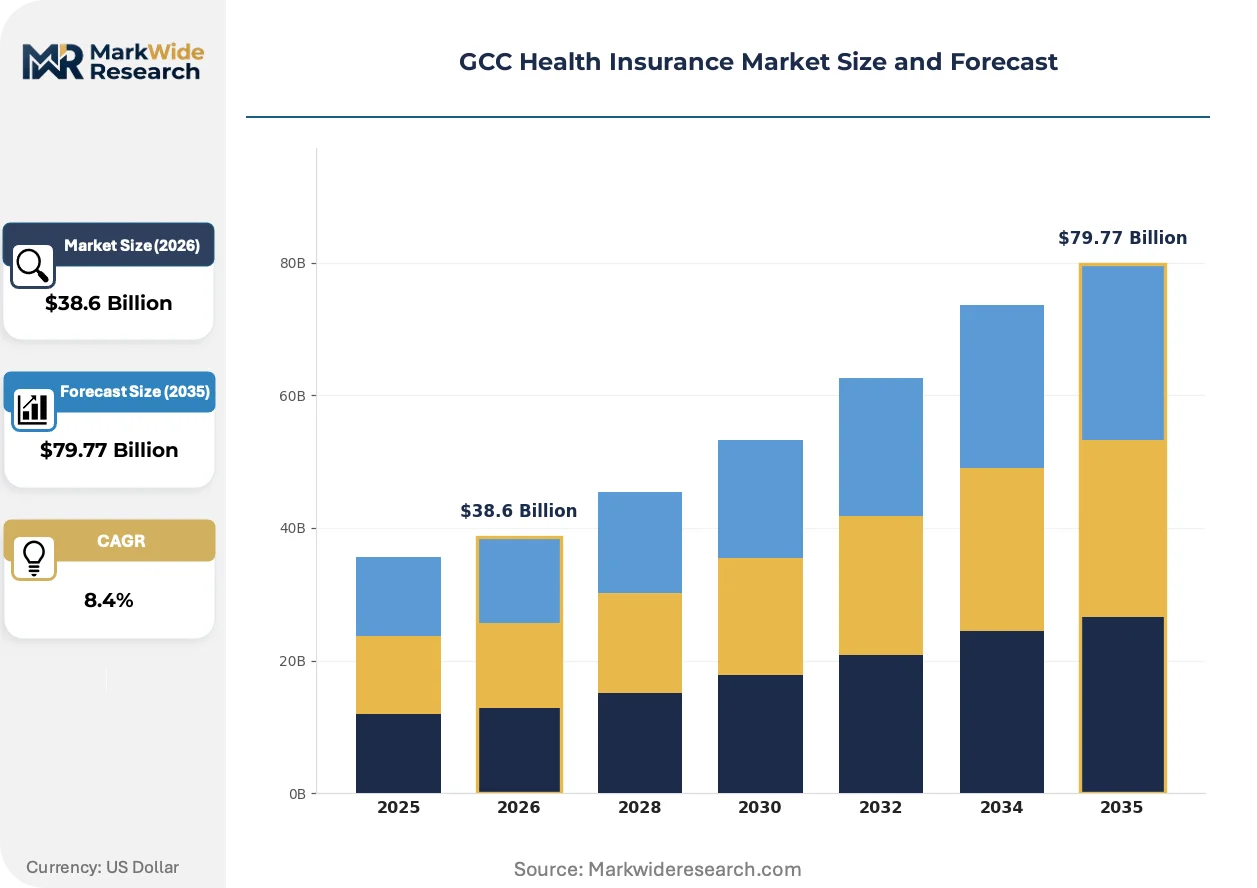
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Individual Plans, Family Plans, Group Plans, Critical Illness Plans End User: Employees, Retirees, Self-employed Individuals, Students Delivery Model: Direct Sales, Online Platforms, Brokers, Insurance Agents Coverage Type: Inpatient, Outpatient, Preventive, Dental |
| Companies Covered | Bupa Global, Tawuniya, Daman Health Insurance, Al Rajhi Takaful, Walaa, AXA Cooperative, MetLife Services and Solutions LLC, Wataniya Insurance, MEDGULF, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Health Insurance Market Strategic Shifts & Innovations
Digital distribution channels are compressing traditional broker intermediation while artificial intelligence tools reshape underwriting precision and claims adjudication speed across Gulf markets.
Blockchain-based claims processing is fragmenting the dominance of centralized clearinghouses. Insurtech platforms in Dubai and Riyadh are piloting distributed ledger verification for pre-authorization workflows. This compression of settlement timelines is fragmenting incumbent advantages built on decades of manual relationship management with hospital networks.
Dubai Health Authority's mandatory health insurance law and its 2024 network adequacy amendments are tightening provider accreditation standards. Insurers must now demonstrate real-time eligibility verification capabilities to maintain operating licenses. Smaller carriers lacking IT infrastructure are exiting the Dubai market rather than absorbing compliance costs.
Employer-sponsored plan design is gravitating toward value-based arrangements that tie premium adjustments to measurable health outcomes. Large Saudi conglomerates are negotiating direct primary care contracts that bypass traditional indemnity structures. This behavioral pivot is most pronounced in Riyadh and Jeddah, where corporate wellness mandates from the Saudi Ministry of Human Resources are accelerating adoption.
GCC Health Insurance Market Segmentation
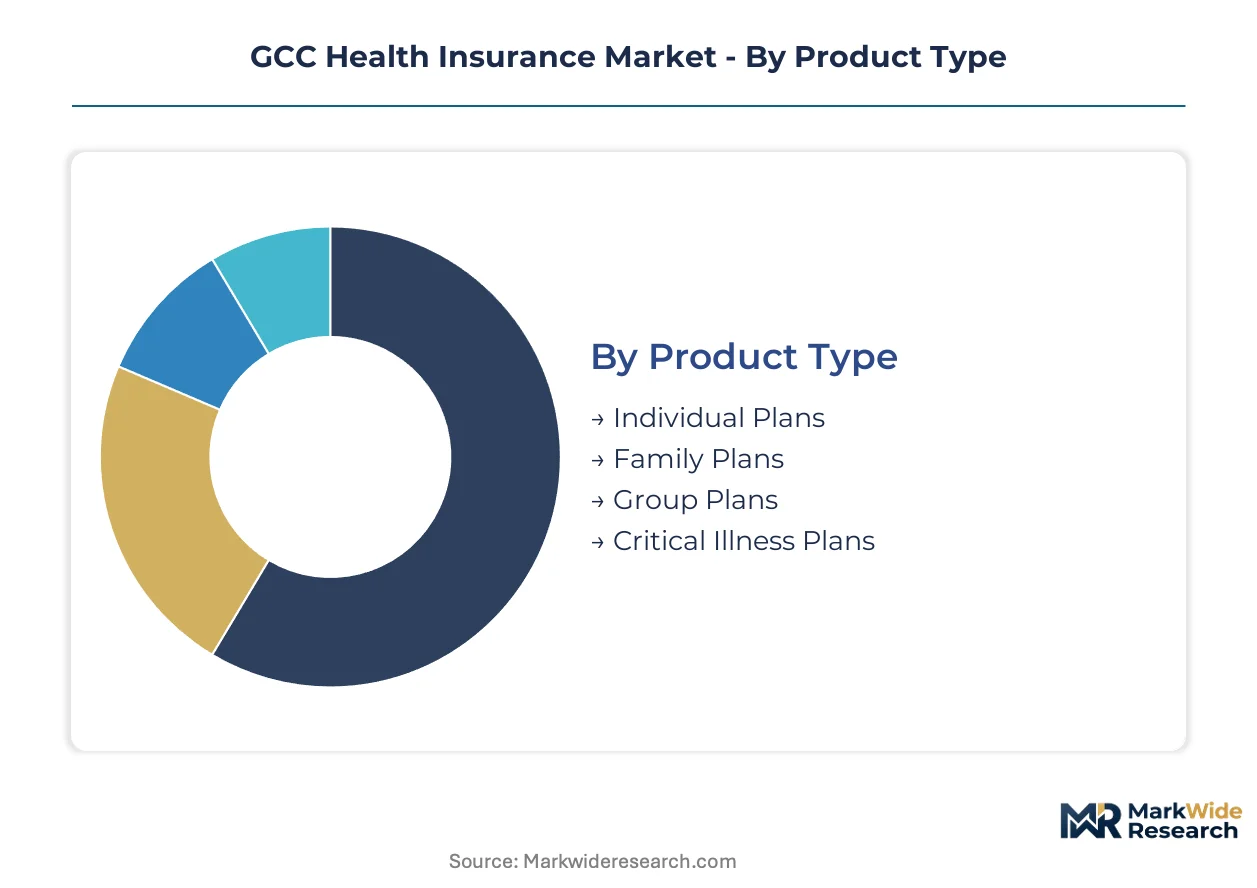
Segmentation in the GCC health insurance market reveals distinct margin pools aligned with regulatory mandates and workforce demographics. Product architecture, distribution channels, and coverage tiers each concentrate value differently across Saudi Arabia, the UAE, and Qatar.
Product Type:
Margin pools concentrate heavily in employer-sponsored categories where regulatory mandates guarantee enrollment volume and pricing power.
- Group Plans:Employer-sponsored coverage pools risk across expatriate workforces in Saudi Arabia and the UAE. Mandatory sponsorship laws in Riyadh and Dubai lock in recurring premium flows from construction, energy, and logistics sectors.
- Critical Illness Plans:Specialized riders covering cardiovascular and oncology treatments command premium pricing. Saudi Arabia's rising diabetes prevalence and the UAE's aging expatriate population concentrate demand in tertiary hospital networks.
- Individual Plans:Portable coverage for high-net-worth expatriates and self-employed professionals. Concentrated in Dubai and Abu Dhabi where regulatory portability requirements apply.
- Family Plans:Dependent coverage extensions tied to primary policyholders. Volume clusters in Qatar and Kuwait where family sponsorship rules dominate visa structures.
The dominant share belongs to Group Plans, while Critical Illness Plans are closing the gap fastest.
End User:
Volume distribution tracks labor force composition and visa category regulations across Gulf jurisdictions.
- Employees:Corporate workforce segments covered under employer mandates. Saudi Arabia's Nitaqat system and the UAE's Wage Protection System enforce enrollment verification.
- Self-employed Individuals:Freelancers and independent contractors purchasing portable coverage. Concentrated in Dubai's free zones and Saudi Arabia's growing gig economy.
- Students:University-mandated coverage for international enrollees. Volume clusters in Qatar's Education City and UAE branch campuses.
- Retirees:Post-employment continuation coverage. Limited penetration due to expatriate visa age restrictions in most GCC states.
Employees capture the deepest enrollment base, though Self-employed Individuals are expanding most quickly.
Delivery Model:
Channel economics shift as regulatory mandates force digitization and compress traditional intermediation.
- Brokers:Traditional intermediaries managing corporate placements and renewals. Retain dominance in complex multi-jurisdiction employer programs.
- Online Platforms:Direct-to-consumer portals and aggregator sites. Dubai Health Authority's real-time eligibility requirements accelerate adoption.
- Insurance Agents:Individual producers serving retail and family segments. Concentrated in Saudi Arabia's secondary cities with limited digital infrastructure.
- Direct Sales:Insurer-owned channels for large corporate accounts. Tawuniya and Daman Health Insurance deploy captive teams for key accounts.
Brokers retain the largest transaction volume, yet Online Platforms are gaining share fastest.
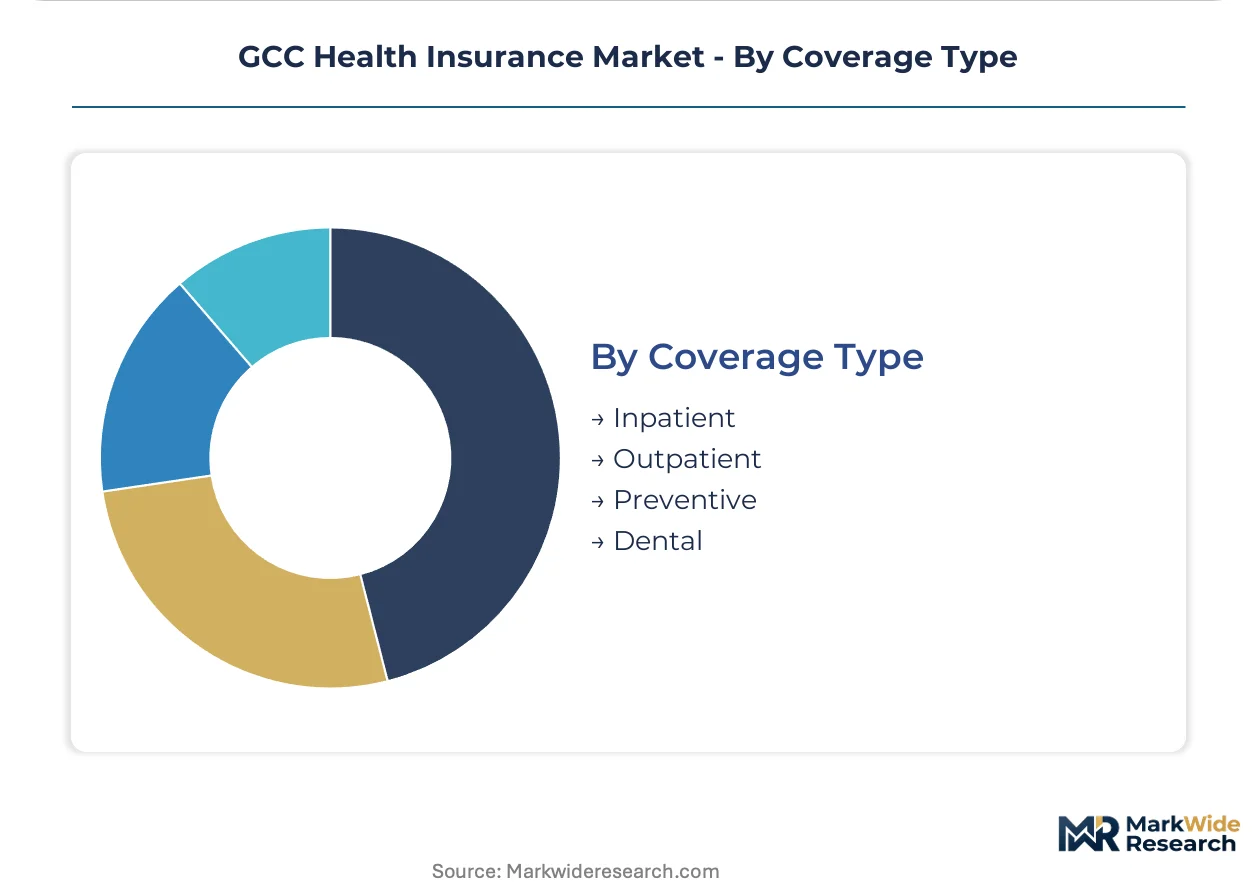
Coverage Type:
Benefit design concentrates cost in acute care while preventive coverage remains underutilized.
- Inpatient:Hospitalization and surgical coverage forming the core of mandatory benefit packages. Regulatory minimums in Abu Dhabi's Thiqa program and Dubai's Essential Benefits Plan set baseline standards.
- Outpatient:Clinic visits, diagnostics, and specialist consultations. Network adequacy requirements from Saudi Central Bank and DHA drive provider contracting intensity.
- Dental:Elective coverage typically excluded from basic mandatory tiers. Premium uptake concentrates in corporate executive plans.
- Preventive:Wellness screenings and vaccination programs. Limited utilization despite Saudi Ministry of Health wellness mandates.
Inpatient claims absorb the dominant cost share, while Outpatient utilization is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insurer balance sheets concentrate heavily in Saudi Arabia and the UAE, where mandatory enrollment laws and large expatriate workforces generate recurring premium flows. Regulatory divergence between Riyadh's price-cap regimes and Dubai's liberalized competition zones shapes capital deployment strategies across the Gulf.
Saudi Arabia
Construction and energy sector expansion drives group plan enrollment under the Nitaqat workforce localization framework. The Saudi Central Bank enforces minimum loss ratios and solvency requirements that compress margins for foreign entrants. Riyadh and Jeddah host the deepest insurer headquarters concentration, with corporate wellness mandates from the Ministry of Human Resources accelerating value-based plan adoption.
United Arab Emirates
Dubai's free zone economies and Abu Dhabi's Thiqa program integration channel divergent demand streams through authorized private carriers. Dubai Health Authority mandates real-time eligibility verification and network adequacy standards that filter out smaller competitors. The Dubai International Financial Centre clusters regional headquarters for multinational insurers seeking Gulf market access.
Qatar
Large-scale infrastructure projects ahead of international sporting events import skilled labor requiring employer-sponsored coverage. The national health insurance scheme mandates private sector participation for expatriate populations. Doha's Education City generates student-mandated coverage volume through university enrollment requirements.
Kuwait
Pending compulsory private coverage implementation for expatriates represents a pre-saturation expansion window. The Ministry of Health currently dominates provision through state facilities. Kuwait City's corporate sector shows early demand for portable individual plans among self-employed professionals and gig economy participants.
Oman
Gradual market liberalization shifts provision from state-dominated structures toward authorized private insurers. The Capital Market Authority issues licenses contingent on localized provider infrastructure commitments. Muscat and Salalah concentrate initial private network development as international carriers test market entry feasibility.
GCC Health Insurance Market Key Industry Players
Concentration sits with domestic incumbents possessing decades of regulatory relationships and captive provider networks. Saudi and Emirati carriers anchor the landscape through mandatory enrollment volumes and government program authorizations. Three archetypes dominate: state-affiliated giants with Thiqa and Nitaqat program access, multinational specialists competing on international portability, and regional takaful operators serving Sharia-compliant segments. Competitive moves center on direct primary care contracting that bypasses traditional indemnity structures, and telehealth platform integration to satisfy DHA real-time verification mandates.
Among the established carrier set, Tawuniya and Daman Health Insurance exemplify domestic incumbents with deep government program integration, while Bupa Global occupies the multinational portability tier. Tawuniya represents the state-affiliated archetype leveraging Saudi group coverage dominance. Daman Health Insurance anchors the Abu Dhabi market through Thiqa program authorization. Bupa Global sits within the mobile executive segment across multiple Gulf jurisdictions.
| Leading Market Players |
|---|
| Bupa Global |
| Tawuniya |
| Daman Health Insurance |
| Al Rajhi Takaful |
| Walaa |
| AXA Cooperative |
| MetLife Services and Solutions LLC |
| Wataniya Insurance |
| MEDGULF |
| Others |
Cost & Logistics Intelligence
Dubai Health Authority's mandatory health insurance law and its network adequacy amendments gate both insurer licensing and premium tier differentiation simultaneously. The regulation compels real-time eligibility verification infrastructure that smaller carriers cannot absorb, while its Essential Benefits Plan establishes baseline coverage floors that stratify voluntary upgrade pricing above mandatory tiers.
Pricing Analysis
Dubai's Essential Benefits Plan dictates the pricing tier structure across the GCC health insurance landscape. Three-tier pricing structure across premium, standard, and economy levels separates basic-mandatory coverage from mid-tier corporate plans and executive international portability products. Price differentiation hinges on network breadth and geographic coverage scope, with premium tiers commanding access to cross-border provider networks. Cost compression in the economy tier is intensifying because pharmaceutical import dependence and specialist physician shortages in secondary Gulf cities compress loss ratios. Small and mid-sized employers demonstrate the highest price sensitivity, while mobile executive segments exhibit minimal elasticity for portable international coverage.
Supply Chain Analysis
Saudi Arabia and the UAE anchor health insurance provision through dominant domestic incumbents with decades of regulatory relationships and captive provider networks. The supply chain draws from London and Singapore reinsurance markets for risk capacity, pharmaceutical import channels for drug cost components, and localized hospital accreditation systems for network adequacy. Single-source vulnerability concentrates in reinsurance capacity, exposing regional carriers to hard-market pricing cycles beyond local control. Distribution runs through broker intermediaries for complex corporate placements, direct sales teams for large accounts, and emerging online platforms for individual and family segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC health insurance market represents an early-cycle expansion story as Oman and Kuwait transition from state-dominated provision toward mandatory private coverage frameworks. This regulatory tailwind creates penetration headroom before saturation compresses returns.
For Market Incumbents: Consolidate through direct primary care contracting that bypasses traditional indemnity structures, capturing margin from value-based arrangements. Deepen telehealth platform integration to satisfy Dubai Health Authority real-time verification mandates and filter out smaller competitors lacking IT infrastructure. Capacity addition in Oman's Muscat and Salalah markets secures first-mover positioning before regulatory saturation. For New Entrants and Emerging Players: Lead with telehealth-integrated products targeting Kuwait's pending compulsory private coverage implementation for expatriates, where incumbent presence remains thin. The self-employed individual segment in Dubai's free zones and Saudi Arabia's gig economy offers the most penetrable entry point. A digital-first distribution model leveraging aggregator platforms and direct-to-consumer portals bypasses broker-dominated corporate channels where incumbents hold entrenched relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational insurers seeking to exit non-core Gulf operations amid regulatory divergence between Saudi price-cap regimes and UAE liberalized competition zones. Long-term viability centers on carriers with Thiqa or Nitaqat program authorizations that lock in recurring government-backed premium flows. The signal to watch is Dubai Health Authority enforcement actions against smaller carriers lacking real-time eligibility verification capabilities, which accelerates consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Dubai Health Authority mandates real-time eligibility verification, filtering out IT-deficient competitors. |
| Direct Primary Care Contracting | Saudi corporate wellness mandates from the Ministry of Human Resources accelerate value-based plan adoption. |
| Thiqa Program Authorization | Abu Dhabi's government-funded scheme channels volume through authorized private insurers, deepening public-private collaboration. |
| Reinsurance Market Diversification | London and Singapore market concentration exposes pricing to hard-market cycles beyond local control. |
| Oman Market Entry | Capital Market Authority licenses contingent on localized provider infrastructure commitments test feasibility. |
Research Approach
A standing panel of health insurance underwriters, regulatory affairs specialists at Dubai Health Authority and Saudi Central Bank, hospital procurement managers, and reinsurance brokers provided ongoing calibration. Primary interviews with these stakeholders combined with secondary validation from Insurance Authority filings, DHA network adequacy reports, Saudi Central Bank solvency disclosures, and customs data on pharmaceutical imports. Bottom-up enrollment data triangulated against top-down premium flow estimates across the analysis window.
Consistency checks validated volume and value outputs against regulatory enrollment thresholds and historical loss ratio patterns. The analytical framework modeled segmentation across product type, end user, delivery model, and coverage type throughout the forecast period. CAGRs derived from actuarial projections of expatriate workforce growth, cardiovascular prevalence trends, and regulatory implementation timelines. Industry-specific inputs included Nitaqat workforce localization quotas and Thiqa program integration schedules.
Forecasts assume regulatory continuity in Dubai Health Authority mandatory coverage regimes and Saudi Central Bank solvency requirements; material policy shifts would require re-modeling. Specific risks include medical inflation volatility from pharmaceutical import dependence and reinsurance capacity contraction in London and Singapore markets. Recalibration cycles align with material shifts in mandatory enrollment law implementations and network adequacy standard amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Dental Insurance Market
Insurance
Self Funded Insurance Market
Insurance
Europe Online Insurance Market
Insurance
Aircraft Insurance Market
Insurance
General Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Endowment Insurances Market
Insurance
Aerospace Insurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
Group Health Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
United States Bancassurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
Global Mobile Phone Insurance Ecosystem Market
Insurance
Insurance Protection Products Market
Insurance
Asia-Pacific Group Health Insurance Market