
 Income Protection Insurance Market | 2026-2036
Income Protection Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Income Protection Insurance Market Insights
Gig economy participation is decoupling from traditional employer-sponsored income protection coverage, forcing insurers to design products for fragmented employment structures. Prudential leverages its group benefits infrastructure to serve hybrid workforces across multiple geographies. Aviva anchors its competitive position through direct-to-consumer distribution channels that bypass intermediary commissions. Legal & General differentiates via long-term coverage products tied to defined-benefit pension schemes.
Income protection insurance constitutes a contractual risk-transfer instrument where an insurer replaces a portion of earned income during periods of disability or incapacity, typically covering 50-70% of pre-disability earnings after a deferred waiting period. The product serves both individual financial stability and macroeconomic resilience by preventing household default cascades during health shocks. Short-term coverage policies command the largest premium volume due to lower barriers to purchase and employer sponsorship prevalence, while flexible plans represent the fastest-growing structural category as policyholders demand adjustable benefit periods and premium holidays. Online platforms as a distribution channel are capturing disproportionate growth among self-employed professionals who research and purchase coverage outside traditional advisory relationships.
The UK's Financial Conduct Authority mandates fair value assessments that reshape product design and disclosure standards, while the Prudential Regulation Authority sets capital adequacy requirements specific to long-term disability liabilities. In the United States, state insurance commissioners enforce varying definitions of disability that fragment product standardization across jurisdictions. Australia's APRA imposes reporting standards that influence reserve calculations for to-retirement benefit periods. Stakeholders must monitor regulatory divergence between jurisdictions that either facilitate or constrain cross-border product portability.
Market Dynamics
Digital underwriting engines are compressing policy issuance timelines from weeks to hours, forcing traditional insurers to rebuild core infrastructure around real-time data ingestion and automated risk scoring.
Growth Catalysts
- Platform Economy Expansion:Gig workers in the United Kingdom, United States, and Australia now purchase individual policies after losing employer-sponsored coverage, creating direct-to-consumer demand channels previously dormant.
- Consumer Duty Mandates:The UK's Financial Conduct Authority now requires insurers to demonstrate fair value, which accelerates product simplification and price transparency across advisory and non-advisory distribution.
- API-Enabled Distribution:Embedded insurance integrations within payroll and accounting software allow policy activation at income source, capturing buyers during employment transitions.
Market Restraints
- Long-Term Disability Reserve Volatility:The Prudential Regulation Authority's capital adequacy requirements for to-retirement liabilities force UK insurers to hold elevated reserves, compressing return on equity.
- Medical Data Fragmentation:Electronic health record interoperability gaps between NHS systems and private providers delay claims verification, extending loss adjustment expense ratios.
- Moral Hazard in Remote Assessment:Telemedicine-based disability verification lacks physical examination rigor, elevating fraud detection costs and claims leakage.
Strategic Opportunities
- Self-Employed Penetration in Germany:Europe's largest freelance workforce maintains minimal income protection coverage, presenting white space for modular products with premium holiday features.
- Retirement Bridge Products:Hybrid policies combining income protection with pension drawdown phases address longevity risk convergence, appealing to pre-retirement cohorts in Japan and the United Kingdom.
- Open Banking Underwriting:Real-time income verification through PSD2-compliant data feeds enables dynamic pricing and eliminates manual financial disclosure.
Industry Challenges
- Actuarial Talent Scarcity:Demand for professionals skilled in behavioral predictive modeling exceeds supply, delaying model deployment for new risk pools.
- Legacy System Integration:Core policy administration platforms from the 1990s resist API connectivity, forcing parallel IT architectures that fragment customer data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Income Protection Insurance Market |
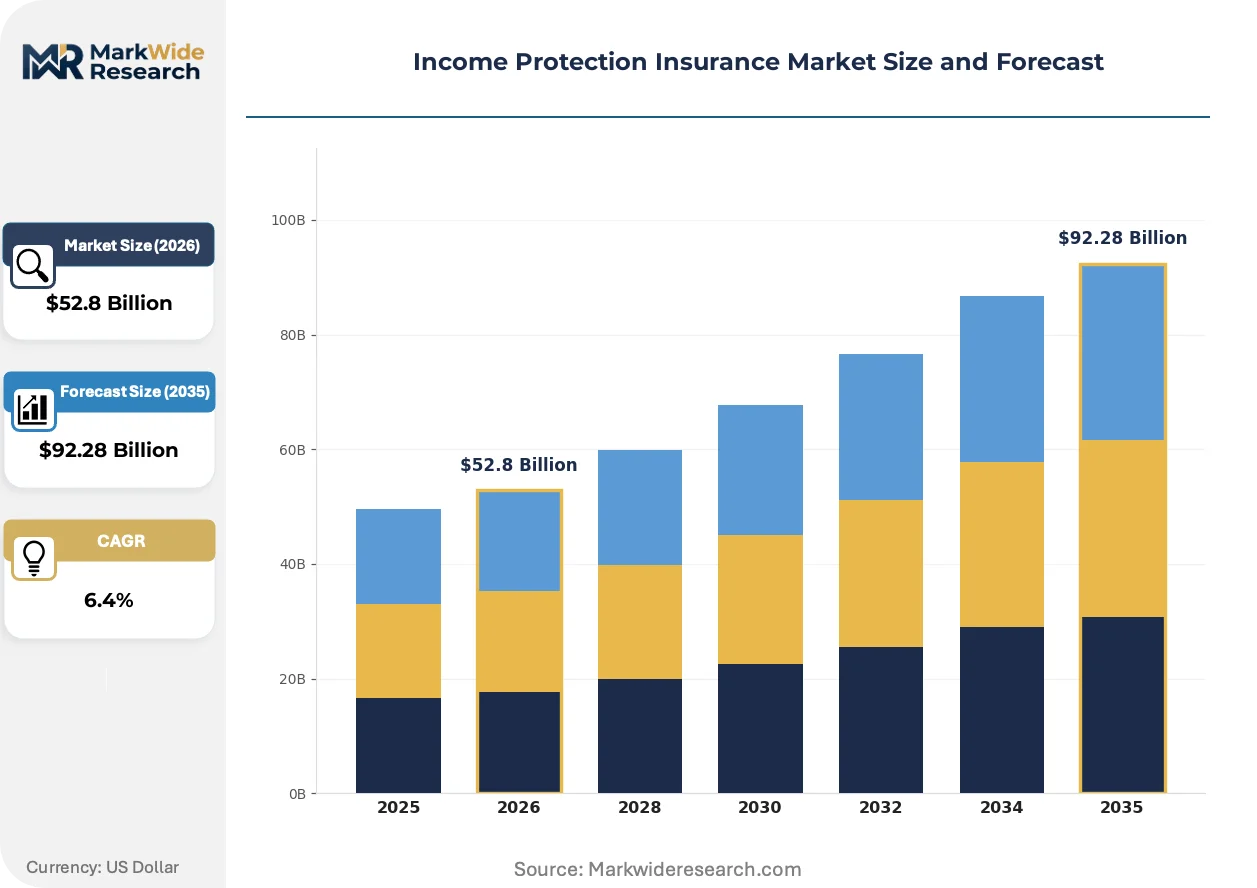
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Short-Term Coverage, Long-Term Coverage, Flexible Plans, Group Policies Distribution Channel: Direct Sales, Brokers & Agents, Online Platforms, Bancassurance Benefit Period: 1 Year, 2 Years, 5 Years, To Retirement Customer Type: Salaried Employees, Self-Employed Professionals, Freelancers, Entrepreneurs |
| Companies Covered | Prudential, Aviva, Legal & General, AIA Group, MetLife, Allianz, Zurich Insurance Group, AXA, Sun Life Financial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Income Protection Insurance Market Trends and Innovations
Artificial intelligence is rewriting the economics of disability assessment, compressing the boundary between underwriting precision and operational cost. Three developments are restructuring competitive capability.
Machine learning models trained on occupational health datasets now predict disability probability from employment metadata rather than medical examinations. Insurers in the United Kingdom and Australia deploy these tools for instant quote generation. Predictive analytics is converging with wearable health monitoring to create continuous risk adjustment mechanisms that modify premiums based on real-time biometric trends.
The Financial Conduct Authority's Consumer Duty framework mandates product governance committees that review value metrics quarterly. Insurers must now document how each product segment serves its target market's needs. UK direct-to-consumer channels face the steepest compliance burden, with firms restructuring commission disclosures and cooling-off periods to satisfy conduct regulators.
Self-employed professionals now research coverage through comparison platforms that aggregate policy features without intermediary involvement. This channel shift bypasses traditional financial advisers who previously dominated income protection distribution. The behavioral change is most pronounced among technology consultants and creative freelancers in London, Berlin, and Sydney, who prioritize digital purchase completion over advisory relationships.
Income Protection Insurance Market Segmentation
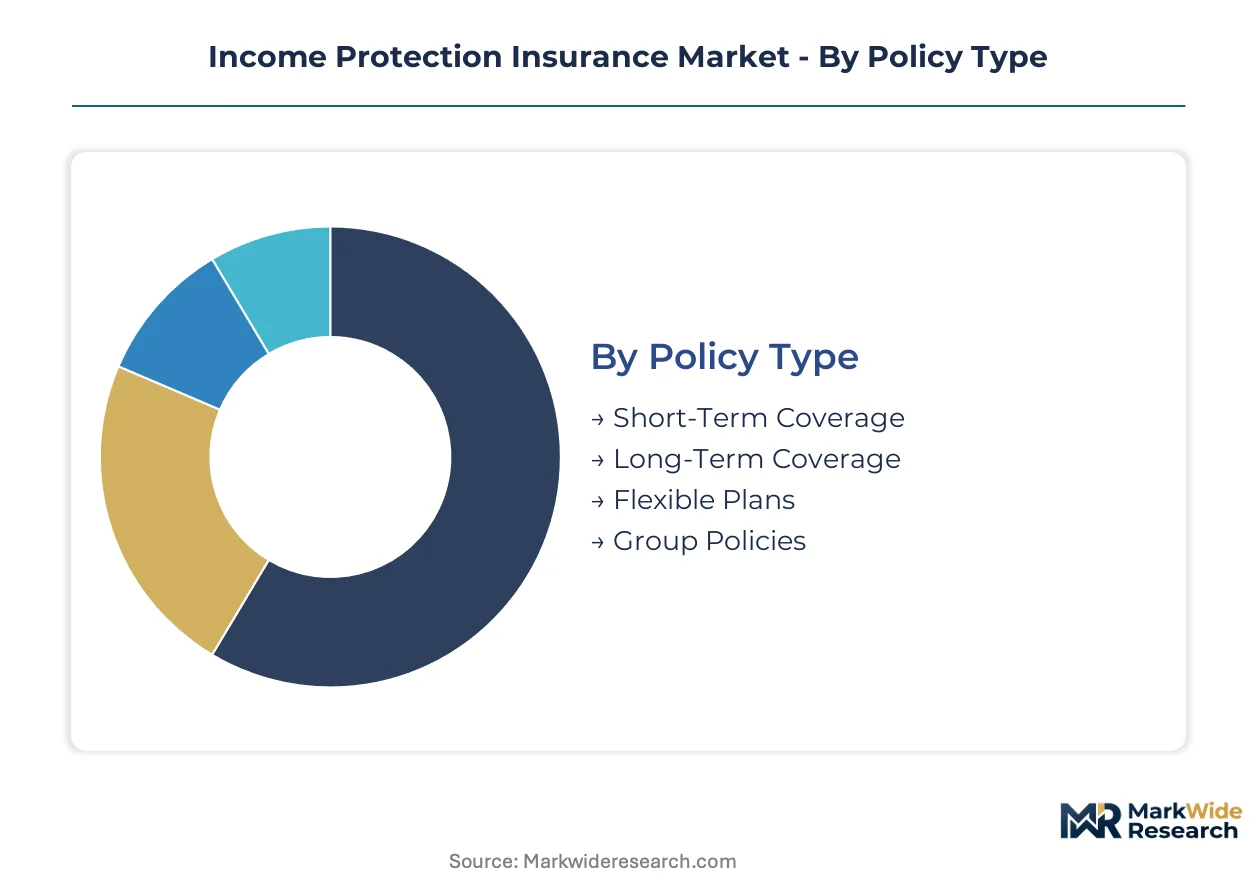
Policyholders select income protection coverage based on employment stability, risk tolerance, and benefit duration needs. Segmentation reveals how insurers must tailor pricing structures and underwriting protocols to divergent income patterns across workforce categories.
Policy Type:
Replacement cycles accelerate as gig workers abandon employer-sponsored group coverage for portable individual policies, compressing product lifecycles and forcing modular redesign.
- Short-Term Coverage:Policies typically span 6-24 months with deferred periods of 1-4 weeks. Demand concentrates among salaried employees in the United Kingdom seeking bridge protection during probationary employment periods; lower premiums sustain volume leadership despite limited benefit duration.
- Flexible Plans:Adjustable benefit periods and premium holiday features accommodate irregular income streams. Self-employed professionals in Australia and the United Kingdom gravitate toward these structures; API-enabled payroll integration now drives distribution efficiency for this segment.
- Long-Term Coverage:Extends benefits to retirement age with rigorous medical underwriting.
- Group Policies:Employer-sponsored coverage pools risk across employee cohorts with simplified enrollment.
Volume placements concentrate in Short-Term Coverage; the faster expansion belongs to Flexible Plans.
Distribution Channel:
Commission structures and regulatory disclosure requirements vary sharply across channels, reshaping insurer profitability profiles and compliance burdens.
- Online Platforms:Comparison engines and direct purchase portals eliminate intermediary friction. Technology consultants and creative freelancers in London, Berlin, and Sydney complete transactions without advisory relationships; the UK's Financial Conduct Authority Consumer Duty mandates intensify platform disclosure obligations.
- Brokers & Agents:Intermediary networks provide personalized needs assessment and claims advocacy. Complex occupational classifications and pre-existing condition negotiations sustain intermediary relevance; commission compression under fair value assessments erodes traditional economics.
- Direct Sales:Insurer-owned channels capture margin through proprietary customer relationships.
- Bancassurance:Banking partnerships embed coverage within mortgage and lending products.
Revenue generation still favors Brokers & Agents; Online Platforms are climbing the fastest.
Benefit Period:
Actuarial reserve requirements escalate with benefit duration, fragmenting capital intensity and pricing methodologies across insurers.
- To Retirement:Coverage extends until statutory pension age with escalating reserve obligations. The Prudential Regulation Authority mandates elevated capital adequacy for UK carriers writing these liabilities; long-duration risk pools attract reinsurance participation.
- 5 Years:Mid-duration policies balance premium affordability with meaningful protection windows. Pre-retirement cohorts in Japan and the United Kingdom favor this structure; hybrid pension-bridge products now incorporate drawdown phase integration.
- 2 Years:Standard employer-sponsored coverage duration with group underwriting concessions.
- 1 Year:Minimal protection for temporary income disruption with lowest entry premiums.
Capital deployment concentrates in To Retirement; 5 Year policies are gaining share fastest.
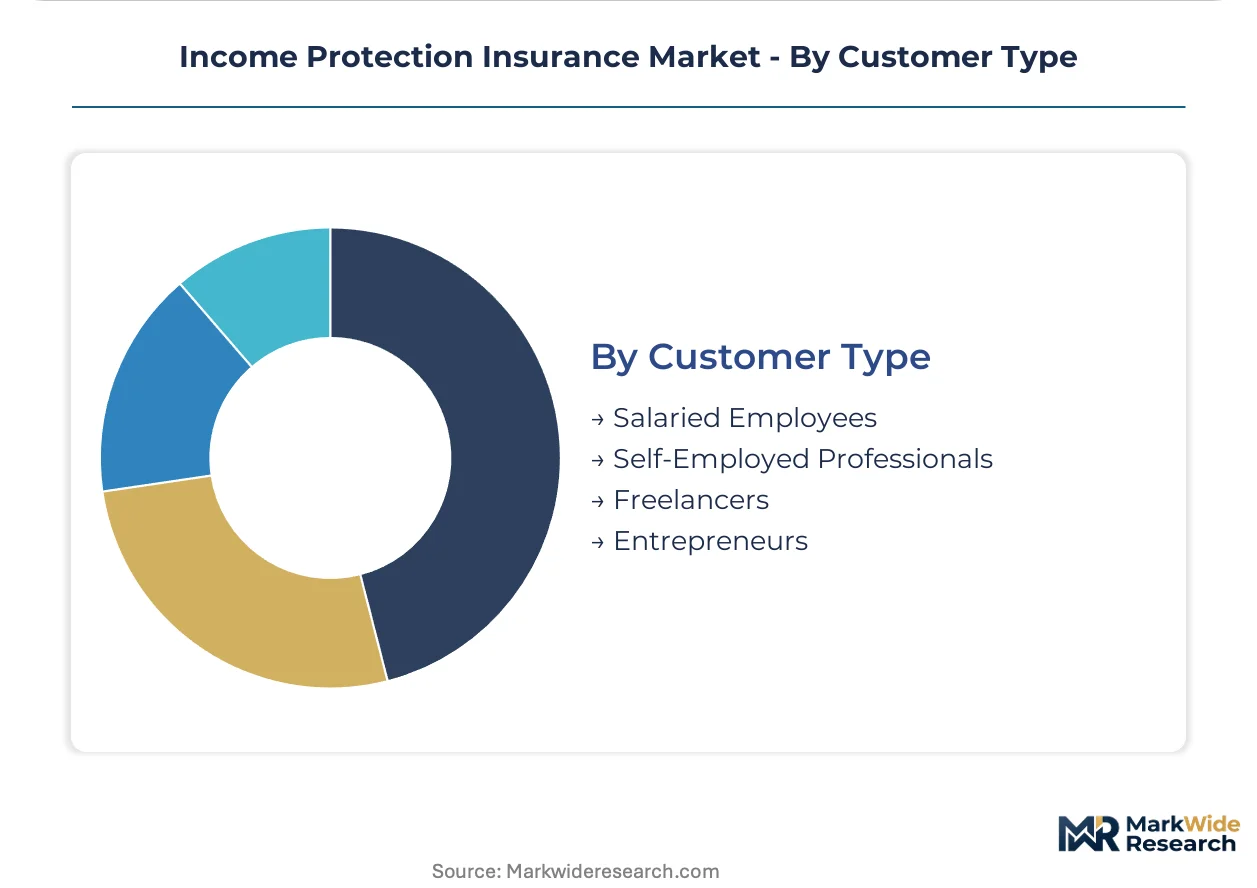
Customer Type:
Employment structure determines coverage portability, underwriting data availability, and claims incidence patterns.
- Self-Employed Professionals:Independent contractors without employer safety nets purchase individual policies with occupation-specific definitions. Germany's freelance workforce presents white space penetration opportunity; open banking income verification through PSD2-compliant feeds now enables dynamic pricing.
- Freelancers:Platform economy participants cycle between projects without benefit continuity. United States and Australian gig workers activate coverage during employment transitions; embedded insurance integrations within accounting software capture buyers at income source.
- Salaried Employees:Traditional workforce with group coverage access and stable income documentation.
- Entrepreneurs:Business owners with variable compensation and equity-linked wealth.
Policy count concentrates in Salaried Employees; Freelancers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insurance-linked special economic zones in Bermuda and Luxembourg concentrate reinsurance capital backing income protection liabilities across multiple jurisdictions. Regulatory arbitrage between these domiciles shapes product pricing and capital efficiency for carriers writing long-duration disability risk.
United Kingdom
Platform economy workers in London and Manchester drive individual policy uptake after losing employer-sponsored coverage. The Financial Conduct Authority's Consumer Duty mandates quarterly fair value assessments that compress intermediary commissions and accelerate direct-to-consumer channel migration. Edinburgh's insurance cluster hosts actuarial talent pools developing predictive models for gig worker risk pools.
United States
State-level regulatory fragmentation creates underwriting complexity as commissioners enforce varying disability definitions across jurisdictions. HIPAA privacy provisions constrain medical data sharing between electronic health record systems and private insurers, extending claims verification timelines. Hartford's historic insurance corridor maintains concentration of group benefits administrators serving hybrid workforces.
Australia
Self-employed professionals in Sydney and Melbourne gravitate toward flexible benefit structures accommodating irregular income streams. APRA's reporting standards for to-retirement reserve calculations influence product design and pricing precision across the sector. Melbourne's fintech cluster incubates API-enabled distribution platforms embedding coverage within accounting software.
Germany
Europe's largest freelance workforce in Berlin and Hamburg maintains minimal income protection penetration, presenting white space for modular products with premium holiday features. BaFin's capital adequacy frameworks for long-term disability reserves align with Solvency II requirements. Munich's insurance hub anchors reinsurance relationships backing German carrier liabilities.
Japan
Pre-retirement cohorts in Tokyo and Osaka seek hybrid policies combining income protection with pension drawdown phases addressing longevity risk convergence. METI's financial services policy coordination shapes product innovation timelines for retirement bridge structures. Tokyo's insurance district hosts regional headquarters of global carriers tailoring products to aging workforce demographics.
Income Protection Insurance Market Competitive Landscape
Top-tier vendors anchor the direct-to-consumer and group benefits segments, while mid-tier specialists concentrate on niche occupational categories and regional distribution partnerships. The market structure consolidates around carriers with proprietary underwriting engines and established reinsurance relationships. Strategic archetypes include legacy insurers rebuilding core infrastructure around real-time data ingestion, and digital-native entrants leveraging API-enabled embedded distribution. Competitive moves center on M&A activity targeting actuarial talent and technology assets, alongside strategic partnerships with payroll and accounting software platforms.
Among UK-based carriers, Prudential, Aviva, and Legal & General occupy distinct positioning archetypes within the competitive matrix. Prudential represents the hybrid workforce infrastructure play, leveraging group benefits platforms across multiple geographies. Aviva exemplifies the direct-to-consumer bypass strategy, capturing margin through proprietary channels that circumvent intermediary economics. Legal & General anchors the long-duration specialist tier, differentiating through defined-benefit pension scheme integration. These three carriers collectively illustrate how product architecture, distribution configuration, and capital structure choices segment competitive space in income protection markets.
| Leading Market Players |
|---|
| Prudential |
| Aviva |
| Legal & General |
| AIA Group |
| MetLife |
| Allianz |
| Zurich Insurance Group |
| AXA |
| Sun Life Financial |
| Others |
Pricing and Supply Chain Analysis
Automated underwriting engine deployment across UK, Australian, and German carriers compresses policy issuance timelines from weeks to hours, simultaneously collapsing distribution costs and concentrating technology procurement among specialized insurtech vendors. This infrastructure transition reshapes both premium pricing flexibility and supply chain dependencies for disability risk transfer products.
Pricing Analysis
Short lead-time policy activation commands premium pricing in the direct-to-consumer channel, while deferred-period inventory discounts attract price-sensitive employer-sponsored group purchasers. Three-tier pricing structure across premium, standard, and economy levels segments by underwriting rigor and benefit duration. Pricing pressure stems from commission compression under the UK's Financial Conduct Authority Consumer Duty mandates. Salaried employees in group coverage show lowest price sensitivity; self-employed freelancers purchasing via online platforms exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements now govern reinsurance relationships for UK and Australian carriers writing to-retirement liabilities, with cedents mandating parallel capacity from both Bermuda and Luxembourg domiciles. Claims adjudication technology draws from specialized vendors concentrated in London, Sydney, and Singapore. Medical data verification rests on NHS and private provider interoperability investments. Single-source vulnerability concentrates in legacy core policy administration platforms from the 1990s. Distribution runs through embedded payroll and accounting software integrations capturing gig workers at income source.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning disability prediction models are displacing traditional medical examination protocols, compressing the boundary between underwriting precision and operational cost economics in income protection markets.
For Market Incumbents: Deepen proprietary data asset accumulation around occupational health datasets and behavioral predictive modeling to defend against digital-native entrants. Invest in API-enabled distribution infrastructure to maintain channel control as embedded insurance integrations capture gig worker transitions. Legacy system modernization represents the critical lever for cost competitiveness.
For New Entrants and Emerging Players: Payroll software vendors and accounting platform providers offer the most penetrable partnership channel for embedded policy activation at income source. Germany's freelance workforce presents white space with minimal incumbent penetration. Target modular products with premium holiday features and open banking income verification through PSD2-compliant feeds.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by legacy carriers seeking actuarial talent and technology assets. Long-term viability hinges on underwriting engine sophistication and reinsurance relationship depth across the projection horizon. Watch for inflection in APRA and Prudential Regulation Authority capital adequacy rule changes affecting reserve requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Underwriting Engine Modernization | Machine learning deployment by UK and Australian carriers compresses policy issuance from weeks to hours. |
| Embedded Distribution Partnership | API integrations with payroll and accounting software capture gig workers during employment transitions. |
| Actuarial Talent Acquisition | Specialists in behavioral predictive modeling command premium as demand exceeds supply across the sector. |
| Regulatory Compliance Investment | Consumer Duty fair value assessments by the Financial Conduct Authority reshape commission disclosures. |
| Modular Product Development | Premium holiday features and adjustable benefit periods address irregular income streams in freelance segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with actuarial directors, underwriting technology leads, claims operations managers, and distribution channel heads with secondary validation. Primary sources included Insurance Europe market statistics, UK Financial Conduct Authority and Prudential Regulation Authority disclosure requirements, APRA reporting standards, and carrier statutory filings. Bottom-up policy volume estimates triangulated against top-down premium projections across the analysis window.
Granularity-level modeling segmented by policy type, distribution channel, benefit period, and customer employment structure, with regional regulatory clusters treated as distinct forecast dimensions. CAGRs derived from trend extrapolation calibrated against historical penetration rates and gig economy participation trajectories. Forecast inputs incorporated platform economy workforce expansion, open banking adoption curves, and embedded insurance integration velocity.
Caveats apply where regulatory divergence between the UK Financial Conduct Authority, US state insurance commissioners, and Australia's APRA could materially shift product portability and capital requirements. Deviation in gig economy participation rates or telemedicine fraud detection costs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Insurance Brokerage Market
Insurance
Peru Insurance Market
Insurance
Auto Compulsory Insurance Market
Insurance
Marine Crew Insurance Market
Insurance
Directors and Officers (Dando) Insurance Market
Insurance
UK Commercial Insurance Market
Insurance
Marine Freight Insurance Market
Insurance
Digital Insurance Market
Insurance
IoT Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
General Insurance Market
Insurance
Europe Liability Insurance Market
Insurance
Cyber Liability Insurance Market
Insurance
Germany Travel Insurance Market
Insurance
Canada House Insurance Market
Insurance
Financial Guarantee Market