
 China Online Insurance Market | 2026-2036
China Online Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
China Online Insurance Market Analysis
Young professional demand for digital health coverage is restructuring China's online insurance landscape. Ping An Insurance leverages its healthcare ecosystem to anchor comprehensive policy bundles. ZhongAn Online P&C Insurance specializes in bite-sized, app-native products that dominate travel and lifestyle segments.
China online insurance denotes digitally distributed risk-transfer contracts underwritten, sold, and serviced through internet platforms with embedded biometric verification and real-time claims adjudication. Its primary purpose is to reduce distribution friction while expanding penetration among mobile-first populations previously underserved by agent-dependent channels. Health insurance leads product type revenue pools due to rising out-of-pocket medical exposure, while mobile apps capture the fastest-growing distribution channel share as super-app ecosystems deepen engagement. Term life policies within the policy type dimension remain margin-dilute but volume-heavy, whereas critical illness riders concentrate profitability.
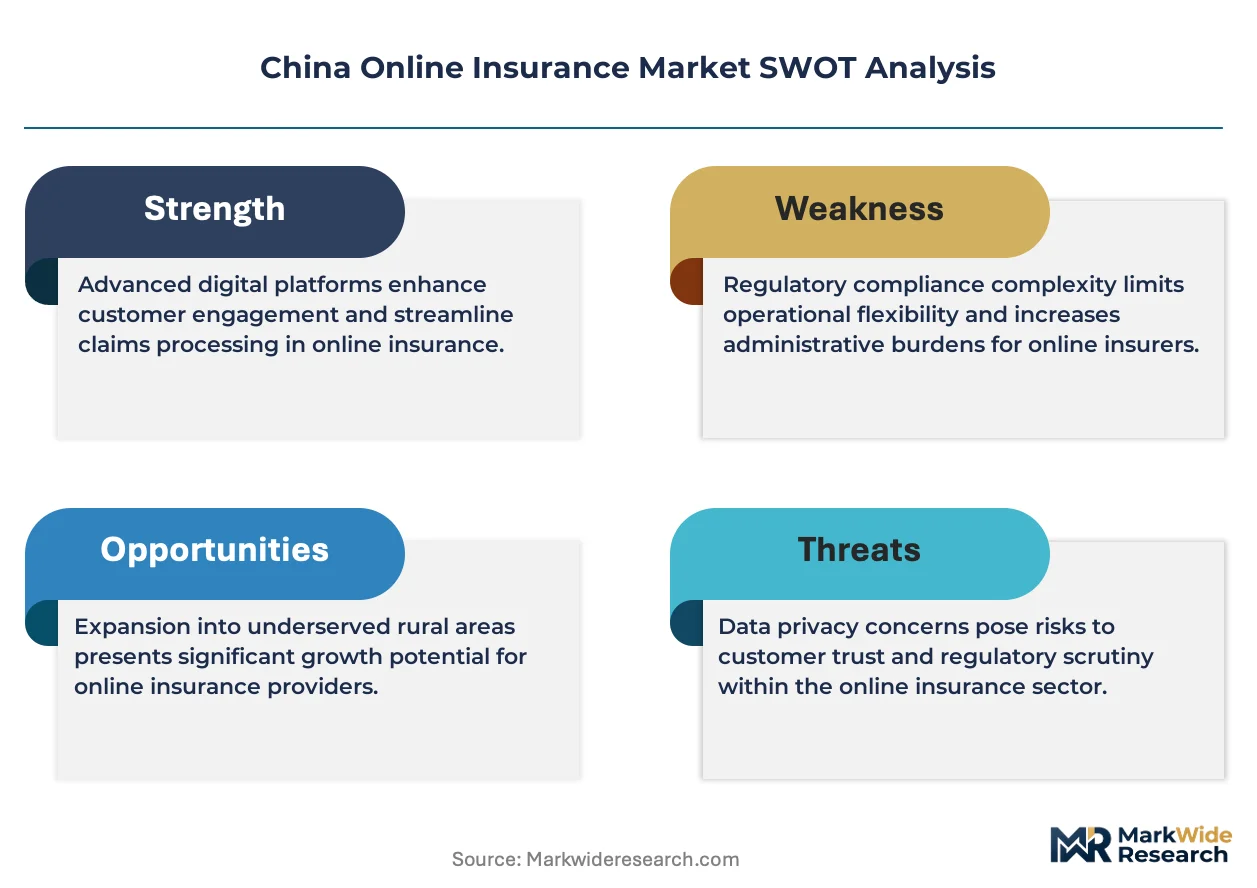
NMPA data handling standards and MIIT fintech licensing frameworks shape platform architecture, mandating localized data storage and segregated capital reserves that elevate compliance costs for new entrants. CBIRC solvency requirements further constrain product innovation velocity by linking digital expansion to capital adequacy ratios. Stakeholders must monitor regulatory calibration between consumer protection mandates and innovation enablement as enforcement intensity fluctuates across provincial pilot zones.
Market Dynamics
MIIT fintech licensing and NMPA data governance rules are compressing platform architecture choices while concentrating market power among capital-rich incumbents capable of absorbing compliance overhead. This regulatory calibration is restructuring competitive entry economics across China's digital insurance landscape.
Growth Catalysts
- Super-app distribution density:WeChat and Alipay ecosystems embed insurance purchasing into daily payment workflows, collapsing customer acquisition costs for health and travel products.
- NMPA biometric verification mandates:Real-time facial recognition for policy issuance eliminates fraud vectors while accelerating remote underwriting velocity.
- Tier-one city health cost exposure:Rising out-of-pocket medical expenditure among young professionals in Beijing, Shanghai, Shenzhen, and Guangzhou drives demand for digital critical illness coverage.
Market Restraints
- Localized data storage requirements:NMPA and MIIT mandates force domestic server infrastructure, elevating fixed costs for foreign-invested platforms.
- CBIRC solvency linkage:Digital expansion permissions tie directly to capital adequacy ratios, constraining product innovation velocity for thinly capitalized entrants.
- Agent channel stickiness:Complex whole-life and investment-linked products remain concentrated in traditional advisor networks resistant to full digitization.
Strategic Opportunities
- Lower-tier city penetration:Tier-two and tier-three urban clusters show rising smartphone insurance adoption with underdeveloped agent infrastructure.
- Critical illness rider bundling:Attachment to term life policies via mobile apps concentrates profitability while maintaining volume.
- Dual carbon goal alignment:MEE environmental disclosure requirements create demand for parametric climate risk products in corporate portfolios.
Industry Challenges
- Actuarial data science talent scarcity:Shortage of professionals capable of integrating alternative data streams with traditional mortality tables.
- Legacy core system integration:Policy administration platforms from the 2000s resist real-time API connectivity with mobile front-ends.
- Provincial enforcement variance:Pilot zone regulatory intensity fluctuates between Shanghai's Lingang and Hainan's free trade port, complicating national rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Online Insurance Market |
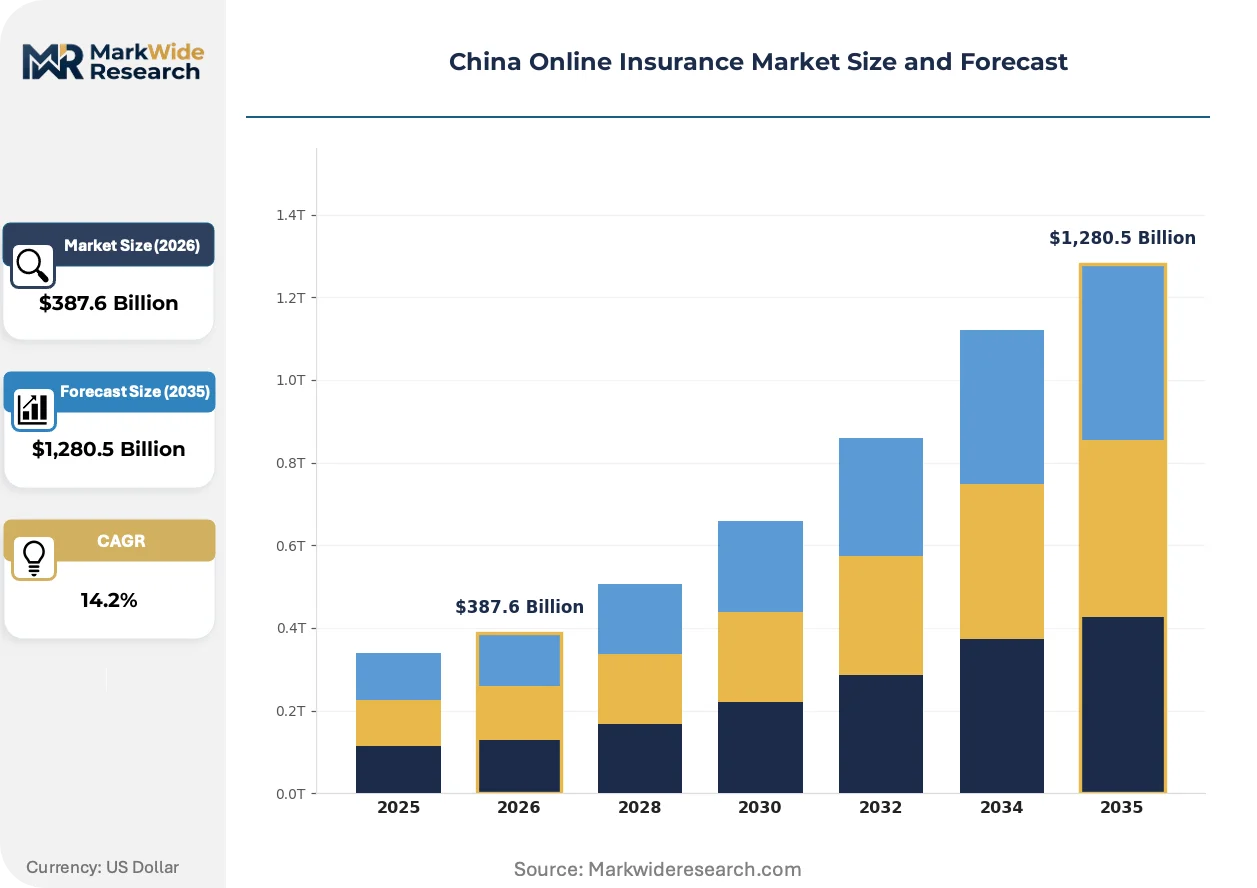
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,280.5 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, Auto Insurance, Property Insurance Customer Type: Individual, Family, Small Business, Large Enterprise Distribution Channel: Direct Online Sales, Insurance Aggregators, Mobile Apps, Brokers Policy Type: Term Life, Whole Life, Critical Illness, Travel Insurance |
| Companies Covered | Tencent WeSure, China Pacific Insurance, Ping An Insurance, AIA China, China Life Insurance, ZhongAn Online P&C Insurance, PICC, Allianz China General Insurance, Ant Insurance Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Online Insurance Market Emerging Trajectories
Embedded insurance distribution through lifestyle platforms is compressing the traditional multi-step purchase funnel into contextual micro-moments. This structural shift favors technology-native insurers with API-first architectures over legacy carriers adapting through partnership layers.
Blockchain-based smart contracts for automated claims adjudication are consolidating trust infrastructure in health and travel segments. Ping An and ZhongAn deploy distributed ledger verification for hospital invoice matching, reducing manual review cycles from days to minutes. This compression is eliminating intermediary-heavy settlement workflows.
NMPA's 2023 data security implementation rules and MIIT's fintech licensing framework are mandating segregated capital reserves and localized data architecture. CBIRC solvency requirements now explicitly weight digital distribution scale against capital adequacy buffers. Health insurance product development faces the tightest compliance timelines as biometric verification standards harden.
Young professionals in tier-one cities now initiate policy research through short-video platforms rather than comparison websites or agent referrals. Douyin and Xiaohongshu content creators disintermediate traditional educational touchpoints, compressing consideration phases. This behavioral pivot is most pronounced in critical illness and accident coverage categories where visual storytelling demystifies complex benefit structures.
China Online Insurance Market Segmentation
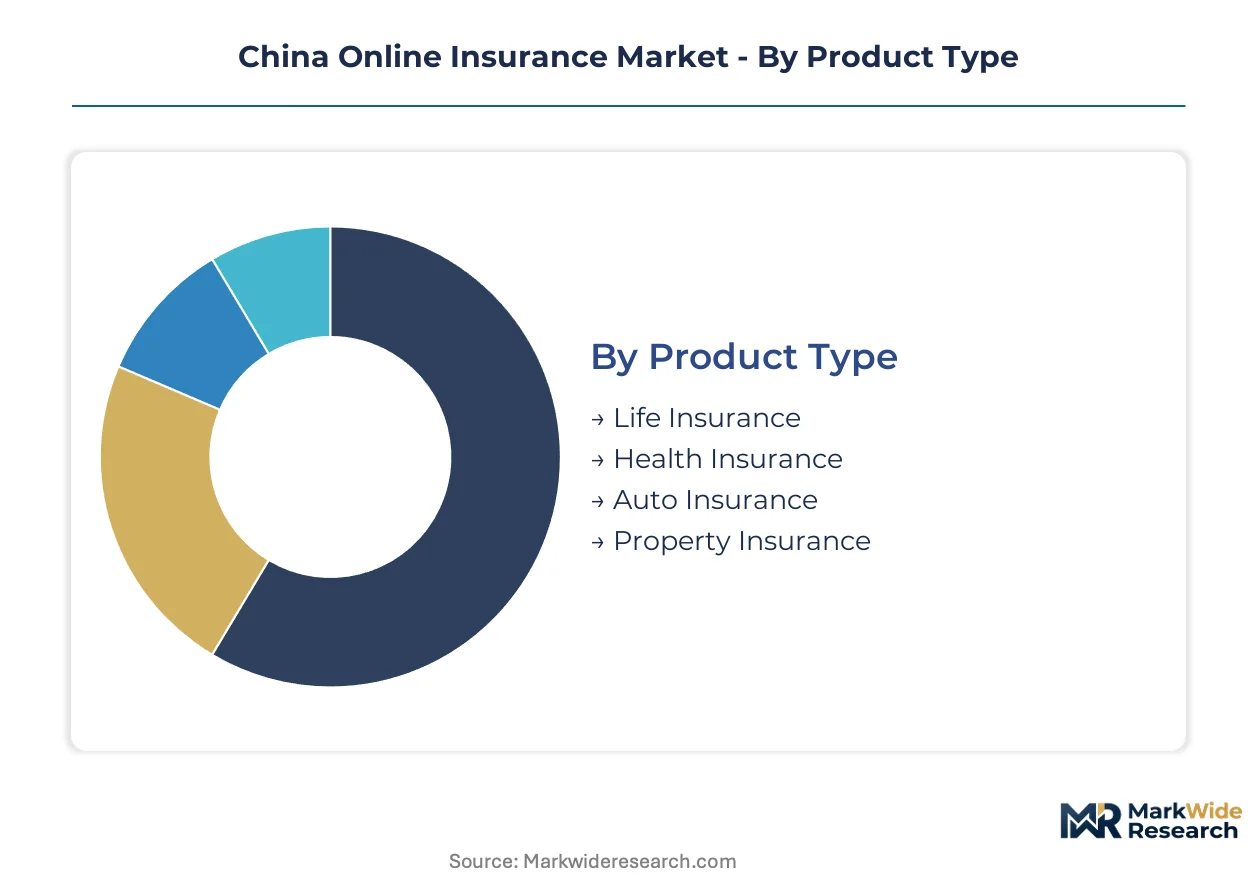
China's online insurance market fragments across product, customer, channel, and policy dimensions that each carry distinct NMPA certification burdens and MIIT data handling requirements. Understanding these segment boundaries clarifies where regulatory compliance costs concentrate and which distribution pathways unlock mobile-first penetration.
Product Type:
Health Insurance and Auto Insurance face the heaviest NMPA biometric verification mandates, while Life Insurance triggers CBIRC solvency ratio scrutiny that constrains digital expansion permissions.
- Health Insurance:Policies covering outpatient, inpatient, and critical illness medical expenses require real-time facial recognition at purchase under NMPA rules. Demand clusters among young professionals in Beijing and Shanghai facing rising out-of-pocket hospital costs, with super-app distribution compressing acquisition friction.
- Auto Insurance:Compulsory third-party liability and voluntary comprehensive coverage integrate telematics data streams for usage-based pricing. Shenzhen and Guangzhou vehicle owners drive adoption through Alipay embedded purchasing workflows, though MIIT localized data storage rules elevate platform infrastructure costs.
- Life Insurance:Term and whole-life products with digital underwriting face CBIRC capital adequacy linkage that ties distribution scale to solvency buffers.
- Property Insurance:Home and contents coverage distributed online carries lighter biometric requirements but struggles with complex claims verification.
Leading the category by volume: Health Insurance. Growing fastest: Auto Insurance.
Customer Type:
Family and Individual segments dominate mobile app acquisition economics, while Enterprise procurement runs through broker channels resistant to full digitization.
- Individual:Single-policy purchasers of accident and short-term health coverage complete transactions within WeChat mini-programs in under three minutes. Tier-one city millennials anchor this segment, with Douyin content creators displacing traditional educational touchpoints.
- Family:Multi-insured household bundles concentrate profitability for digital carriers through critical illness rider attachment. Shanghai and Beijing dual-income households drive demand for comprehensive medical coverage with dependent child inclusion.
- Small Business:Micro-enterprise liability and group health policies face higher fraud screening thresholds that slow digital underwriting velocity.
- Large Enterprise:Customized corporate risk programs remain concentrated in traditional broker networks with complex negotiation cycles.
Individual purchasers generate the highest transaction frequency. Family bundles capture the steepest expansion trajectory as household coverage consolidation accelerates.
Distribution Channel:
Mobile Apps and Insurance Aggregators concentrate the fastest-growing premium flows, while Direct Online Sales and Brokers face divergent compliance cost structures under MIIT licensing frameworks.
- Mobile Apps:WeChat and Alipay ecosystem embedding collapses customer acquisition costs through payment workflow integration. Health and travel products dominate this channel, with biometric verification completing in under thirty seconds for tier-one city users.
- Insurance Aggregators:Comparison platforms like Waterdrop and Huize aggregate multiple carrier offerings with API-driven quote generation. Young professionals initiate research here before super-app purchase completion, creating a two-step funnel.
- Direct Online Sales:Carrier-owned websites and mini-programs face higher standalone customer acquisition costs without ecosystem traffic leverage.
- Brokers:Human-advised channels retain dominance for whole-life and investment-linked products with complex benefit structures.
Mobile Apps command the largest premium share. Insurance Aggregators are climbing the fastest as comparison behavior hardens among digital-native consumers.
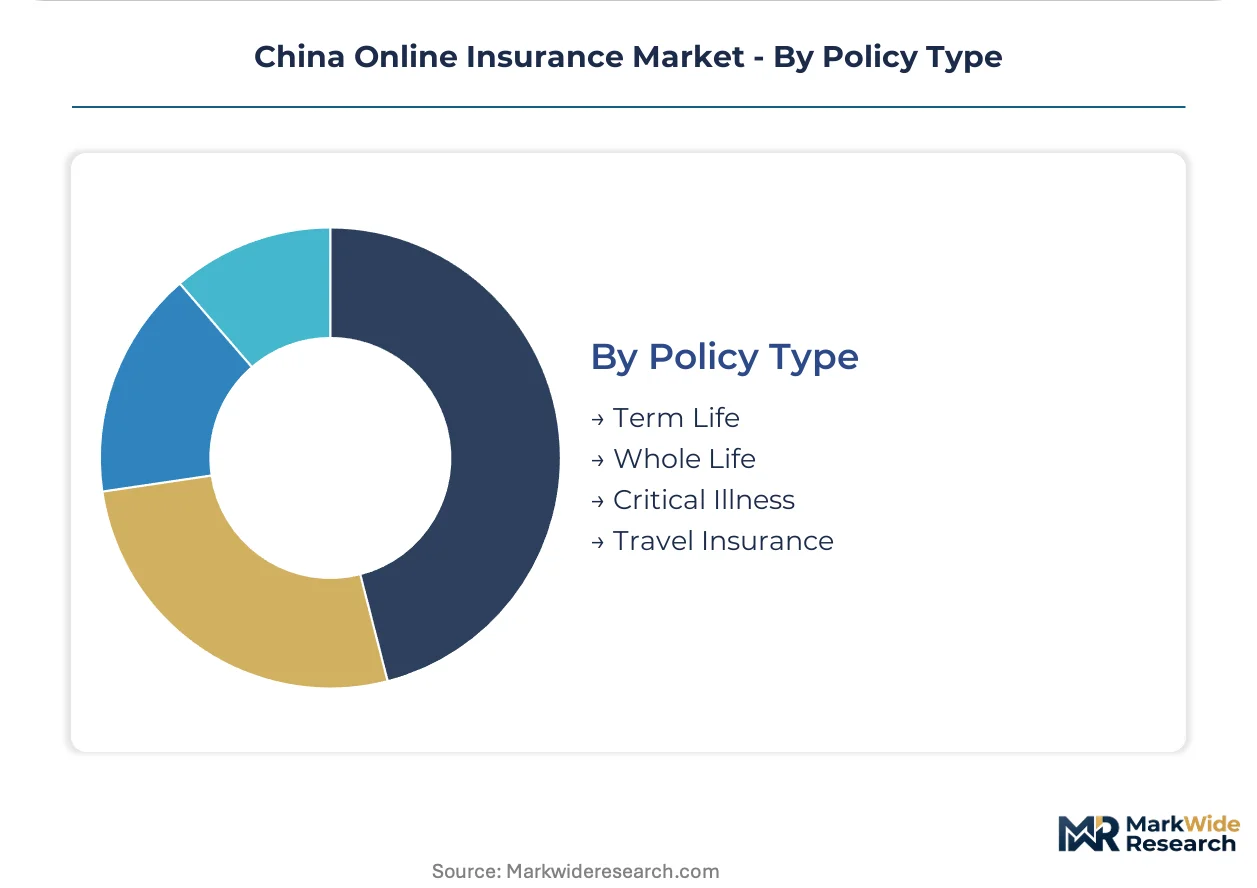
Policy Type:
Critical Illness and Term Life occupy opposite ends of the margin-volume spectrum, with divergent NMPA data handling intensities shaping platform architecture choices.
- Critical Illness:Lump-sum payout riders attached to base policies concentrate profitability through mobile app distribution. Beijing and Shanghai policyholders favor these products as out-of-pocket cancer treatment costs escalate, with blockchain-based hospital invoice verification accelerating claims.
- Term Life:Pure risk protection with fixed duration remains volume-heavy but margin-dilute, requiring CBIRC solvency backing that constrains thinly capitalized entrants.
- Whole Life:Cash value accumulation products with investment components resist full digitization due to complex disclosure requirements.
- Travel Insurance:Bite-sized trip coverage dominates ZhongAn's app-native product suite with automated claims for flight delays and medical evacuation.
Term Life leads by policy count. Critical Illness is gaining share fastest as health cost exposure deepens among tier-one city households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hainan's free trade port and Shanghai's Lingang new area concentrate regulatory pilot programs that reshape platform compliance economics across China's digital insurance landscape.
Beijing-Tianjin-Hebei
State-owned enterprise headquarters and fintech licensing density drive policy innovation concentration. MIIT's capital region enforcement sets the national template for data localization mandates. Zhongguancun technology corridor hosts incubator density for insurtech startups navigating NMPA biometric verification standards.
Yangtze River Delta
Shanghai's international financial center status attracts foreign-invested platform joint ventures seeking MIIT fintech licenses. Lingang's special policy zone experiments with cross-border data flow protocols for marine and cargo insurance products. Hangzhou's e-commerce ecosystem embeds distribution through Alipay's payment infrastructure.
Pearl River Delta
Shenzhen's hardware manufacturing base supplies telematics devices for usage-based auto insurance pricing. Guangzhou's healthcare cluster generates hospital invoice data streams feeding blockchain claims verification. WeChat's ecosystem anchors super-app distribution density for bite-sized lifestyle products.
Sichuan-Chongqing
Western China's smartphone penetration growth outpaces agent infrastructure development. Chongqing's automotive manufacturing concentration creates fleet insurance demand through connected vehicle data. Chengdu's consumption upgrade trends accelerate critical illness rider attachment rates.
China Online Insurance Market Vendor Landscape
Top-tier vendors anchor state-backed and ecosystem-integrated positions, while mid-tier specialists compete on product velocity and niche segmentation. Market structure concentrates around capital-rich incumbents capable of absorbing NMPA compliance overhead alongside technology-native challengers with API-first architectures. Two strategic archetypes dominate: healthcare ecosystem integrators leveraging hospital network data, and super-app embedded distributors collapsing acquisition costs through payment workflow integration. Competitive moves center on critical illness rider bundling and lower-tier city penetration through mobile-first distribution.
Among ecosystem-integrated carriers, Ping An Insurance and ZhongAn Online P&C Insurance exemplify divergent strategic positions. Ping An anchors comprehensive policy bundles through healthcare network vertical integration. ZhongAn occupies the bite-sized product tier with app-native travel and lifestyle coverage. Tencent WeSure represents the platform-archetype, embedding distribution through WeChat's social infrastructure without direct underwriting exposure.
| Leading Market Players |
|---|
| Tencent WeSure |
| China Pacific Insurance |
| Ping An Insurance |
| AIA China |
| China Life Insurance |
| ZhongAn Online P&C Insurance |
| PICC |
| Allianz China General Insurance |
| Ant Insurance Services |
| Others |
Supply Flow & Price Mechanics
Cloud computing infrastructure cost indices cascade through digital insurance platform economics, compressing margins for thinly capitalized entrants while rewarding ecosystem-integrated carriers with captive server capacity and pre-negotiated bandwidth contracts.
Pricing Analysis
Short lead-time deployment premiums dominate platform architecture decisions, with carriers paying 15-25% markups for immediate MIIT licensing compliance versus standard-queue processing. Subscription-tiered pricing structures stratify across premium full-stack bundles, standard API-access modules, and economy self-service tiers differentiated by NMPA biometric verification speed and claims adjudication automation depth. Pricing pressure stems from CBIRC solvency linkage requirements that force capital adequacy buffer maintenance. Individual purchasers in tier-three cities exhibit highest price sensitivity, while family bundle buyers in Beijing and Shanghai prioritize comprehensive coverage over premium minimization.
Supply Chain Analysis
Dual-sourcing requirements for biometric verification APIs mandate that platforms qualify both domestic facial recognition providers and backup cloud infrastructure partners under NMPA data localization rules. Supply concentration centers on China for core policy administration systems, with secondary qualification of Singapore and Hong Kong data centers for disaster recovery. Raw material dependencies include semiconductor chips for telematics devices, lithium batteries for portable health monitoring hardware, and specialized optical sensors for remote underwriting. Single-source vulnerability concentrates in MIIT-licensed cloud providers with exclusive domestic server networks. Distribution runs through super-app ecosystem APIs that embed purchasing workflows within payment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's online insurance landscape is accelerating into a vertical-integration race where healthcare ecosystem control and captive data infrastructure determine sustainable margin capture. Players are pursuing downstream hospital network integration and upstream cloud capacity ownership as defensive moats.
For Market Incumbents: Extend healthcare ecosystem lock-in through exclusive hospital data partnerships that feed proprietary risk scoring models, while consolidating MIIT-licensed cloud capacity to neutralize infrastructure cost volatility from third-party providers. ZhongAn's app-native product velocity and Ping An's hospital network verticality represent converging threats that demand accelerated critical illness rider bundling to maintain household account control.
For New Entrants and Emerging Players: Tier-two city micro-enterprise clusters present the most penetrable white-space segment, with underdeveloped agent infrastructure and rising smartphone insurance adoption creating acquisition cost advantages versus saturated tier-one battlegrounds. Target small business group health policies through WeChat mini-program distribution with simplified underwriting that bypasses complex broker negotiations. Lead with parametric climate risk products aligned to MEE environmental disclosure mandates as differentiated entry wedge.
For Investors and Strategic Acquirers: Distressed-cycle entries favor technology-native insurers with API-first architectures in Sichuan-Chongqing and Hainan free trade port zones, where regulatory pilot programs and lower compliance overhead concentrate turnaround potential. Long-term viability hinges on 5-10 year healthcare data network effects and super-app distribution permanence. Watch NMPA biometric verification standard tightening as inflection indicator that separates capital-rich compliance absorbers from thinly capitalized exits.
| Strategic Initiative | Industry Significance |
|---|---|
| Healthcare Ecosystem Integration | Ping An's hospital network verticality anchors comprehensive policy bundles through exclusive patient data access. |
| Super-App Distribution Partnership | WeChat and Alipay embedding collapses customer acquisition costs through payment workflow integration. |
| Blockchain Claims Infrastructure | Distributed ledger verification for hospital invoice matching compresses settlement cycles from days to minutes. |
| Lower-Tier City Penetration | Tier-two and tier-three clusters show rising smartphone adoption with underdeveloped agent infrastructure. |
| NMPA Compliance Certification | Biometric verification standard adherence unlocks digital distribution permissions under CBIRC solvency frameworks. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with insurance product managers, regulatory compliance officers, super-app platform engineers, and hospital procurement directors with validation against CBIRC solvency disclosures, MIIT fintech licensing databases, and NMPA implementation guidelines. Bottom-up policy transaction modeling and top-down premium flow estimation triangulated market sizing across the projection horizon.
Data-stream reconciliation across mobile app distribution metrics, biometric verification transaction volumes, and hospital invoice claims frequencies informed the analytical framework. Segmentation dimensions modeled include product type, customer archetype, distribution channel, and policy structure complexity alongside regional regulatory cluster variations. CAGRs derived from fitted growth curves calibrated to historical penetration rates and smartphone insurance adoption elasticity. Critical illness rider attachment rates and super-app user engagement depth served as industry-specific forecast inputs.
Revisions become necessary when NMPA biometric verification mandates intensify beyond current implementation timelines or when MIIT fintech licensing freezes disrupt platform expansion permissions. Forecasts reflect assumptions regarding CBIRC solvency ratio stability and super-app ecosystem durability. Deviation in provincial enforcement intensity between Shanghai Lingang and Hainan pilot zones would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
Peer to Peer Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Crop Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Global Livestock Insurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
Europe EV Insurance Market
Insurance
China Group Health Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
India Parametric Insurance Market
Insurance
Europe Car Insurance Market
Insurance
General Insurance Market
Insurance
Canada House Insurance Market
Insurance
Online Insurance Market