
 Middle East and Africa Vibration Sensors Market | 2026-2036
Middle East and Africa Vibration Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Vibration Sensors Market Foresight
CE marking requirements under the EU Machinery Directive is restructuring market access for vibration sensor suppliers exporting into North African manufacturing zones. SKF GmbH leverages its bearing-condition monitoring integration to dominate predictive maintenance bundling across Gulf petrochemical complexes. Emerson Electric Corporation anchors its position through wireless sensor networks tailored for remote oilfield infrastructure. Texas Instruments Inc. competes on MEMS chip-scale manufacturing, driving cost compression for high-volume displacement sensor deployments.
Vibration sensors are electromechanical transducers that convert mechanical oscillation into proportional electrical signals, typically operating across frequency ranges from 0.1 Hz to 30 kHz with sensitivity tolerances of ±5% for industrial-grade units; their primary purpose is to enable real-time machinery health assessment and prevent catastrophic equipment failure. Accelerometers lead product type revenue due to universal compatibility with rotating equipment diagnostics across energy and manufacturing end users. Wireless technology segments expand fastest as mining operators in South Africa and copper belt regions prioritize battery-powered sensor networks for hazardous, cable-inaccessible environments. Wired piezoelectric configurations retain margin concentration in aerospace and precision machinery protection applications where signal fidelity requirements exclude MEMS alternatives.
South Africa's national standards body enforces SANS 10368 alignment with ISO 10816 vibration severity charts, compelling mining houses to upgrade from periodic manual readings to continuous monitoring architectures. Saudi Arabia's SFDA and SASO technical regulations for industrial equipment safety create dual compliance layers for sensor suppliers entering food-pharma manufacturing and heavy process industries. Nigeria's Department of Petroleum Resources mandates structural integrity programs for offshore platforms, directly stimulating demand for triaxial accelerometer arrays in deepwater asset monitoring. Stakeholders must weigh the capex-opex trade-off between retrofit wired installations and greenfield wireless architectures as African utility grids stabilize and industrial electrification accelerates.
Market Dynamics
Wireless sensor networks are displacing wired piezoelectric architectures across Gulf petrochemical corridors, as operators prioritize battery-powered deployments in cable-inaccessible zones and hazardous classification areas.
Growth Catalysts
- Saudi Vision 2030 industrial mandates:Smart manufacturing investments across petrochemical and renewable energy facilities are mandating continuous condition monitoring infrastructure.
- ISO 10816 machinery vibration standards:South Africa's national standards body enforces SANS 10368 alignment, compelling mining houses to upgrade from periodic manual readings to continuous monitoring architectures.
- Triaxial accelerometer arrays:Nigeria's Department of Petroleum Resources mandates structural integrity programs for offshore platforms, directly stimulating demand for deepwater asset monitoring systems.
Market Restraints
- MEMS chip-scale manufacturing concentration:Texas Instruments and select Asian foundries dominate high-volume displacement sensor production, creating supply vulnerability for cost-sensitive African utility deployments.
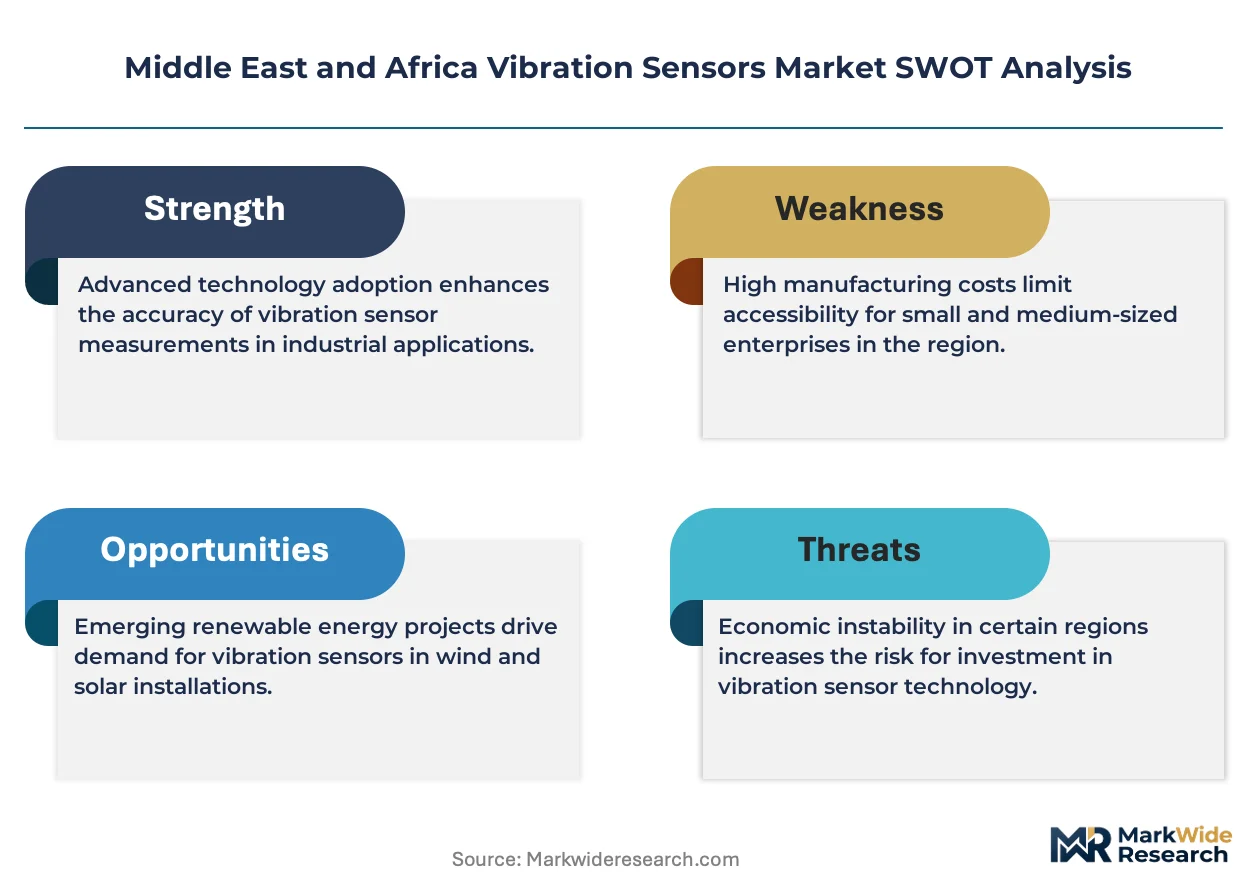
- Dual compliance layers:Saudi Arabia's SFDA and SASO technical regulations for industrial equipment safety impose certification friction for sensor suppliers entering food-pharma manufacturing alongside heavy process industries.
- Signal fidelity limitations:Wired piezoelectric configurations retain irreplaceable margin concentration in aerospace and precision machinery protection applications where MEMS alternatives fail to meet performance thresholds.
Strategic Opportunities
- Copper belt wireless expansion:Mining operators in Zambia and the Democratic Republic of Congo prioritize battery-powered sensor networks for hazardous, cable-inaccessible underground environments.
- CE marking restructuring:EU Machinery Directive requirements are repositioning market access for vibration sensor suppliers exporting into North African manufacturing zones, favoring pre-certified European vendors.
- AI-driven predictive maintenance convergence:Machine learning analytics platforms are integrating with vibration sensor data streams, creating bundled service revenue models for Gulf petrochemical operators.
Industry Challenges
- Retrofit integration complexity:Mining houses in South Africa face technical debt from legacy wired installations that resist seamless incorporation with modern wireless gateway architectures.
- Certification timeline compression:Dual SASO and SFDA approval pathways in Saudi Arabia extend product launch cycles for industrial safety equipment categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Vibration Sensors Market |
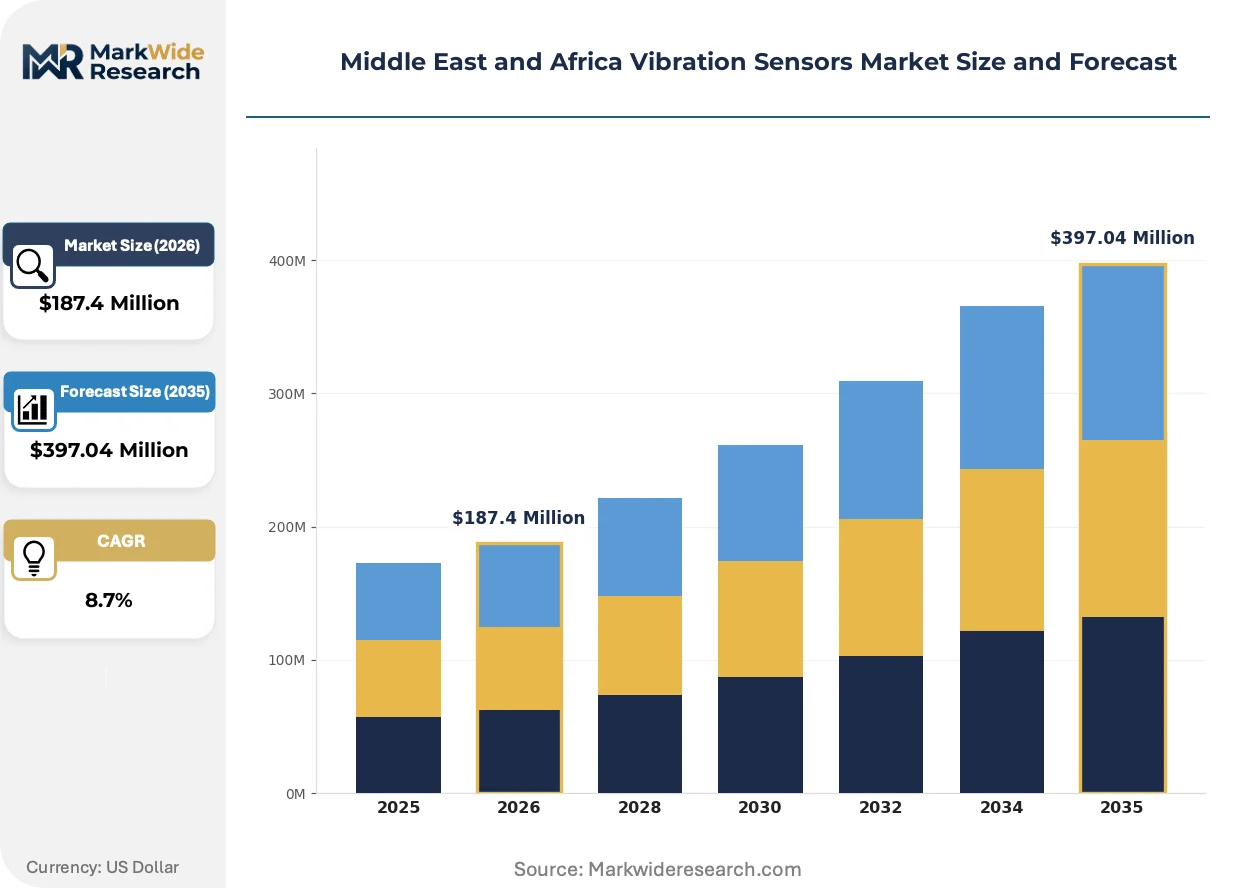
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Displacement Sensors, Velocity Sensors, Strain Gauges End User: Manufacturing, Automotive, Energy, Aerospace Technology: Wired, Wireless, Piezoelectric, MEMS Application: Predictive Maintenance, Condition Monitoring, Structural Health Monitoring, Machinery Protection |
| Companies Covered | SKF GmbH, Emerson Electric Corporation, Texas Instruments Inc., National Instruments Corporation, Honeywell International Inc., Fluke Corporation, TE Connectivity Ltd, Robert Bosch GmbH, PCB Piezotronics, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Vibration Sensors Market Shifts & Advancements
MEMS-based vibration sensing is compressing unit economics while expanding addressable applications beyond traditional industrial strongholds into renewable energy and precision agriculture.
MEMS accelerometers convert mechanical oscillation into proportional electrical signals through micro-machined silicon structures, enabling chip-scale manufacturing at fractional cost points. Mining operators across South Africa's platinum belt and copper belt regions are adopting these units for mass-deployment scenarios. This technology is electrifying demand for high-volume displacement sensor deployments in price-sensitive African utility and agricultural machinery segments.
South Africa's SANS 10368 enforcement creates binding alignment with ISO 10816 vibration severity charts across mining and power generation assets. Mining houses must now maintain continuous monitoring documentation for regulatory audit compliance. Underground platinum and gold operations represent the most affected segment, with operators retrofitting sensor networks to satisfy inspection protocols.
Procurement patterns across Gulf petrochemical complexes are consolidating around predictive maintenance bundling rather than discrete sensor transactions. SKF GmbH and Emerson Electric Corporation anchor this shift through integrated bearing-condition monitoring and wireless network offerings. Saudi Aramco and ADNOC facilities display the most visible concentration of outcome-based service contracting models.
Middle East and Africa Vibration Sensors Market Segmentation
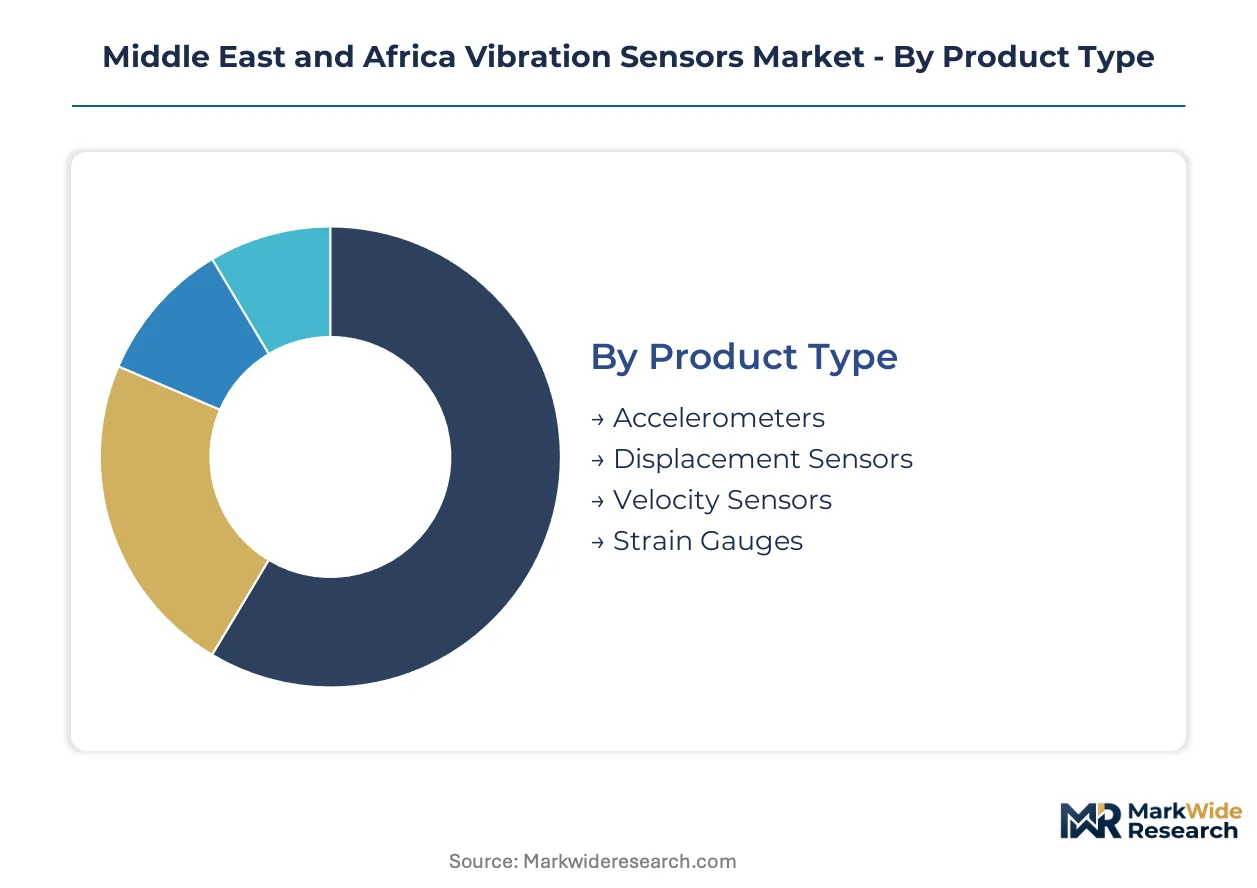
Vibration sensor procurement across the Middle East and Africa stratifies sharply by certification burden. Saudi SFDA and SASO dual-layer approvals favor established product architectures, while South African SANS 10368 enforcement drives standardization in mining procurement.
Product Type:
Accelerometers and displacement sensors carry divergent certification loads for Gulf petrochemical deployment. SASO technical regulations impose stricter documentation on piezoelectric-based units than on MEMS alternatives.
- Accelerometers:Electromechanical transducers measuring vibration amplitude across 0.1 Hz to 30 kHz frequency ranges with ±5% sensitivity tolerance. Demand concentrates in Saudi Aramco and ADNOC petrochemical complexes where Vision 2030 mandates continuous condition monitoring infrastructure for rotating equipment.
- Displacement Sensors:Eddy-current and laser-based devices quantifying relative shaft motion in turbomachinery. South African platinum belt mining houses deploy these for ISO 10816 compliance, compelled by SANS 10368 enforcement to upgrade from periodic manual readings.
- Velocity Sensors:Seismic velocity transducers optimized for low-frequency machinery monitoring in hydropower and wind turbine applications.
- Strain Gauges:Foil-resistive sensors measuring mechanical deformation for structural integrity assessment in Nigerian offshore platform programs.
Leading the category by volume: Accelerometers. Growing fastest: Displacement sensors.
End User:
Cost tier segmentation separates premium aerospace-grade deployments from high-volume mining and utility installations.
- Manufacturing:Food-pharma and heavy process industries in Saudi Arabia face dual SFDA and SASO compliance layers, extending certification timelines for sensor suppliers.
- Energy:Oil and gas operators across the Gulf prioritize wireless sensor networks for remote infrastructure, with Nigerian Department of Petroleum Resources mandates stimulating triaxial accelerometer arrays for deepwater asset monitoring.
- Automotive:Precision machinery protection applications in South African vehicle component manufacturing retain wired piezoelectric configurations where MEMS alternatives fail signal fidelity thresholds.
- Aerospace:High-margin applications demanding irreplaceable piezoelectric performance for flight-critical systems.
Revenue concentration: Energy. Margin leadership: Aerospace.
Technology:
Application environment dictates architecture selection between wired fidelity and wireless accessibility.
- Wireless:Battery-powered sensor networks expanding fastest across Zambia and Democratic Republic of Congo copper belt mining operations for hazardous, cable-inaccessible underground environments.
- MEMS:Chip-scale manufacturing at fractional cost points electrifying demand in price-sensitive African utility and agricultural machinery segments.
- Wired:Piezoelectric configurations retaining margin concentration where signal integrity requirements exclude solid-state alternatives.
- Piezoelectric:Ceramic crystal-based sensing elements delivering superior dynamic range for precision diagnostics.
Widest deployment: Wired. Steepest expansion trajectory: Wireless.
Application:
Customer procurement patterns consolidate around outcome-based service models rather than discrete hardware transactions.
- Predictive Maintenance:Integrated bearing-condition monitoring and analytics platforms creating bundled service revenue models across Gulf petrochemical operators.
- Condition Monitoring:Continuous documentation requirements under South African SANS 10368 enforcement compelling mining houses to maintain regulatory audit trails.
- Structural Health Monitoring:Nigerian offshore platform integrity programs mandating sensor arrays for deepwater asset protection.
- Machinery Protection:Emergency shutdown systems for critical rotating equipment in power generation and hydrocarbon processing.
Procurement volume leader: Condition Monitoring. Fastest service-model transition: Predictive Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical and mining operators across the Middle East and Africa concentrate vibration sensor procurement in Saudi Arabia, South Africa, Nigeria, and the UAE, with regulatory mandates and industrial diversification programs driving deployment patterns.
Saudi Arabia
Vision 2030 mandates smart manufacturing investments across petrochemical and renewable energy facilities. SFDA and SASO technical regulations impose dual compliance layers for industrial equipment safety. Jubail Industrial City and Yanbu petrochemical complexes anchor demand for continuous condition monitoring infrastructure.
South Africa
Platinum belt and gold mining operations drive accelerometer procurement for machinery health assessment. SANS 10368 enforcement aligns with ISO 10816 vibration severity charts, compelling regulatory audit documentation. Rustenburg and Johannesburg industrial corridors host the most visible retrofit sensor network installations.
Nigeria
Offshore platform structural integrity programs stimulate triaxial accelerometer array demand. The Department of Petroleum Resources mandates deepwater asset monitoring systems for hydrocarbon infrastructure. Lagos and Port Harcourt serve as procurement hubs for oilfield sensor deployment.
United Arab Emirates
ADNOC facilities and downstream petrochemical operators prioritize wireless sensor networks for remote infrastructure monitoring. MOHAP industrial safety frameworks intersect with SASO-equipment standards for manufacturing zones. Ruwais and Jebel Ali industrial clusters concentrate predictive maintenance service contracting.
Egypt
Suez Canal Economic Zone manufacturing expansion creates emerging demand for machinery protection systems. National industrial modernization programs reference European machinery directives for equipment safety compliance. Alexandria and Cairo industrial corridors represent the primary addressable sensor markets.
Middle East and Africa Vibration Sensors Market Competitive Landscape
European producers anchor the premium-tier segment through integrated condition monitoring bundling; North American specialists hold wireless and semiconductor-scale positions. Market structure consolidates around predictive maintenance service models rather than discrete hardware transactions. Three archetypes dominate: bearing-integrated system providers, wireless network platform vendors, and MEMS chip-scale manufacturers. Competitive moves concentrate on strategic partnerships for AI analytics integration and geographic licensing arrangements for hazardous-area certification.
Within the integrated-system tier, SKF GmbH and Emerson Electric Corporation exemplify the shift toward outcome-based service contracting across Gulf petrochemical corridors. Texas Instruments Inc. occupies the semiconductor-manufacturing archetype, representing cost-compression strategies for high-volume displacement sensor production. These three entities collectively illustrate the market's bifurcation between premium service bundling and component-scale manufacturing economics.
| Leading Market Players |
|---|
| SKF GmbH |
| Emerson Electric Corporation |
| Texas Instruments Inc. |
| National Instruments Corporation |
| Honeywell International Inc. |
| Fluke Corporation |
| TE Connectivity Ltd |
| Robert Bosch GmbH |
| PCB Piezotronics |
| Others |
Supply & Pricing Matrix
Sovereign-backed petrochemical operators and private-equity-consolidated sensor distributors anchor procurement patterns across Gulf industrial corridors, translating concentrated buying power into volume-tier pricing discipline while fragmenting supplier margins. Their financing structures favor long-term service contracts over discrete hardware purchases, compressing transactional pricing flexibility for component vendors serving African utility and mining segments.
Pricing Analysis
Premium pricing attaches to short-lead-time deliveries of SASO-certified piezoelectric units for Saudi food-pharma manufacturing, while spot inventory of MEMS alternatives trades at discounts in South African mining procurement. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade signal fidelity from industrial-condition monitoring and agricultural-machinery displacement sensing. Pricing pressure stems from Texas Instruments' chip-scale manufacturing scale feeding cost compression into high-volume African utility deployments. Mining houses in Zambia and the DRC copper belt exhibit highest price sensitivity, while Gulf petrochemical operators prioritize outcome-based service bundling over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese MEMS foundries and South Korean piezoelectric ceramic suppliers for precision sensing elements. Manufacturing concentration in Germany, the United States, and Japan feeds specialized accelerometer and displacement sensor production for aerospace and precision machinery protection. Raw material dependencies span rare-earth elements for magnetic sensing, synthetic quartz for piezoelectric crystals, and high-purity silicon for MEMS fabrication. Tariff exposure runs through EU Machinery Directive CE marking requirements restructuring North African manufacturing zone access. Distribution runs through authorized industrial automation distributors and direct OEM contracting for Gulf petrochemical complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless sensor networks are displacing wired piezoelectric architectures across hazardous mining and remote oilfield environments, creating a technology-transition phase where battery-powered MEMS platforms replace legacy cable-dependent installations. This substitution pattern reconfigures competitive positioning around integrated analytics bundling rather than discrete hardware transactions.
For Market Incumbents: Acquire AI-driven predictive maintenance software platforms to defend service-revenue attachment rates against emerging wireless-native entrants. SKF GmbH and Emerson Electric Corporation exemplify this consolidation trajectory through integrated bearing-condition monitoring offerings. Cement certification pre-positioning for Saudi SFDA and SASO dual-layer approvals to extend product launch cycle advantages over challengers. Backward integration into MEMS foundry partnerships reduces exposure to Taiwanese supply concentration for high-volume African utility deployments.
For New Entrants and Emerging Players: Begin with copper belt wireless expansion in Zambia and the Democratic Republic of Congo, where hazardous underground environments exclude cable installations and incumbent presence remains thin. Target South African platinum belt retrofit opportunities where SANS 10368 enforcement compels continuous monitoring upgrades from periodic manual readings. Pursue OEM white-label partnerships for agricultural machinery vibration sensing, leveraging MEMS cost compression to penetrate price-sensitive African utility segments.
For Investors and Strategic Acquirers: Distressed-cycle entries favor wireless sensor network platform specialists with hazardous-area certification libraries in Gulf petrochemical corridors. Long-term viability hinges on outcome-based service contract penetration rather than hardware shipment volumes. Monitor AI analytics integration rates across Saudi Aramco and ADNOC facilities as the inflection signal for predictive maintenance bundling maturity. Acquisition targets should demonstrate established SASO technical regulation pathways and copper belt mining operator relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Sensor Network Deployment | Battery-powered architectures penetrate cable-inaccessible copper belt mining environments in Zambia and DRC. |
| AI Analytics Platform Integration | Machine learning convergence with vibration data streams enables outcome-based service contracting across Gulf petrochemical operators. |
| Dual Certification Investment | SFDA and SASO pre-approval positioning accelerates product launch cycles for Saudi food-pharma and heavy process manufacturing entry. |
| MEMS Manufacturing Scale-Up | Chip-scale production cost compression electrifies high-volume displacement sensor demand in African utility and agricultural machinery. |
| Copper Belt Channel Partnership | Authorized distributor relationships in Zambia and DRC secure hazardous-area deployment access ahead of wireless-native competitors. |
Research Methodology
Independent corroboration across maintenance directors at Gulf petrochemical complexes, mining engineers in South Africa's platinum belt, and procurement leads at Nigerian offshore operators underwrites the qualitative findings. Primary interviews with plant engineers, OEM aftermarket service heads, and industrial automation distributors combined with secondary validation from customs and trade data, SEC filings of listed sensor manufacturers, and ISO 10816 machinery vibration standard documentation. Bottom-up and top-down triangulation cross-referenced deployment volumes against regulatory mandate timelines.
Rate-of-change decomposition separated technology substitution effects from regulatory compliance drivers and greenfield industrial investment cycles across the projection horizon. Segmentation dimensions modeled include product type, end user industry, technology architecture, and application purpose alongside regional regulatory cluster differentiation. CAGRs derived from historical deployment trajectories adjusted for mandate enforcement schedules and infrastructure electrification patterns. Industry-specific forecast inputs incorporated SANS 10368 audit documentation requirements and Nigerian Department of Petroleum Resources structural integrity program mandates.
Commodity price volatility for rare-earth sensing materials, MEMS foundry capacity allocation shifts, and Gulf petrochemical operator capex cycle timing are the dominant revision risks. Forecasts reflect documented assumptions regarding wireless battery life improvements and African utility grid stabilization trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Air Particle Monitor System Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Hall-Effect Sensors Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
Tip Location Devices Market
Sensors and Controls
Battery Free Sensor Market