
 Micropump Market | 2026-2036
Micropump Market Size, Share, and Industry Trends Forecast 2026-2036
Micropump Market Analysis
The EU Green Deal is broadening sustainability mandates across medical device supply chains, compelling manufacturers to redesign fluid handling systems for lower energy consumption and reduced material waste. IDEX Corporation leverages its diversified fluidics portfolio to serve both life science and industrial analytical applications. The Lee Company anchors its position through specialized miniature valve and pump architectures designed for aerospace and medical OEMs. Bartels Mikrotechnik GmbH competes with piezoelectric actuation expertise tailored to portable diagnostic platforms.
A micropump is a precision fluid displacement device engineered to manipulate liquid or gas volumes typically ranging from microliters to milliliters per minute, employing actuation mechanisms such as piezoelectric diaphragms, peristaltic rollers, or rotating gear elements fabricated from chemically inert polymers or stainless steel substrates. Its primary industrial purpose centers on controlled dosing, sample handling, and reagent metering in analytical instruments, implantable therapeutics, and microreactor systems. Piezoelectric micropumps command structural attention due to their silent operation, minimal heat generation, and compatibility with battery-powered wearable formats, whereas peristaltic variants retain dominance in biopharmaceutical processing where sterility and disposable flow paths protect against cross-contamination. Drug delivery applications concentrate margin pools as chronic disease management shifts toward patient-administered infusion and closed-loop hormonal regulation.
FDA quality system regulations, EU MDR conformity requirements, and ISO 13485 medical device standards collectively shape micropump validation protocols, biocompatibility testing burdens, and market access timelines for new entrants. The EPA and REACH frameworks additionally constrain material selection for sealing components and wetted surfaces in environmental monitoring and chemical processing deployments. Stakeholders must monitor evolving FDA guidance on combination products and EU IVDR diagnostic device classifications to anticipate regulatory bottlenecks affecting pump-integrated delivery systems.
Market Dynamics
Piezoelectric actuation architectures are displacing electromagnetic alternatives in battery-powered medical devices, compressing power budgets while tightening FDA validation timelines for fluid handling subsystems.
Growth Catalysts
- EU MDR Conformity Pressure:Tighter biocompatibility testing mandates for implantable drug delivery systems are forcing OEMs to source validated micropump modules rather than build in-house, expanding the addressable supplier base.
- Chronic Disease Management:Patient-administered hormonal regulation and closed-loop insulin delivery are concentrating demand in wearable formats requiring silent, heat-minimal fluid displacement.
- German Precision Engineering Clusters:Stuttgart and Munich medical device manufacturing hubs provide integrated supply chains for polymer micromachining and stainless steel substrate fabrication.
Market Restraints
- Piezoelectric Ceramic Supply Concentration:Lead zirconate titanate (PZT) feedstock dependence on Chinese rare earth processing creates input cost volatility and forced substitution risk.
- ISO 13485 Certification Burden:Quality system documentation requirements extend market access timelines by 18-24 months for new entrants lacking established medical device audit histories.
- Peristaltic Pump Dominance in Bioprocessing:Sterile disposable flow path preference in biopharmaceutical manufacturing limits addressable market for reusable diaphragm architectures.
Strategic Opportunities
- Point-of-Care Diagnostic Expansion:Portable PCR and immunoassay platforms in India and Brazil present underpenetrated demand for low-cost piezoelectric metering modules.
- EU Green Deal Material Mandates:Sustainability-driven redesign of sealing components creates first-mover advantage for bio-based elastomer suppliers meeting REACH-compliant wetted surface requirements.
- Microreactor Process Intensification:Flow chemistry adoption in pharmaceutical manufacturing converges micropump precision with continuous manufacturing regulatory pathways.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Fluid-structure-electrothermal coupling expertise for piezoelectric diaphragm optimization concentrates in specialized academic programs and incumbent engineering teams.
- Legacy Analytical Instrument Integration:Retrofitting established HPLC and mass spectrometry platforms with miniaturized fluid handling requires custom manifold redesign and extended validation cycles.
- IP Licensing Complexity:Patent thickets covering piezoelectric drive circuits and valve sealing geometries force cross-licensing negotiations or design-around engineering investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micropump Market |
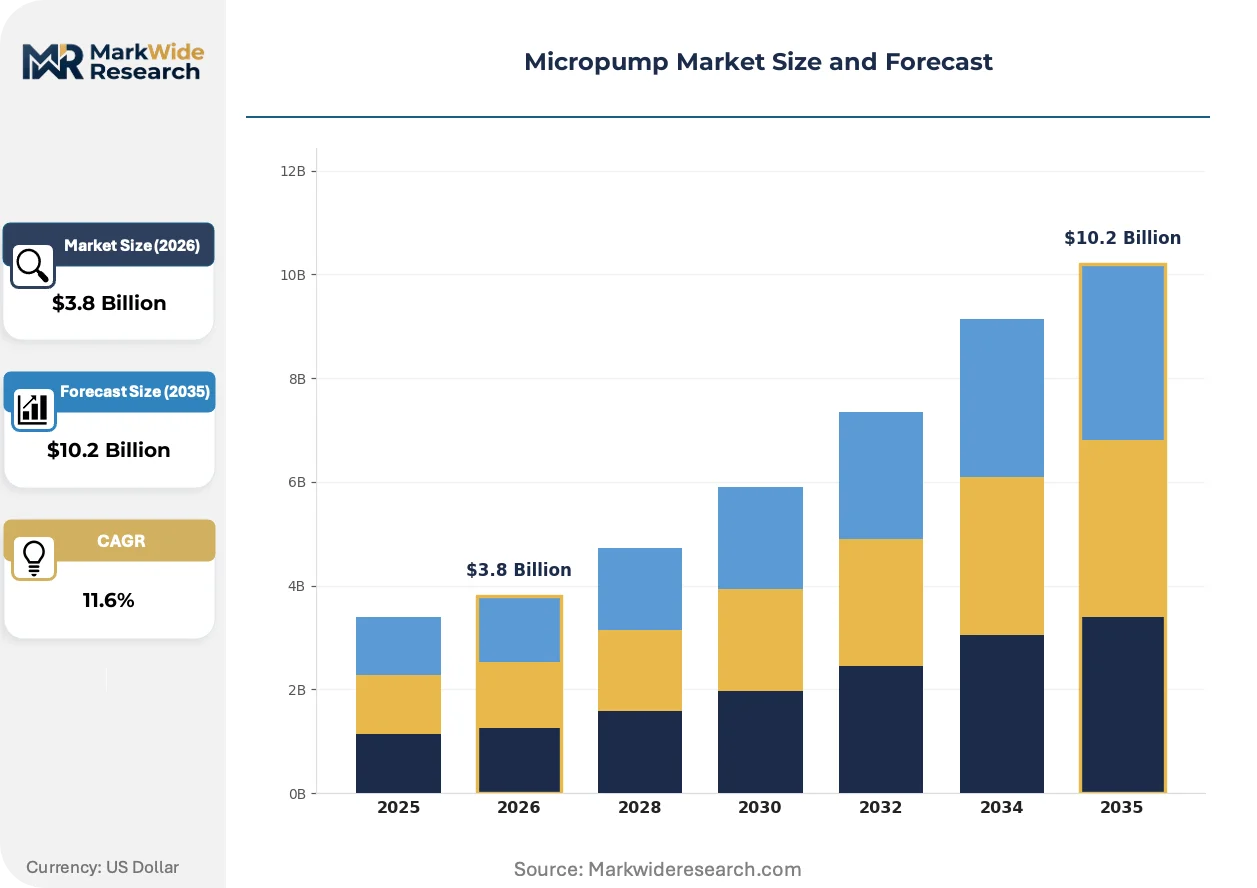
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peristaltic Micropumps, Centrifugal Micropumps, Gear Micropumps, Piezoelectric Micropumps End User: Pharmaceuticals, Agriculture, Automotive, Industrial Process Application: Drug Delivery, Water Treatment, Fuel Dispensing, Chemical Processing Technology: Microelectromechanical Systems, Carbon Nanotube Technology, Digital Valves, Optical Sensors |
| Companies Covered | Takasago Electric Inc., IDEX Corporation, The Lee Company, Bartels Mikrotechnik GmbH, Fluigent, Xavitech Micropumps, Servoflo Corporation, KNF Group, Dolomite Microfluids, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micropump Market Emerging Trajectories
Actuation physics, regulatory material mandates, and procurement centralization are simultaneously reshaping competitive differentiation in fluid handling subsystems.
Silicon-Pyrex bonded microvalve architectures are converging with printed circuit board integration techniques to enable single-chip lab-on-a-card systems. Diagnostic OEMs in Germany and Switzerland are adopting these platforms for portable coagulation monitoring. The structural consequence is compressing assembly steps from discrete component mounting to wafer-level batch processing, collapsing unit economics for high-volume disposable cartridges.
REACH Annex XIV authorization requirements for persistent organic pollutants are forcing fluoropolymer seal suppliers to validate perfluoroalkoxy (PFA) alternatives in wetted surfaces. The industrial consequence is material qualification bottlenecks extending pump development cycles by 8-12 months. Environmental monitoring instrument manufacturers in the Netherlands and Belgium are most affected, accelerating bio-based thermoplastic elastomer testing programs.
Hospital procurement consortia are consolidating fluid handling component sourcing through framework agreements with pre-qualified medical device suppliers. The distributor channel for standalone micropump modules is contracting as OEMs negotiate direct long-term supply contracts. This concentration is most visible in German and French acute care networks, where combination product liability concerns favor single-source validation over multi-vendor qualification.
Micropump Market Segmentation
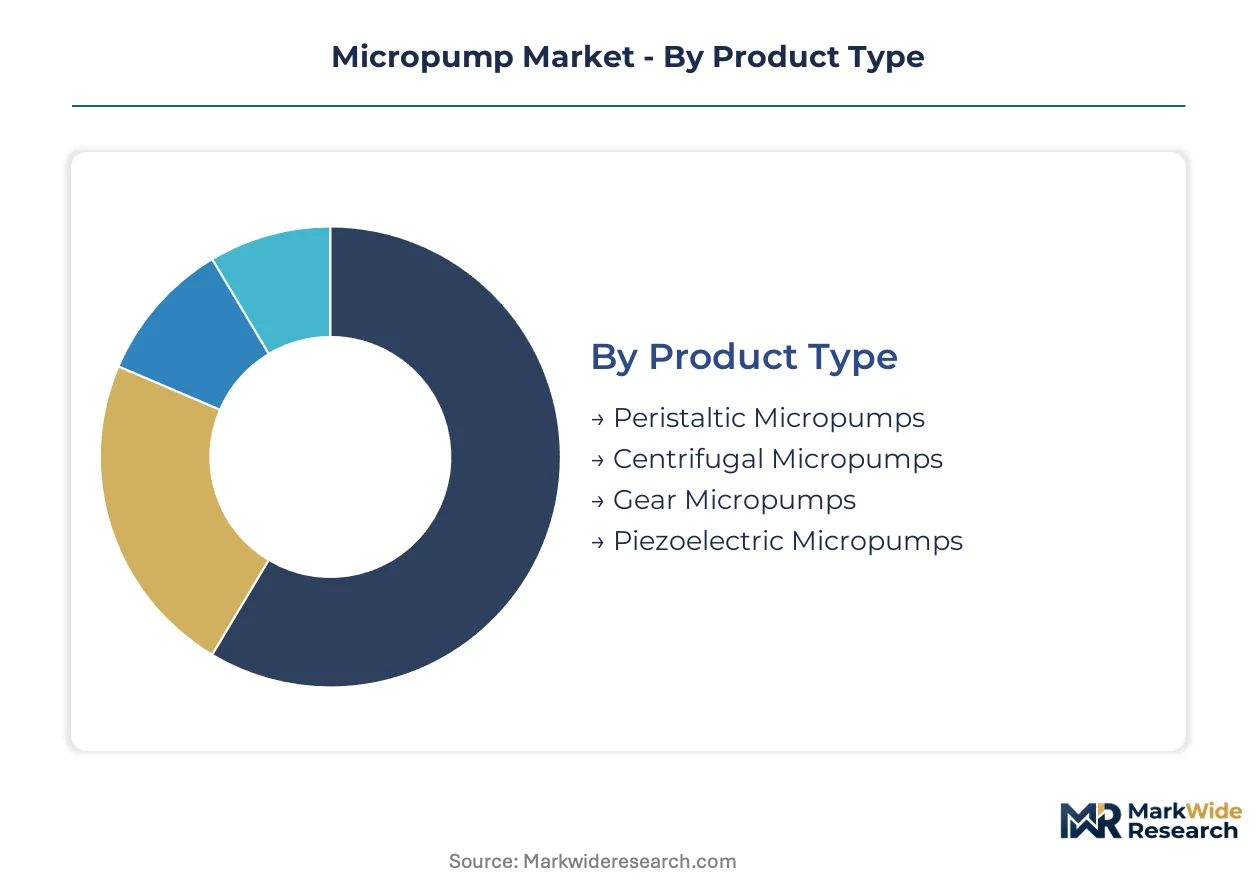
Micropump architectures diverge sharply across actuation physics, each commanding distinct validation burdens and margin structures. Segmentation by product type, end user, application, and technology reveals where procurement centralization and regulatory material mandates are compressing supplier economics.
Product Type:
Piezoelectric diaphragm actuation and peristaltic roller mechanisms anchor the technology axis, with centrifugal and gear architectures serving specialized flow regimes.
- Peristaltic Micropumps:Roller-based fluid displacement through compressible tubing creates sterile disposable flow paths essential for biopharmaceutical processing. Demand concentrates in German and Swiss contract manufacturing organizations where FDA validation histories protect against cross-contamination liability.
- Piezoelectric Micropumps:Lead zirconate titanate diaphragms enable silent, heat-minimal operation critical for wearable insulin delivery and closed-loop hormonal regulation. Patient-administered chronic disease management in Stuttgart and Munich medical device clusters drives procurement volume.
- Centrifugal Micropumps:Rotating impeller designs serve high-flow, low-pressure chemical processing applications where material compatibility outweighs precision dosing requirements.
- Gear Micropumps:Intermeshing polymer or stainless steel elements deliver pulsation-free metering for analytical instrument sample handling and microreactor continuous manufacturing.
Peristaltic micropumps lead on scale; piezoelectric micropumps lead on momentum.
End User:
Cost tier stratification separates validated medical device supply from industrial procurement where specification tolerance permits broader supplier qualification.
- Pharmaceuticals:Combination product regulations and EU MDR biocompatibility mandates force OEMs toward pre-qualified micropump modules with established ISO 13485 audit trails. Implantable drug delivery and portable diagnostic platforms concentrate demand.
- Agriculture:Precision fertigation and pesticide metering systems in water-stressed regions deploy low-cost peristaltic architectures with reduced validation documentation.
- Automotive:Fuel cell humidification and selective catalytic reduction dosing require automotive-grade sealing materials surviving thermal cycling and vibration exposure.
- Industrial Process:Chemical transfer and environmental monitoring instruments prioritize chemical inertness over precision, expanding addressable supply base beyond medical-qualified vendors.
Pharmaceuticals commands premium pricing; industrial process offers volume scale.
Application:
Application segmentation tracks where fluid handling precision intersects with patient safety criticality or environmental compliance exposure.
- Drug Delivery:Wearable infusion pumps and implantable hormonal regulators demand piezoelectric actuation for battery efficiency and silent operation. FDA combination product guidance and EU MDR implantable device classifications extend validation timelines.
- Water Treatment:Reagent metering for disinfection and pH adjustment deploys peristaltic and diaphragm architectures where chemical compatibility dominates specification.
- Fuel Dispensing:Micro-dosing accuracy for alternative fuel vehicles and hydrogen infrastructure requires specialized sealing materials meeting ATEX and EPA vapor recovery mandates.
- Chemical Processing:Flow chemistry microreactors and continuous manufacturing platforms integrate gear and centrifugal micropumps for precise stoichiometric control.
Drug delivery captures margin concentration; chemical processing expands most quickly.
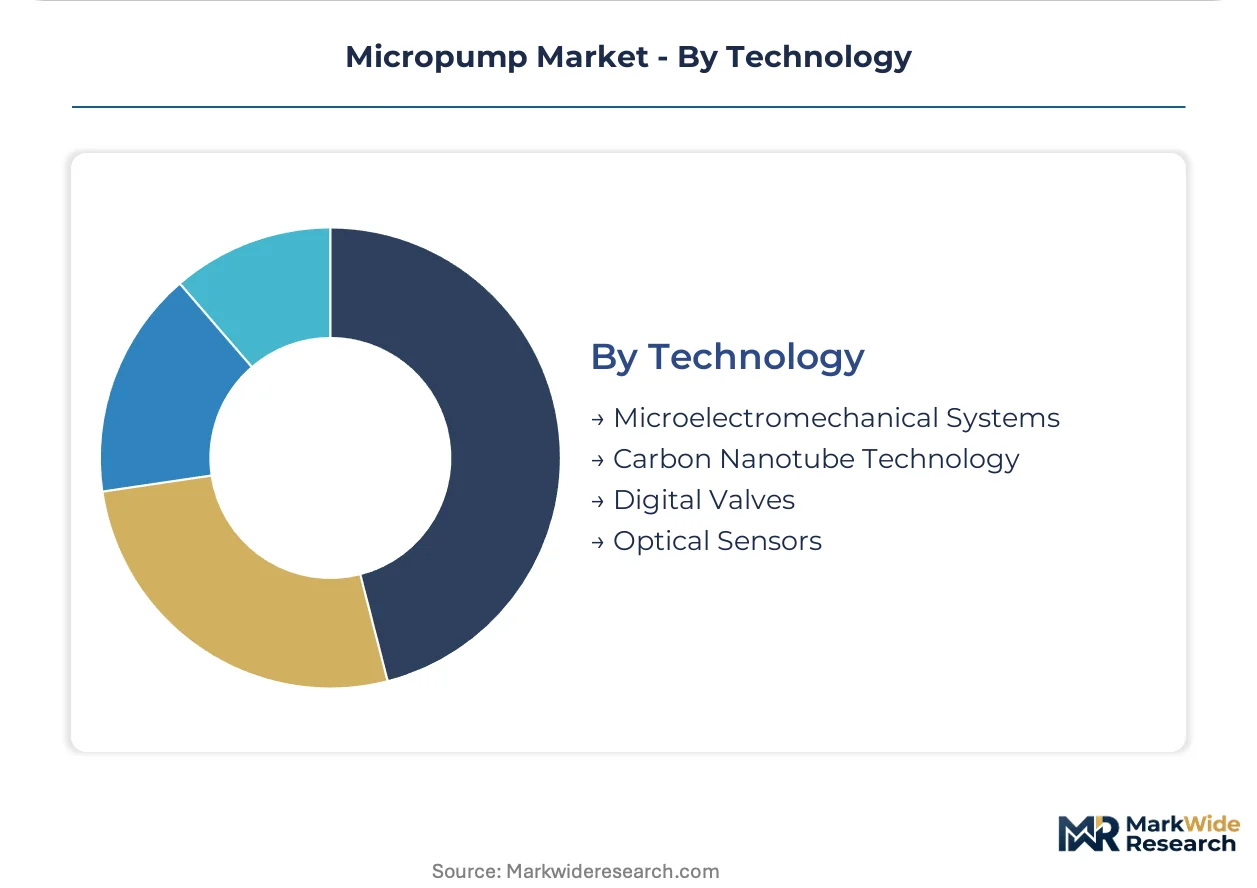
Technology:
Technology segmentation distinguishes mature MEMS fabrication from emerging material platforms still navigating qualification bottlenecks.
- Microelectromechanical Systems:Silicon-Pyrex bonded microvalves and piezoelectric diaphragms fabricated through semiconductor batch processing enable wafer-level economics for high-volume disposable diagnostic cartridges. German and Swiss diagnostic OEMs lead adoption for portable coagulation monitoring.
- Carbon Nanotube Technology:Nanostructured flow channels and electrically actuated membranes remain confined to research-phase drug delivery and lab-on-chip prototypes.
- Digital Valves:Solenoid-actuated microvalve arrays enable programmable flow routing in multiplexed analytical instruments and automated liquid handling workstations.
- Optical Sensors:Integrated flow rate monitoring through laser Doppler or particle image velocimetry supports closed-loop control in precision dosing applications.
MEMS dominates manufacturing scale; carbon nanotube technology holds steepest expansion trajectory contingent on biocompatibility validation completion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering traditions established micropump manufacturing fundamentals during the 1980s medical device boom, later diffusing to Swiss micromachining clusters and American life science corridors. Stuttgart's polymer fabrication expertise and Boston's diagnostic instrument concentration now anchor regional specialization patterns.
Germany
Stuttgart and Munich medical device manufacturing clusters drive procurement volume for piezoelectric diaphragm architectures in wearable insulin delivery systems. EU MDR biocompatibility testing mandates compress validation timelines for implantable drug delivery OEMs sourcing fluid handling modules. Baden-Württemberg's polymer micromachining supply chains support stainless steel substrate fabrication for precision dosing applications.
United States
FDA combination product guidance extends market access timelines for closed-loop hormonal regulation devices requiring silent, heat-minimal fluid displacement. Greater Boston's diagnostic instrument corridor concentrates demand for MEMS-fabricated microvalves in portable coagulation monitoring platforms. California's wearable health technology startups are sourcing validated micropump modules rather than building in-house fluid handling capabilities.
Switzerland
Swissmedic medical device classifications align with EU MDR requirements, creating streamlined regulatory pathways for German and French OEMs. Basel's pharmaceutical manufacturing hub integrates micropump-enabled microreactors for continuous manufacturing process intensification. Zurich's precision engineering clusters specialize in silicon-Pyrex bonded architectures for lab-on-card diagnostic systems.
China
Lead zirconate titanate feedstock dependence creates input cost volatility for piezoelectric actuator manufacturers serving domestic diagnostic instrument makers. NMPA medical device registration requirements are tightening quality system documentation for fluid handling subsystems in combination products. Yangtze River Delta precision manufacturing clusters are developing alternative ceramic actuation materials to reduce rare earth processing exposure.
India
CDSCO diagnostic device regulations are converging with EU IVDR frameworks for point-of-care PCR and immunoassay platforms requiring low-cost piezoelectric metering modules. Maharashtra's pharmaceutical manufacturing corridor is expanding contract research organization capacity for micropump-integrated drug delivery validation. Karnataka's medical device parks are attracting German and Swiss OEMs seeking qualified suppliers for portable diagnostic cartridges.
Micropump Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with ISO 13485 medical device audit histories protecting pricing power against unqualified industrial suppliers. The vendor base organizes into three strategic archetypes: diversified fluidics conglomerates serving multiple end-markets, specialized miniature valve and pump architects focused on aerospace and medical OEMs, and piezoelectric actuation experts targeting portable diagnostic platforms. Competitive moves concentrate on strategic partnerships with diagnostic OEMs and technology licensing agreements to navigate patent thickets covering drive circuits and sealing geometries.
Within the diversified conglomerate tier, IDEX Corporation represents multi-market fluid handling exposure across life science and industrial analytical applications. Among specialized architects, The Lee Company exemplifies focused miniature valve and pump expertise for aerospace and medical OEM qualification requirements. On the actuation-specialist vector, Bartels Mikrotechnik GmbH occupies a position defined by piezoelectric expertise tailored to portable diagnostic platforms. These three anchors illustrate how competitive positioning stratifies across certification depth, actuation physics specialization, and end-market diversification breadth.
| Leading Market Players |
|---|
| Takasago Electric Inc. |
| IDEX Corporation |
| The Lee Company |
| Bartels Mikrotechnik GmbH |
| Fluigent |
| Xavitech Micropumps |
| Servoflo Corporation |
| KNF Group |
| Dolomite Microfluids |
| Others |
Supply Flow & Price Mechanics
Lead zirconate titanate ceramic feedstock moves from Chinese rare earth processing through German precision engineering clusters before stratifying into ISO 13485-certified premium tiers and unqualified industrial supply.
Pricing Analysis
Certification-grade pricing stratification separates validated medical device modules from commodity industrial supply. Premium tiers command sustained margins through FDA audit trails and EU MDR biocompatibility documentation, while standard tiers compete on polymer micromachining scale in analytical instrument applications. Cost compression in the economy tier intensifies as Yangtze River Delta manufacturers enter diagnostic instrument supply. Hospital procurement consortia exhibit lowest price sensitivity due to combination product liability exposure; agricultural fertigation systems show highest sensitivity with specification tolerance permitting broader supplier qualification.
Supply Chain Analysis
Freight cost volatility from Asia-Europe routes compounds lead zirconate titanate ceramic dependence on Chinese rare earth processing. German and Swiss precision manufacturing clusters anchor finished pump assembly, drawing from Baden-Württemberg polymer micromachining and Stuttgart stainless steel substrate fabrication. Single-source vulnerability concentrates in piezoelectric actuator feedstock. Distribution runs through direct long-term contracts with diagnostic OEMs rather than distributor channels, as hospital procurement consortia consolidate sourcing through framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The micropump market compounds steadily as chronic disease management shifts toward patient-administered wearable formats requiring validated fluid handling subsystems.
For Market Incumbents: Deepen backward integration into piezoelectric ceramic supply to offset Chinese rare earth processing concentration. Expand ISO 13485-certified capacity in Baden-Württemberg polymer micromachining clusters to capture EU MDR-driven module outsourcing from implantable drug delivery OEMs. Patent thickets covering drive circuits and valve sealing geometries demand sustained cross-licensing investment to defend positioning. For New Entrants and Emerging Players: Diagnostic OEM partnerships in Maharashtra and Karnataka medical device parks offer white-space access as CDSCO regulations converge with EU IVDR frameworks. Point-of-care PCR and immunoassay platforms in India and Brazil present underpenetrated demand for low-cost piezoelectric metering modules. Pursue technology licensing agreements with established MEMS fabrication specialists to bypass 18-24 month ISO 13485 certification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 audit histories protect pricing power against unqualified industrial suppliers. The five-to-ten year viability thesis rests on wearable drug delivery penetration and continuous manufacturing adoption in pharmaceutical processing. Acquisition targets center on piezoelectric actuation specialists with established diagnostic OEM relationships. Watch for REACH Annex XIV fluoropolymer authorization bottlenecks as inflection indicators for bio-based elastomer substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Accelerates market access timelines for implantable drug delivery OEMs sourcing validated modules. |
| Piezoelectric Ceramic Supply Agreement | Reduces forced substitution risk from Chinese rare earth processing concentration. |
| Diagnostic OEM Partnership | Locks in framework agreements as hospital procurement consortia consolidate fluid handling sourcing. |
| Bio-Based Elastomer Development | Captures first-mover advantage from EU Green Deal REACH-compliant wetted surface mandates. |
| MEMS Fabrication Scale-Up | Enables wafer-level economics for high-volume disposable diagnostic cartridge production. |
Methodological Framework
Bottom-up pharmaceutical and diagnostic instrument modeling reconciled against top-down precision manufacturing capacity tracking forms the analytical core. Primary interviews with biomedical engineers, hospital GPO contracts managers, regulatory affairs leads at combination product OEMs, and polymer micromachining plant directors combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, ISO 13485 audit registries, and German medical device production statistics.
Historical trendline analysis of installed base expansion and replacement cycles across piezoelectric and peristaltic architectures informed projection frameworks. Segmentation modeling spanned actuation physics, certification grade, end-use industry, and regional regulatory cluster. CAGRs derived from elasticity-adjusted penetration curves for wearable insulin delivery and point-of-care diagnostic platforms. Forecast inputs incorporated EU MDR implementation timelines and REACH Annex XIV authorization schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to piezoelectric ceramic supply disruptions and FDA combination product guidance evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Disposable Ph Sensors Market
Sensors and Controls
Global Wireless Brain Sensors Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
Battery Free Sensor Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Temperature Monitoring Devices Market
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Digital Automation Temperature Regulator Market