
 Occupancy Sensor Market | 2026-2036
Occupancy Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Occupancy Sensor Market Intelligence
China is narrowing its component supply gap for passive infrared elements and microwave detector cores used in occupancy sensor assemblies. Honeywell International leverages backward integration into MEMS fabrication to secure detector supply for its building automation portfolio. Acuity Brands anchors its position through deep specification relationships with North American electrical contractors and lighting designers. Legrand competes by bundling occupancy sensors with structured wiring and PoE infrastructure across European commercial fit-outs.
An occupancy sensor detects human presence through passive infrared, ultrasonic, or dual-technology detection methods, typically operating at detection ranges of 15 to 30 feet with field-of-view angles between 110 and 360 degrees depending on lens configuration; its primary purpose is to trigger automated responses in lighting, climate, or security systems based on real-time space utilization. Dual-technology sensors command premium positioning by combining PIR and ultrasonic elements to eliminate false triggers in complex commercial environments, while wireless sensors represent the fastest-expanding technology segment as battery-harvesting and mesh protocols reduce installation labor in retrofit projects. Smart lighting applications absorb the largest volume share, though energy management platforms are emerging as the higher-margin attachment point for software-integrated sensor networks.
The EU Green Deal and F-Gas Regulation are tightening energy performance standards for commercial buildings, directly expanding specification requirements for occupancy-driven HVAC and lighting controls across member states. The US Department of Energy appliance standards and state-level stretch codes in California and New York mandate automatic shutoff capabilities that embed occupancy detection as baseline infrastructure. Stakeholders must monitor how evolving cybersecurity frameworks for connected building devices reshape certification barriers and procurement criteria for wireless sensor deployments.
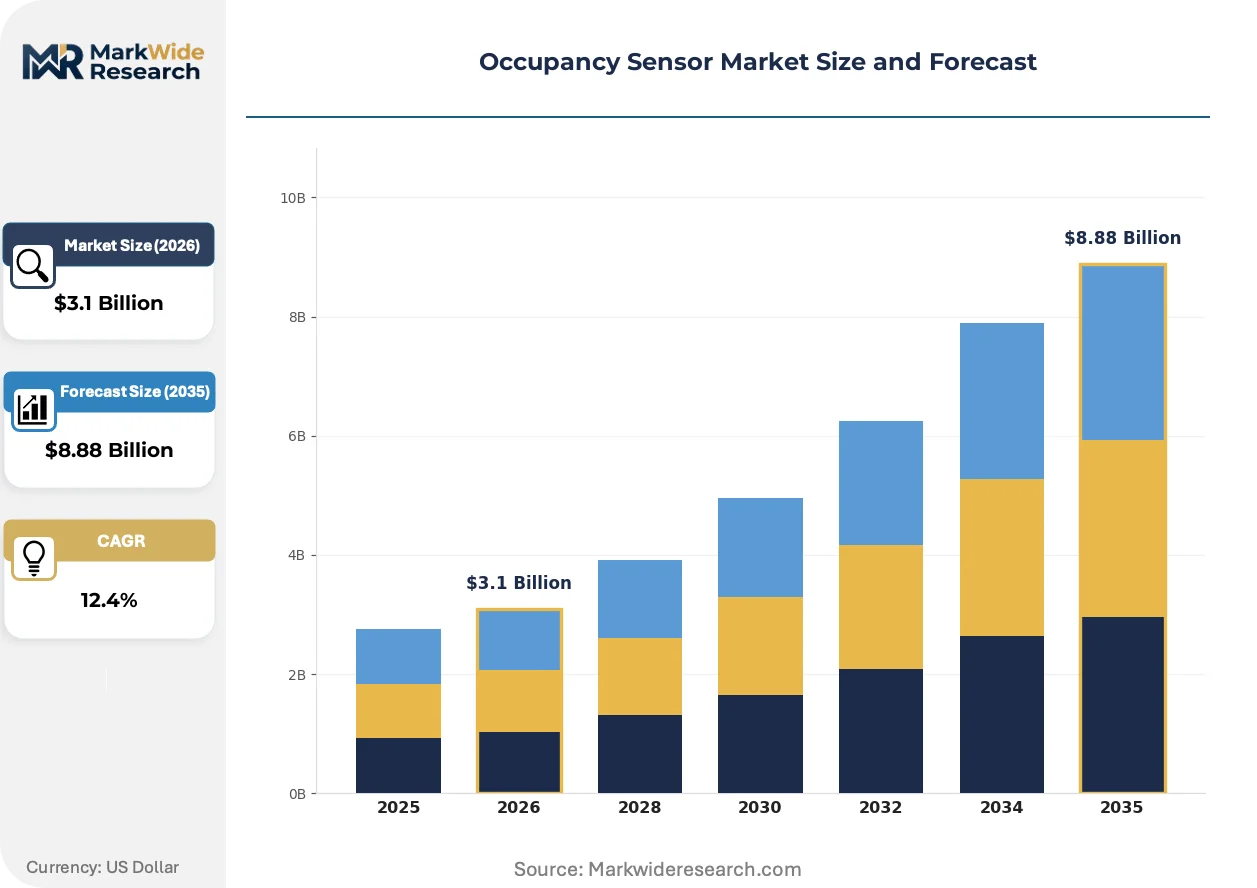
Market Dynamics
Building automation retrofits are compressing installation timelines for occupancy-driven controls, as energy compliance deadlines force facility managers to prioritize wireless and PoE-enabled sensors over traditional hardwired infrastructure.
Growth Catalysts
- EU Green Deal building mandates:Member states must achieve near-zero energy performance in commercial structures, embedding occupancy sensors as baseline HVAC and lighting control infrastructure.
- Passive infrared element supply localization:China's narrowing component gap is reducing lead times for detector cores and lowering assembly costs for regional manufacturers.
- Smart lighting retrofits:Commercial office landlords are specifying dual-technology sensors to satisfy automatic shutoff requirements while minimizing false triggers in open-plan environments.
Market Restraints
- MEMS fabrication concentration:Backward integration into detector production requires capital-intensive cleanroom investment, favoring incumbents with captive semiconductor supply.
- F-Gas Regulation refrigerant phase-down:HVAC sensor specifications must adapt to lower-GWP systems, creating compatibility friction with legacy control architectures.
- Ultrasonic interference vulnerability:Industrial facilities with high-frequency equipment generate false positives that degrade user trust and trigger manual override.
Strategic Opportunities
- German industrial automation:Factory digitization programs are creating specification pull for ruggedized PoE sensors with integrated temperature and humidity sensing.
- Battery-harvesting wireless protocols:Kinetic and photovoltaic energy harvesting is eliminating battery replacement labor in hard-to-access retrofit locations.
- Energy management platform bundling:Software-integrated sensor networks command premium positioning through subscription-based analytics rather than hardware margin alone.
Industry Challenges
- Cybersecurity certification timelines:Connected device frameworks for building automation are extending type-approval cycles and fragmenting procurement criteria across member states.
- Legacy BAS integration complexity:Proprietary communication protocols in existing building management systems require protocol gateways that inflate installed cost and commissioning duration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Occupancy Sensor Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Sensors, Ultrasonic Sensors, Dual-Technology Sensors, Photoelectric Sensors Application: Smart Lighting, HVAC Control, Security Systems, Energy Management End User: Residential Buildings, Commercial Offices, Retail Stores, Industrial Facilities Technology: Wired Sensors, Wireless Sensors, Battery-Powered Sensors, PoE Sensors |
| Companies Covered | Honeywell International, Acuity Brands, Legrand, Hubbell, Signify Holding, Johnson Controls, Schneider Electric, Lutron Electronics, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Occupancy Sensor Market Strategic Shifts & Innovations
Wireless mesh architectures and energy-harvesting power supplies are rewriting the economics of sensor deployment in retrofit-dominated building stock. Three developments are compressing the traditional technology lifecycle.
Time-of-flight infrared sensing is collapsing the cost-performance tradeoff that previously favored ultrasonic detection in high-ceiling commercial spaces. Big-box retailers and distribution centers are specifying solid-state ToF modules for aisle-level occupancy granularity without the maintenance burden of mechanical relays. The technology is collapsing installation labor requirements by enabling ceiling-mount flexibility that eliminates the wiring runs demanded by fixed-position PIR lenses.
The F-Gas Regulation's refrigerant phase-down schedule is forcing HVAC control manufacturers to recalibrate sensor algorithms for variable-refrigerant-flow systems. Equipment OEMs must validate occupancy-driven compressor modulation across new thermal profiles, compressing R&D cycles for integrated control packages. German and French commercial building codes are tightening fastest, pulling sensor specification toward dual-technology units capable of reliable detection in thermally stratified atrium spaces.
Electrical contractors are consolidating specification influence through design-build contracts that bundle sensor selection with lighting and low-voltage infrastructure. This channel compression is displacing traditional distributor-led procurement in North American commercial fit-outs. California and New York stretch codes are accelerating the shift by mandating automatic receptacle control that contractors address through unified sensor-activated circuit designs.
Occupancy Sensor Market Segmentation
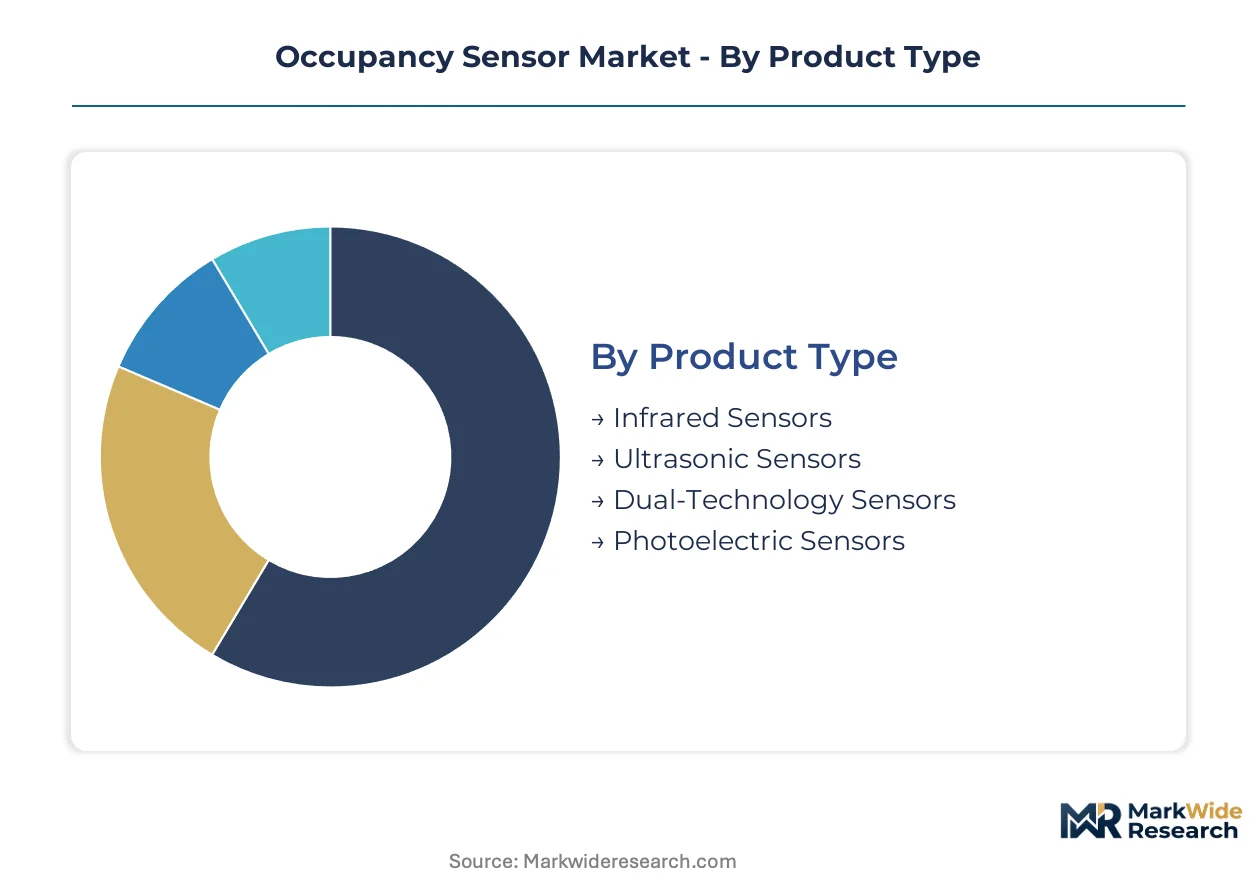
Segmentation in the occupancy sensor market reflects divergent technical requirements across building automation layers. Product architecture, power delivery, and detection methodology determine specification viability for distinct retrofit versus new-construction scenarios.
Product Type:
Detection methodology defines unit economics and false-trigger susceptibility across commercial deployment contexts.
- Infrared Sensors:Passive infrared elements detect body heat through Fresnel lens arrays with 110-degree to 180-degree coverage patterns. Demand concentrates in German industrial retrofits where EU Green Deal energy audits mandate low-cost presence detection for warehouse aisle lighting.
- Dual-Technology Sensors:Combined PIR and ultrasonic detection eliminates false positives through correlated signal validation. California commercial office landlords specify these units to satisfy Title 24 automatic shutoff requirements while maintaining occupant comfort in open-plan environments.
- Ultrasonic Sensors:Doppler-shift detection covers 360-degree zones through ceiling-mounted transducers. New York healthcare facilities deploy these for restroom and corridor monitoring where line-of-sight obstruction challenges infrared reliability.
- Photoelectric Sensors:Beam-break and reflective variants serve specialized door-counting and zone-boundary applications. Logistics operators in Dutch distribution centers integrate these with warehouse management systems for real-time occupancy dashboards.
Infrared sensors command the established base. The steepest expansion runs through dual-technology units.
Application:
Use-case priority determines sensor specification complexity and software integration depth.
- Smart Lighting:Fixture-embedded sensors enable daylight harvesting and dimming control through DALI or 0-10V interfaces. French commercial building codes now mandate autonomous lighting shutoff, pulling specification toward wireless retrofit units in Parisian office stock.
- Energy Management:Granular space-utilization data feeds analytics platforms for demand-response optimization. German facility managers bundle these sensors with BMS subscriptions to comply with federal efficiency reporting requirements.
- HVAC Control:Occupancy-driven variable air volume modulation reduces conditioning load in intermittently used zones. The F-Gas Regulation's refrigerant phase-down forces recalibration of sensor algorithms for lower-GWP equipment across EU member states.
- Security Systems:Intrusion detection and access verification require tamper-resistant housings with supervised signaling. Italian banking infrastructure projects specify PoE-powered units with integrated camera triggers for branch protection.
Smart lighting absorbs the highest unit volumes. Energy management platforms are climbing the fastest as software-integrated networks displace standalone hardware sales.
End User:
Building typology shapes procurement authority, installation labor constraints, and technology refresh cycles.
- Commercial Offices:Tenant improvement budgets and lease compliance deadlines compress decision timelines. Design-build electrical contractors in California and New York now specify unified sensor-activated circuits to meet stretch code receptacle control mandates.
- Industrial Facilities:Ruggedized housings with IP65 ratings withstand dust, vibration, and temperature extremes. German factory digitization programs create specification pull for PoE sensors with integrated environmental sensing on production floors.
- Retail Stores:Aisle-level granularity and queue monitoring drive time-of-flight infrared adoption. Big-box operators prioritize solid-state modules that eliminate mechanical relay maintenance burdens.
- Residential Buildings:Battery-powered wireless units dominate retrofit installations where routing new wiring proves cost-prohibitive. Multi-family developers in Spain specify these for common area lighting control under national efficiency certification schemes.
Commercial offices represent the core revenue pool. Industrial facilities are expanding most quickly as manufacturing automation deepens sensor penetration.
Technology:
Power delivery architecture determines installation economics, maintenance burden, and network integration capabilities.
- PoE Sensors:IEEE 802.3bt-powered units combine data and power on single cable runs, eliminating separate electrical contractor mobilization. Legrand bundles these with structured wiring infrastructure across European commercial fit-outs to capture specification influence.
- Wireless Sensors:Mesh protocols and battery-harvesting designs eliminate wiring labor in hard-to-access retrofit locations. Kinetic and photovoltaic energy harvesting variants are gaining specification in historic building renovations where fabric preservation restricts invasive work.
- Wired Sensors:Hardwired power and signal connections remain standard in new construction with open ceilings. Traditional PIR lenses in this category face displacement as time-of-flight modules enable more flexible ceiling-mount positioning.
- Battery-Powered Sensors:Self-contained operation suits rapid deployment in temporary or leased spaces. Maintenance contracts for battery replacement create recurring revenue streams for facility service providers in fragmented European markets.
Wired infrastructure retains the installed base. Wireless architectures are gaining share fastest as retrofit timelines compress and energy-harvesting reliability improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detector core fabrication concentrates in East Asian foundries, while specification authority and systems integration remain anchored in Western European and North American building automation hubs. This geographic split shapes procurement patterns, regulatory alignment, and technology transfer flows across the value chain.
United States
Commercial office retrofits in California and New York are compressing installation timelines for wireless occupancy sensors as state stretch codes mandate automatic receptacle control. The US Department of Energy appliance standards embed occupancy detection as baseline infrastructure for lighting shutoff compliance. Design-build electrical contractors in Los Angeles and Manhattan now specify unified sensor-activated circuits to capture specification influence.
Germany
Industrial facility automation and building efficiency mandates are driving procurement of dual-technology and PoE-enabled occupancy sensors across factory floors and logistics centers. The EU Green Deal and tightening F-Gas Regulation are reshaping HVAC-linked sensor specifications, forcing algorithm recalibration for lower-GWP equipment. Bavarian automotive suppliers and North Rhine-Westphalia distribution hubs represent concentrated demand clusters for ruggedized environmental sensing units.
China
Domestic manufacturers are narrowing the component supply gap for passive infrared elements and microwave detector cores used in occupancy sensor assemblies. National efficiency certification schemes for commercial buildings are accelerating specification of locally produced wireless retrofit units. Yangtze River Delta electronics clusters and Pearl River Delta assembly operations are capturing growing share of regional detector fabrication.
France
Commercial building codes in Paris and Lyon mandate autonomous lighting shutoff, pulling specification toward wireless retrofit occupancy sensors in aging office stock. The F-Gas Regulation's refrigerant phase-down is forcing HVAC control manufacturers to validate sensor algorithms for variable-refrigerant-flow systems. Île-de-France commercial landlords bundle sensor networks with energy management platform subscriptions to comply with federal efficiency reporting requirements.
Japan
MEMS fabrication capabilities in Kanto and Kansai regions support precision detector production for building automation OEMs serving domestic and export markets. METI efficiency standards for commercial structures embed occupancy-driven controls as baseline infrastructure. Tokyo and Osaka commercial retrofit projects prioritize solid-state time-of-flight modules to minimize maintenance burdens in high-ceiling retail and logistics environments.
Occupancy Sensor Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in detector fabrication and lens assembly. The vendor base spans three tiers: multinational building automation conglomerates with captive semiconductor supply, mid-scale electrical manufacturers bundling sensors with infrastructure products, and regional specialists focused on wireless retrofit deployment. Two competitive moves dominate: backward integration into MEMS fabrication to secure detector supply, and specification capture through design-build contractor relationships that displace traditional distribution channels.
Among diversified building technology conglomerates, Honeywell International, Acuity Brands, and Legrand occupy positions that exemplify contrasting strategic archetypes. Honeywell represents the vertically integrated platform play with in-house detector production. Acuity Brands anchors the specification-driven lighting integration model through contractor relationships. Legrand exemplifies the infrastructure-bundling approach, capturing sensor placement through structured wiring and PoE package dominance in European commercial fit-outs.
| Leading Market Players |
|---|
| Honeywell International |
| Acuity Brands |
| Legrand |
| Hubbell |
| Signify Holding |
| Johnson Controls |
| Schneider Electric |
| Lutron Electronics |
| Eaton |
| Others |
Cost & Logistics Intelligence
East Asian MEMS foundry concentration in Taiwan and South Korea funnels detector supply through a narrow upstream tier, concentrating margin capture with building automation conglomerates that have secured captive semiconductor production while squeezing mid-scale electrical manufacturers dependent on merchant markets.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across European commercial fit-outs, with F-Gas Regulation compliance costs stratifying hardware margins. Three-tier pricing structure across premium dual-technology, standard PIR, and economy infrared levels reflects certification grade and PoE integration depth. Cost compression in wireless retrofit units is intensifying because battery-harvesting designs eliminate installation labor premiums. Design-build electrical contractors in California and New York show least price sensitivity due to stretch-code compliance deadlines, while multi-family residential developers in Spain remain most cost-conscious.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for detector core procurement. Component fabrication concentrates in China, Taiwan, and Japan, with assembly operations drawing from Yangtze River Delta and Pearl River Delta electronics clusters. Raw material dependencies rest on silicon wafers, Fresnel lens polymers, and rare-earth elements for microwave transducers. Single-source vulnerability in MEMS cleanroom capacity creates bottleneck risk for non-integrated manufacturers. Distribution runs through specification-capture relationships with design-build contractors and electrical distributors, displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Energy management platform subscriptions are expanding faster than standalone hardware sales, converting one-time sensor transactions into recurring analytics revenue streams that attach to building automation service contracts.
For Market Incumbents: Pre-empt wireless retrofit specialists by acquiring battery-harvesting protocol expertise before kinetic and photovoltaic designs commoditize installation labor advantages. Secure captive MEMS fabrication capacity to defend against detector supply rationing during capacity crunches. Channel control through design-build contractor relationships represents the critical defensive lever against distributor disintermediation. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with national efficiency certification schemes accelerating specification of cost-optimized wireless units. Historic building renovations across Southern Europe offer secondary white-space where fabric preservation restrictions favor non-invasive sensor deployment. A go-to-market angle anchored to facility management software partnerships bypasses entrenched electrical distribution channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across wireless sensor sub-segments as energy-harvesting designs eliminate battery replacement infrastructure. Long-term viability favors platform-integrated vendors with software attach capabilities over pure hardware manufacturers. Acquisition target archetype: regional wireless retrofit specialists with established contractor relationships and localized certification expertise. The signal to watch is design-build contract consolidation in North American commercial fit-outs as an indicator of specification influence concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Honeywell's captive detector production secures supply against Taiwan foundry bottlenecks. |
| PoE Infrastructure Bundling | Legrand's structured wiring packages capture sensor placement in European commercial fit-outs. |
| Energy Management Platform Integration | Software-integrated networks command subscription revenue beyond hardware margins alone. |
| Wireless Mesh Protocol Development | Battery-harvesting designs eliminate installation labor barriers in historic building retrofits. |
| Design-Build Contractor Specification Capture | Acuity Brands' electrical contractor relationships displace traditional distribution channels. |
Research Approach
Desk research of regulatory filings, customs trade databases, and building code amendments preceded structured interviews with building automation system integrators, electrical contractor procurement leads, facility management software vendors, and MEMS fabrication specialists. Primary fieldwork with design-build contractors in California, New York, and Germany validated specification timeline compression and wireless adoption patterns. Secondary sources included EU Green Deal implementation directives, F-Gas Regulation technical guidance, and DOE appliance standard dockets. Bottom-up sensor shipment estimates triangulated against top-down building automation market sizing.
Assumptions held fixed include regulatory compliance deadlines across EU member states and US stretch code adoption trajectories, while variables included energy-harvesting technology maturation curves and wireless protocol standardization outcomes. The analytical framework modeled segmentation across detection methodology, power delivery architecture, application layer, and end-user building typology throughout the forecast period. CAGRs derived from installed base turnover rates, new construction permitting data, and retrofit project pipelines. Industry-specific inputs incorporated HVAC equipment refresh cycles tied to F-Gas refrigerant phase-down schedules and smart lighting fixture replacement rates in commercial office stock.
Macroeconomic conditions sit as an overlay; deviation in commercial real estate investment volumes and construction cost inflation would shift the trajectory. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory enforcement intensity. Cybersecurity certification timeline extensions and legacy BAS integration complexity represent specific risk factors that could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Spain Digital Thermometer Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Non-Contact Infrared Thermometer Market
Sensors and Controls
Magnetic Field Sensor Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
France Air Purifier Market