
 US Digital Pregnancy Test Kits Market | 2026-2036
US Digital Pregnancy Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
US Digital Pregnancy Test Kits Market Analytics
Biodegradable plastics are restructuring material economics across the US Digital Pregnancy Test Kits landscape as manufacturers reduce petroleum-based polymer dependence. Church & Dwight Co., Inc. leverages its established retail shelf presence to sustain volume leadership in drugstore channels. Swiss Precision Diagnostics GmbH anchors premium positioning through sensor-based accuracy claims. Procter & Gamble Co. competes via broad distribution infrastructure spanning supermarkets and online platforms.
US Digital Pregnancy Test Kits are single-use diagnostic devices incorporating monoclonal antibody-based hCG detection chemistry with LCD or Bluetooth-enabled digital readout interfaces, manufactured through injection-molded plastic housing assembly and lateral flow membrane integration, primarily serving conception confirmation and fertility monitoring applications. Digital Test Kits command margin concentration due to consumer willingness to pay for unambiguous result displays versus line-interpretation ambiguity in traditional formats. Mobile Integration represents the fastest-expanding technology segment as smartphone-connected cycle tracking creates recurring engagement beyond the single-test event. Online Sales channels are displacing drugstore dominance among younger demographics seeking privacy and subscription replenishment options.
FDA 510(k) clearance requirements govern over-the-counter diagnostic claims and accuracy thresholds, while EPA regulations on medical device waste streams influence end-of-life disposal labeling obligations. The FTC monitors advertising substantiation for fertility-related health claims, creating compliance overhead for emerging entrants. Stakeholders must weigh sensor technology investments against evolving FDA software-as-medical-device guidance that could reclassify app-connected tests.
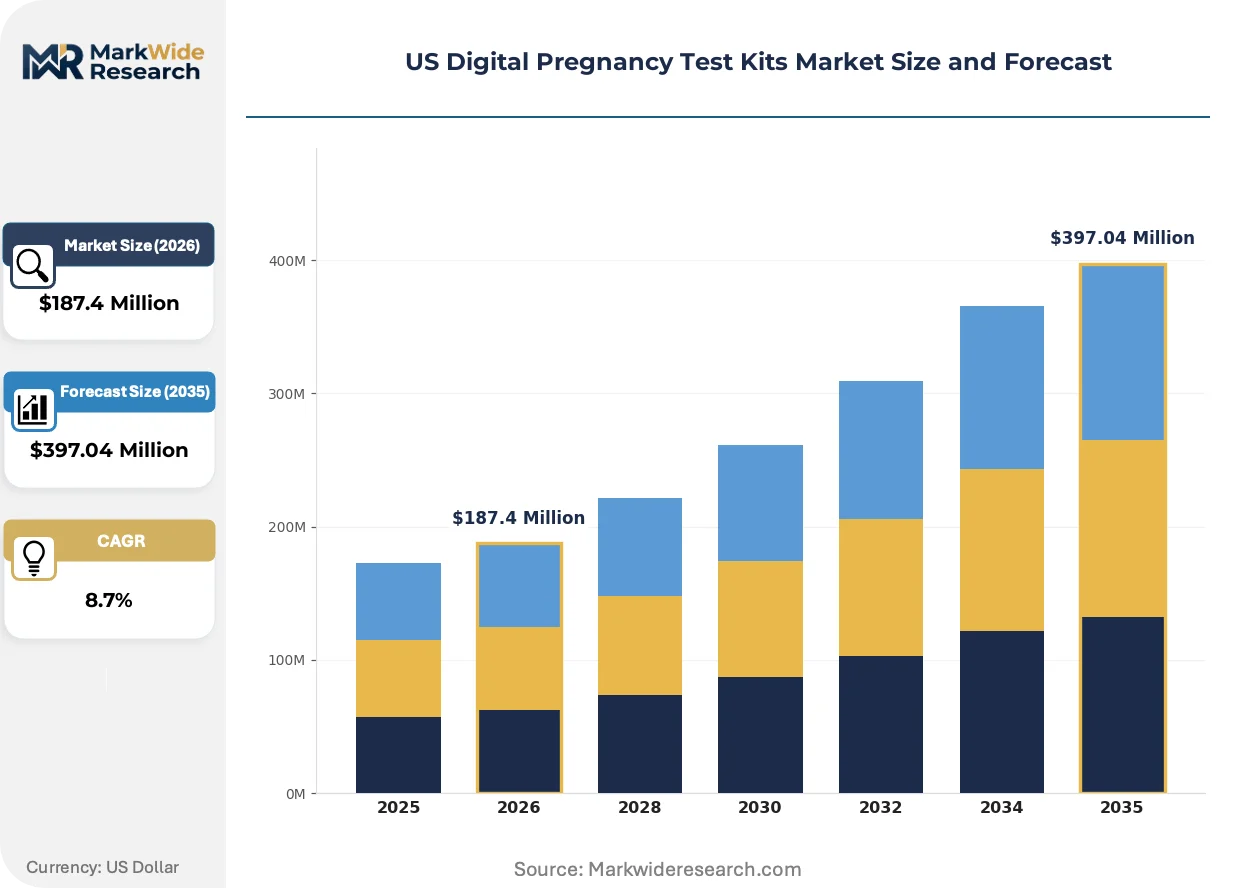
Market Dynamics
Bluetooth-enabled cycle tracking is electrifying product roadmaps as manufacturers compete for recurring app engagement beyond single-use diagnostics, forcing FDA to clarify software-as-medical-device boundaries for connected fertility tools.
Growth Catalysts
- Self-Directed Health Monitoring:Home-use consumers in California, Texas, and New York corridors drive volume as digital health literacy intersects with pharmacy chain density.
- FDA 510(k) Pathway Clarity:Established over-the-counter clearance frameworks accelerate commercialization timelines for lateral flow membrane innovations.
- Biodegradable Plastics:Material substitution away from petroleum-based polymers reduces EPA disposal compliance costs while appealing to environmentally conscious buyers.
Market Restraints
- Monoclonal Antibody Supply Concentration:hCG detection chemistry depends on specialized bioreactor capacity concentrated among contract manufacturers.
- Injection-Molded Housing Cost Volatility:Petroleum-derived plastic resin prices fluctuate with energy markets, compressing margins on economy-tier SKUs.
- LCD Component Lead Times:Display module procurement faces semiconductor foundry allocation constraints extending production schedules.
Strategic Opportunities
- Subscription Replenishment Models:Online sales channels enable recurring revenue capture among privacy-seeking demographics under 35.
- Fertility Monitoring Apps:Smartphone-connected test results integrate with cycle prediction algorithms, expanding addressable use cases beyond conception confirmation.
- EPA Waste Stream Labeling:Anticipated medical device disposal regulations create first-mover advantage for biodegradable housing adopters.
Industry Challenges
- FTC Advertising Substantiation:Fertility-related health claims require clinical evidence documentation, elevating compliance overhead for emerging entrants.
- Sensor Calibration Expertise:Capacitive hCG detection demands specialized electrochemistry talent scarce in traditional diagnostic device engineering pools.
- App-Connected Test Reclassification Risk:Evolving FDA software guidance threatens to recategorize Bluetooth-enabled products as higher-risk devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Digital Pregnancy Test Kits Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Test Kits, Traditional Test Kits, Midstream Test Kits, Early Detection Kits End User: Women, Clinics, Pharmacies, Online Retailers Distribution Channel: Online Sales, Retail Stores, Supermarkets, Drugstores Technology: Fertility Tracking, Sensor-based Testing, Mobile Integration, Signal Detection |
| Companies Covered | Church & Dwight Co., Inc., Swiss Precision Diagnostics GmbH, Gregory Pharmaceutical Holdings, Inc., Procter & Gamble Co., Quidel Corporation, Sugentech, Inc., Mankind Pharma, Prestige Consumer Healthcare Inc., NTBIO Diagnostics Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Digital Pregnancy Test Kits Market Evolving Landscape
Sensor miniaturization and wireless connectivity are compressing the traditional pregnancy test into a data-generating node within broader reproductive health ecosystems, blurring hardware boundaries with software services.
Capacitive hCG sensing is electrifying accuracy benchmarks by detecting hormone concentration through electrical impedance rather than optical line interpretation. Fertility-focused millennials and Gen Z adopters in metropolitan corridors are switching to premium digital formats at three times the rate of suburban counterparts. This sensor architecture is compressing the price-performance gap between clinical laboratory immunoassays and over-the-counter diagnostics.
FTC scrutiny of fertility app data monetization is tightening substantiation requirements for algorithmic cycle predictions derived from test results. Manufacturers must now document clinical validation for any health claim extending beyond binary pregnancy detection. Connected test providers in California and New York face the steepest compliance ramps as state attorneys general coordinate with federal enforcement.
Subscription-based replenishment is displacing drugstore impulse purchases among cohorts prioritizing discretion and automated supply continuity. Pharmacy chains in Texas and Florida are responding with private-label digital formats and loyalty-program bundling. This channel rotation concentrates margin pressure on traditional retail distributors while rewarding direct-to-consumer infrastructure investments.
US Digital Pregnancy Test Kits Market Segmentation
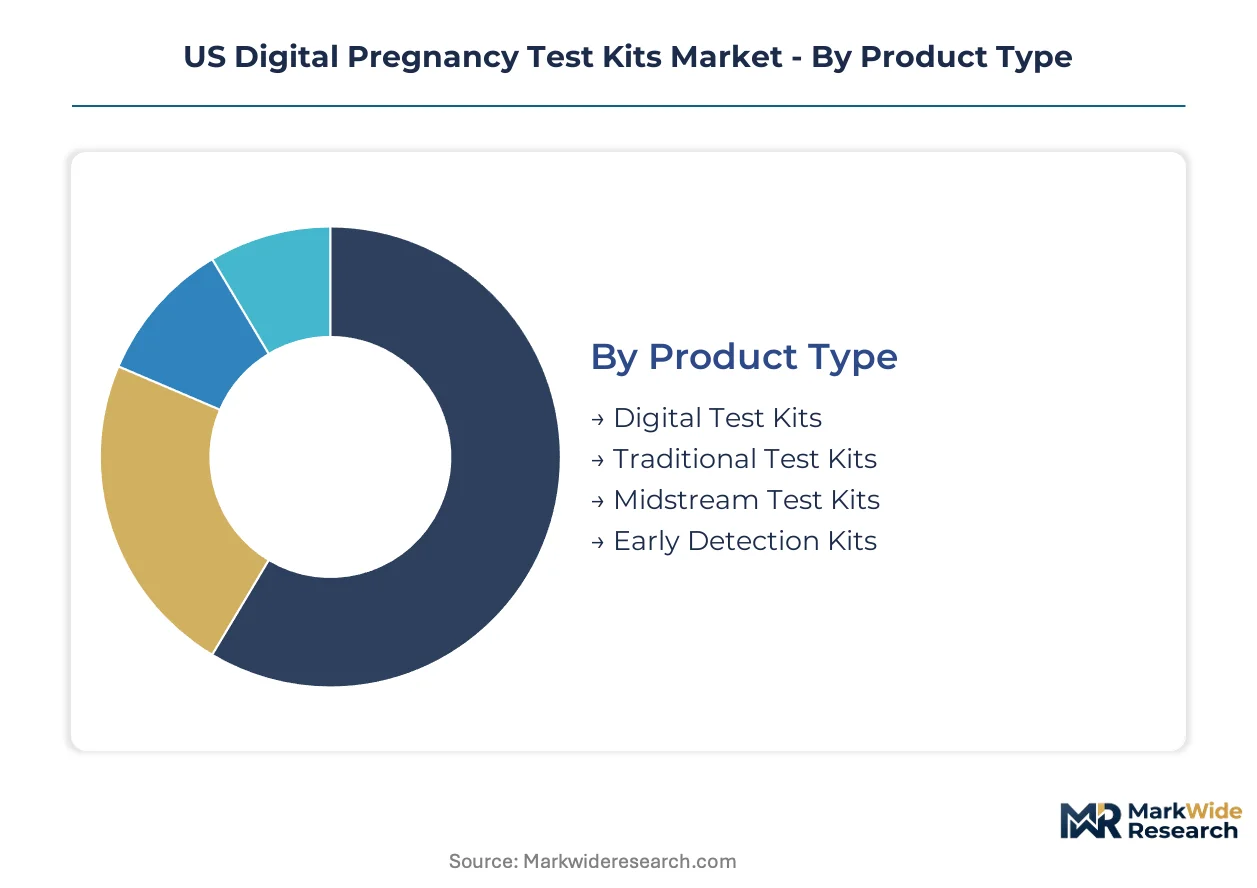
Segmentation in the US Digital Pregnancy Test Kits market reveals how manufacturing capacity, regulatory pathways, and channel economics concentrate value capture. Distinct product tiers, user profiles, and technology investments create divergent margin structures across the competitive landscape.
Product Type:
Supply concentration in monoclonal antibody sourcing and LCD module procurement favors manufacturers with scale to secure bioreactor capacity and semiconductor allocation.
- Digital Test Kits:These devices combine monoclonal antibody-based hCG detection chemistry with LCD or Bluetooth-enabled readout interfaces, manufactured through injection-molded plastic housing assembly. Demand concentrates among metropolitan consumers in California, Texas, and New York corridors where digital health literacy and pharmacy chain density intersect most densely. FDA 510(k) clearance requirements for over-the-counter diagnostics shape development timelines and substantiation costs for accuracy claims.
- Early Detection Kits:Engineered for hCG detection at lower concentration thresholds through enhanced lateral flow membrane sensitivity, these products command premium positioning. Adoption clusters among fertility-focused millennials and Gen Z adopters in metropolitan healthcare corridors seeking cycle tracking integration, with subscription replenishment models displacing traditional drugstore purchases among privacy-seeking demographics under 35.
- Midstream Test Kits:Standard-format devices with direct urine stream application, manufactured through conventional lateral flow membrane integration without digital readout components.
- Traditional Test Kits:Line-interpretation format devices utilizing optical result reading, facing margin compression as consumers shift toward unambiguous digital displays.
Digital Test Kits absorb the bulk of installed capacity; Early Detection Kits are expanding most quickly.
End User:
Customer type determines channel economics and regulatory exposure, with direct-to-consumer models reducing intermediary margin extraction while elevating FTC advertising substantiation requirements.
- Women:The primary adoption segment encompasses home-use consumers seeking conception confirmation and fertility monitoring through self-directed health management. Demand concentrates in metropolitan healthcare corridors where pharmacy chain density supports impulse purchase availability, while younger demographics increasingly prefer online channels for privacy and automated replenishment.
- Online Retailers:E-commerce platforms capture recurring revenue through subscription models and bundling with fertility tracking applications, displacing traditional retail dominance among cohorts prioritizing discretion. FTC scrutiny of fertility app data monetization tightens substantiation requirements for algorithmic predictions in California and New York where state attorneys general coordinate enforcement.
- Clinics:Healthcare facilities utilizing professional-grade diagnostic formats with batch purchasing and inventory management requirements.
- Pharmacies:Retail pharmacy chains facing margin pressure from channel rotation toward direct-to-consumer infrastructure, responding with private-label digital formats and loyalty-program bundling in Texas and Florida markets.
Women represent the dominant volume segment; Online Retailers are climbing the fastest as channel rotation accelerates.
Distribution Channel:
Channel configuration directly determines customer acquisition economics and inventory velocity, with digital-native pathways reducing working capital requirements while demanding fulfillment infrastructure investment.
- Online Sales:Direct-to-consumer and platform-mediated transactions enable subscription replenishment and privacy-preserving purchase experiences. Younger demographics under 35 in metropolitan corridors drive displacement of drugstore dominance, with automated supply continuity capturing recurring engagement beyond single-test events.
- Drugstores:Pharmacy chain retail maintains volume leadership through established shelf presence and impulse purchase availability, though facing margin compression from channel rotation.
- Retail Stores:General merchandise retailers with health and beauty sections, experiencing traffic decline as consumer purchase behavior shifts toward digital channels.
- Supermarkets:Grocery-anchored health product sections with convenience-driven purchase occasions, limited by inventory breadth constraints compared to dedicated pharmacy formats.
Drugstores retain the largest share of throughput; Online Sales are gaining share fastest as demographic preferences shift.
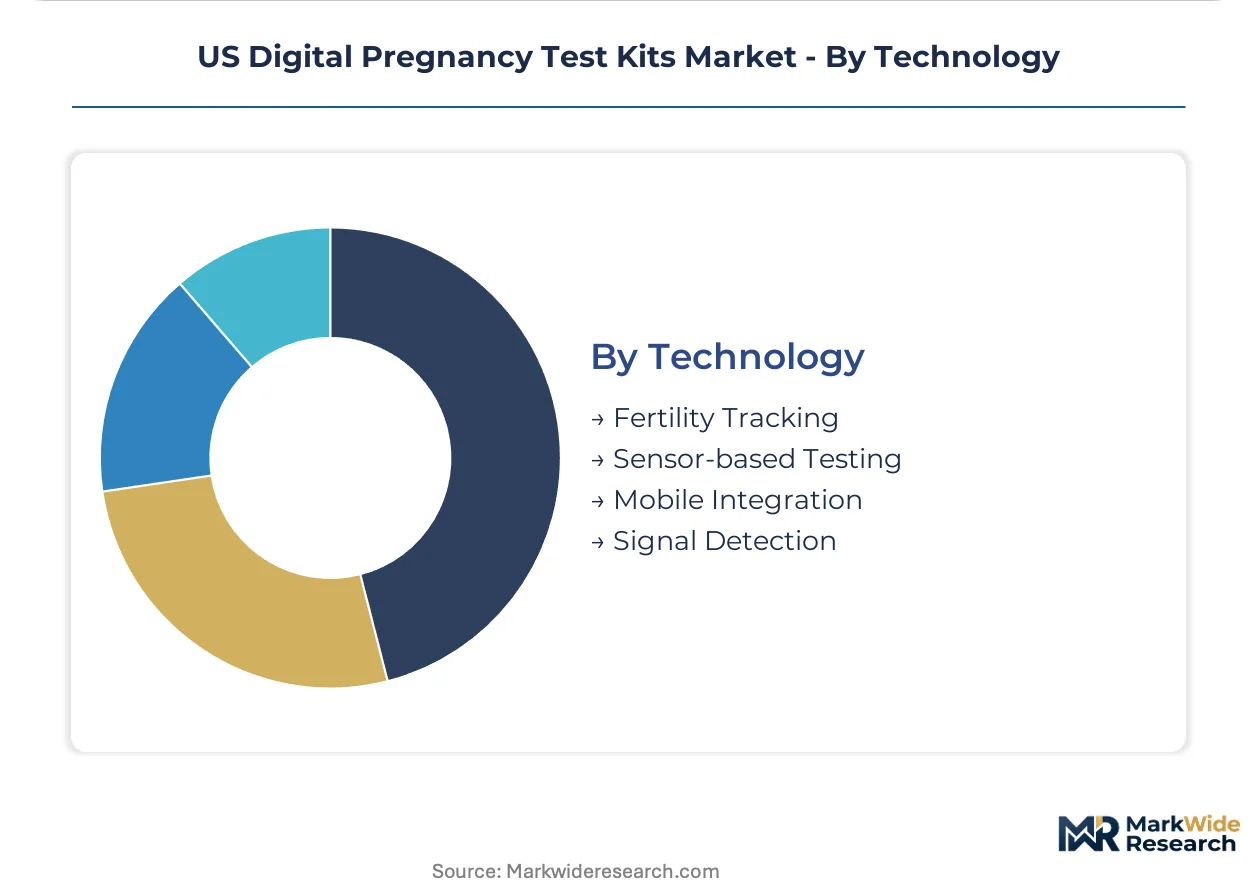
Technology:
Technology investments determine product roadmap differentiation and regulatory classification risk, with connected capabilities forcing FDA to clarify software-as-medical-device boundaries.
- Mobile Integration:Smartphone-connected test results integrate with cycle prediction algorithms and fertility tracking applications, creating recurring engagement beyond single-use diagnostics. Bluetooth-enabled cycle tracking electrifies product roadmaps as manufacturers compete for app engagement, while evolving FDA software guidance threatens reclassification as higher-risk devices.
- Sensor-based Testing:Capacitive hCG detection through electrical impedance rather than optical line interpretation compresses the price-performance gap with clinical laboratory immunoassays. Specialized electrochemistry talent scarcity constrains engineering capacity for emerging entrants developing premium positioning through accuracy claims.
- Fertility Tracking:Algorithmic cycle prediction derived from test result data, requiring clinical validation documentation under tightening FTC substantiation requirements.
- Signal Detection:Core lateral flow membrane chemistry with optical or electronic result interpretation, forming the baseline technology layer across product tiers.
Sensor-based Testing commands the deepest R&D investment; Mobile Integration is expanding most quickly as ecosystem integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in coastal and Sun Belt metropolitan corridors where pharmacy chain density, digital health literacy, and fertility-focused consumer demographics intersect most densely. The FDA's 510(k) clearance framework shapes commercialization timelines uniformly across sub-regions, while state-level enforcement coordination on health advertising substantiation creates compliance intensity variation.
California
San Francisco Bay Area and Los Angeles Basin clusters drive premium digital format adoption among tech-sector millennials seeking smartphone-connected fertility tracking. State Attorney General coordination with FTC on algorithmic health claims substantiation tightens compliance requirements for app-integrated test providers. San Diego's biotech corridor hosts contract monoclonal antibody manufacturers supplying detection chemistry to national kit assemblers.
Texas
Dallas-Fort Worth and Houston metropolitan areas sustain volume leadership through pharmacy chain impulse purchase availability and rapid population growth among family-forming demographics. State medical device waste disposal regulations under EPA delegation influence end-of-life labeling obligations for plastic housing components. Austin's emerging digital health startup ecosystem incubates subscription-based fertility platform ventures.
New York Metro
Greater New York City demand concentrates among privacy-seeking professionals under 35 migrating toward online replenishment channels. State-level coordination with federal FTC enforcement on fertility app data monetization creates substantiation documentation requirements for algorithmic cycle predictions. Long Island's precision manufacturing base supplies injection-molded plastic components to regional assembly operations.
Florida
Southeast Florida corridors exhibit strong pharmacy chain loyalty program engagement as retailers respond to channel rotation with private-label digital format bundling. State environmental regulations on medical device landfill disposal accelerate biodegradable housing material evaluation by national manufacturers. Tampa Bay's distribution infrastructure supports rapid inventory replenishment for direct-to-consumer fulfillment networks.
Pacific Northwest
Seattle and Portland metropolitan areas show elevated environmental sensitivity influencing biodegradable plastic housing preference signals. State procurement policies favoring sustainable medical device materials create pilot program opportunities for petroleum-polymer-reduced formats. Vancouver, Washington's electronics manufacturing cluster faces semiconductor allocation constraints affecting LCD module lead times for regional device assemblers.
US Digital Pregnancy Test Kits Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with established consumer health conglomerates commanding retail shelf presence while emerging entrants capture direct-to-consumer subscription volume. The market structure reflects moderate consolidation at the branded tier alongside fragmentation among private-label and regional suppliers. Three archetypes dominate: diversified consumer health conglomerates with broad distribution infrastructure, precision diagnostics specialists with sensor technology differentiation, and pharmaceutical-holding entities with vertical integration into bioreactor capacity. Competitive moves concentrate on subscription platform development and biodegradable material certification racing.
Among diversified consumer health conglomerates, Church & Dwight Co., Inc. and Procter & Gamble Co. anchor retail channel dominance through established drugstore and supermarket relationships. Swiss Precision Diagnostics GmbH occupies a position within the precision diagnostics specialist tier, exemplifying European-origin engineering focus on sensor-based accuracy claims. Gregory Pharmaceutical Holdings, Inc. represents pharmaceutical-holding archetype integration into diagnostic device assembly. These three named entities illustrate how geographic origin and corporate structure map to distinct competitive positioning vectors without prescribing specific strategic actions or market share figures.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Swiss Precision Diagnostics GmbH |
| Gregory Pharmaceutical Holdings, Inc. |
| Procter & Gamble Co. |
| Quidel Corporation |
| Sugentech, Inc. |
| Mankind Pharma |
| Prestige Consumer Healthcare Inc. |
| NTBIO Diagnostics Inc. |
| Others |
Value Network & Pricing Analysis
Captive bioreactor capacity for monoclonal antibody production anchors supply security for established manufacturers while simultaneously underwriting premium pricing power against contract-dependent challengers. This backward integration into hCG detection chemistry insulates incumbents from raw material volatility that compresses margins for economy-tier competitors sourcing through third-party suppliers.
Pricing Analysis
Volume leadership concentrates in economy-tier SKUs sold through pharmacy chains, while margin capture clusters in premium digital formats with Bluetooth connectivity and app integration. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification status, sensor accuracy claims, and mobile platform bundling. Cost compression in economy segments is intensifying because petroleum-derived plastic resin prices fluctuate with energy markets. Pharmacy chain buyers exhibit highest price sensitivity; direct-to-consumer subscribers under 35 demonstrate lowest sensitivity due to privacy premium willingness.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific electronics clusters disrupts LCD module procurement schedules for US-based device assemblers. Monoclonal antibody bioreactor capacity concentrates in Switzerland, Singapore, and California's San Diego corridor; lateral flow membrane substrates draw from specialized cellulose manufacturers in Germany and Japan. Single-source vulnerability in semiconductor foundry allocation for display controllers threatens production continuity. Distribution runs through pharmacy chain warehouses, direct-to-consumer fulfillment centers, and third-party logistics providers serving online subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
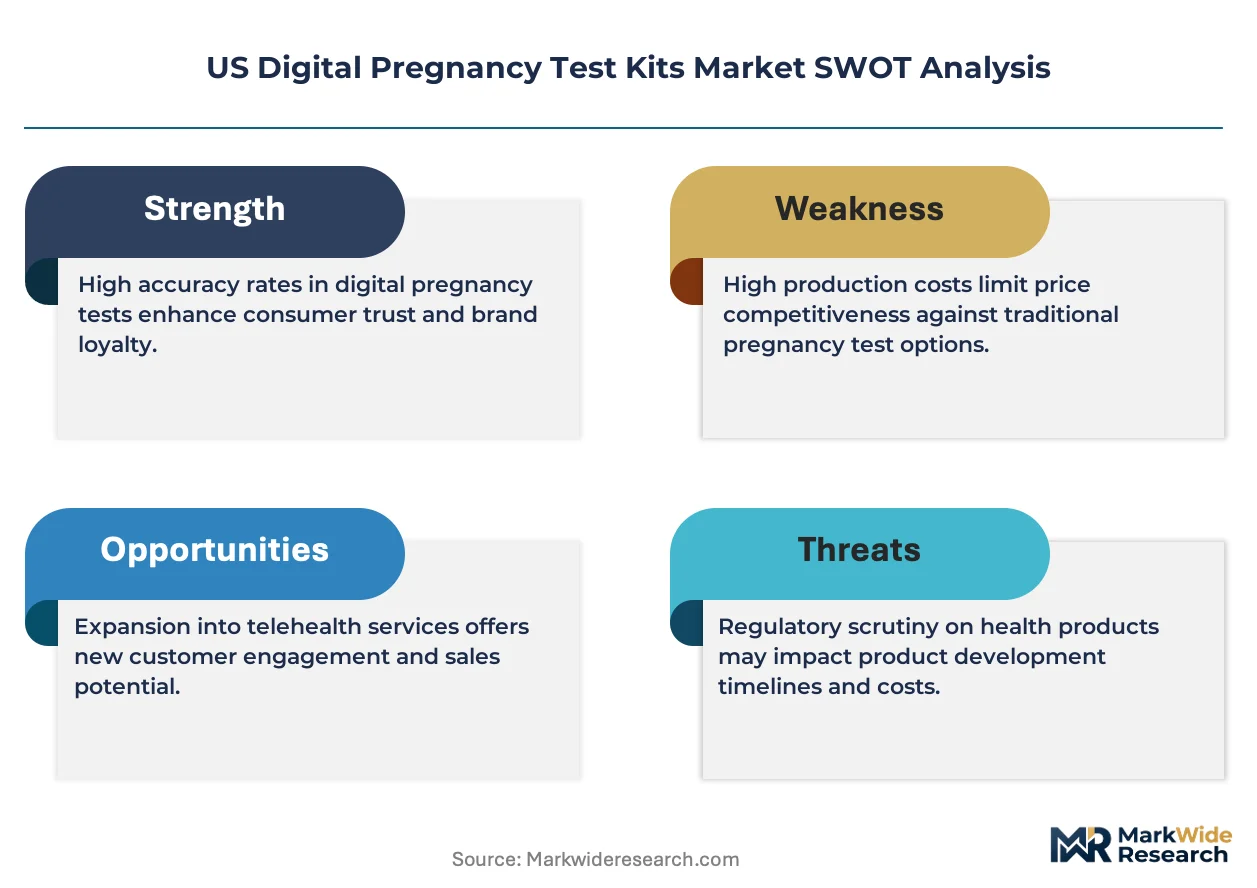
FDA 510(k) clearance requirements function as a cost-of-compliance moat, elevating substantiation overhead that filters out undercapitalized entrants while rewarding established players with cleared predicate devices and documented clinical validation.
For Market Incumbents: Deploy subscription platform infrastructure to capture recurring revenue from fertility-tracking demographics before channel rotation accelerates. Consolidate monoclonal antibody supply through captive bioreactor investments or long-term offtake agreements with San Diego contract manufacturers. Sensor calibration expertise scarcity constrains emerging rivals developing capacitive hCG detection formats. For New Entrants and Emerging Players: Capture biodegradable housing certification first-mover advantage as EPA medical device waste regulations tighten disposal labeling obligations. Target Pacific Northwest metropolitan corridors where environmental sensitivity drives sustainable material preference signals. Direct-to-consumer launch with privacy-preserving packaging and automated replenishment bypasses pharmacy chain slotting fee barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in precision diagnostics specialists with sensor-based accuracy claims and established FDA 510(k) predicate devices. Long-term viability hinges on software-as-medical-device boundary clarity from FDA guidance evolution. Watch for FTC enforcement coordination with state attorneys general on fertility app data monetization as inflection indicator for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Early clearance capture secures predicate device status for line extensions before guidance tightens. |
| Biodegradable Housing Certification | EPA disposal compliance advantage positions brands for state procurement preference programs. |
| Subscription Platform Development | Recurring revenue models displace drugstore impulse economics among privacy-seeking millennials. |
| Sensor Calibration Talent Acquisition | Electrochemistry expertise scarcity limits competitor replication of capacitive hCG accuracy claims. |
| Direct-to-Consumer Channel Expansion | Automated replenishment bypasses pharmacy chain margin extraction and slotting fee structures. |
Research Methodology
FDA 510(k) premarket notification database, EPA medical device waste stream regulations, and pharmacy chain procurement records formed the secondary backbone for regulatory and channel analysis. Primary interviews with diagnostic device regulatory affairs leads, GPO contracts managers, biomedical engineers at fertility clinics, and brand managers at consumer health conglomerates validated demand assumptions and pricing dynamics. Bottom-up unit economics modeling and top-down category spend analysis triangulated market sizing across the analysis window.
Historical trendline analysis of lateral flow diagnostic pricing and digital health device adoption patterns informed projection framework construction. Segmentation modeling spanned product format tiers, distribution channel economics, technology integration levels, and metropolitan corridor demand density. CAGRs derived from regression analysis of volume trajectories adjusted for FDA clearance timeline variability and semiconductor allocation constraints affecting LCD module supply.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software-as-medical-device reclassification guidance and FTC fertility claim substantiation enforcement intensity. Forecasts reflect documented assumptions regarding bioreactor capacity expansion and biodegradable material cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Pulmonology Lasers Market
Medical Devices
Global Glucometer Market
Medical Devices
Pathology Devices Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Aortic Valve Replacement Devices Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Asia-Pacific Digital Dentistry Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Europe Otoscope Market
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Micro-Bypass Systems Market
Medical Devices
United States Drug Delivery Devices Market