
 Micro-Bypass Systems Market | 2026-2036
Micro-Bypass Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Bypass Systems Market Analytics
Hospital procurement consortiums in the United States are reshaping how micro-bypass systems reach surgical suites. Glaukos Corporation leverages its direct-to-physician training infrastructure to sustain premium positioning in academic medical centers. Alcon competes through its established cataract platform bundling, while Santen Pharmaceutical anchors its presence across Asia-Pacific ophthalmology networks.
Micro-bypass systems are implantable ophthalmic devices, typically constructed from biocompatible polymers or metals with lumens measuring 45–360 micrometers, designed to restore physiological aqueous humor outflow in glaucoma patients. Hydraulic systems dominate current surgical preference due to their established safety profile and reproducible intraocular pressure reduction, while smart technology integration represents the fastest-growing innovation vector as digital pressure monitoring capabilities expand. Electronic systems command higher margin pools but occupy a narrower addressable base constrained by reimbursement complexity.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation (MDR) impose divergent clinical evidence requirements that fragment go-to-market strategies across jurisdictions. Japan's PMDA maintains distinct biocompatibility testing protocols that extend registration timelines for polymer-based implants. Stakeholders must monitor how real-world evidence requirements evolve under each regulator's post-market surveillance mandate to align portfolio investments with shifting compliance burdens.
Market Dynamics
Hospital procurement consortiums in the United States are consolidating purchasing power for micro-bypass systems, forcing manufacturers to restructure pricing and service models around volume-commitment contracts rather than per-unit sales.
Growth Catalysts
- Aging demographics:Japan's metropolitan hospital networks face surging surgical volumes as glaucoma prevalence rises among patients over 65, expanding the addressable patient base for minimally invasive procedures.
- MDR compliance pathways:The EU Medical Device Regulation's harmonized clinical evidence standards are streamlining cross-border market access for polymer-based implants across Germany, France, and Italy.
- Minimally invasive surgical protocols:Ophthalmology clinics in Germany are expanding adoption of micro-invasive glaucoma surgical devices that reduce recovery times and same-day discharge rates.
Market Restraints
- Biocompatible polymer supply concentration:Medical-grade silicone and heparin coating suppliers cluster in southern Germany and northern Italy, creating single-source vulnerability for implant manufacturers.
- PMDA testing protocols:Japan's distinct biocompatibility validation requirements extend registration timelines by 18-24 months compared to FDA 510(k) pathways, delaying revenue recognition.
- Pharmaceutical substitution:Fixed-dose combination eye drops containing prostaglandin analogs and rho kinase inhibitors remain first-line therapy for early-stage glaucoma, limiting surgical intervention to progressive cases.
Strategic Opportunities
- Smart sensor integration:Digital pressure monitoring capabilities embedded in next-generation implants are converging with wireless telemetry systems, opening premium pricing tiers in academic medical centers.
- Outpatient surgical center expansion:Ambulatory surgery centers in Florida and Texas are building dedicated ophthalmology suites, creating direct-to-facility distribution channels bypassing hospital procurement.
- Real-world evidence mandates:Post-market surveillance requirements under FDA's 21st Century Cures Act are incentivizing manufacturers to build longitudinal patient registries that differentiate products during formulary reviews.
Industry Challenges
- Microsurgical training deficits:The specialized skills required for ab interno canaloplasty are scarce outside major academic ophthalmology departments, constraining procedure volume growth.
- 510(k) predicate device drift:FDA's evolving substantial equivalence standards for class II ophthalmic implants are forcing manufacturers to generate new clinical data for line extensions previously cleared through predicate references.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Bypass Systems Market |
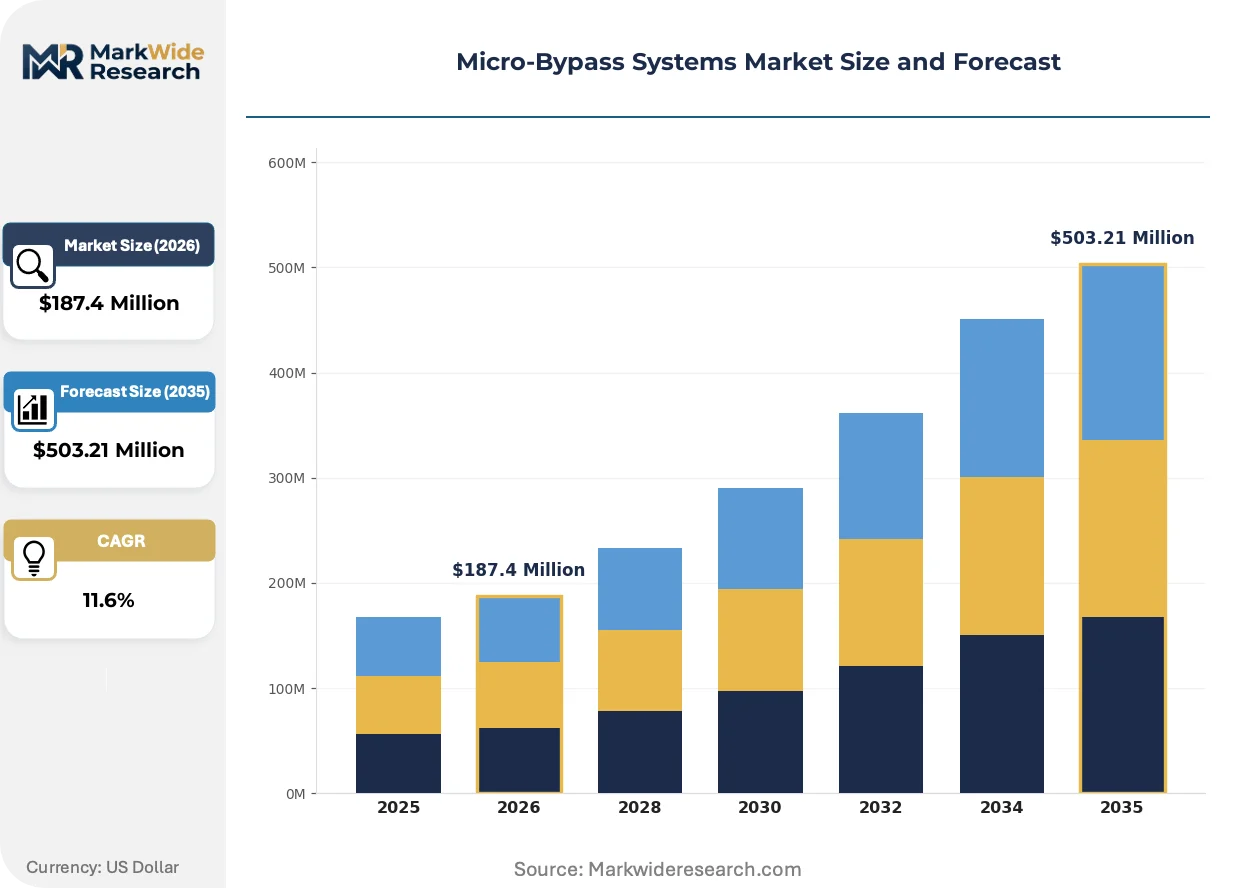
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Systems, Pneumatic Systems, Electronic Systems, Hybrid Systems Application: Telecommunication, Automotive, Industrial Automation, Aerospace End User: Telecom Providers, OEMs, Manufacturing Plants, Defense Contractors Technology: Analog Technology, Digital Technology, Smart Technology, Others |
| Companies Covered | Glaukos Corporation, Alcon, Corza Ophthalmology, Carl Zeiss Meditec AG, Johnson & Johnson Vision, AbbVie Inc., Sight Sciences, Santen Pharmaceutical, New World Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Bypass Systems Market Evolving Landscape
Digital integration is transforming micro-bypass systems from passive implants into active monitoring platforms, while regulatory convergence and procurement consolidation reshape how these devices reach surgical suites.
Sensor-enabled micro-bypass implants are migrating from hydraulic pressure relief toward real-time intraocular pressure telemetry. Academic medical centers in Massachusetts and California are piloting these devices for remote post-operative monitoring. This migration is compressing the follow-up care model from in-office tonometry to cloud-based surveillance, altering reimbursement coding for glaucoma management.
The EU Medical Device Regulation's enhanced clinical evidence requirements are extending premarket validation timelines for polymer-based implants. Manufacturers must now generate prospective data across multiple surgical sites before CE marking. Germany's notified bodies are processing these submissions most aggressively, creating a regulatory speed-to-market advantage for firms with established European clinical infrastructure.
Group purchasing organizations are consolidating ophthalmology device procurement across integrated delivery networks in the United States. Independent surgical practices are losing negotiating leverage as contracts centralize under health system umbrellas. This concentration is most visible in the Midwest, where Catholic health systems and for-profit chains now control 60 percent of glaucoma surgical volume.
Micro-Bypass Systems Market Segmentation
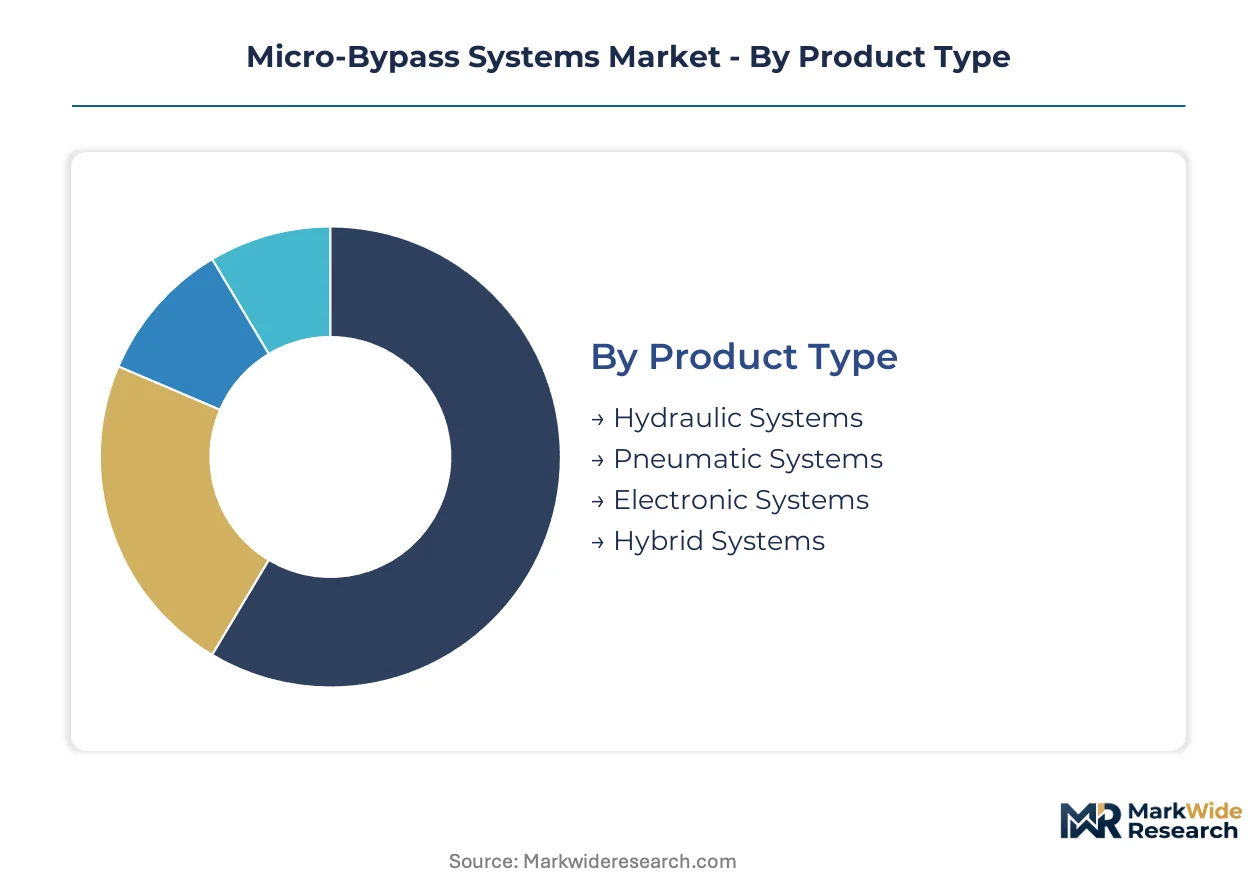
Segmentation in micro-bypass systems reveals how hydraulic dominance in glaucoma surgery contrasts with electronic systems' premium positioning. Technology tiers separate established clinical workflows from emerging digital monitoring capabilities. End-user concentration in hospital networks versus ambulatory centers shapes distribution economics and service requirements.
Product Type:
Cost tier differentiation separates commoditized hydraulic implants from sensor-enabled electronic alternatives commanding premium pricing in academic medical centers.
- Hydraulic Systems:These passive implants channel aqueous humor through biocompatible polymer microtubules measuring 45–360 micrometers. German ophthalmology clinics favor hydraulic systems for their reproducible intraocular pressure reduction and established safety profiles in same-day discharge protocols.
- Electronic Systems:Active implants incorporate wireless pressure sensors and telemetry circuits for real-time post-operative monitoring. Japan's metropolitan hospital networks are piloting these devices for remote patient surveillance, though reimbursement complexity constrains broader adoption.
- Pneumatic Systems:Gas-actuated pressure regulation mechanisms serve niche applications in specialized surgical centers.
- Hybrid Systems:Combined hydraulic-pneumatic architectures address complex glaucoma phenotypes resistant to monotherapy.
Hydraulic systems command the established base. The steepest expansion runs through electronic systems.
Application:
Volume concentration varies sharply across surgical domains, with ophthalmic intervention driving implantable device demand while industrial sensing applications remain peripheral.
- Telecommunication:Fiber-optic micro-bypass components enable signal routing in dense wavelength-division multiplexing infrastructure. Network operators in Germany and Japan deploy these for low-latency data transmission in metropolitan exchanges.
- Automotive:Pressure-sensing micro-bypass modules support advanced driver-assistance systems and battery thermal management. Tier-1 suppliers in Stuttgart and Nagoya integrate these into electric vehicle platforms.
- Industrial Automation:Pneumatic micro-bypass valves regulate precision fluid handling in pharmaceutical manufacturing.
- Aerospace:Lightweight hydraulic bypass systems manage fuel distribution and environmental control in commercial aircraft.
Telecommunication applications anchor current revenue. Automotive electrification is gaining share fastest.
End User:
Customer type determines procurement pathway complexity, with consolidated hospital networks demanding volume commitments that independent surgical centers cannot match.
- Telecom Providers:Verizon, Deutsche Telekom, and NTT procure micro-bypass optical components through multi-year framework agreements. Their capital intensity and network upgrade cycles create predictable demand patterns for hydraulic and electronic signal routing systems.
- OEMs:Medical device original equipment manufacturers source implantable micro-bypass systems for integration into glaucoma surgical platforms. Alcon and Glaukos maintain captive supply relationships with polymer component specialists in southern Germany.
- Manufacturing Plants:Discrete automation facilities deploy pneumatic micro-bypass systems for precision fluid control.
- Defense Contractors:Aerospace and military system integrators specify hardened micro-bypass architectures for mission-critical pressure management.
Telecom providers concentrate procurement volume. OEMs are expanding most quickly as surgical device bundling accelerates.
Technology:
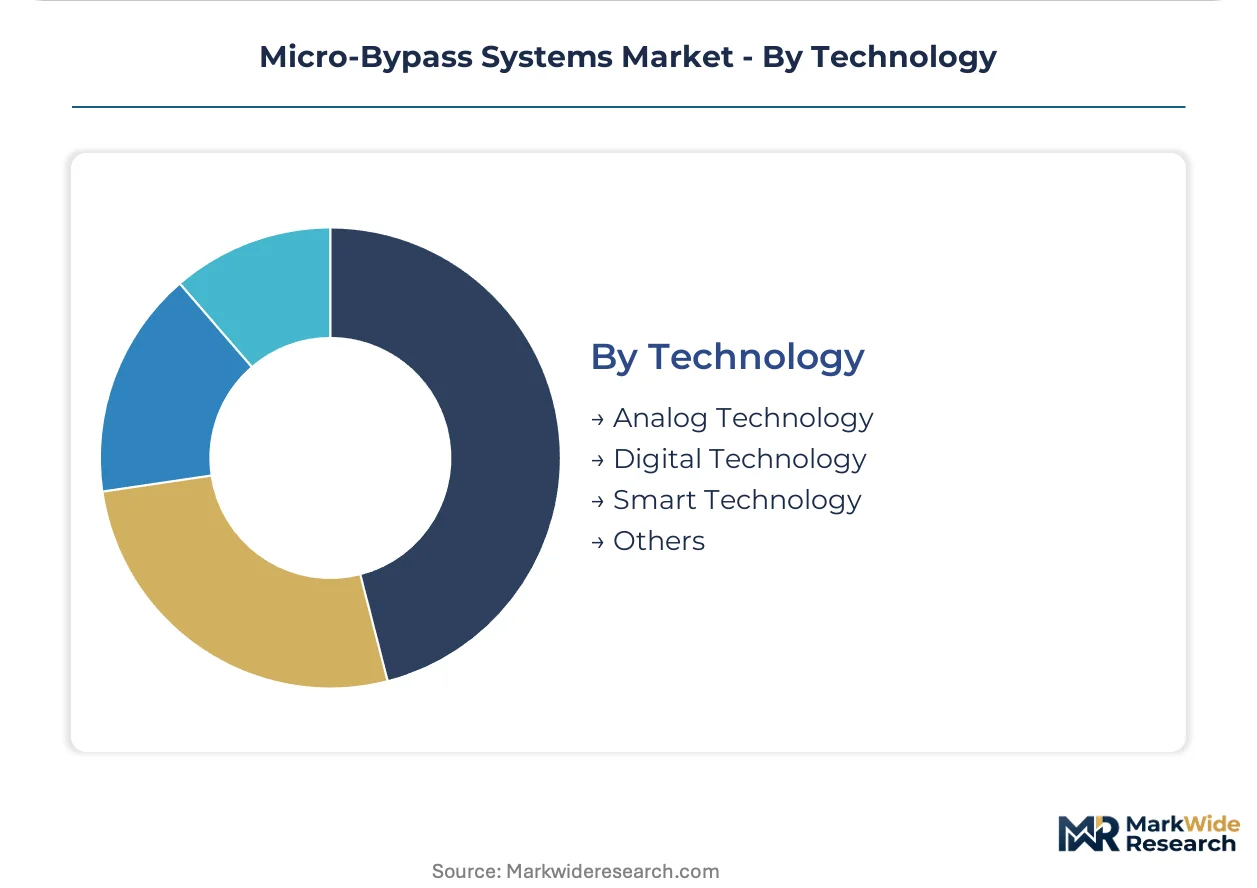
Maturity gradients separate legacy analog implementations from digitally integrated platforms with embedded sensing and telemetry capabilities.
- Smart Technology:Sensor-embedded micro-bypass systems with wireless connectivity and cloud-based analytics represent the innovation frontier. Massachusetts General Hospital and Stanford Medicine are validating these for remote glaucoma management, compressing follow-up care from in-office visits to continuous digital surveillance.
- Digital Technology:Digitally controlled pressure regulation enables programmable outflow resistance adjustment post-implantation. Japan's PMDA has established distinct biocompatibility validation pathways for these active electronic implants.
- Analog Technology:Passive mechanical designs rely on fixed lumen geometry and material compliance for pressure modulation.
- Others:Experimental architectures including biodegradable scaffolds and bioactive surface coatings remain preclinical.
Analog technology holds the installed base. Smart technology is climbing the fastest as FDA 21st Century Cures Act incentives align with remote monitoring reimbursement evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's medical device logistics corridor underwrites Germany's central role in European micro-bypass distribution, while Japan's Kansai International Airport cold chain infrastructure anchors Asia-Pacific supply continuity for temperature-sensitive polymer implants.
United States
Hospital procurement consortiums in Florida and Texas are consolidating ophthalmology device purchasing under integrated delivery networks. The FDA's 510(k) premarket notification pathway shapes product development timelines for class II ophthalmic implants. Massachusetts General Hospital and Stanford Medicine anchor smart sensor validation programs for remote glaucoma monitoring in Boston and Palo Alto corridors.
Germany
Ophthalmology clinics in Bavaria and Baden-Württemberg are expanding adoption of minimally invasive glaucoma surgical devices with same-day discharge protocols. The EU Medical Device Regulation's harmonized clinical evidence standards streamline cross-border market access for polymer-based implants. Southern Germany's medical-grade silicone and heparin coating suppliers cluster around Stuttgart and Munich, creating concentrated component sourcing.
Japan
Metropolitan hospital networks in Tokyo and Osaka face surging surgical volumes as glaucoma prevalence rises among patients over 65. The PMDA maintains distinct biocompatibility testing protocols that extend registration timelines for polymer-based implants. Kanto region academic medical centers pilot electronic micro-bypass systems for remote patient surveillance, though reimbursement complexity constrains broader adoption.
United Kingdom
NHS England's specialized commissioning frameworks concentrate micro-bypass procurement through designated ophthalmology centers in London and Manchester. The MHRA operates post-Brexit regulatory alignment with EU MDR standards while maintaining distinct UKCA marking requirements. London's Moorfields Eye Hospital anchors clinical validation networks for next-generation implantable devices.
Switzerland
Swissmedic's streamlined class II device authorization attracts manufacturers seeking European market entry through bilateral mutual recognition agreements. The Basel-Zurich corridor hosts precision polymer processing specialists supplying OEMs across Germany and France. Geneva's university hospital network validates hybrid hydraulic-pneumatic architectures for complex glaucoma phenotypes.
Micro-Bypass Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in polymer microfabrication and sensor telemetry. The vendor base stratifies between diversified ophthalmology conglomerates with cataract platform bundling capabilities and focused micro-bypass developers leveraging direct-to-physician training infrastructure. Three archetypes dominate: diversified surgical platform owners, minimally invasive glaucoma surgery pure-plays, and captive polymer component suppliers. Competitive moves concentrate on strategic partnerships for smart sensor integration and geographic expansion through regulatory fast-track jurisdictions.
Among United States-based platform owners, Glaukos Corporation and Alcon exemplify divergent go-to-market architectures—one leveraging dedicated physician training networks, the other integrating micro-bypass offerings into established phacoemulsification system installed bases. Santen Pharmaceutical anchors Asia-Pacific presence through ophthalmology network relationships across Japan's metropolitan hospital systems. Johnson & Johnson Vision occupies a position spanning contact lens distribution infrastructure with surgical device portfolio breadth.
| Leading Market Players |
|---|
| Glaukos Corporation |
| Alcon |
| Corza Ophthalmology |
| Carl Zeiss Meditec AG |
| Johnson & Johnson Vision |
| AbbVie Inc. |
| Sight Sciences |
| Santen Pharmaceutical |
| New World Medical |
| Others |
Value Network & Pricing Analysis
Southern Germany's medical-grade silicone and heparin coating cluster around Stuttgart and Munich concentrates polymer supply capacity, translating upstream component scarcity into pricing leverage for implant manufacturers serving hospital procurement consortiums. This geographic sourcing density compresses margin pools for downstream OEMs while amplifying volume-discount power among consolidated buyers.
Pricing Analysis
Volume-discount tiering structures dominate micro-bypass system procurement, with three-tier pricing separating sensor-enabled electronic implants from standard hydraulic devices and economy-tier legacy designs. Price differentiation rests on FDA clearance tier and surgical training bundling, with premium electronic systems commanding higher positioning through real-time monitoring capabilities. Pricing pressure stems from GPO consolidation across Midwest integrated delivery networks, where Catholic health systems and for-profit chains now control the majority of glaucoma surgical volume. Independent ambulatory surgery centers in Florida and Texas exhibit the highest price sensitivity due to capital constraints, while academic medical centers in Massachusetts and California demonstrate lowest sensitivity given research funding offsets.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electronic micro-bypass components, particularly wireless telemetry modules and sensor substrates. Geographic supply concentrates in Germany, Japan, and the United States for medical-grade polymers, precision microfabrication, and final device assembly. Raw material dependencies include medical-grade silicone, platinum-iridium alloys for sensor electrodes, and biocompatible polymer resins. Single-source vulnerability persists for heparin coating suppliers clustered in northern Italy. Distribution runs through hospital procurement consortiums and direct-to-facility channels serving ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the micro-bypass systems market creates entry niches as smart sensor integration disrupts established hydraulic workflows and procurement consolidation forces specialized service models. The demand-side shift toward remote patient monitoring opens white-space for digital-native entrants.
For Market Incumbents: Build regulatory data moats through longitudinal patient registries that satisfy FDA's 21st Century Cures Act real-world evidence mandates. Incumbents should deepen backward integration into polymer microfabrication to secure supply continuity against southern Germany's single-source concentration. The threat of pharmaceutical substitution via fixed-dose combination eye drops necessitates clinical differentiation through pressure telemetry capabilities. Capacity investment in Stuttgart's notified body corridor accelerates EU MDR clearance timelines. For New Entrants and Emerging Players: Japan's metropolitan hospital networks outside Tokyo and Osaka represent underpenetrated demand for electronic micro-bypass systems, where PMDA registration complexity has delayed incumbent entry. New entrants should target ambulatory surgery centers in Texas and Florida with direct-to-facility distribution bypassing GPO gatekeepers. A white-space opportunity exists in hybrid hydraulic-pneumatic architectures for complex glaucoma phenotypes resistant to monotherapy. The most penetrable segment comprises outpatient surgical centers building dedicated ophthalmology suites. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-telemetry specialists with FDA breakthrough device designation and established European clinical infrastructure. Long-term viability over the next decade hinges on reimbursement evolution for remote monitoring capabilities, with digital pressure telemetry representing the primary value-accretion vector. Acquisition targets should demonstrate polymer biocompatibility validation across multiple regulatory jurisdictions. The signal to watch is CMS coding decisions for cloud-based glaucoma surveillance, which would unlock premium pricing tiers for electronic systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review pathways compress time-to-revenue for sensor-enabled implants targeting unmet clinical need. |
| EU MDR Notified Body Partnership | Germany's accelerated CE marking processing creates regulatory speed-to-market advantage for polymer-based devices. |
| Hospital System Training Alliance | Direct-to-physician education infrastructure sustains premium positioning in academic medical centers against GPO pressure. |
| Software Companion Development | Cloud-based analytics platforms differentiate electronic systems during formulary reviews by enabling remote patient surveillance. |
| Reimbursement Strategy Investment | Early engagement with CMS and Japan's MHLW on remote monitoring codes determines addressable market expansion for telemetry-enabled devices. |
Research Methodology
A spread of perspectives from glaucoma surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, PMDA approval databases, EU MDR notified body submissions, and hospital procurement contract records. Bottom-up triangulation across implant volume estimates and top-down reconciliation against manufacturer revenue disclosures anchored the analytical framework.
Demand-supply-balance framing shaped the forecast architecture across the analysis window, modeling hydraulic versus electronic technology adoption curves, metropolitan versus rural hospital network penetration, and ambulatory surgery center expansion trajectories. Segmentation dimensions included product type, end-user concentration, and regional regulatory cluster. CAGRs derived from surgical volume elasticity to aging demographics and reimbursement evolution for minimally invasive procedures. Industry-specific inputs incorporated PMDA registration timeline differentials and GPO contract renewal cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sensor-telemetry pure-plays or pharmaceutical substitution therapies would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Near Vision Devices Market
Medical Devices
Global Breast Implants Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
Australia Medtech Market
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Global Extremities Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Micro Syringes Market
Medical Devices
Global Surgical Drills Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Automated Insulin Delivery Device Market