
 Digital Pregnancy Test Kits Market | 2026-2036
Digital Pregnancy Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Pregnancy Test Kits Market Analysis
Direct-to-consumer home testing is hardening as the dominant demand channel for digital pregnancy test kits, pulling volume away from clinical settings. Abbott leverages its diagnostics infrastructure to sustain broad retail shelf presence across North America and Europe. SPD Swiss Precision Diagnostics GmbH anchors premium positioning through the Clearblue brand, while Wondfo competes aggressively on manufacturing scale in Asia-Pacific markets.
Digital pregnancy test kits are electrochemical or optical biosensor devices that detect human chorionic gonadotropin (hCG) in urine samples at thresholds typically between 10 and 25 mIU/mL, displaying results through liquid crystal or OLED screens rather than chromatic lines. Their primary purpose is to eliminate user interpretation error while providing gestational timing estimates through algorithmic hormone level analysis. Midstream formats dominate unit volume due to ergonomic sampling design, though Bluetooth-connected variants represent the fastest-growing feature segment as smartphone integration enables cycle tracking and telehealth handoffs. Distribution through drugstores and online channels captures the deepest margin pools, while hospital procurement operates on fundamentally different volume-contracting terms.
FDA 510(k) clearance requirements and CE marking under the EU In Vitro Diagnostic Regulation shape product development timelines and market access barriers for manufacturers seeking multi-jurisdiction distribution. ISO 13485 quality management certification functions as a baseline qualifier for contract manufacturing relationships with major brands. Stakeholders must monitor evolving data privacy frameworks as connected devices transmit reproductive health information across jurisdictions with divergent personal data protections.
Market Dynamics
Connected health infrastructure is compressing the traditional diagnostic value chain, pulling pregnancy testing from clinical settings into app-integrated home environments where data continuity replaces single-use transactions.
Growth Catalysts
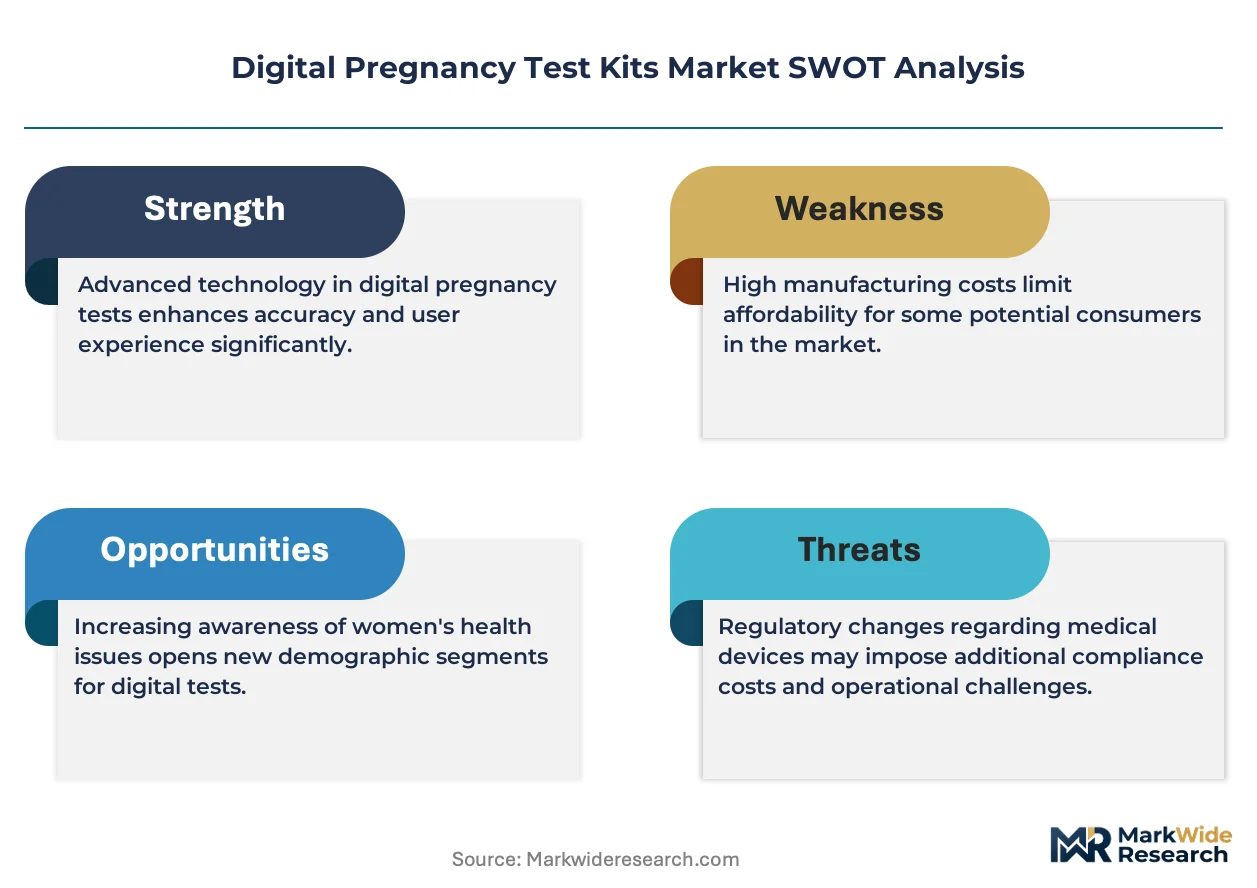
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for predicate-based digital diagnostics reduce time-to-market for algorithm-enhanced hCG detection devices.
- Telehealth handoff protocols:Bluetooth-enabled test kits feed directly into remote consultation platforms, embedding pregnancy testing within broader reproductive health workflows.
- Gesture-based sampling ergonomics:Midstream form factor innovations reduce user error rates compared to traditional strip-based alternatives.
Market Restraints
- Optical biosensor component concentration:CMOS image sensor supply chains cluster in East Asian foundries, creating single-source vulnerability for OLED display integration.
- EU In Vitro Diagnostic Regulation compliance costs:MDR technical documentation requirements impose disproportionate burdens on sub-$20 consumer diagnostic categories.
- Chromatographic strip substitution:Low-cost lateral flow devices retain price-sensitive segments where digital readouts offer marginal perceived value.
Strategic Opportunities
- Cycle tracking ecosystem integration:Fertility app partnerships transform pregnancy tests into recurring data subscription touchpoints beyond single-use hardware margins.
- German pharmacy channel digitization:EU-wide e-prescription frameworks enable direct-to-consumer telehealth bundling in Europe's largest reimbursed diagnostic market.
- hCG quantification algorithms:Machine learning on hormone progression curves opens gestational dating services adjacent to binary positive/negative results.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified quality management certification bodies face backlogs extending device launch timelines by 6-12 months.
- Cross-border data governance fragmentation:HIPAA, GDPR, and China's Personal Information Protection Law impose conflicting reproductive health data localization requirements on connected device architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Pregnancy Test Kits Market |
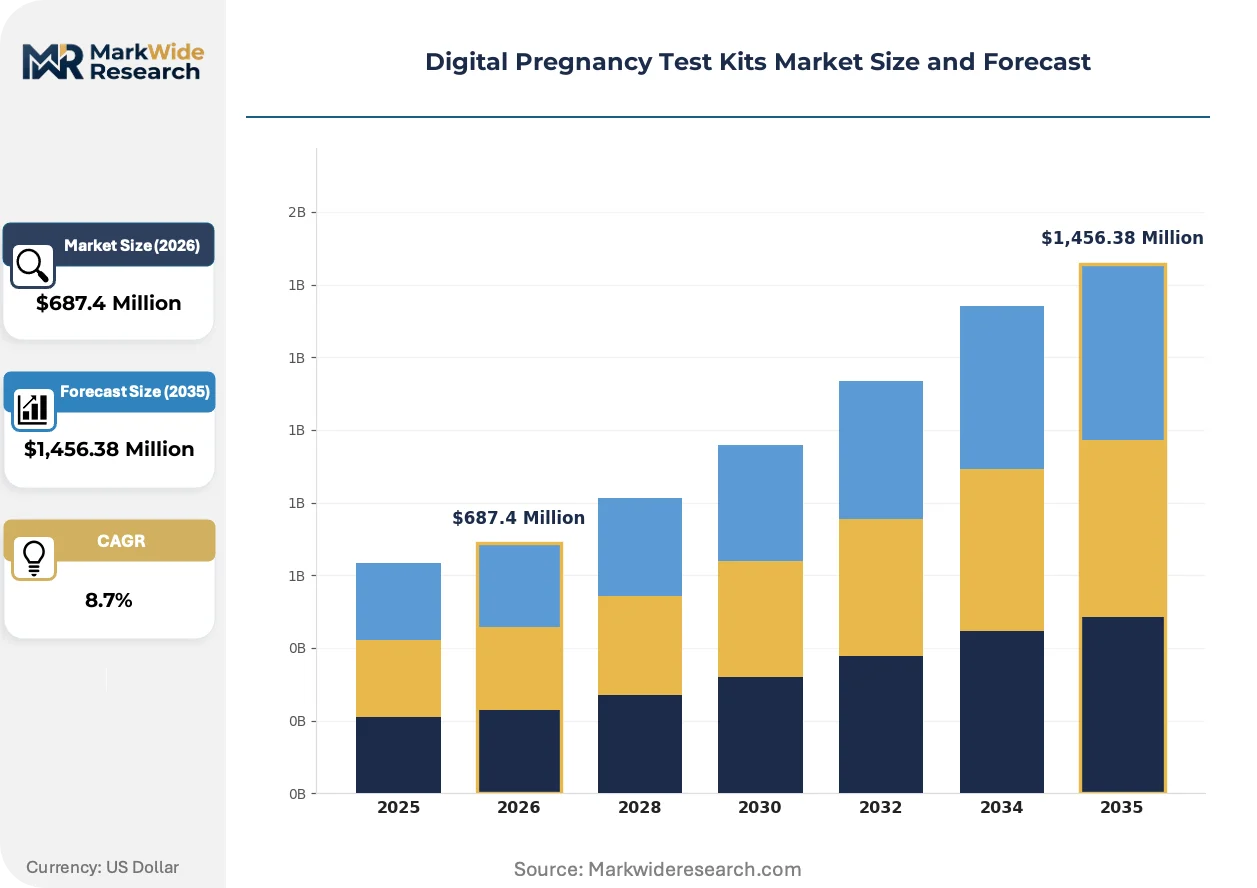
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,456.38 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Midstream, Cassette, Digital, Strip End User: Home Users, Clinics, Hospitals, Pharmacies Distribution Channel: Online, Retail, Drugstores, Supermarkets Feature: Bluetooth Connectivity, Digital Display, Accuracy, Speed |
| Companies Covered | Abbott, bioMérieux, SPD Swiss Precision Diagnostics GmbH, Clearblue, Wondfo, Church & Dwight, Procter & Gamble, Roche Diagnostics, QuidelOrtho, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Pregnancy Test Kits Market Emerging Trajectories
Electrochemical sensing architectures and smartphone-native health platforms are collapsing the traditional boundaries between consumer diagnostics and clinical laboratory information systems.
Printed electrochemical electrodes is electrifying cost structures in digital pregnancy test manufacturing. These flexible sensor substrates replace discrete optical components with thin-film chemistry deposited directly onto plastic cartridges. Contract manufacturers in Shenzhen and Seoul are adopting roll-to-roll electrode printing to serve private-label brands. This technology is electrifying entry barriers, enabling mid-tier competitors to match Abbott's hardware specifications at 40% lower bill-of-materials.
REACH substance restrictions on phthalates and bisphenol-A are forcing material transitions across European-bound device packaging. Manufacturers must validate alternative plasticizers for urine collection wands and test strip housings under shortened transition deadlines. German and French notified bodies are prioritizing biocompatibility assessments for these reformulated polymers, creating temporary bottlenecks in CE marking throughput for 2024-2025 product cycles.
Subscription-based fertility monitoring is displacing episodic pregnancy test purchasing among urban millennial demographics. Monthly hardware-and-app bundles from direct-to-consumer brands capture lifetime value across conception attempts rather than single-transaction margins. This pattern concentrates in US coastal metropolitan markets where employer-sponsored fertility benefits normalize recurring diagnostic spending.
Digital Pregnancy Test Kits Market Segmentation
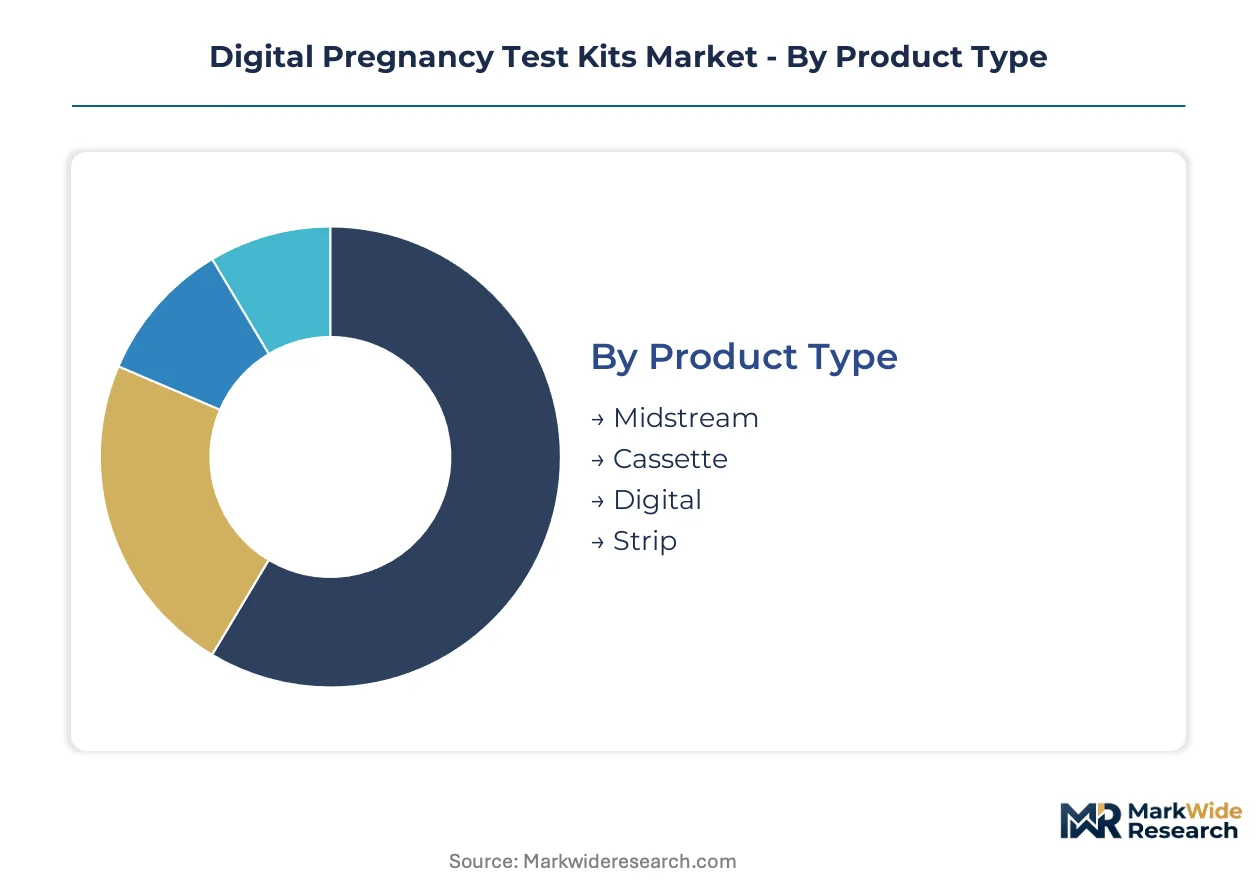
Segmentation in digital pregnancy test kits reveals how hardware specifications, user environments, and channel economics create distinct margin pools. Each axis exposes different competitive dynamics, from electrochemical sensor architectures to telehealth integration workflows.
Product Type:
Form factor engineering determines sampling ergonomics, manufacturing complexity, and retail price positioning across the value chain.
- Midstream:Ergonomic wand design integrates absorbent tip, reaction chamber, and digital display in a single handheld unit. Home users in the United States and Germany favor this format for reduced contamination risk during urine collection. FDA 510(k) predicates for midstream devices streamline clearance timelines for algorithm-enhanced variants.
- Digital:Electrochemical biosensors with liquid crystal or OLED readouts eliminate chromatic line interpretation errors. Demand concentrates among first-time pregnancy testers seeking gestational timing estimates through hCG quantification algorithms.
- Cassette:Dropper-based sample application onto exposed test strips suits clinical batch processing environments. Lower unit economics appeal to hospital procurement contracting.
- Strip:Bare sensor format without integrated housing targets price-sensitive markets where digital readouts offer marginal perceived value. Chromatographic lateral flow chemistry dominates this tier.
Midstream leads on scale; digital leads on momentum.
End User:
User setting dictates accuracy requirements, purchasing frequency, and data connectivity expectations.
- Home Users:Direct-to-consumer testing environments demand smartphone integration, discrete packaging, and app-based cycle tracking. Bluetooth-enabled kits feed reproductive health data into fertility platforms.
- Clinics:Point-of-care settings prioritize batch consistency and electronic health record compatibility over consumer-oriented features. CE marking under EU MDR shapes procurement specifications.
- Hospitals:High-volume central laboratory operations require quantitative hCG reporting with calibration traceability. Volume-contracting terms differ fundamentally from retail margin structures.
- Pharmacies:German pharmacy digitization enables telehealth bundling where reimbursed diagnostic workflows intersect with over-the-counter accessibility.
Home users command volume concentration; pharmacies are climbing the fastest on channel innovation.
Distribution Channel:
Channel selection determines margin capture, brand control, and customer relationship continuity.
- Online:Direct-to-consumer platforms enable subscription-based fertility monitoring bundles. Monthly hardware-and-app packages transform episodic pregnancy testing into recurring revenue streams.
- Retail:Drugstore and supermarket shelf presence requires broad retail infrastructure. Abbott leverages diagnostics scale to sustain North American and European distribution.
- Drugstores:Pharmacy chains in Germany and France combine diagnostic sales with professional consultation access. REACH substance restrictions on packaging materials complicate pan-European supply.
- Supermarkets:Mass-market placement competes on price visibility. Private-label brands exploit roll-to-roll electrode printing cost advantages from Shenzhen contract manufacturers.
Online channels gain share fastest; retail maintains absolute volume leadership.
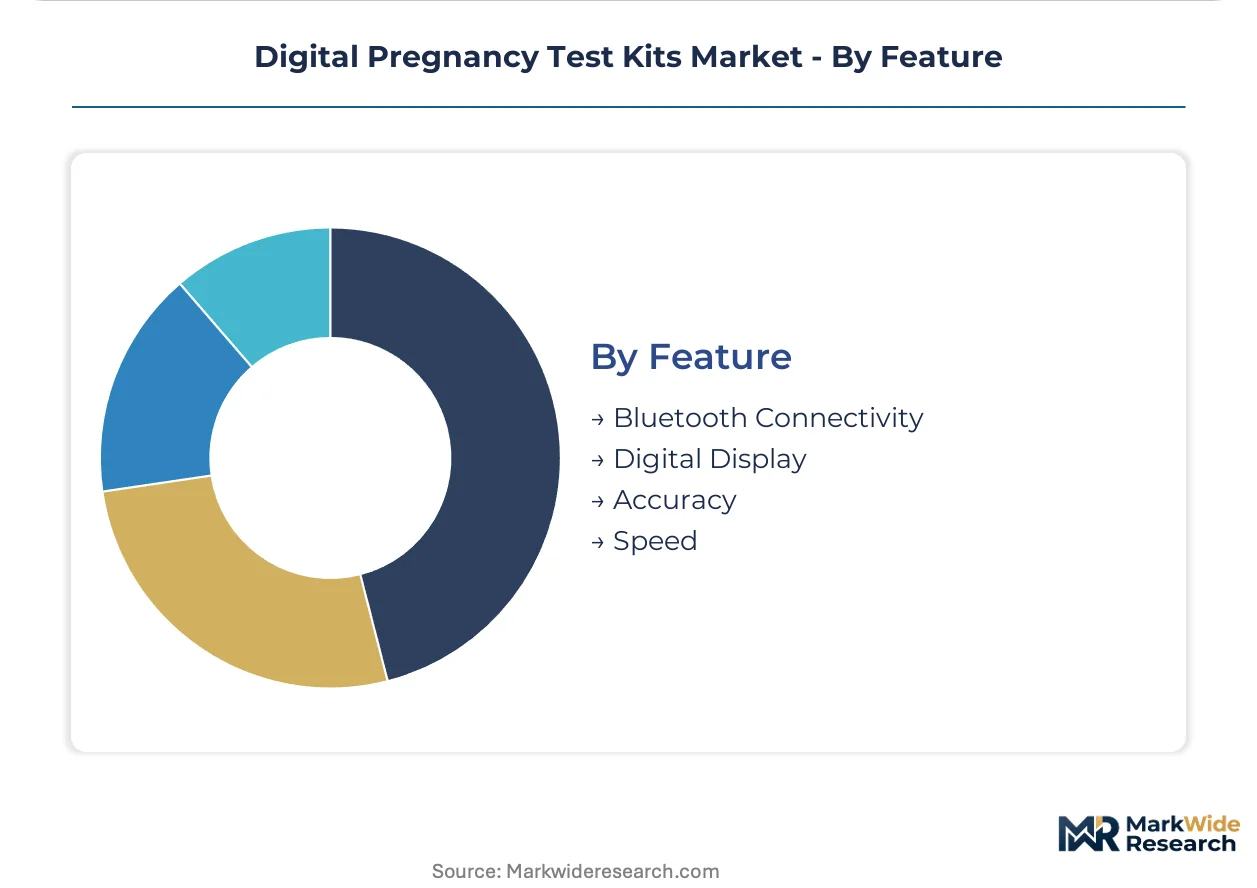
Feature:
Capability layering separates premium positioning from commoditized alternatives.
- Bluetooth Connectivity:Smartphone-native data transmission enables cycle tracking ecosystem integration. HIPAA and GDPR compliance requirements fragment connected device architectures across jurisdictions.
- Digital Display:Liquid crystal and OLED screens replace chromatic lines with unambiguous positive/negative readouts. Gestational week estimates require algorithmic hormone progression analysis.
- Accuracy:Sensitivity thresholds between 10 and 25 mIU/mL define clinical equivalence claims. ISO 13485 quality management certification functions as baseline qualifier for contract manufacturing.
- Speed:Rapid result display within one to three minutes reduces user anxiety. Electrochemical architectures achieve faster reaction kinetics than optical biosensor alternatives.
Digital display anchors volume; Bluetooth connectivity shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration toward jurisdictions with streamlined in vitro diagnostic compliance timelines is redrawing competitive geography. Cost-of-certification gaps between FDA 510(k) pathways and EU MDR technical documentation requirements pull production decisions toward specific national regulatory environments.
United States
Direct-to-consumer subscription models concentrate demand in coastal metropolitan corridors. FDA 510(k) clearance predicates for digital hCG devices accelerate time-to-market for algorithm-enhanced variants. Boston and San Francisco health-tech clusters incubate fertility app integrations that bundle connected test hardware.
Germany
Pharmacy digitization under EU e-prescription frameworks enables reimbursed diagnostic workflows to intersect with over-the-counter accessibility. REACH substance restrictions on phthalates and bisphenol-A force material transitions in urine collection wand packaging. The Rhine-Main industrial corridor hosts contract manufacturers serving private-label brands across pan-European distribution.
China
Roll-to-roll electrode printing capabilities in Shenzhen and Seoul compress bill-of-materials for electrochemical biosensor architectures. NMPA regulatory harmonization with international standards accelerates domestic market access for connected diagnostic devices. Yangtze River Delta contract manufacturers exploit scale economies to serve mid-tier competitors matching premium hardware specifications.
United Kingdom
Fertility benefit normalization through employer-sponsored programs drives recurring diagnostic spending in London and Southeast England. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR technical documentation requirements. Cambridge life-sciences clusters develop machine learning algorithms for gestational dating services adjacent to binary test results.
India
Price-sensitive segments sustain demand for chromatographic lateral flow alternatives where digital readouts offer marginal perceived value. CDSCO medical device rules impose quality management certification requirements on imported diagnostic components. Maharashtra pharmaceutical manufacturing hubs assemble private-label kits for Southeast Asian export markets.
Digital Pregnancy Test Kits Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium positioning commanding shelf-space rents in pharmacy channels while OEM fabricators capture volume through private-label arrangements. The vendor base organizes into three tiers: multinational diagnostics conglomerates with broad retail infrastructure, precision-focused specialists anchored in European quality regimes, and Asian-scale manufacturers competing on unit economics. Consolidation pressure concentrates at the mid-tier where ISO 13485 certification costs create barriers to sustained participation. Strategic moves center on fertility app ecosystem partnerships and backward integration into electrochemical sensor substrate production.
Among diversified health-care conglomerates, Abbott and Procter & Gamble occupy positions defined by retail distribution depth and consumer brand equity. SPD Swiss Precision Diagnostics GmbH exemplifies the European specialist archetype, leveraging Swiss manufacturing heritage to anchor premium positioning through the Clearblue brand. Wondfo represents the Asian-scale manufacturer archetype, with Guangzhou-based production facilities serving private-label demand across price-sensitive segments. These three patterns—conglomerate breadth, specialist precision, and scale-driven fabrication—structure competitive dynamics across channel and feature tiers.
| Leading Market Players |
|---|
| Abbott |
| bioMérieux |
| SPD Swiss Precision Diagnostics GmbH |
| Clearblue |
| Wondfo |
| Church & Dwight |
| Procter & Gamble |
| Roche Diagnostics |
| QuidelOrtho |
| Others |
Supply Flow & Price Mechanics
Roll-to-roll electrode printing specialists concentrated in Shenzhen and Seoul compress manufacturing labor-cost differentials into pricing-tier spreads across premium and private-label digital pregnancy test kit segments.
Pricing Analysis
Retailer markup layers in pharmacy and drugstore channels absorb margin pools that direct-to-consumer online platforms bypass through subscription bundling. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification grade and Bluetooth connectivity feature depth. Cost compression in economy tiers intensifies because roll-to-roll electrode printing from Guangzhou contract manufacturers erodes hardware differentiation. Price-sensitive segments in India and Southeast Asian markets sustain demand for chromatographic lateral flow alternatives where digital readouts offer marginal perceived value.
Supply Chain Analysis
CMOS image sensor supply rests on Taiwanese and South Korean foundry capacity for OLED display integration in premium digital readout variants. Electrochemical biosensor architectures draw from printed electrode substrates manufactured in Shenzhen, Seoul, and Guangzhou facilities. REACH substance restrictions on phthalates and bisphenol-A in European-bound packaging create regulatory chokepoint risks for urine collection wand material sourcing. Distribution runs through pharmacy chains in Germany and France, direct-to-consumer online platforms in the United States, and supermarket mass-market channels across price-sensitive Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where gestational timing algorithms and Bluetooth-enabled cycle tracking displace commoditized binary test formats toward premium specifications.
For Market Incumbents: Extend firmware development capabilities into fertility app ecosystem partnerships that transform single-use hardware transactions into recurring data subscription relationships. Backward integration into electrochemical sensor substrate production in the Rhine-Main corridor defends margin position against Shenzhen contract manufacturers exploiting roll-to-roll printing cost advantages. ISO 13485 auditor scarcity threatens launch timelines; incumbents should captive quality management certification relationships to preempt 6-12 month backlog delays. For New Entrants and Emerging Players: Begin with private-label supply arrangements to German pharmacy digitization channels where EU e-prescription frameworks enable reimbursed diagnostic workflows intersecting over-the-counter accessibility. Telehealth bundling partnerships with fertility benefit administrators in US coastal metropolitan markets represent the most penetrable white-space target. A direct-to-consumer go-to-market angle through subscription-based monthly hardware-and-app packages captures lifetime value across conception attempts. For Investors and Strategic Acquirers: Diagnostics conglomerates with broad retail infrastructure are the most active acquirer in this space, seeking precision-focused specialists with European quality regime positioning and backward integration into sensor substrate production. Mid-tier competitors facing ISO 13485 certification cost barriers represent the primary acquisition target archetype. The signal to watch is NMPA regulatory harmonization progress in China accelerating domestic market access for connected diagnostic devices.| Strategic Initiative | Industry Significance |
|---|---|
| Fertility App Ecosystem Partnership | Bluetooth-enabled test kits feed reproductive health data into cycle tracking platforms, embedding hardware within subscription revenue streams. |
| CE Marking Pathway Investment | EU MDR technical documentation requirements impose disproportionate burdens that certified specialists convert into competitive moats. |
| Roll-to-Roll Electrode Printing Scale-Up | Shenzhen and Seoul contract manufacturers exploit flexible sensor substrate deposition to match premium hardware specifications at reduced bill-of-materials. |
| Telehealth Bundling Launch | German pharmacy digitization enables reimbursed diagnostic workflows to intersect with over-the-counter accessibility through e-prescription frameworks. |
| hCG Quantification Algorithm Development | Machine learning on hormone progression curves opens gestational dating services adjacent to binary positive/negative results. |
Methodological Framework
Multiple input streams — executive interviews with diagnostics product managers, regulatory affairs specialists at notified bodies, and pharmacy procurement directors; secondary validation through FDA 510(k) filings, CE marking databases, and EU MDR transition guidance documents; plus trade data from customs records — were reconciled through bottom-up and top-down triangulation to construct segment-level estimates.
Data-stream reconciliation across product type, end-user setting, distribution channel, and connectivity feature dimensions shaped analytical framework construction over the projection horizon. CAGRs were derived from algorithmic hormone detection adoption curves and smartphone-native health platform penetration patterns. Electrochemical sensor cost curves and ISO 13485 certification throughput constraints fed industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt REACH substance restriction enforcement timelines, NMPA regulatory harmonization delays, and cross-border reproductive health data governance fragmentation. Forecasts reflect documented assumptions about telehealth handoff protocol standardization and fertility benefit administrator coverage expansion. A small set of named triggers — CMOS image sensor foundry capacity allocation shifts, EU MDR notified body bottleneck resolution, and HIPAA-GDPR-China PIPL compliance architecture convergence — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
Bilirubin Meters Market
Medical Devices
Australia Drug Delivery Devices Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Face Mask Device Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Medical Thermometer Market
Medical Devices
Injection Pen Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Medical Tricorder Market
Medical Devices
Accelerometers Medical Sensors Market