
 Teledentistry Market | 2026-2036
Teledentistry Market Size, Share, and Industry Trends Forecast 2026-2036
Teledentistry Market Intelligence
Cloud-native infrastructure is pivoting away from legacy on-premise dental software architectures toward API-first platforms that reduce per-consultation delivery costs. SmileDirectClub leverages direct-to-consumer channel control to sustain orthodontic subscription volumes outside traditional office networks. Align Technology anchors its competitive position through proprietary intraoral scanning hardware that locks clinicians into integrated treatment workflows. MouthWatch specializes in low-cost remote visualization tools that extend basic diagnostic reach into underserved markets.
Teledentistry encompasses the remote delivery of dental care, patient education, and clinical consultation through synchronous video platforms, asynchronous store-and-forward imaging, and connected monitoring devices operating over secure broadband or cellular networks. Its primary commercial purpose is to collapse geographic barriers between dental professionals and patients while enabling early intervention that reduces downstream procedural costs. Video conferencing and digital imaging represent the most mature technology pairings, though mobile apps are capturing the fastest growth as smartphone-native patient populations expand. Among applications, preventive care occupies the deepest margin pool because recurring remote screenings generate predictable utilization without requiring specialist labor.
The FDA exercises jurisdiction over teledentistry platforms that incorporate diagnostic algorithms, while HIPAA mandates govern patient data transmission and storage architectures across all interstate service delivery. State dental boards in the United States retain authority over licensure reciprocity and the standard of care for remote procedures, creating a fragmented compliance landscape that platform operators must navigate jurisdiction by jurisdiction. Stakeholders should monitor whether emerging FDA guidance on artificial-intelligence-assisted radiograph interpretation triggers reclassification of currently exempt teledentistry software tools.
Market Dynamics
Cloud-native infrastructure is collapsing per-consultation delivery costs for dental platforms while FDA software-as-a-medical-device guidance forces diagnostic algorithm developers into protracted compliance cycles. This tension between cost efficiency and regulatory burden defines current competitive positioning.
Growth Catalysts
- HIPAA-compliant data architectures:Secure transmission mandates in the United States have standardized encryption protocols that reduce liability exposure for interstate platform operators. This lowers barriers to multi-state service expansion.
- Smartphone penetration in tier-2 Indian cities:Asynchronous store-and-forward imaging leverages existing device density to bypass dentist-to-patient ratio constraints without capital-intensive clinic builds.
- Rural health network integration:United States federally qualified health centers embed teledentistry as primary care extensions, creating institutional demand anchors outside metropolitan dental markets.
Market Restraints
- State-by-state licensure fragmentation:United States dental boards retain independent standard-of-care authority, forcing platforms to maintain jurisdiction-specific compliance architectures that duplicate overhead.
- Diagnostic algorithm validation costs:FDA premarket review pathways for AI-assisted radiograph interpretation impose capital requirements that exclude mid-size platform developers from advanced feature deployment.
- Cellular bandwidth inconsistency:Synchronous video consultation quality degrades in rural United States markets with limited 5G infrastructure, constraining real-time diagnostic fidelity.
Strategic Opportunities
- Preventive care subscription models:Recurring remote screenings generate predictable utilization without specialist labor, capturing margin pools unavailable to procedure-dependent platforms.
- API-first platform architectures:Modular integration with legacy dental practice management software enables penetration of established clinical workflows without full system replacement.
- India's tier-2 city expansion:Structural dentist shortages in Lucknow, Jaipur, and Indore create openings for asynchronous models that decouple diagnostic access from physical provider presence.
Industry Challenges
- Cross-border credential verification:Platforms serving multiple United States jurisdictions must maintain parallel licensure tracking systems that complicate workforce scheduling and increase administrative headcount.
- Legacy software integration friction:On-premise dental practice management systems in established United States clinics resist cloud-native API connections, slowing platform adoption cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Teledentistry Market |
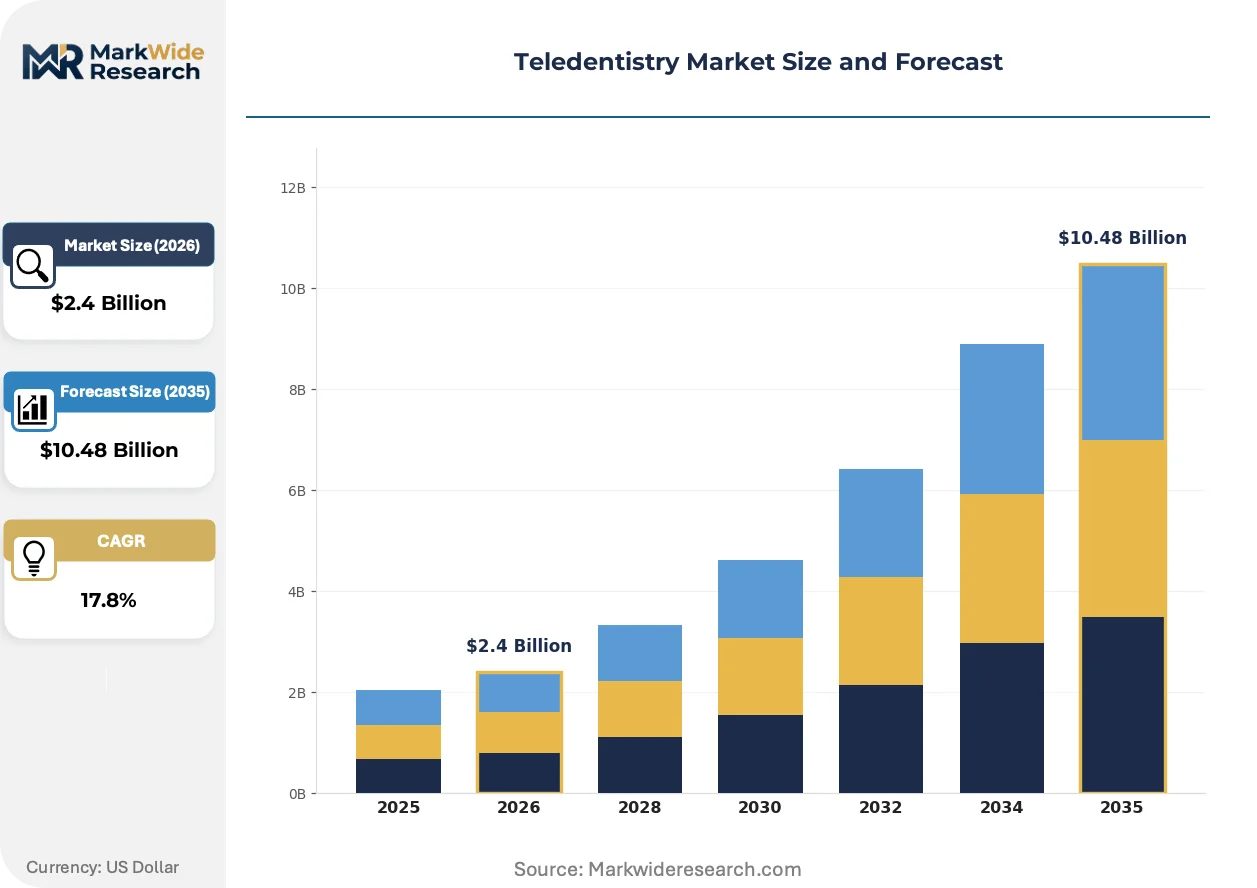
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $10.48 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultation, Diagnosis, Follow-Up, Treatment Planning Technology: Video Conferencing, Mobile Apps, Remote Monitoring, Digital Imaging End User: Patients, Dentists, Clinics, Insurance Providers Application: Preventive Care, Orthodontics, Periodontics, Cosmetic Dentistry |
| Companies Covered | SmileDirectClub, Koninklijke Philips N.V., Align Technology, Inc., Dentsply Sirona Inc., Henry Schein, Inc., MouthWatch, LLC, Dentulu, Inc., The TeleDentists, Sesame, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Teledentistry Market Strategic Shifts & Innovations
Diagnostic imaging platforms are converging with artificial intelligence inference engines while regulatory frameworks struggle to classify software outputs as medical devices. This convergence is compressing diagnostic timelines and redrawing competitive boundaries between hardware and software providers.
Intraoral scanning hardware paired with cloud-based treatment planning algorithms is expanding into orthodontic workflows previously dominated by physical impression methods. United States dental groups with multi-site operations adopt these systems fastest, consolidating purchasing power across locations. The technology is expanding into direct-to-consumer channels that bypass traditional specialist gatekeeping.
FDA draft guidance on machine-learning-enabled radiograph interpretation is forcing platform developers into premarket submission pathways previously reserved for hardware devices. Diagnostic software vendors now face validation requirements that extend commercialization timelines by eighteen to thirty-six months. United States-based asynchronous screening platforms are most affected, delaying feature rollouts for caries detection algorithms.
Employer-sponsored dental benefits in the United States are unbundling traditional managed care contracts in favor of direct platform relationships that capture utilization data. Large self-insured employers negotiate directly with teledentistry providers, displacing intermediary carriers. This pattern concentrates in technology and professional services sectors with distributed workforces lacking geographic access to traditional dental networks.
Teledentistry Market Segmentation
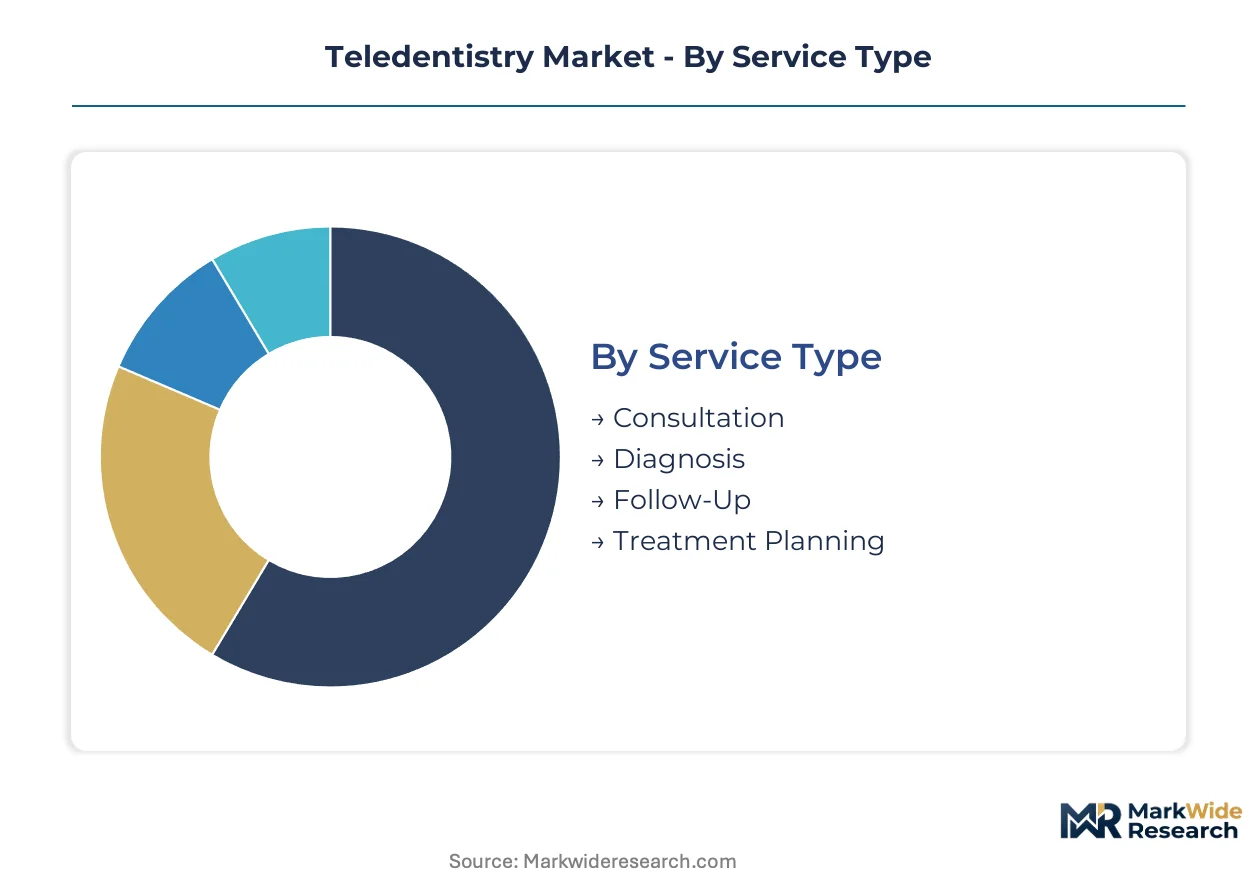
Teledentistry market participants configure platform architectures around distinct service delivery modes, technology stacks, and clinical applications. Segmentation clarity enables vendors to match reimbursement pathways with operational capabilities and regulatory scope.
Service Type:
Patient willingness to pay out-of-pocket varies sharply across service intensity tiers.
- Consultation:Initial remote triage sessions assess symptom severity and route patients to appropriate care levels. Rural health networks in the United States deploy these as primary care extensions where specialist density is lowest.
- Diagnosis:Clinician-rendered diagnostic determinations based on synchronous examination or asynchronous imaging review carry higher liability exposure and command premium reimbursement rates from commercial payers.
- Follow-Up:Post-procedure monitoring sessions reduce chair time overhead for established patients.
- Treatment Planning:Comprehensive care sequencing for complex cases integrates remote consultation with in-person procedure scheduling.
Consultation leads on scale; Diagnosis leads on momentum.
Technology:
Platform selection hinges on cellular bandwidth availability and patient digital literacy profiles.
- Video Conferencing:Real-time audiovisual consultation requires stable broadband infrastructure and delivers highest diagnostic fidelity for acute presentations. United States metropolitan markets with 5G coverage concentrate synchronous platform deployment.
- Mobile Apps:Asynchronous store-and-forward imaging through smartphone-native interfaces bypasses real-time connectivity constraints. India's tier-2 cities exploit existing device penetration to extend reach without clinic infrastructure investment.
- Remote Monitoring:Connected hardware tracks treatment compliance and physiological markers between visits.
- Digital Imaging:Cloud-based radiograph and photograph transmission enables specialist consultation across geographic boundaries.
Video Conferencing dominates revenue concentration; Mobile Apps expand most quickly into underserved catchments.
End User:
Procurement authority and reimbursement flow determine platform design priorities.
- Patients:Direct-to-consumer channels require intuitive interfaces and transparent pricing for elective services like orthodontic screening.
- Dentists:Licensed practitioners demand EHR integration and liability coverage for remote standard-of-care determinations.
- Clinics:Multi-site dental groups prioritize centralized scheduling and unified patient records across locations.
- Insurance Providers:Payers seek utilization data and cost containment metrics to justify benefit inclusion.
Clinics anchor procurement volume; Patients drive channel diversification.
Application:
Clinical domain selection shapes regulatory pathway and margin structure.
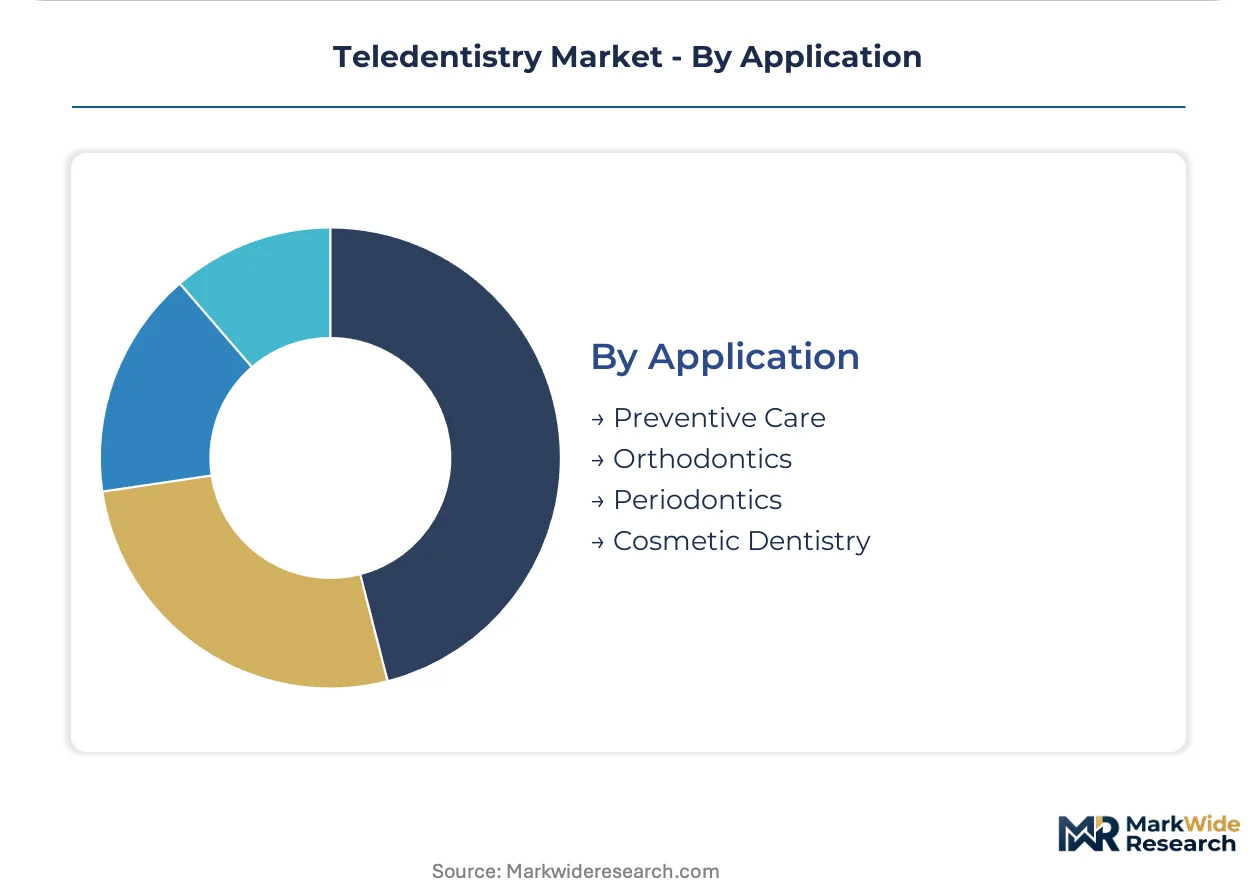
- Preventive Care:Recurring remote screenings for caries and periodontal disease generate subscription revenue without specialist labor. Employer-sponsored benefits in United States technology sectors favor this utilization pattern for distributed workforces.
- Orthodontics:Remote monitoring of clear aligner therapy reduces in-person adjustment frequency. Direct-to-consumer models bypass traditional orthodontic gatekeeping in price-sensitive segments.
- Periodontics:Gum disease management requires periodic tissue assessment that asynchronous imaging supports.
- Cosmetic Dentistry:Aesthetic consultation and treatment simulation carry premium pricing and discretionary demand volatility.
Preventive Care captures the deepest recurring margin pool; Orthodontics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States rural health networks anchor teledentistry infrastructure deployment, with federally qualified health centers embedding remote dental consultations as primary care extensions where specialist density remains lowest.
United States
Federally qualified health centers in Mississippi and Alabama deploy synchronous video platforms to extend specialist reach into dental deserts. HIPAA mandates standardize encryption protocols that reduce interstate liability exposure for multi-state platform operators. Dallas and Houston dental groups consolidate purchasing power across multi-site operations for cloud-native intraoral scanning systems.
India
Tier-2 cities including Lucknow, Jaipur, and Indore exploit smartphone penetration rates to bypass dentist-to-patient ratio constraints through asynchronous store-and-forward imaging. The country's national pharmaceutical regulator evaluates software-as-medical-device classifications for diagnostic algorithm platforms. Bangalore health technology clusters incubate API-first teledentistry architectures targeting preventive care subscription models.
Germany
Baden-Württemberg dental technology manufacturers integrate intraoral scanning hardware with cloud-based treatment planning algorithms for orthodontic workflows. CE marking requirements under the EU Medical Device Regulation govern diagnostic software validation timelines for platform developers. Munich dental groups adopt employer-sponsored direct platform relationships that displace traditional managed care intermediaries.
United Kingdom
London and Southeast England employer benefits in technology and professional services sectors unbundle traditional dental contracts for direct teledentistry platform access. The Medicines and Healthcare products Regulatory Agency aligns with evolving FDA guidance on artificial-intelligence-assisted radiograph interpretation. Manchester and Birmingham dental practices face legacy software integration friction resisting cloud-native API connections.
Brazil
São Paulo dental groups pilot asynchronous screening platforms for caries detection in employer-sponsored benefit programs. ANVISA evaluates premarket submission pathways for diagnostic algorithm developers facing extended commercialization timelines. Rio de Janeiro telehealth clusters concentrate mobile app development for patient-native interfaces in price-sensitive market segments.
Teledentistry Market Key Industry Players
Strategic partnerships dominate the current landscape as platform operators seek to embed teledentistry services into established healthcare delivery networks. The vendor base organizes around three tiers: direct-to-consumer orthodontic platforms, enterprise clinical workflow integrators, and low-cost remote visualization specialists. Two archetypes define competitive positioning: hardware-anchored ecosystems that lock clinicians into proprietary treatment workflows, and software-native architectures that reduce per-consultation delivery costs through API-first infrastructure. M&A activity concentrates on diagnostic algorithm capabilities, while geographic expansion through state-by-state licensure navigation occupies mid-size platform developers.
Within the hardware-anchored ecosystem tier, Align Technology and Koninklijke Philips N.V. exemplify vertically integrated positioning through proprietary intraoral scanning hardware that binds clinicians into integrated treatment workflows. MouthWatch, LLC occupies a position among low-cost remote visualization specialists extending basic diagnostic reach into underserved markets. SmileDirectClub anchors the direct-to-consumer channel control archetype, sustaining orthodontic subscription volumes outside traditional office networks through platform-native patient acquisition.
| Leading Market Players |
|---|
| SmileDirectClub |
| Koninklijke Philips N.V. |
| Align Technology, Inc. |
| Dentsply Sirona Inc. |
| Henry Schein, Inc. |
| MouthWatch, LLC |
| Dentulu, Inc. |
| The TeleDentists |
| Sesame, Inc. |
| Others |
Cost & Logistics Intelligence
Multi-site dental groups in the United States concentrate procurement authority and negotiate platform licensing through enterprise SaaS tiers that collapse per-seat costs below direct-to-consumer rates. This buyer concentration tilts pricing power toward volume-committed clinic networks while fragmenting revenue capture for standalone practitioners.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and AI inference engine licensing feeds directly into platform subscription tiers. Three-tier pricing structure across premium, standard, and economy levels separates enterprise clinic deployments from individual practitioner licenses and patient-facing mobile apps. Pricing pressure stems from open-source diagnostic algorithm alternatives eroding proprietary software premiums. Individual dentists exhibit highest price sensitivity, while hospital systems and dental service organizations absorb premium tiers for integrated workflow guarantees.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor hardware fulfillment networks for intraoral scanners and remote monitoring devices. Component sourcing draws from Taiwanese semiconductor foundries for imaging sensors, Chinese battery manufacturers for portable devices, and German precision optics suppliers for lens assemblies. Single-source vulnerability concentrates in specialized CMOS sensor production for intraoral cameras. Distribution runs through dental equipment distributors with exclusive territory agreements in developed markets, while direct-to-manufacturer ordering dominates price-sensitive emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
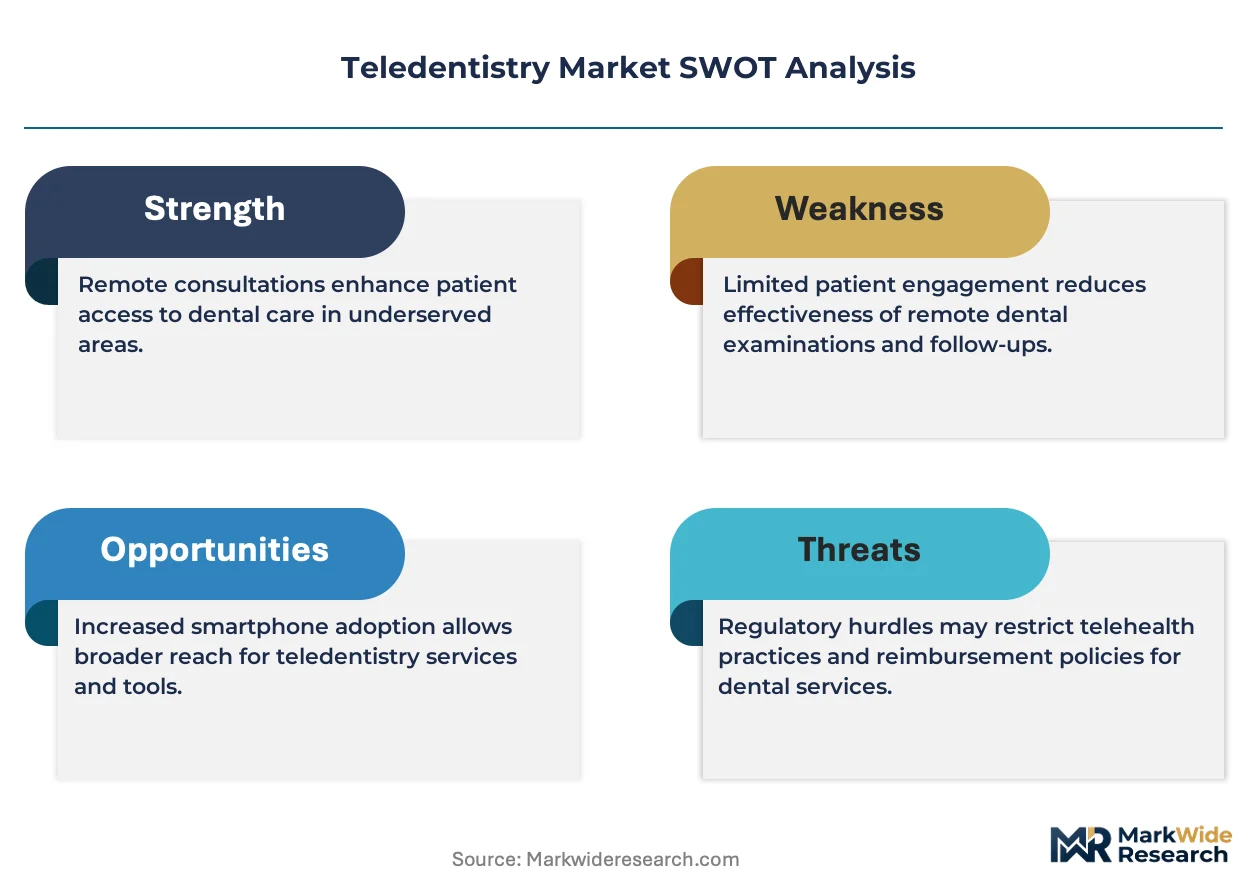
Teledentistry operates as a regulatory compounder where FDA software-as-a-medical-device guidance on AI-assisted radiograph interpretation is accelerating compliance investment requirements and consolidating vendor viability around capitalized platform developers.
For Market Incumbents: Anticipate state-by-state licensure fragmentation as a persistent margin drain requiring jurisdiction-specific compliance architectures. Counter emerging API-first competitors by deepening backward integration into proprietary intraoral scanning hardware that locks clinicians into captive treatment workflows. Prioritize CE marking investment under EU Medical Device Regulation to preempt European market entry by software-native challengers. For New Entrants and Emerging Players: Begin with India's tier-2 cities where dentist-to-patient ratio constraints and smartphone penetration create structural white space for asynchronous store-and-forward models. Target employer-sponsored benefits in United States technology sectors as the most penetrable reimbursement channel. Deploy direct-to-consumer mobile acquisition with transparent subscription pricing to bypass entrenched dental group procurement gatekeepers. For Investors and Strategic Acquirers: Dental service organizations and multi-site clinic consolidators are the most active acquirers in this space, seeking platform capabilities to unify patient records across geographic footprints. Long-term viability hinges on regulatory navigation capacity rather than pure technology differentiation. Monitor FDA premarket submission timelines for AI-assisted diagnostic features as the critical inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Modular connectivity with legacy practice management software accelerates clinic adoption without system replacement. |
| CE Marking Pathway | EU Medical Device Regulation compliance unlocks German and United Kingdom dental group procurement channels. |
| Hospital System Partnership | Federally qualified health center integration in Mississippi and Alabama anchors rural primary care extension demand. |
| Software Companion Development | FDA-aligned diagnostic algorithm validation extends commercialization timelines but excludes undercapitalized competitors. |
| Reimbursement Strategy | Direct employer benefit contracting in Dallas and Houston displaces traditional managed care intermediaries. |
Research Approach
Bottom-up dental group and clinic procurement modeling reconciled against top-down platform provider revenue tracking forms the analytical core of this study. Primary interviews with teledentistry platform executives, dental practice management software engineers, hospital purchasing committee members, and state dental board regulatory officers combined with secondary validation from FDA 510(k) filings, CE marking databases, CMS Medicare telehealth reimbursement data, and dental equipment distributor customs records. Triangulation across these sources anchored volume and value estimates.
Historical trendline analysis of synchronous and asynchronous service delivery modes informed projection frameworks across the modeling period. Segmentation dimensions include service type intensity, technology stack deployment, end-user procurement authority, and clinical application domain. CAGRs derived from regression analysis of adoption velocity curves in comparable remote healthcare verticals, calibrated against smartphone penetration trajectories and regulatory milestone timing. Forecast inputs incorporate HIPAA compliance cost trajectories and AI diagnostic algorithm validation pipeline visibility.
Several conditions sit outside the modeled scope, including state-level licensure reciprocity agreements not yet ratified, FDA final guidance publication timing, and cellular infrastructure buildout pace in rural United States markets. Forecasts reflect documented assumptions about reimbursement pathway stability and platform security architecture standardization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
EMEA Dental Service Organization Market
Dental Services
Dental Services Market
Dental Services
Dental Fluoride Treatment Market
Dental Services
Dental Service Organization Market
Dental Services
Chronic Gingivostomatitis Treatment Market
Dental Services
Dental Market
Dental Services
Global Dental Support Organizations Market
Dental Services
US Dental Chains Market
Dental Services
Orthodontic Services Market
Dental Services
United States Dental Services Market
Dental Services
Microdontia Treatment Market
Dental Services
Periodontal Dental Service Market