
 Dental Fluoride Treatment Market | 2026-2036
Dental Fluoride Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Fluoride Treatment Market Intelligence
The EU Green Deal is recalibrating procurement criteria for dental consumables across European clinics, pushing suppliers toward biodegradable packaging and reduced chemical footprints. Colgate-Palmolive Company leverages its retail pharmacy network to sustain volume leadership in home-use fluoride rinses. Dentsply Sirona anchors the professional channel through direct sales to dental clinics, while VOCO GmbH differentiates via specialized varnish formulations for pediatric applications.
Dental fluoride treatment encompasses professionally applied and self-administered formulations containing sodium fluoride, stannous fluoride, or acidulated phosphate fluoride, typically delivered at concentrations between 1.23% and 5% depending on clinical indication and regulatory jurisdiction. These preparations function primarily as topical remineralizing agents that inhibit demineralization and enhance enamel resistance to acid challenge. Varnish dominates professional settings due to prolonged contact time and reduced risk of ingestion, while rinse formats lead home care penetration through pharmacy and online store availability. Dental supply distributors capture margin pools in the institutional segment by bundling fluoride products with broader preventive equipment portfolios.
FDA regulates over-the-counter fluoride rinses under monograph standards limiting adult formulations to 0.02% sodium fluoride equivalent, while professional gels and foams fall under medical device or drug pathways requiring stricter compliance. EMA and national European regulators enforce REACH compliance on fluoride active ingredients, constraining formulation flexibility for suppliers serving multiple jurisdictions. Stakeholders must monitor evolving EPA environmental assessments on fluoride discharge from manufacturing facilities, as wastewater standards could reshape production geography and cost structures for concentrated gel and foam products.
Market Dynamics
The EU Green Deal is recalibrating procurement criteria for dental consumables across European clinics, pushing suppliers toward biodegradable packaging and reduced chemical footprints. This regulatory pressure intersects with FDA scrutiny of over-the-counter fluoride concentrations to reshape formulation strategies and manufacturing geography.
Growth Catalysts
- REACH compliance frameworks:ECHA enforcement on fluoride active ingredients drives premiumization of professional-grade formulations as suppliers absorb certification costs into higher-margin products.
- Pediatric dentistry expansion:North American clinics are expanding professional fluoride applications amid heightened parental awareness of early childhood caries prevention protocols.
- Statutory insurance coverage:Germany's statutory dental insurance covers preventive fluoride for high-risk patients, anchoring institutional demand within Europe's largest dental market.
Market Restraints
- Raw material concentration:Sodium fluoride supply concentrates among Chinese chemical processors, exposing formulators to export license volatility and shipping cost spikes.
- Technical limitation in varnish adhesion:Moisture sensitivity of conventional resin bases limits application efficacy in humid climates, constraining addressable market in tropical regions.
- Regulatory friction from EPA assessments:Evolving EPA environmental assessments on fluoride discharge from manufacturing facilities threaten production cost structures for concentrated gel and foam products.
Strategic Opportunities
- Biodegradable packaging mandates:EU Green Deal procurement criteria create first-mover advantage for suppliers with compostable varnish unit-dose sachets and recyclable rinse bottles.
- Tele-dentistry integration:Remote diagnostic platforms enable prescription-strength fluoride rinse distribution through verified pharmacy networks, bypassing traditional clinic gatekeepers.
- Japan's aging demographic:METI preventive healthcare incentives target root caries in elderly populations, opening specialized high-fluoride varnish segments for geriatric dental services.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in acidulated phosphate fluoride stability and taste masking commands premium compensation, constraining R&D throughput at mid-size manufacturers.
- Dual certification timelines:Simultaneous FDA monograph compliance and MDR technical documentation for professional gels extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Fluoride Treatment Market |
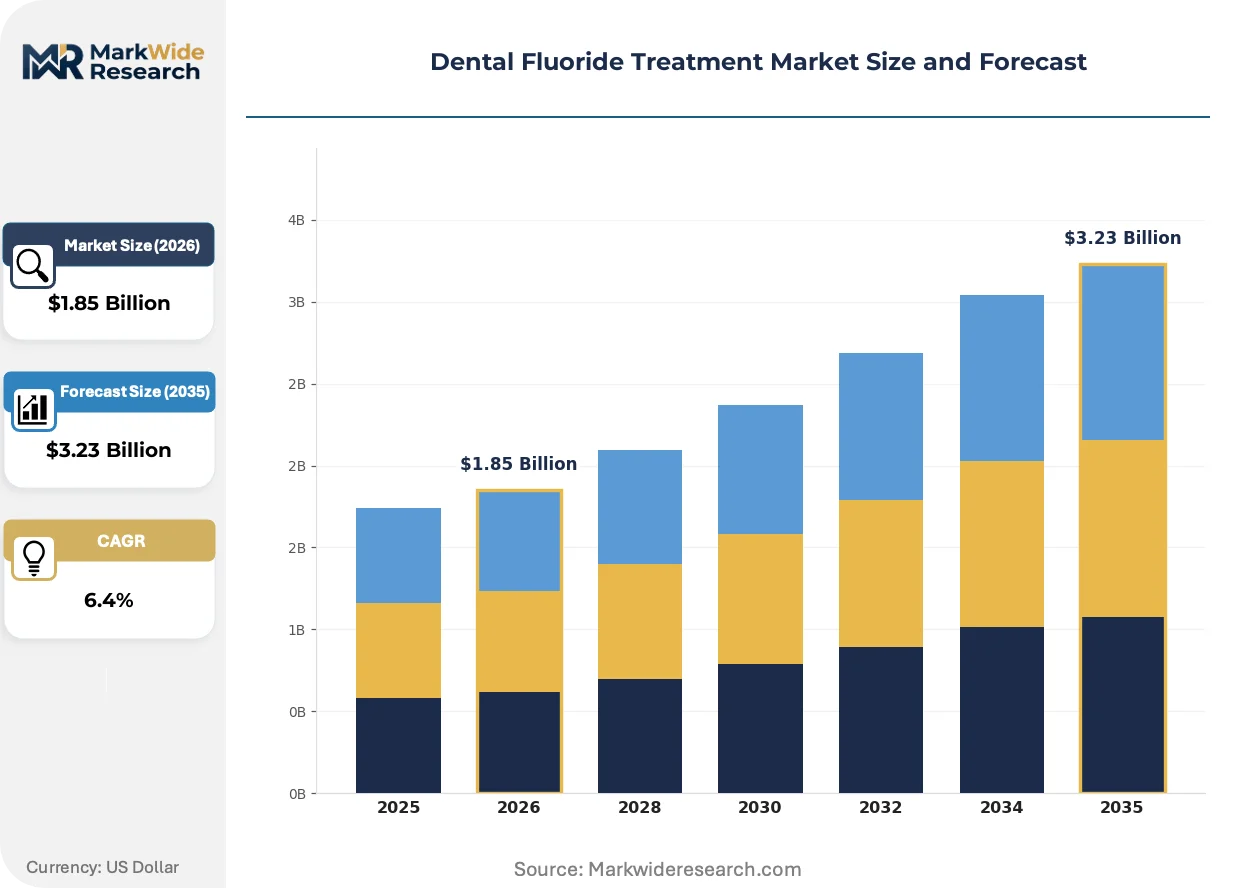
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Foam, Rinse, Varnish End User: Dental Clinics, Hospitals, Home Care, Educational Institutions Application: Cavity Prevention, Sensitivity Protection, Oral Health Maintenance, Treatment of Caries Distribution Channel: Direct Sales, Retail Pharmacies, Online Stores, Dental Supply Distributors |
| Companies Covered | DMG Dental, Ivoclar Vivadent, Colgate-Palmolive Company, Church & Dwight, Ultradent Products, Dentsply Sirona, VOCO GmbH, Young Dental, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Fluoride Treatment Market Strategic Shifts & Innovations
Formulation chemistry and delivery mechanisms are undergoing parallel evolution as clinicians demand prolonged contact time with minimized ingestion risk. These shifts favor varnish architectures and precision-dosing systems over conventional rinse formats.
Nano-hydroxyapatite fluoride hybrids are consolidating professional preference as next-generation remineralizing agents. Pediatric dental clinics in Germany and the United States are adopting these materials at accelerating rates. The technology is consolidating market share from conventional sodium fluoride gels by delivering comparable efficacy at lower active concentrations.
EMA's tightened MDR surveillance of fluoride-containing medical devices is elevating documentation burdens for professional-grade foams. Manufacturers must now submit clinical performance data for renewed CE marking, compressing margins on legacy formulations. The professional channel across France, Italy, and Spain faces the steepest compliance cost escalation as national competent authorities enforce divergent interpretation guidelines.
Parental purchasing of home-use fluoride rinses is migrating from pharmacy shelves to subscription-direct models. Amazon and specialized oral health platforms are capturing volume from Colgate-Palmolive's traditional retail pharmacy network. This channel rotation is most pronounced in United States suburban markets where convenience purchasing overrides brand loyalty.
Dental Fluoride Treatment Market Segmentation
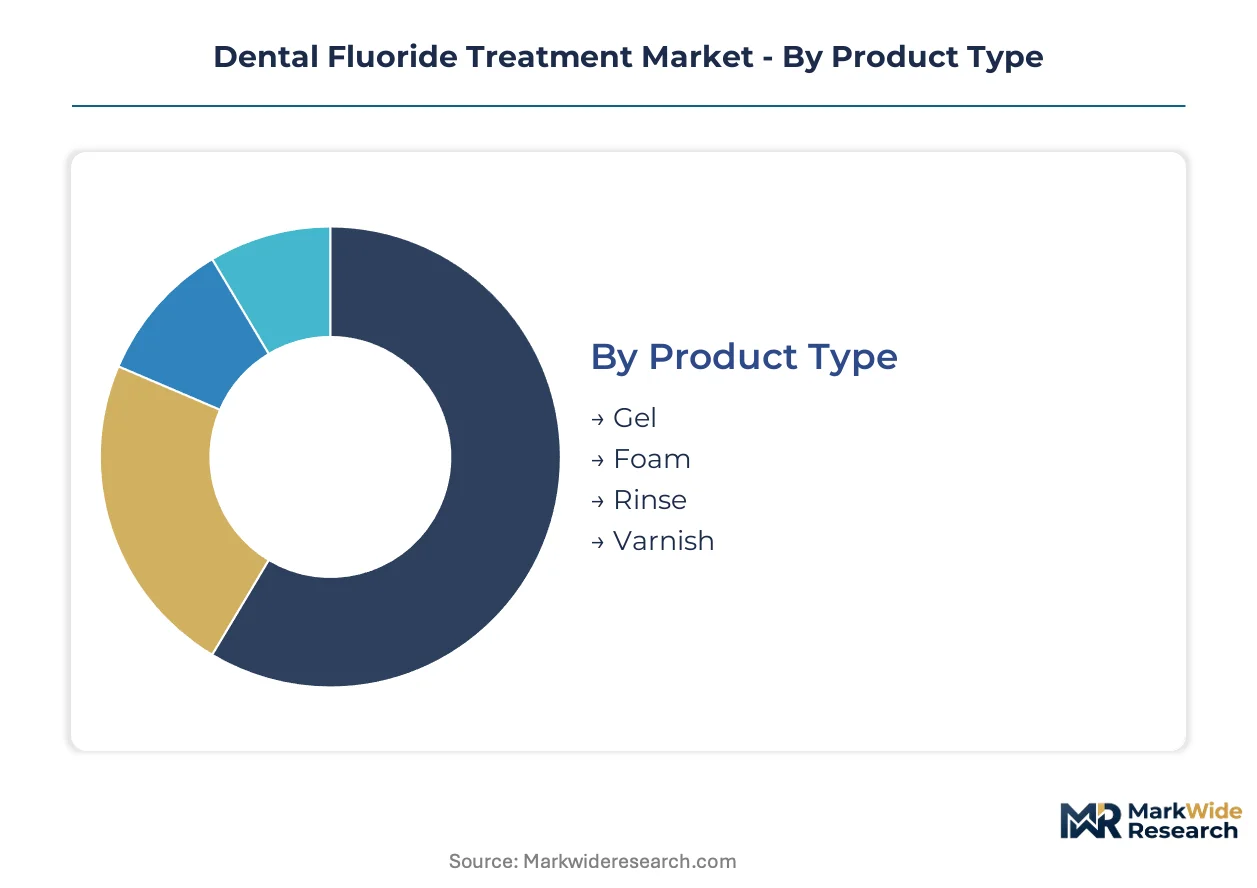
Dental fluoride treatment segmentation reflects divergent clinical workflows and procurement pathways. Product form dictates reimbursement eligibility and application setting, while distribution channel determines margin capture and regulatory compliance burden.
Product Type:
Clinicians select formulations based on contact time requirements, patient compliance capacity, and ingestion risk profiles.
- Varnish:Resin-based suspensions of sodium fluoride or difluorosilane adhere to enamel for 4-6 hours, enabling prolonged mineral uptake with minimal salivary washout. Pediatric dental clinics in Germany and the United States favor varnish for early childhood caries protocols due to its tolerance in non-cooperative patients and reduced toxicity risk.
- Rinse:Aqueous solutions containing 0.02-0.05% sodium fluoride designed for daily home use, typically dispensed in 10ml unit doses. Amazon and specialized oral health platforms are capturing volume from traditional retail pharmacy networks in United States suburban markets where convenience purchasing overrides brand loyalty.
- Gel:Thixotropic preparations loaded into trays for 4-minute professional applications, traditionally acidulated to pH 3.5 for enhanced enamel penetration. FDA monograph compliance and MDR technical documentation requirements extend product launch cycles by 18-24 months for manufacturers pursuing dual certification.
- Foam:Mousse-like dispersions offering equivalent fluoride delivery with reduced material volume per patient. EMA's tightened MDR surveillance elevates documentation burdens for renewed CE marking, compressing margins on legacy formulations across France, Italy, and Spain.
Volume sits with rinse formats through pharmacy and mass retail ubiquity; growth tilts toward varnish as pediatric dentistry expansion and parental safety concerns reshape professional preference.
End User:
Procurement authority and reimbursement pathways fragment demand across institutional and consumer-directed settings.
- Dental Clinics:Independent and group practices purchasing professional-grade varnishes and gels through dental supply distributors, often bundled with broader preventive equipment portfolios. Dentsply Sirona anchors this channel through direct sales relationships.
- Home Care:Individual consumers selecting OTC rinses based on dentist recommendation, pharmacy availability, or direct-to-subscription purchasing. Colgate-Palmolive Company leverages its retail pharmacy network to sustain volume leadership despite channel migration.
- Hospitals:Acute and ambulatory surgical centers with centralized procurement functions, prioritizing formulary standardization and infection control compliance. VOCO GmbH targets this segment with specialized high-concentration formulations.
- Educational Institutions:School-based prevention programs and university dental clinics operating under public health budgets with heightened cost sensitivity. EU Green Deal procurement criteria are recalibrating supplier selection toward biodegradable packaging and reduced chemical footprints.
Revenue concentrates in dental clinics through professional product premiumization; expansion accelerates in home care as tele-dentistry platforms enable prescription-strength rinse distribution.
Application:
Clinical indication determines fluoride concentration, application frequency, and regulatory classification.
- Cavity Prevention:Prophylactic protocols targeting enamel demineralization inhibition through regular topical application, representing the foundational use case across all product formats. Germany's statutory dental insurance covers preventive fluoride for high-risk patients, anchoring institutional demand.
- Treatment of Caries:Therapeutic interventions for active lesions, including silver diamine fluoride combinations and high-concentration varnish protocols for arrested caries. Nano-hydroxyapatite fluoride hybrids are consolidating professional preference by delivering comparable efficacy at lower active concentrations.
- Sensitivity Protection:Formulations targeting exposed dentin tubule occlusion, often incorporating potassium nitrate or arginine alongside fluoride. METI preventive healthcare incentives in Japan target root caries in elderly populations, opening specialized segments for geriatric dental services.
- Oral Health Maintenance:General wellness positioning for compliant patients with low caries risk, emphasizing convenience and taste acceptance over therapeutic intensity. Subscription-direct models are capturing volume from traditional retail channels in United States suburban markets.
Volume sits with cavity prevention through established prophylactic protocols; growth tilts toward treatment of caries as remineralization science advances and minimally invasive dentistry gains traction.
Distribution Channel:
Channel selection determines margin structure, customer relationship depth, and regulatory compliance pathway.
- Dental Supply Distributors:Specialized intermediaries bundling fluoride products with chairside equipment, infection control supplies, and practice management software. These distributors capture margin pools in the institutional segment by consolidating procurement workflows.
- Online Stores:E-commerce platforms including Amazon and dedicated oral health sites enabling subscription-direct purchasing with automated replenishment. Parental purchasing of home-use fluoride rinses is migrating from pharmacy shelves to these channels.
- Retail Pharmacies:Brick-and-mortar drugstores and mass merchandisers with OTC fluoride rinse placement, historically dominated by Colgate-Palmolive's retail network. Channel rotation is compressing foot traffic-dependent volume.
- Direct Sales:Manufacturer-to-clinic relationships bypassing distributor markups, favored by large dental service organizations with centralized procurement. Dentsply Sirona anchors the professional channel through this model.
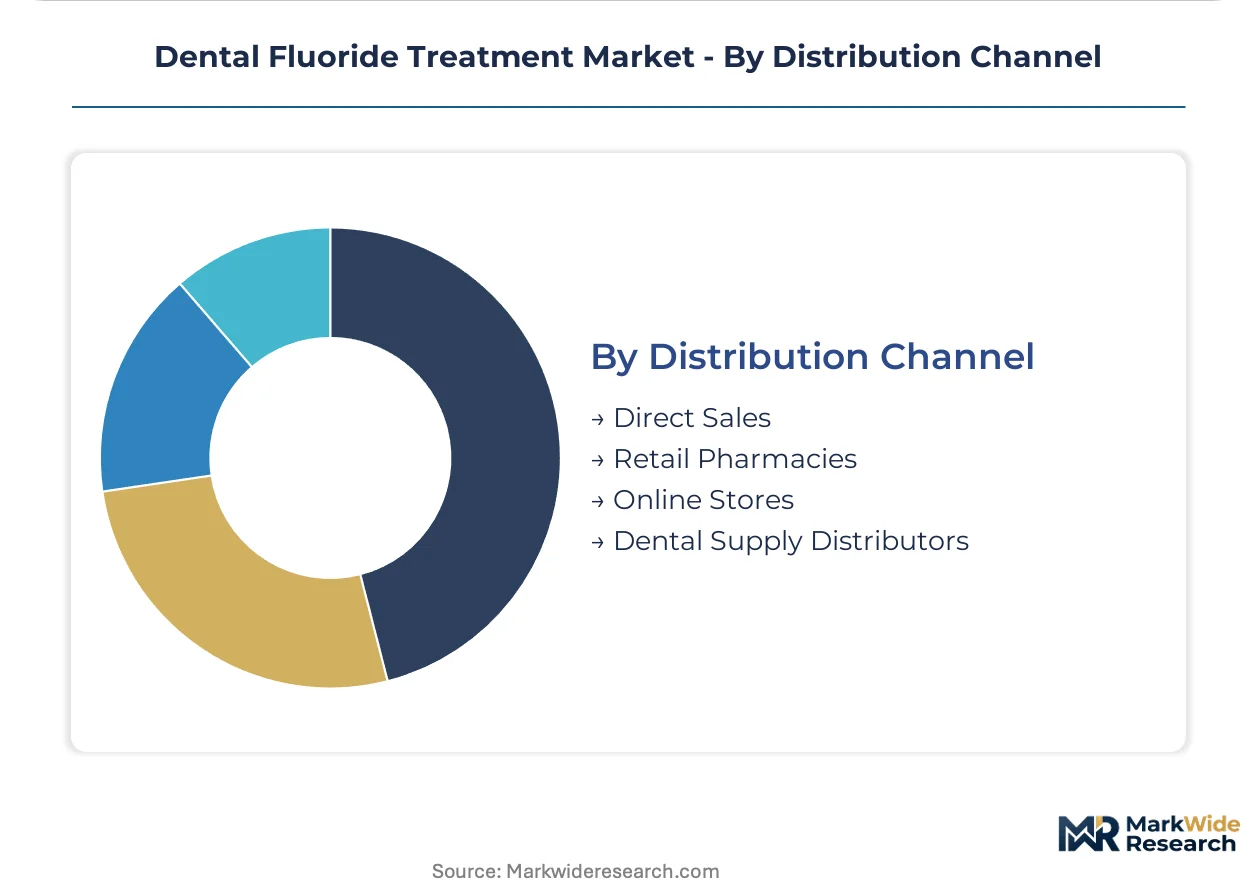
Revenue concentrates in dental supply distributors through bundling economics; expansion accelerates in online stores as convenience purchasing and subscription mechanics reshape consumer behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese chemical processors concentrate sodium fluoride supply, while consumption tilts toward Germany, the United States, and Japan where insurance coverage and pediatric dentistry expansion drive institutional procurement. Manufacturing geography and end-market demand sit on opposite sides of the Pacific.
United States
Pediatric dental clinics in suburban markets are expanding professional fluoride applications as parental awareness of early childhood caries protocols intensifies. FDA monograph standards limit over-the-counter rinse concentrations to 0.02% sodium fluoride equivalent, channeling higher-risk patients toward professional settings. Amazon and specialized oral health platforms in California and Texas are capturing home-use volume from traditional pharmacy networks through subscription-direct mechanics.
Germany
Statutory dental insurance coverage for preventive fluoride in high-risk patients anchors European institutional demand. ECHA REACH compliance frameworks elevate certification costs for professional-grade formulations, pushing suppliers toward premiumization. VOCO GmbH in Cuxhaven exemplifies specialized varnish manufacturing for pediatric applications, while Bavarian dental distributors bundle fluoride products with broader preventive equipment portfolios.
Japan
METI preventive healthcare incentives target root caries in elderly populations, opening specialized high-fluoride varnish segments for geriatric dental services. Osaka-based clinics are adopting nano-hydroxyapatite fluoride hybrids at accelerating rates. The Kanto region around Tokyo concentrates tele-dentistry platform development enabling prescription-strength rinse distribution through verified pharmacy networks.
China
Sodium fluoride raw material supply concentrates among domestic chemical processors, exposing formulators to export license volatility and shipping cost spikes. Yangtze River Delta manufacturers face tightening MEE environmental assessments on fluoride discharge from production facilities. Shanghai and Jiangsu province clinics are importing professional-grade varnishes to circumvent domestic formulation quality inconsistencies.
Brazil
School-based prevention programs in São Paulo and Minas Gerais operate under public health budgets with heightened cost sensitivity. ANVISA regulatory pathways for professional fluoride gels lag FDA and EMA timelines by 12-18 months, delaying product availability. Rio de Janeiro dental service organizations are consolidating procurement through direct manufacturer relationships to bypass distributor markups.
Dental Fluoride Treatment Market Key Industry Players
The competitive structure tilts toward diversified healthcare conglomerates with parallel consumer and professional channels. Three distinct archetypes populate the vendor base: multinational oral care brands with retail pharmacy dominance, specialized dental equipment manufacturers with direct clinic relationships, and regional varnish formulators with pediatric specialization. Consolidation pressure is accelerating through dental service organization procurement centralization and tele-dentistry platform integration.
Among diversified healthcare conglomerates, Colgate-Palmolive Company and Koninklijke Philips occupy positions spanning home-use rinse distribution and connected oral health devices. Dentsply Sirona exemplifies the professional-channel archetype through direct sales relationships with dental clinics. VOCO GmbH represents specialized varnish manufacturing with pediatric application focus. DMG Dental, Ivoclar Vivadent, and Ultradent Products sit within mid-tier professional formulations, while Church & Dwight and Young Dental compete on pharmacy shelf presence and unit-dose convenience formats.
| Leading Market Players |
|---|
| DMG Dental |
| Ivoclar Vivadent |
| Colgate-Palmolive Company |
| Church & Dwight |
| Ultradent Products |
| Dentsply Sirona |
| VOCO GmbH |
| Young Dental |
| Koninklijke Philips |
| Others |
Cost & Logistics Intelligence
EU Green Deal procurement criteria for biodegradable packaging and reduced chemical footprints gate qualified supply access and premium-tier pricing power for dental fluoride treatment suppliers. REACH certification costs and FDA monograph compliance create tiered qualification barriers that concentrate margin capture among formulators with dual-jurisdiction documentation capabilities.
Pricing Analysis
Outcome-based pricing anchors professional varnish formulations to clinical efficacy metrics including enamel remineralization rates and caries arrest outcomes. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and application setting, with MDR-compliant professional gels commanding highest positioning. Cost compression in economy-tier rinses is intensifying because Amazon and subscription-direct platforms are bypassing traditional pharmacy markups. Educational institutions and school-based programs exhibit greatest price sensitivity, while hospital procurement committees prioritize formulary standardization over unit cost.
Supply Chain Analysis
Dental supply distributors handle institutional demand through bundled procurement workflows combining fluoride varnishes with chairside equipment and infection control supplies. Sodium fluoride raw material supply concentrates in China, with secondary sourcing from Germany and Japan for high-purity pharmaceutical grades. Formulation chemistry depends on specialized resin bases and acidulated phosphate stabilizers with limited qualified suppliers. Single-source vulnerability in Chinese chemical processor export licensing exposes formulators to supply interruption. Distribution runs through direct manufacturer-to-clinic relationships for large dental service organizations, bypassing intermediary markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as suppliers pursue captive control over sodium fluoride raw material sourcing to insulate margins from export license volatility and shipping cost spikes.
For Market Incumbents: Cement channel control through exclusive distribution partnerships with dental service organizations, while acquiring specialized varnish formulators with pediatric application expertise. Nano-hydroxyapatite fluoride hybrids threaten conventional sodium fluoride gel positioning, requiring accelerated R&D investment in next-generation remineralizing agents. Backward integration into sodium fluoride raw material supply hedges against Chinese processor concentration risk.
For New Entrants and Emerging Players: Capture tele-dentistry-enabled prescription-strength rinse distribution through verified pharmacy network partnerships, bypassing traditional clinic gatekeepers. Japan's geriatric dental services present the most penetrable geography given METI preventive healthcare incentives targeting root caries in elderly populations. White-space opportunity sits with compostable varnish unit-dose sachets aligned with EU Green Deal procurement criteria.
For Investors and Strategic Acquirers: EMA's tightened MDR surveillance elevating documentation burdens for renewed CE marking is the leading indicator that professional-grade formulation capabilities will consolidate toward vendors with established regulatory affairs infrastructure. Long-term viability favors vertically integrated suppliers with captive raw material sourcing and dual FDA-EMA certification track records. Acquisition target archetype: mid-tier varnish specialists with pediatric dental clinic relationships and biodegradable packaging capabilities. Signal to monitor: EPA environmental assessment outcomes on fluoride discharge from manufacturing facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Fluoride Supply | Captive sourcing from Chinese chemical processors insulates margin structures from export license volatility. |
| Biodegradable Packaging Transition | Compostable varnish unit-dose sachets unlock EU Green Deal procurement preference across European clinics. |
| Tele-Dentistry Platform Partnership | Prescription-strength rinse distribution through verified pharmacy networks bypasses traditional clinic gatekeepers. |
| Nano-Hydroxyapatite R&D Investment | Next-generation remineralizing agents consolidate professional preference from conventional sodium fluoride gels. |
| Dual FDA-EMA Certification Acceleration | Simultaneous monograph compliance and MDR documentation compresses product launch cycles against competitors. |
Research Approach
Document review covered FDA monograph filings, EMA MDR submission databases, REACH compliance registries, and dental supply distributor catalogs, complemented by interviews with pediatric dental clinic directors, hospital purchasing committee members, GPO contracts managers, and formulation chemistry specialists. Secondary validation drew from EPA environmental assessment disclosures, EU Green Deal procurement guideline releases, and statutory insurance coverage policy documents. Bottom-up demand modeling across patient risk segments triangulated against top-down market sizing from dental consumables trade data.
Revenue and volume projections across the analysis window employed a segmented analytical framework incorporating product form, end-user setting, clinical indication, and distribution channel dimensions. CAGRs were derived from growth rate convergence modeling applied to pediatric dentistry expansion rates, insurance coverage policy trajectories, and tele-dentistry platform adoption curves. Forecast inputs included parental awareness indices for early childhood caries prevention, regulatory documentation burden cost estimates, and raw material shipping cost volatility assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA wastewater standard revisions, ECHA REACH enforcement intensity, and Chinese export license policy shifts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
Dental Market
Dental Services
Chronic Gingivostomatitis Treatment Market
Dental Services
US Dental Chains Market
Dental Services
Teledentistry Market
Dental Services
EMEA Dental Service Organization Market
Dental Services
Dental Services Market
Dental Services
Global Dental Support Organizations Market
Dental Services
Microdontia Treatment Market
Dental Services
Periodontal Dental Service Market
Dental Services
United States Dental Services Market
Dental Services
Dental Service Organization Market
Dental Services
Orthodontic Services Market