
 Orthodontic Services Market | 2026-2036
Orthodontic Services Market Size, Share, and Industry Trends Forecast 2026-2036
Orthodontic Services Market Analysis
Clear aligner precision standards are redrawing competitive boundaries in orthodontic services. Align Technology, Inc. leverages its proprietary SmartTrack material science to sustain margin leadership across direct-to-consumer and practitioner channels. Dentsply Sirona anchors its position through integrated digital workflow ecosystems spanning intraoral scanning to finishing. Henry Schein, Inc. competes by controlling distribution density across North American dental practices.
Orthodontic services encompass the diagnosis, prevention, and correction of malpositioned teeth and jaws through mechanical appliances, digital planning software, and periodic clinical supervision; treatment protocols specify force levels measured in grams, movement velocities of 0.5-1.0 mm monthly, and root parallelism tolerances within 5 degrees. Clear aligners command the fastest-growing treatment type as adult patients prioritize aesthetics and removability over fixed appliances. Adolescents still generate the largest volume pool, though adult demand is accelerating fastest across teleorthodontics and comprehensive care service models.
FDA 510(k) pathways govern clear aligner material biocompatibility and software-as-medical-device claims in the United States, while the EU MDR imposes stricter clinical evidence requirements on custom-manufactured orthodontic appliances sold in Europe. State dental boards regulate the scope of teleorthodontics, creating fragmented market access for remote treatment models. Stakeholders must monitor how AI-driven treatment planning algorithms reshape liability frameworks and whether group practice consolidation alters pricing power.
Market Dynamics
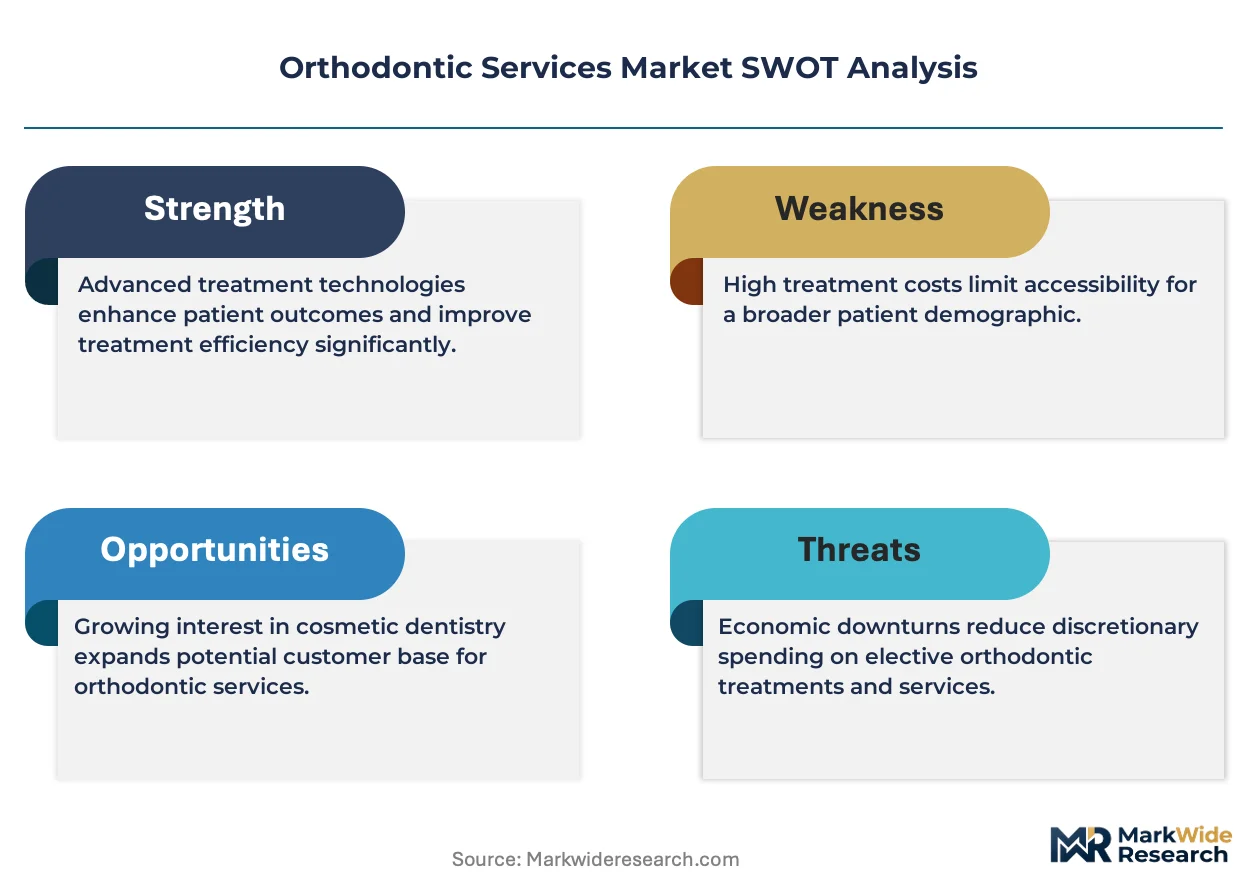
AI-driven treatment planning software is compressing clinical decision cycles and redistributing orthodontic expertise from chairside judgment to algorithm-assisted protocols, forcing incumbents to rebuild service delivery models around predictive analytics rather than experiential craft.
Growth Catalysts
- Teenage aesthetic demand:Adolescents and young adults now initiate orthodontic consultations based on social media-driven appearance standards, expanding addressable patient pools beyond traditional malocclusion severity thresholds.
- FDA 510(k) pathway acceleration:Streamlined clearances for software-as-medical-device claims in the United States are shortening commercialization timelines for digital orthodontics platforms.
- SmartTrack material science:Proprietary thermoplastic formulations with optimized elastic recovery properties are enabling predictable tooth movement across broader case complexity ranges.
Market Restraints
- Petrochemical input volatility:Medical-grade thermoplastic polyurethane supply chains remain tethered to oil price fluctuations, compressing aligner manufacturing margins during feedstock spikes.
- EU MDR clinical evidence burdens:Stricter documentation requirements for custom-manufactured orthodontic appliances in Europe are extending regulatory timelines and elevating compliance costs for market entrants.
- Lingual fixed appliance substitution:Invisible fixed brackets retain preference among complex malocclusion cases, limiting clear aligner penetration in severe correction segments.
Strategic Opportunities
- Teleorthodontics channel expansion:Remote monitoring platforms are unlocking access to patients in rural and secondary urban markets previously underserved by specialist density concentration.
- Indian middle-class penetration:Rising disposable incomes and dental tourism infrastructure in India present expansion vectors for premium aligner brands seeking volume beyond saturated Western markets.
- AI-3D printing convergence:Integration of generative treatment algorithms with direct-print aligner manufacturing is collapsing traditional thermoforming steps and enabling same-day delivery models.
Industry Challenges
- Digital workflow integration friction:Legacy practice management systems resist seamless API connectivity with cloud-based treatment planning platforms, forcing costly middleware development.
- Orthodontist-dentist scope boundary disputes:State dental boards across the United States issue conflicting guidance on teleorthodontics supervision requirements, creating liability ambiguity for multi-state operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthodontic Services Market |
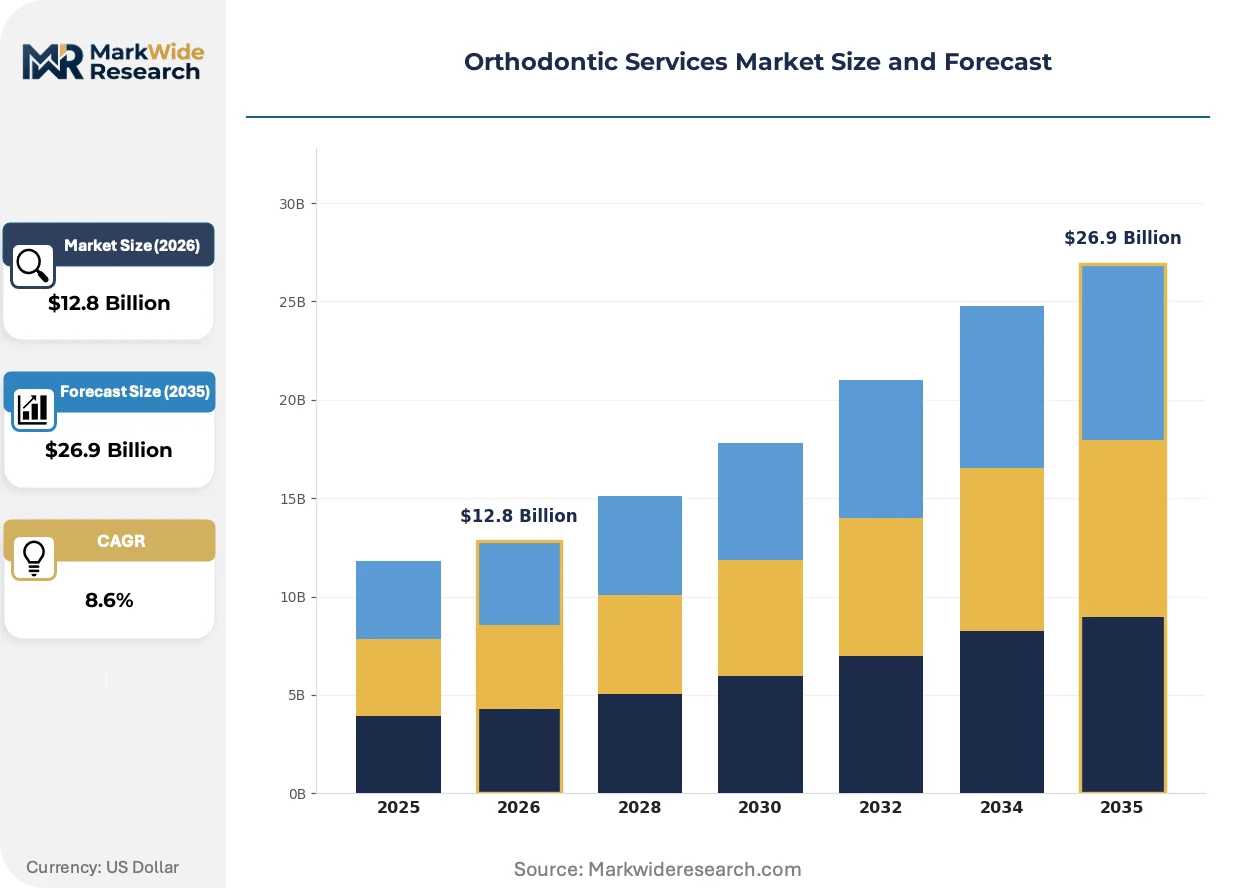
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Braces, Clear Aligners, Retainers, Space Maintainers Patient Age Group: Children, Adolescents, Adults, Seniors Practice Size: Solo Practice, Group Practice, Multispecialty Clinic, Hospital-Based Service Model: In-Person, Teleorthodontics, Mobile Services, Comprehensive Care |
| Companies Covered | Align Technology, Inc., Dentsply Sirona, Envista Holdings Corporation, 3M Corporation, Henry Schein, Inc., Ormco Corporation, American Orthodontics, Solventum Corporation, Institut Straumann AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthodontic Services Market Emerging Trajectories
Orthodontic service delivery is fragmenting across three simultaneous vectors: hardware miniaturization, algorithmic treatment personalization, and channel disintermediation. Each vector carries distinct competitive implications for incumbents and entrants.
Intraoral scanning hardware is bifurcating the diagnostic workflow between chairside capture and remote patient-submitted impressions. Specialist practices in the United States and Germany are deploying sub-$5,000 handheld scanners to replace physical mold logistics, while direct-to-consumer brands rely on smartphone-guided home impression kits. This hardware democratization is compressing the traditional orthodontist-laboratory-patient triad into bilateral digital relationships.
EU MDR implementation is tightening clinical evidence requirements for custom orthodontic appliances sold in Europe. Manufacturers must now submit prospective patient outcome data for CE marking renewals, elevating post-market surveillance costs. Smaller aligner brands without established clinical trial infrastructure are withdrawing from European markets or seeking notified body partnerships in Switzerland.
Subscription-based treatment monitoring is displacing per-visit fee structures in adult cosmetic orthodontics. Patients in metropolitan United States markets increasingly prefer flat-rate packages bundling aligners, remote check-ins, and refinement guarantees over itemized clinical billing. This preference shift is pressuring traditional practices to unbundle comprehensive care into modular service tiers or risk patient defection to platform-based competitors.
Orthodontic Services Market Segmentation
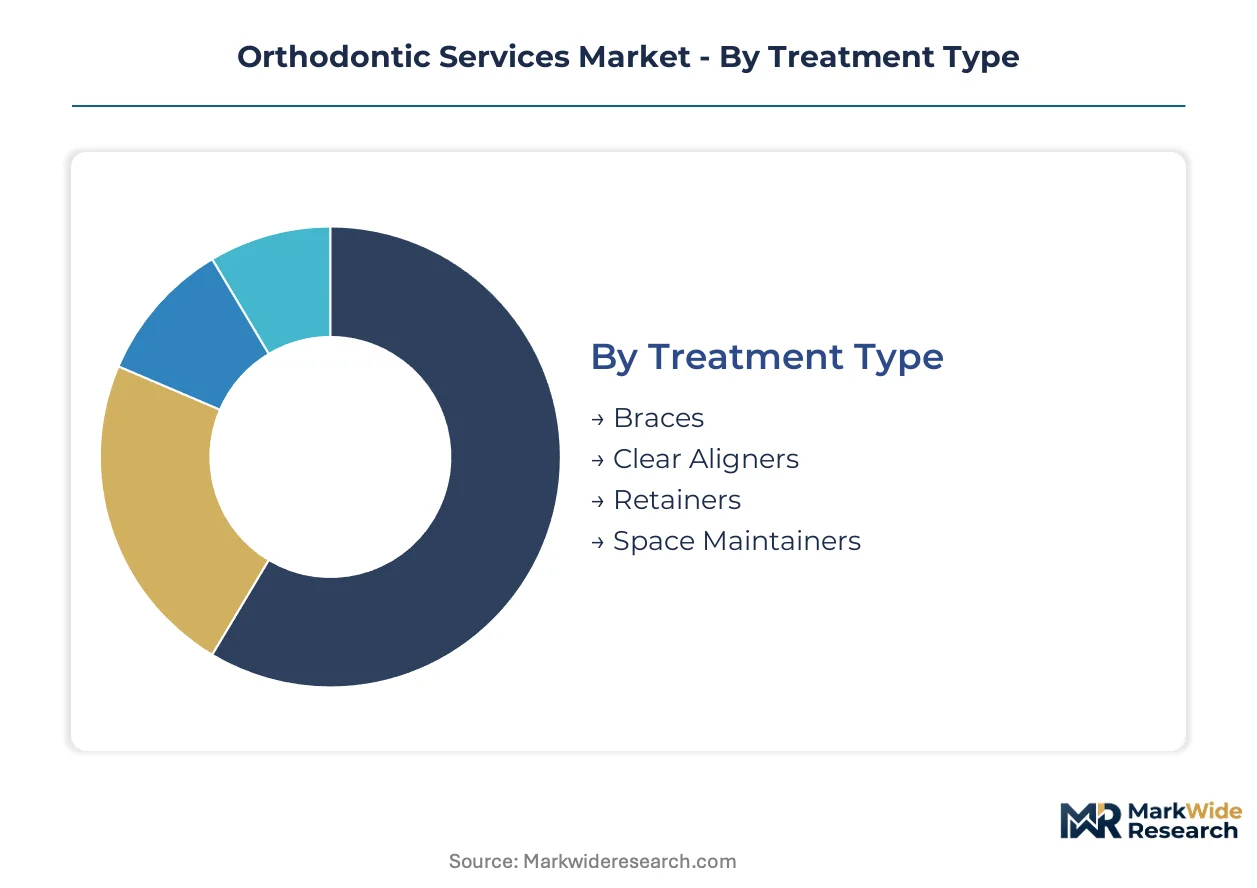
Orthodontic services fragment across four structural dimensions that reshape competitive positioning and regulatory exposure. Treatment modality determines FDA 510(k) pathway requirements, while patient age and service delivery channel dictate reimbursement mechanics and liability frameworks.
Treatment Type:
FDA 510(k) clearance pathways diverge sharply across mechanical versus removable appliance categories, with material biocompatibility testing and software-as-medical-device claims triggering distinct review timelines.
- Clear Aligners:Thermoplastic polyurethane appliances manufactured through CAD/CAM workflows and 3D thermoforming. Demand concentrates among adults aged 25-40 in metropolitan United States markets seeking aesthetic removability; FDA streamlined software claims are compressing commercialization timelines for new entrants.
- Braces:Fixed mechanical appliances employing nickel-titanium archwires and bonded brackets to apply continuous orthodontic force. Adolescent patients in employer-sponsored dental benefit plans drive volume; lingual bracket systems retain preference for complex malocclusion cases beyond aligner capability.
- Retainers:Post-treatment stabilization devices including Hawley wire-acrylic and vacuum-formed Essix variants. Orthodontist-dispensed retention protocols dominate, though direct-to-consumer subscription models are emerging for long-term maintenance.
- Space Maintainers:Passive appliances preserving arch length following premature tooth loss in pediatric patients. Pediatric dental practices and hospital-based dentistry programs handle the majority of fittings.
Braces handle the majority of throughput; clear aligners are expanding most quickly on share.
Patient Age Group:
Reimbursement mechanics and treatment motivation vary dramatically across developmental stages, from Medicaid-covered pediatric interceptive care to out-of-pocket adult cosmetic services.
- Adolescents:Patients aged 12-18 undergoing comprehensive correction during peak craniofacial growth velocity. Parental insurance coverage and social media-driven appearance standards accelerate consultation rates; traditional fixed appliances remain dominant for compliance-controlled treatment.
- Adults:Patients over 18 seeking aesthetic improvement or relapse correction, typically self-funding through flexible spending arrangements or installment financing. Teleorthodontics platforms and direct-to-consumer aligner channels concentrate demand among time-constrained professionals in dense urban markets.
- Children:Patients under 12 receiving interceptive orthopedic guidance or habit-breaking appliances. Pediatric dental homes and early orthodontic screening programs identify candidates; Medicaid and CHIP coverage shapes access geography.
- Seniors:Patients over 65 addressing tooth migration, occlusal collapse, or implant-orthodontic coordination. Medicare exclusion of routine dental services limits penetration; affluent retirees in Florida and Arizona retirement clusters drive private-pay volume.
Adolescents generate the largest absolute patient pool; adults are climbing the fastest on volume contribution.
Practice Size:
Capital intensity and digital workflow adoption scale non-linearly with practice configuration, reshaping competitive economics across solo operator versus institutional platforms.
- Group Practice:Multi-clinician platforms with centralized treatment planning and shared overhead. United States suburban markets show concentration; private equity consolidation is standardizing intraoral scanning and aligner fulfillment workflows.
- Solo Practice:Individual orthodontist owner-operators with chairside-centric service delivery. Rural and secondary urban markets retain significant solo density; legacy practice management systems resist API integration with cloud-based planning platforms.
- Multispecialty Clinic:Integrated dental-medical facilities combining orthodontics with oral surgery, periodontics, and prosthodontics. Hospital-adjacent locations and academic health centers dominate; complex interdisciplinary cases requiring orthognathic coordination drive referral patterns.
- Hospital-Based:Craniofacial and cleft palate programs within academic medical centers. Federally qualified health centers and children's hospitals handle Medicaid-heavy pediatric deformity cases; residency training pipelines sustain staffing.
Group practices are capturing share fastest from solo operators; hospital-based settings handle the most complex case throughput.
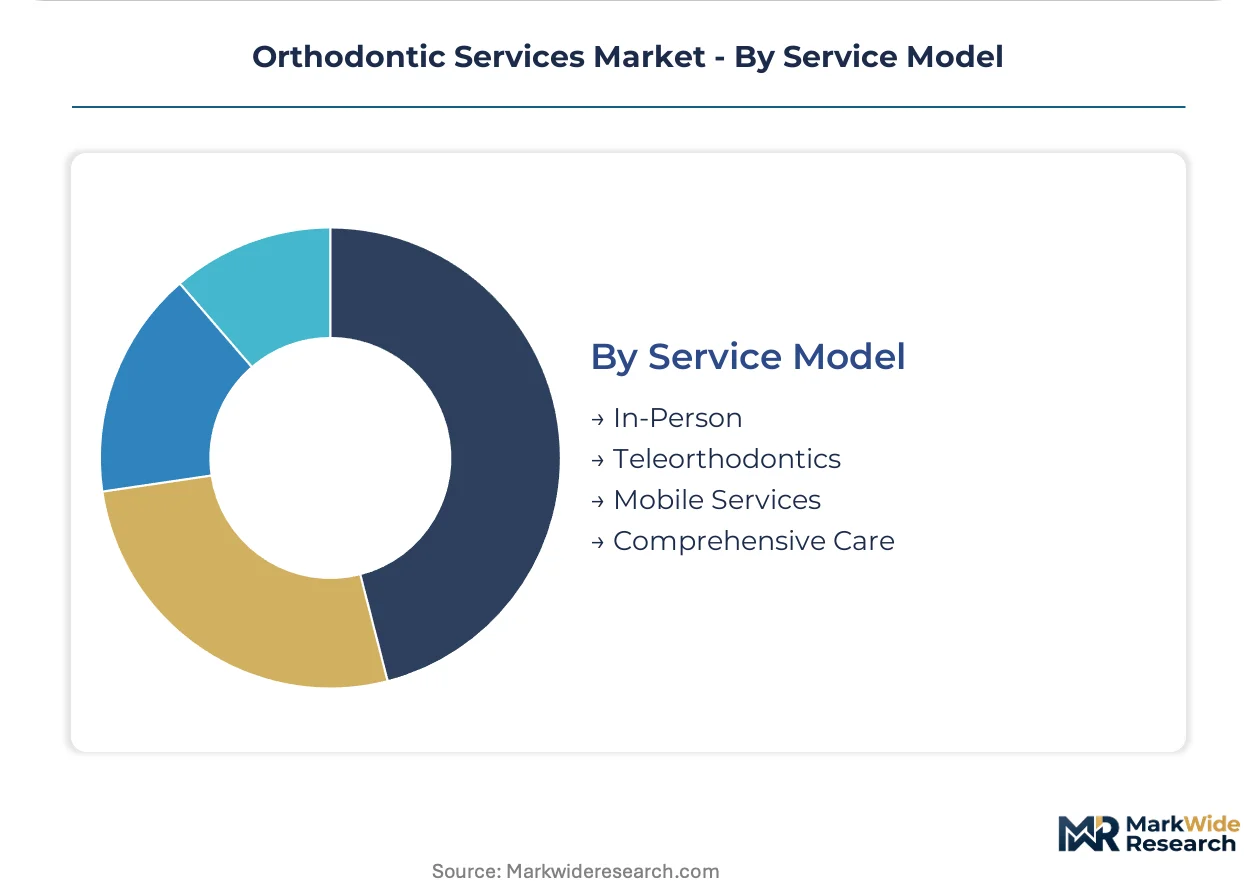
Service Model:
Channel disintermediation and supervision requirements fragment liability exposure, with state dental boards issuing conflicting guidance on remote orthodontic monitoring.
- In-Person:Traditional chairside delivery with direct clinician-patient contact at each appointment. Specialist practices in high-density metropolitan markets retain this model; per-visit fee structures face pressure from subscription alternatives.
- Teleorthodontics:Remote monitoring platforms employing smartphone photography and AI-assisted progress tracking. Direct-to-consumer brands and hybrid practitioner models are expanding fastest; state board supervision requirements create multi-state operational friction.
- Mobile Services:Portable equipment deployment to schools, nursing facilities, and rural communities. School-based sealant and screening programs in Texas and California incorporate orthodontic triage; reimbursement coding limits sustainability.
- Comprehensive Care:Bundled packages spanning diagnosis through retention with flat-rate pricing. Adult cosmetic patients in United States coastal metros prefer this predictability; refinement guarantees and remote monitoring inclusions differentiate platform offerings.
In-person service handles the majority of case volume; teleorthodontics is gaining share fastest among adult cosmetic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthodontic service supply chains concentrate manufacturing and digital platform development in the United States, Germany, China, and Switzerland, with clinical delivery networks extending through localized specialist practices and telehealth platforms.
United States
Employer-sponsored dental benefits and direct-to-consumer aligner channels coexist to drive patient access across metropolitan markets. FDA 510(k) pathways govern clear aligner material biocompatibility and software-as-medical-device claims, compressing commercialization timelines for digital platforms. Los Angeles and New York City clusters anchor specialist practice density, while teleorthodontics platforms expand into secondary urban markets.
Germany
Integrated digital workflow ecosystems spanning intraoral scanning to finishing command premium positioning among European practitioners. EU MDR imposes stricter clinical evidence requirements on custom-manufactured orthodontic appliances, extending regulatory timelines for market entrants. Munich and Stuttgart industrial corridors concentrate precision manufacturing capabilities for orthodontic hardware.
China
Rising middle-class disposable incomes and dental tourism infrastructure accelerate demand for aesthetic correction services. NMPA medical device registration requirements shape market access for imported aligner brands and domestic manufacturers. Shanghai and Beijing metropolitan areas concentrate private dental clinic chains and digital orthodontics platform development.
India
Expanding dental tourism infrastructure and rising disposable incomes present volume opportunities for premium aligner brands beyond saturated Western markets. CDSCO medical device regulations govern import and local manufacturing compliance for orthodontic appliances. Mumbai and Bengaluru clusters anchor specialist training programs and private dental hospital networks.
Switzerland
Precision manufacturing heritage and notified body partnerships attract smaller aligner brands seeking CE marking pathways amid EU MDR complexity. Swissmedic regulations provide alternative market access frameworks for custom orthodontic appliances. Basel and Zurich regions concentrate dental technology R&D and specialized manufacturing operations.
Orthodontic Services Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the orthodontic services value chain, creating tiered competitive dynamics rather than consolidated control. The vendor base spans proprietary material science specialists, integrated digital workflow providers, and distribution-dense service platforms. Three strategic archetypes dominate: technology-anchored innovators controlling precision standards, workflow integrators spanning hardware-to-software stacks, and scale-driven distributors capturing practice-level purchasing decisions. Competitive moves concentrate on M&A consolidation of digital planning capabilities and strategic partnerships bridging manufacturer-practitioner relationships.
Within the technology-anchored tier, Align Technology, Inc. exemplifies proprietary material science differentiation, while Dentsply Sirona occupies a position spanning integrated digital ecosystems from diagnostic capture through treatment completion. Henry Schein, Inc. represents distribution-density competitive positioning across North American dental practice procurement channels. These three companies illustrate how divergent strategic vectors—material innovation, workflow integration, and supply chain control—can coexist without direct substitution.
| Leading Market Players |
|---|
| Align Technology, Inc. |
| Dentsply Sirona |
| Envista Holdings Corporation |
| 3M Corporation |
| Henry Schein, Inc. |
| Ormco Corporation |
| American Orthodontics |
| Solventum Corporation |
| Institut Straumann AG |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for medical-grade thermoplastic polyurethane lock in both feedstock access and cost visibility for aligner manufacturers, insulating production schedules from petrochemical spot market volatility while compressing margin flexibility during oil price spikes.
Pricing Analysis
FDA 510(k) dictates the pricing tier structure across orthodontic services, separating premium proprietary aligner systems from standard practitioner-dispensed alternatives and economy direct-to-consumer channels. Price differentiation rests on material certification grade and geographic delivery cost, with coastal metropolitan practices commanding premiums over inland markets. Cost compression in the economy tier is intensifying because direct-to-consumer brands are absorbing remote monitoring overhead into flat-rate bundles. Employer-sponsored dental benefit enrollees show lowest price sensitivity; self-funding adult cosmetic patients exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for custom-manufactured aligners stretch across thermoforming, quality verification, and cross-border logistics, creating working capital intensity that favors scaled operators with captive production. Supply concentrates in the United States, China, and Germany, with thermoplastic polyurethane resin drawing from petrochemical feedstocks and nickel-titanium archwires sourcing from specialized metallurgy facilities. Single-source vulnerability in medical-grade polymer grades threatens continuity. Distribution runs through dental supply distributors, direct-to-consumer fulfillment centers, and hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FDA-cleared AI treatment planning algorithms concentrates competitive advantage among early movers, creating acquisition premiums for platforms with validated software-as-medical-device claims and established clinical outcome databases.
For Market Incumbents: Compound material science differentiation through proprietary thermoplastic formulations that extend case complexity range beyond commodity aligner capabilities. Defend against direct-to-consumer substitution by embedding remote monitoring into comprehensive care bundles. Prioritize vertical integration into intraoral scanning hardware to capture diagnostic workflow economics. For New Entrants and Emerging Players: Lead with teleorthodontics penetration in Indian and Southeast Asian middle-class markets where specialist density remains thin and smartphone adoption enables remote impression capture. Target adult cosmetic segments in secondary United States urban markets underserved by incumbent platform coverage. Deploy hybrid practitioner partnerships to navigate state dental board supervision requirements. For Investors and Strategic Acquirers: Capital is best deployed toward digital workflow integrators possessing cloud-based treatment planning platforms with API-ready practice management connectivity. Long-term viability hinges on regulatory moats around software-as-medical-device claims and clinical evidence libraries. Monitor FDA enforcement discretion on direct-to-consumer supervision models as the inflection signal for teleorthodontics addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software Clearance | Accelerates commercialization timelines for AI-assisted treatment planning platforms against legacy competitors. |
| Proprietary Material Science Investment | SmartTrack-type thermoplastic formulations sustain margin leadership through predictable elastic recovery properties. |
| Teleorthodontics Platform Expansion | Unlocks rural and secondary urban patient pools previously constrained by specialist geographic concentration. |
| Practice Management API Integration | Resolves digital workflow friction that fragments cloud-based planning adoption across legacy solo operators. |
| Indian Market Localization Partnership | Captures rising disposable income and dental tourism infrastructure beyond saturated Western demand centers. |
Methodological Framework
A spread of perspectives from orthodontists, dental supply procurement managers, GPO contracts administrators, and aligner manufacturing executives converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CDSCO medical device registrations, EU MDR notified body documentation, and hospital procurement database extracts. Bottom-up patient volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Segmentation dimensions modeled include treatment modality, patient age cohort, practice configuration, and service delivery channel. CAGRs were derived from trend extrapolation anchored in historical adoption curves and regulatory pathway timelines. Forecast inputs incorporated AI treatment planning penetration rates and teleorthodontics supervision model evolution across state dental board jurisdictions.
Forecasts assume regulatory continuity in FDA 510(k) software claims, EU MDR custom appliance requirements, and state dental board telehealth guidance; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
United States Dental Services Market
Dental Services
Global Dental Support Organizations Market
Dental Services
Dental Market
Dental Services
Teledentistry Market
Dental Services
Periodontal Dental Service Market
Dental Services
Dental Services Market
Dental Services
Dental Fluoride Treatment Market
Dental Services
EMEA Dental Service Organization Market
Dental Services
Microdontia Treatment Market
Dental Services
US Dental Chains Market
Dental Services
Chronic Gingivostomatitis Treatment Market
Dental Services
Dental Service Organization Market