
 United States Dental Services Market | 2026-2036
United States Dental Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Dental Services Market Insights
Dental hygienist workforce shortages across the South and Midwest is unwinding appointment availability and forcing delivery model innovation. Heartland Dental leverages its multi-state practice footprint to sustain volume through centralized scheduling and staffing pools. Pacific Dental Services anchors its growth in technology-integrated offices that compete on patient throughput and clinical consistency.
Dental services encompass the diagnosis, prevention, treatment, and management of oral conditions using procedures ranging from prophylactic cleanings to surgical implant placement with titanium alloy fixtures and ceramic restorations. The primary commercial purpose is maintaining or restoring masticatory function, aesthetics, and systemic health linked to periodontal status. Preventive care occupies the largest service volume due to recurring six-month visit patterns, while tele-dentistry represents the fastest-expanding delivery channel as state licensing boards adapt remote supervision rules. Cosmetic dentistry commands premium pricing and attracts substantial out-of-pocket spending from middle-income households seeking elective aesthetic enhancement.
The FDA regulates dental materials and radiation-emitting devices, while state dental boards governed by the American Dental Association's model act oversee practitioner licensure and scope-of-practice boundaries. OSHA mandates bloodborne pathogen protocols and hazard communication standards that shape clinic infrastructure investment and operational compliance costs. Stakeholders must monitor state-level Medicaid reimbursement rate negotiations and scope-of-practice reform for dental therapists as these decisions will reshape competitive access in underserved counties.
Market Dynamics
Workforce scarcity among dental hygienists is compressing appointment availability across the South and Midwest, forcing multi-location practice groups to restructure staffing models and invest in centralized scheduling infrastructure.
Growth Catalysts
- Medicaid expansion in holdout states:State-level negotiations over reimbursement rates for adult dental coverage are unlocking pent-up demand in rural counties previously excluded from preventive care networks.
- Tele-dentistry licensing reforms:State dental boards adapting remote supervision rules under the ADA model act are enabling asynchronous consultation models that extend specialist reach into underserved markets.
- Retiree migration to Sun Belt metros:Population inflows to Phoenix, Tampa, and Austin are outpacing provider supply growth, creating volume absorption capacity for scalable practice platforms.
Market Restraints
- Titanium alloy supply concentration:Implant fixture manufacturing depends on a narrow supplier base, exposing practices to input cost volatility and extended procurement timelines.
- OSHA compliance capex burden:Bloodborne pathogen protocol mandates require continuous clinic infrastructure investment in sterilization equipment and ventilation systems.
- Scope-of-practice fragmentation:Inconsistent state-level authorization for dental therapists creates operational friction for multi-state practice groups seeking standardized care protocols.
Strategic Opportunities
- Appalachian and Delta region penetration:Federally Qualified Health Centers in these dental deserts present partnership opportunities for teledentistry-enabled specialty consultation networks.
- School-based screening integration:Pediatric oral health programs embedded in public education systems create captive patient acquisition channels with recurring visit patterns.
- AI-assisted radiographic interpretation:FDA-cleared diagnostic algorithms are converging with cloud-based practice management platforms to enable chairside decision support and coding optimization.
Industry Challenges
- Hygienist training pipeline gaps:Accelerated retirement among experienced practitioners is colliding with enrollment constraints in accredited programs, compressing labor supply recovery timelines.
- Legacy practice management system integration:Consolidated practice groups face data migration friction when unifying disparate electronic health record architectures across acquired locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Dental Services Market |
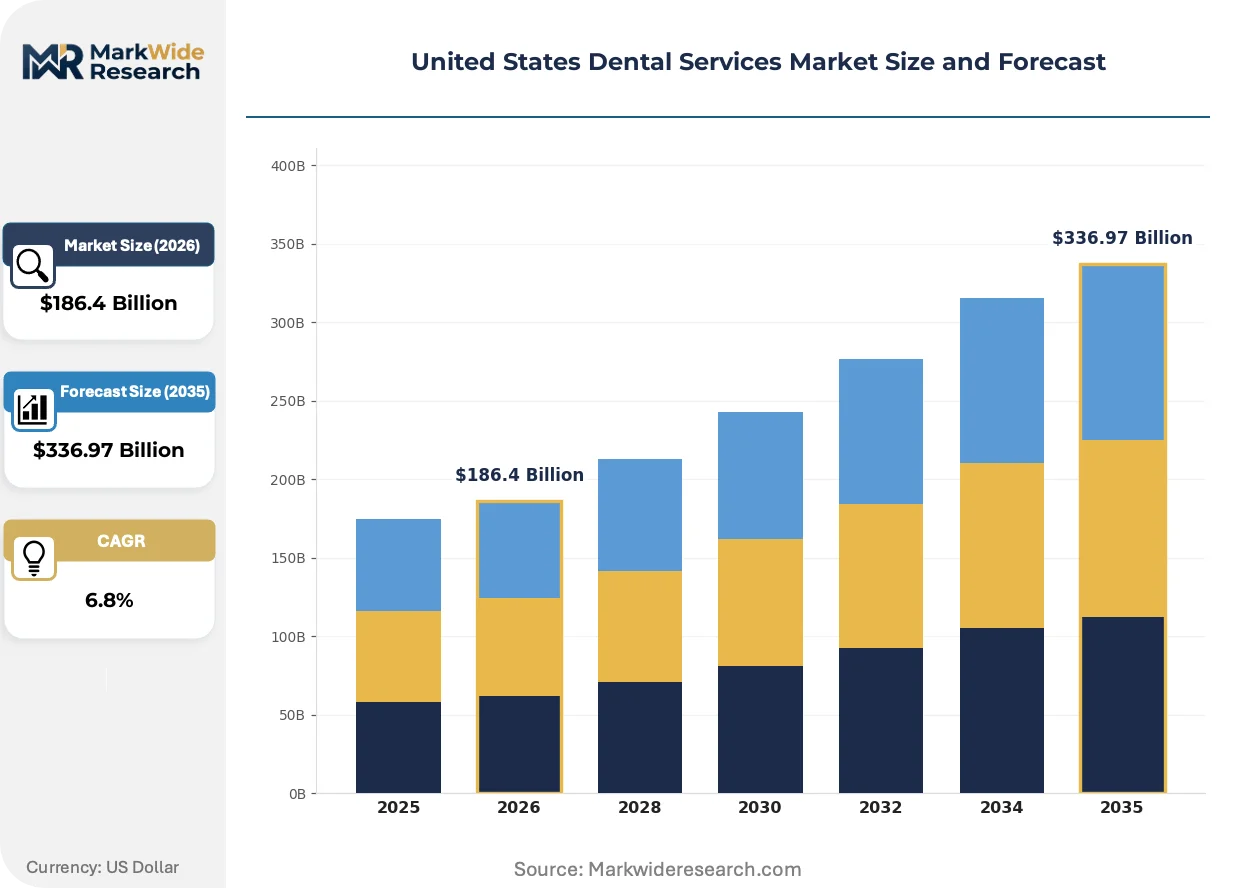
| Market Size in 2026 | $186.4 Billion |
| Market Size in 2035 | $336.97 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Care, Restorative Dentistry, Orthodontics, Cosmetic Dentistry Delivery Model: In-Office, Mobile Dentistry, Tele-Dentistry, Dental Clinics Patient Type: Adults, Children, Seniors, Families Payer Type: Private Insurance, Medicaid, Out-of-Pocket, Employer-Sponsored |
| Companies Covered | Heartland Dental, Pacific Dental Services, Smile Brands Inc., Aspen Dental Management, Inc., Dental Care Alliance, Western Dental, Great Expressions Dental Centers, InterDent, MB2 Dental, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Dental Services Market Trends and Innovations
Digital workflow integration is restructuring clinical productivity benchmarks across the United States dental services market, compressing chair time requirements and elevating throughput expectations for reimbursed procedures.
Intraoral scanning technology is supplanting conventional polyvinyl siloxane impressions in restorative and orthodontic workflows. Multi-location practice groups are deploying chairside scanners to eliminate laboratory shipping delays and same-day crown fabrication. This shift is compressing appointment counts per case completion and enabling higher daily patient volume targets without proportional staffing expansion.
State dental boards are harmonizing teledentistry supervision standards under revised interpretations of the ADA model act. These regulatory adaptations are enabling asynchronous specialist consultation for rural and incarcerated populations. Safety-net providers in Medicaid-dependent markets are deploying remote diagnostic platforms to extend endodontic and periodontal triage without physical specialist presence.
Employer-sponsored dental benefit structures are migrating toward tiered network designs that steer patients toward value-based practice partners. Large self-insured employers in manufacturing and logistics verticals are contracting directly with multi-location groups for predictable per-employee-per-month cost structures. This procurement evolution is most visible in Texas and Florida metropolitan corridors where employer concentration supports direct contracting at scale.
United States Dental Services Market Segmentation
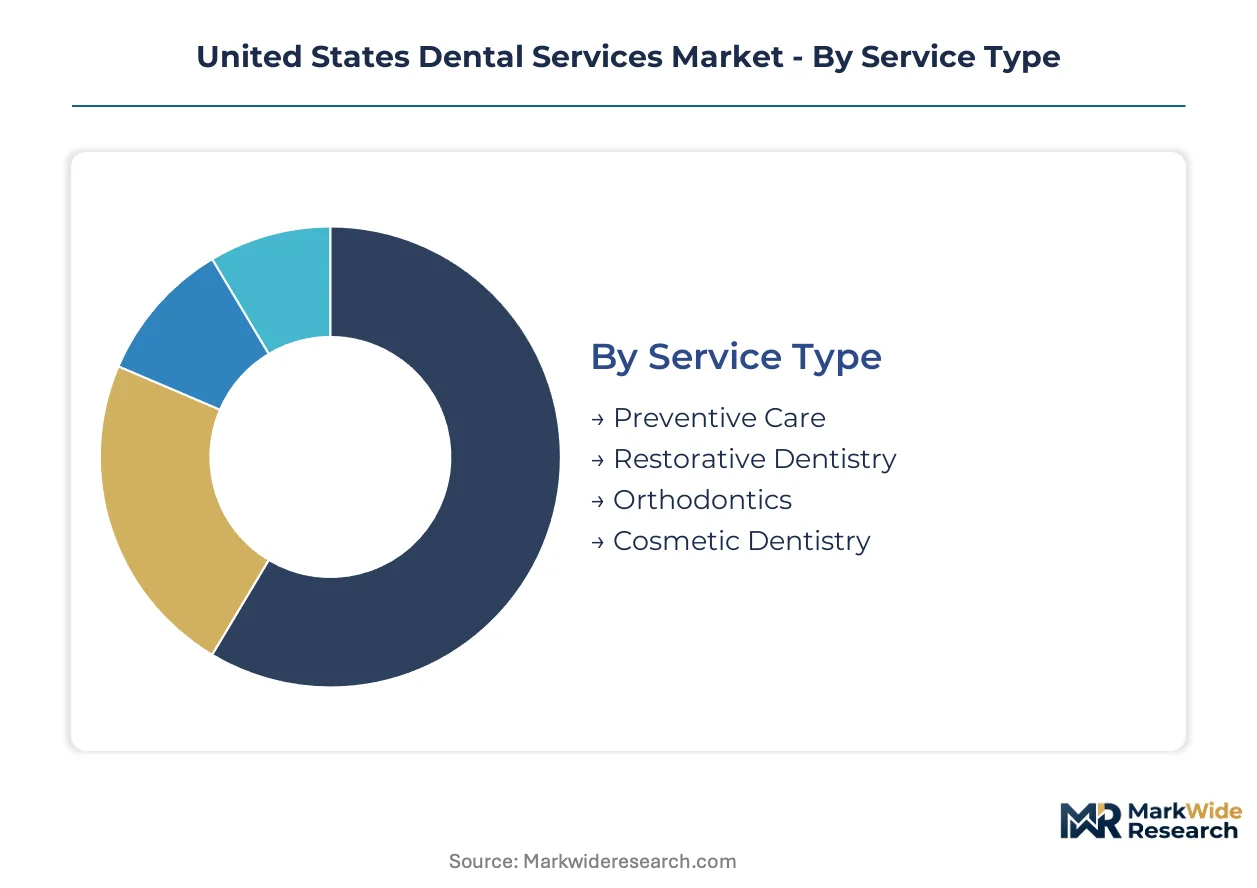
Service differentiation across the United States dental services market determines reimbursement rates, patient acquisition costs, and platform scalability. Understanding segment boundaries reveals where multi-location groups concentrate capital versus where independent practices retain defensible positions.
Service Type:
Margin pools concentrate in elective procedures where pricing escapes insurance fee schedules, while high-volume preventive services anchor patient lifetime value calculations.
- Preventive Care:Prophylactic cleanings, fluoride applications, and periodontal maintenance form the recurring revenue base through six-month visit cycles. Demand concentrates in employer-sponsored networks across Texas and Florida metros where large self-insured manufacturers negotiate direct capitation contracts with multi-location groups.
- Cosmetic Dentistry:Veneers, whitening systems, and aesthetic bonding command premium out-of-pocket pricing with margins insulated from Medicaid reimbursement compression. Patient acquisition flows through social media channels in Sun Belt retirement corridors where discretionary spending on aesthetic enhancement exceeds national averages.
- Restorative Dentistry:Crowns, bridges, and implant-supported prosthetics using titanium alloy fixtures and ceramic restorations.
- Orthodontics:Clear aligner therapy and conventional bracket systems for malocclusion correction.
Preventive Care holds installed capacity. Cosmetic Dentistry is rotating up the share rankings.
Delivery Model:
Volume distribution reflects regulatory adaptation speed, with states harmonizing teledentistry supervision rules under revised ADA model act interpretations.
- Tele-Dentistry:Asynchronous specialist consultation and remote diagnostic imaging extend endodontic and periodontal triage into dental deserts without physical presence. Safety-net providers in Medicaid-dependent Appalachian and Delta counties deploy FDA-cleared radiographic platforms to bridge specialist access gaps.
- In-Office:Traditional chairside delivery with direct practitioner-patient contact remains the default for surgical and complex restorative procedures.
- Mobile Dentistry:Portable equipment configurations serving schools, nursing facilities, and correctional institutions.
- Dental Clinics:Federally Qualified Health Centers and community health centers targeting underserved populations.
In-Office retains procedure complexity. Tele-Dentistry is climbing the fastest as state boards finalize remote supervision frameworks.
Patient Type:
Customer lifetime value varies sharply across age cohorts, with pediatric acquisition creating decades of subsequent adult service demand.
- Children:School-based oral health screening programs embedded in public education systems generate captive patient pipelines with recurring visit patterns. Pediatric utilization expands as districts integrate Medicaid-funded preventive services into mandatory health requirements.
- Seniors:Retiree migration to Phoenix, Tampa, and Austin metros outpaces provider supply growth, creating absorption capacity for implant and periodontal maintenance services.
- Adults:Working-age populations driving employer-sponsored benefit utilization.
- Families:Multi-generational household units consolidating care coordination.
Children represent the longest duration revenue stream. Seniors are gaining share fastest through demographic migration patterns.
Payer Type:
Reimbursement stability diverges between capitated employer contracts and state Medicaid rate volatility.
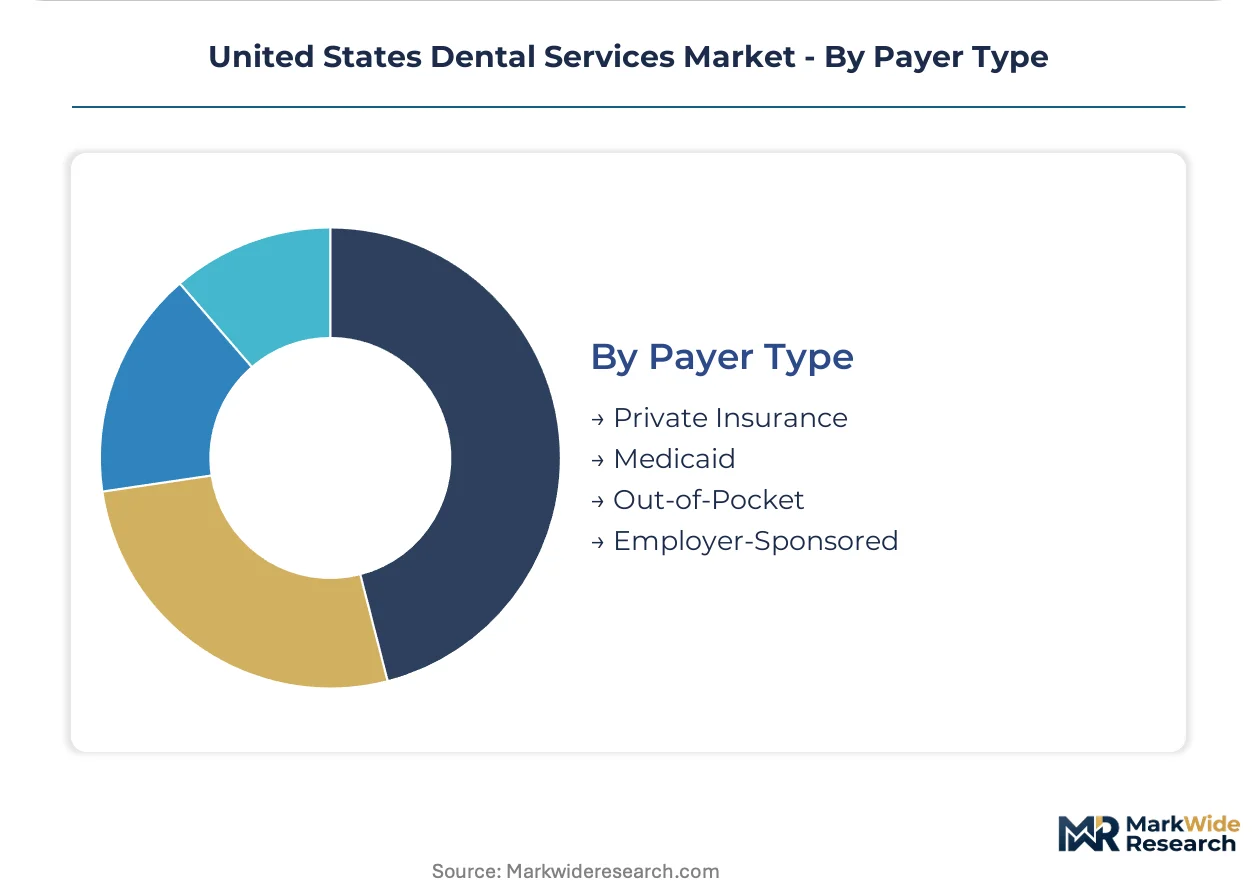
- Private Insurance:Commercial dental benefit administrators negotiate fee-for-service schedules with network participation requirements. Tiered network designs steer patients toward value-based practice partners in manufacturing and logistics verticals.
- Medicaid:State-level adult dental coverage expansion in holdout states unlocks pent-up demand in rural counties previously excluded from preventive networks. Reimbursement rate negotiations vary by state, compressing margins in markets with low provider participation.
- Out-of-Pocket:Direct consumer payment for elective procedures outside insurance coverage.
- Employer-Sponsored:Self-insured employers contracting directly with multi-location groups for per-employee-per-month cost structures.
Private Insurance holds contracted volume. Medicaid is expanding fastest where expansion states negotiate sustainable reimbursement floors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Phoenix and Tampa dental markets substantially exceeds that in Cleveland and Detroit, reflecting divergent retiree inflows and provider scarcity ratios. Sun Belt metros absorb implant and periodontal demand faster than new graduates enter regional workforces. Medicaid reimbursement floors in expansion states reshape rural access economics.
Southwest
Phoenix and Austin dental markets absorb retiree migration volumes that outpace hygienist training pipeline output. Arizona and Texas Medicaid programs negotiate adult dental coverage rates that unlock preventive demand in previously excluded rural counties. Federally Qualified Health Centers in El Paso and Tucson deploy teledentistry platforms to bridge endodontic specialist access gaps.
Southeast
Tampa and Miami metropolitan corridors concentrate employer-sponsored dental benefit contracting with self-insured logistics and manufacturing firms. Florida state dental boards harmonize remote supervision rules under revised ADA model act interpretations, enabling asynchronous specialist consultation. School-based oral health screening programs in Orange and Hillsborough counties generate captive pediatric patient pipelines.
Midwest
Chicago and Detroit markets face compressed appointment availability as accelerated hygienist retirement collides with enrollment constraints in accredited training programs. Illinois and Michigan Medicaid rate negotiations vary by county, creating patchwork participation incentives for preventive care networks. Dental Care Alliance leverages multi-state scheduling infrastructure to sustain volume across Michigan and Ohio locations.
West Coast
Los Angeles and Seattle metropolitan areas anchor technology-integrated practice expansion with intraoral scanning deployment and same-day crown fabrication workflows. California OSHA mandates shape sterilization equipment investment cycles and ventilation system upgrades. Pacific Dental Services concentrates cloud-based practice management platform deployment across Southern California and Pacific Northwest markets.
Northeast
Boston and New York City dental markets retain independent practice density despite multi-location group expansion pressure. Massachusetts and New York state scope-of-practice boundaries for dental therapists create operational friction for standardized care protocols. Great Expressions Dental Centers maintains presence across Connecticut and New Jersey suburban corridors with employer-contracted volume.
United States Dental Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United States dental services market. Consolidated multi-location practice groups deploy centralized scheduling and cloud-based practice management platforms to compress operational overhead, while regional independents retain patient relationships through embedded community presence. Three archetypes dominate: technology-integrated platform operators, cost-focused volume aggregators, and specialty-anchored regional networks. Competitive dynamics center on workforce recruitment infrastructure and payer contract scale.
Among multi-location platform operators, Heartland Dental and Pacific Dental Services exemplify divergent strategic vectors. Heartland Dental occupies a position within the cost-optimization archetype through centralized staffing pools and standardized procurement. Pacific Dental Services anchors the technology-integrated tier with chairside scanner deployment and digital workflow compression. Smile Brands Inc. sits within the mid-market consolidation space, representing volume aggregation without full technology stack integration.
| Leading Market Players |
|---|
| Heartland Dental |
| Pacific Dental Services |
| Smile Brands Inc. |
| Aspen Dental Management, Inc. |
| Dental Care Alliance |
| Western Dental |
| Great Expressions Dental Centers |
| InterDent |
| MB2 Dental |
| Others |
Pricing and Supply Chain Analysis
Capitation contracts with self-insured employers lock in both titanium alloy fixture supply access and predictable per-employee-per-month price visibility across Texas and Florida metropolitan corridors. These multi-year agreements insulate multi-location practice groups from Medicaid reimbursement volatility while committing volume to specialized implant manufacturers.
Pricing Analysis
The customization-premium spread separates standard preventive prophylaxis from configured-to-order cosmetic veneer and implant-supported prosthetic procedures. Pricing stratifies across premium cosmetic tiers, standard restorative bundles, and economy preventive maintenance based on material grade and chairside technology deployment. Cost compression in standard preventive tiers is intensifying because employer-sponsored networks negotiate direct capitation contracts that compress fee-for-service margins. Medicaid-dependent patient segments exhibit highest price sensitivity, while elective aesthetic patients in Sun Belt retirement corridors demonstrate lowest sensitivity to out-of-pocket pricing.
Supply Chain Analysis
Titanium alloy concentrate refining in China, Japan, and Germany anchors implant fixture manufacturing capacity for United States dental practices. Raw material flows draw from zirconium dioxide ceramic suppliers, precision-milled titanium billet producers, and polyvinyl siloxane impression material manufacturers. Single-source vulnerability concentrates in titanium sponge processing, where geopolitical friction threatens input cost stability. Distribution runs through regional dental supply distributors maintaining sterilization equipment and radiographic device inventories for multi-location practice groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States dental services market functions as a defensive-moat story where regulatory entrenchment through state dental board licensure and scope-of-practice boundaries protects incumbent positions from rapid competitive displacement.
For Market Incumbents: Shield market position by deepening backward integration into cloud-based practice management platforms that lock in acquired practice data architectures and compress competitor switching incentives. Fortify hygienist workforce pipelines through accredited program sponsorships and accelerated certification pathways to counter emerging teledentistry-enabled competitors exploiting remote supervision rule harmonization.
For New Entrants and Emerging Players: Anchor in Appalachian and Delta region Federally Qualified Health Center partnerships where specialist access gaps create penetrable white-space for asynchronous consultation platforms. Target Medicaid-dependent rural counties in holdout expansion states where pent-up preventive demand exceeds incumbent provider participation. Deploy FDA-cleared radiographic interpretation algorithms as the primary go-to-market wedge against legacy in-office diagnostic workflows.
For Investors and Strategic Acquirers: Multi-location technology-integrated platform operators with demonstrated chairside scanner deployment and same-day crown fabrication capabilities represent the highest-conviction acquisition target archetype. Long-term viability over the next decade hinges on capturing employer-sponsored direct contracting relationships before manufacturing and logistics verticals consolidate procurement around preferred provider networks. Watch state-level dental therapist scope-of-practice expansion as the critical inflection signal for care protocol standardization and multi-state operational scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Practice Management Platform Deployment | Centralized scheduling infrastructure enables Heartland Dental and Pacific Dental Services to sustain volume across dispersed geographic footprints. |
| FDA-Cleared AI Radiographic Interpretation Integration | Chairside diagnostic algorithms converge with practice management systems to compress coding optimization timelines and elevate triage accuracy. |
| Employer-Sponsored Direct Contracting Expansion | Self-insured manufacturers in Texas and Florida metros negotiate capitation structures that bypass traditional commercial benefit administrators. |
| Teledentistry-Enabled Specialty Consultation Networks | Remote endodontic and periodontal triage extends specialist reach into Appalachian and Delta dental deserts without physical presence requirements. |
| Intraoral Scanner Deployment for Same-Day Fabrication | Digital workflow compression eliminates laboratory shipping delays and enables higher daily patient throughput without proportional staffing expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dental group executives, state dental board administrators, hygienist training program directors, and employer benefits managers. Secondary validation drew from FDA device clearance databases, CMS Medicaid reimbursement rate filings, OSHA compliance guidance documents, and ADA model act interpretation records. Bottom-up practice location counts and top-down service expenditure estimates were triangulated to anchor market sizing.
Across the analysis window, the forecasting framework modeled segmentation dimensions including service type, delivery model, patient age cohort, and payer category alongside geographic provider density ratios. CAGRs were derived from historical utilization trend extrapolation adjusted for retiree migration patterns and workforce pipeline constraints. State-level Medicaid expansion negotiations and teledentistry supervision rule adaptations served as key scenario inputs.
Material uncertainties — state reimbursement rate volatility, titanium alloy supply disruptions, and accelerated hygienist retirement waves — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory adaptation speed and employer contracting evolution that practitioners should keep alternative scenarios live as demographic migration patterns and scope-of-practice reform negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
US Dental Chains Market
Dental Services
EMEA Dental Service Organization Market
Dental Services
Dental Market
Dental Services
Periodontal Dental Service Market
Dental Services
Teledentistry Market
Dental Services
Microdontia Treatment Market
Dental Services
Dental Services Market
Dental Services
Dental Fluoride Treatment Market
Dental Services
Chronic Gingivostomatitis Treatment Market
Dental Services
Dental Service Organization Market
Dental Services
Orthodontic Services Market
Dental Services
Global Dental Support Organizations Market