
 Dental Services Market | 2026-2036
Dental Services Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Services Market Intelligence
Multi-source procurement of clinical supplies and laboratory partnerships is consolidating as dental service organizations scale regionally. Heartland Dental leverages centralized purchasing to compress supply costs across hundreds of affiliated practices. Aspen Dental Management, Inc. anchors its model on standardized care protocols and consumer-facing brand uniformity. Pacific Dental sustains technology leadership through early deployment of AI-assisted diagnostic platforms in its owner-doctor network.
Dental services encompass the diagnosis, prevention, and treatment of oral conditions through procedures ranging from routine prophylaxis to complex maxillofacial reconstruction, typically delivered in outpatient settings using sterilized handpieces, radiographic imaging, and biocompatible restorative materials. Preventive care generates the steadiest patient visit frequency and insurance reimbursement reliability, while orthodontics captures premium out-of-pocket spending from adult cosmetic demand. Tele-dentistry represents the fastest-expanding treatment modality as asynchronous image review and remote consultation protocols reduce geographic barriers to specialist access.
FDA regulates medical devices used in dental procedures, including CAD/CAM milling units and 3D-printed surgical guides, while HIPAA mandates encryption standards for digital patient records exchanged between clinics and payers. State dental boards govern scope-of-practice rules that determine whether hygienists may administer anesthesia or place restorations without direct dentist supervision. Stakeholders must monitor how state-level Medicaid reimbursement adjustments and emerging FDA guidance on AI diagnostic tools reshape capital deployment and workforce training priorities.
Market Dynamics
Private equity consolidation of dental service organizations is compressing the independent practice model, as centralized procurement and standardized protocols displace fragmented ownership structures across outpatient networks.
Growth Catalysts
- FDA 510(k) clearance acceleration:Streamlined pathways for digital intraoral scanners and CAD/CAM systems shorten technology adoption cycles from years to months.
- Japan's geriatric implant demand:Super-aged population demographics drive prosthetic and implant service volumes beyond replacement rates in other developed economies.
- Tele-dentistry reimbursement expansion:State-level Medicaid program adjustments legitimize asynchronous specialist consultation as a billable service category.
Market Restraints
- Biocompatible ceramic supply concentration:Zirconia and lithium disilicate blank manufacturing clusters in Germany and Japan create single-source vulnerability for chairside milling operations.
- HIPAA encryption compliance costs:Mandatory standards for digital patient record exchange between clinics and payers impose recurring infrastructure expenditure on mid-sized practices.
- Hygienist scope-of-practice fragmentation:Inconsistent state dental board rules on anesthesia administration and restoration placement limit workforce deployment flexibility.
Strategic Opportunities
- AI diagnostic tool deployment:Early-moving dental service organizations capture patient volume through differentiated chairside imaging interpretation capabilities.
- Rural tele-dentistry penetration:Geographic barriers to specialist access in the Mountain West and Great Plains states create whitespace for hub-and-spoke consultation models.
- Medicaid adult dental benefit restoration:State-level coverage expansion for adult preventive and restorative services unlocks previously excluded patient populations.
Industry Challenges
- Digital workflow integration complexity:Legacy practice management systems resist seamless interoperability with cloud-based imaging platforms and AI diagnostic modules.
- Chairside milling technician training gaps:CAD/CAM system operation requires hybrid clinical-digital skill sets scarce in conventional dental assistant pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Services Market |
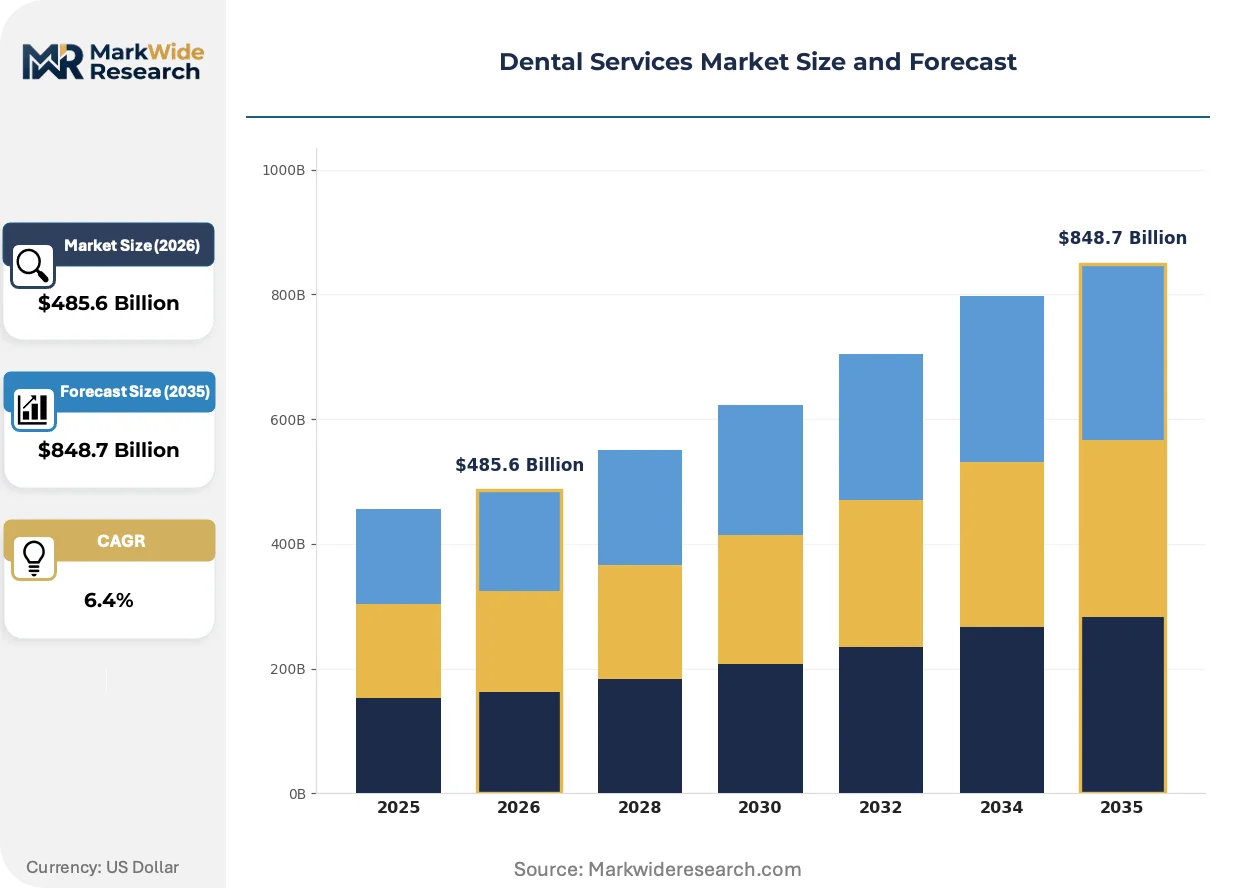
| Market Size in 2026 | $485.6 Billion |
| Market Size in 2035 | $848.7 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Oral Surgery, Preventive Care, Restorative Services, Orthodontics End User: Adults, Children, Seniors, Patients with Special Needs Facility Type: Private Practices, Dental Clinics, Hospitals, Community Health Centers Treatment Modality: In-Office Procedures, Tele-dentistry, Mobile Units, Emergency Care |
| Companies Covered | Pacific Dental Services, Aspen Dental Management, Inc., Heartland Dental, Dental Services Group, Coast Dental, Gentle Dental of New England, Abano Healthcare Group, Smile Brands Inc., Dental Care Alliance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Services Market Strategic Shifts & Innovations
Digital fabrication and artificial intelligence are converging to compress treatment timelines and redistribute clinical labor between dentists, hygienists, and automated systems.
Intraoral scanning paired with AI-powered caries detection is rewriting diagnostic workflows in general practice settings. Mid-sized dental service organizations deploy these platforms across affiliate networks within eighteen-month rollout cycles. The technology compresses specialist referral volumes by enabling real-time chairside treatment planning that previously required separate radiology interpretation.
EU Medical Device Regulation (MDR) reclassification of 3D-printed surgical guides imposes clinical evidence requirements that smaller dental laboratories struggle to satisfy. German and Swiss manufacturers dominate the notified body certification pipeline, creating regulatory friction for North American guide producers seeking European market access. Device sponsors respond by concentrating pre-market submission resources on Class IIa indications with established predicate pathways.
Subscription-based equipment financing is displacing traditional capital purchase models for chairside milling units and cone-beam CT systems. Independent practices in Texas and Florida lead this shift, attracted by bundled maintenance and software update provisions that smooth cash flow volatility. Equipment financiers capture residual value through certified pre-owned remarketing channels serving secondary market entrants.
Dental Services Market Segmentation
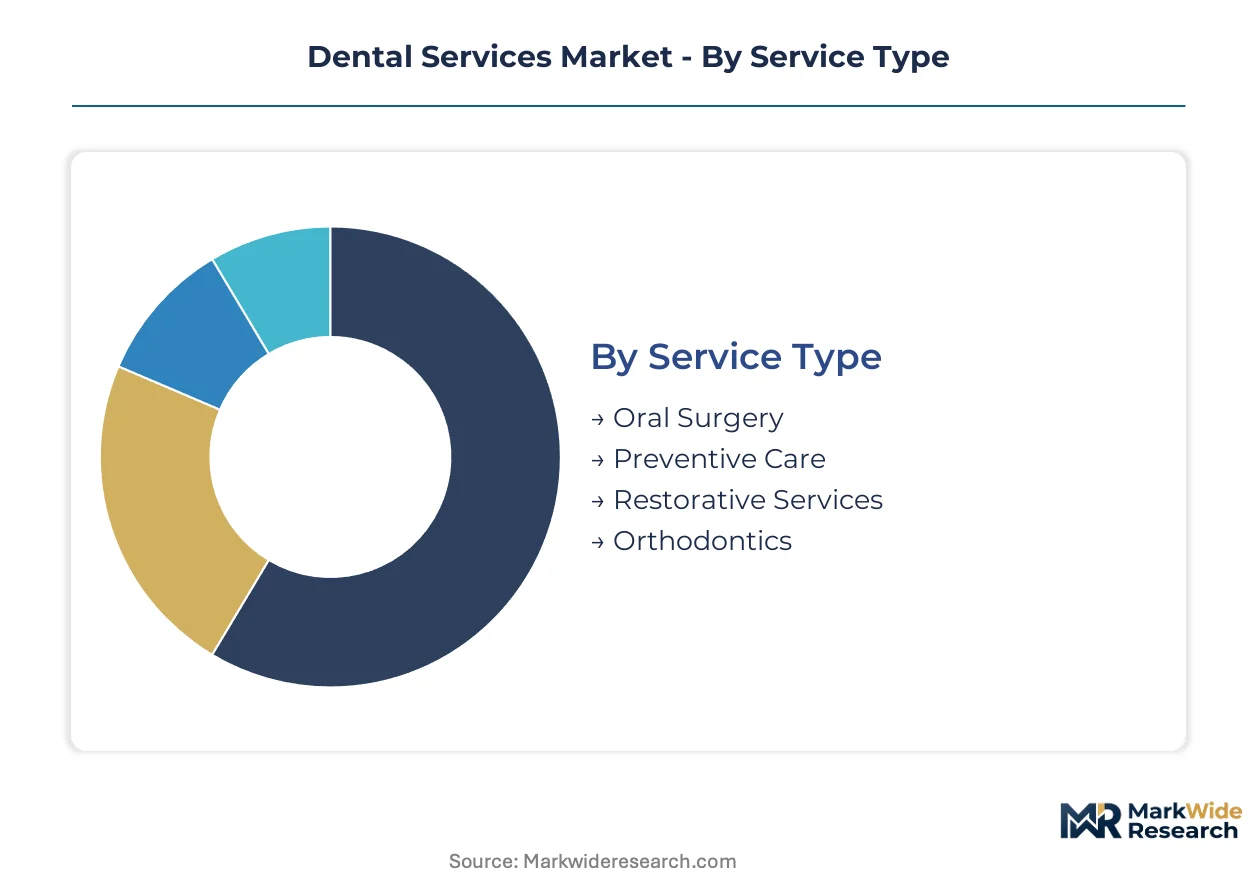
Dental services fragmentation demands precise segmentation to align capital deployment with reimbursement reliability and patient visit frequency. Service mix, facility infrastructure, and treatment modality each impose distinct margin profiles and regulatory compliance burdens.
Service Type:
Customization intensity spans from protocol-driven preventive protocols to patient-specific surgical reconstruction, with reimbursement stability inversely correlated to procedural complexity.
- Preventive Care:Routine prophylaxis, fluoride application, and periodontal maintenance generate the steadiest visit frequency and insurance reimbursement reliability. Demand concentrates in United States dental service organization networks where standardized recall protocols maximize chair utilization and patient retention metrics.
- Orthodontics:Fixed appliances, clear aligner therapy, and retention systems capture premium out-of-pocket spending from adult cosmetic demand. Japan's geriatric population drives unexpected late-life orthodontic volume for occlusal rehabilitation preceding implant restoration.
- Restorative Services:Direct composite fillings, crown-and-bridge work, and endodontic therapy occupy the revenue core of general practice economics.
- Oral Surgery:Exodontia, implant placement, and maxillofacial procedures require specialized operator credentials and surgical facility certification.
Most installed capacity flows through Preventive Care. Expansion is steepest in Orthodontics.
End User:
Patient life-stage determines reimbursement pathway complexity and treatment acceptance rates across private, public, and charitable funding sources.
- Adults:Employed populations with commercial dental benefits drive elective cosmetic procedure volume and aligner subscription models. United States private equity-backed clinic networks target this demographic through consumer-facing brand uniformity and financing partnerships.
- Seniors:Edentulism, periodontal disease, and implant-supported prosthetics dominate service mix. Japan's super-aged demographics sustain implant and prosthetic service volumes beyond replacement rates in other developed economies.
- Children:Pediatric dental visits concentrate on sealant programs and early orthodontic intervention funded through Medicaid and school-based initiatives.
- Patients with Special Needs:Behavioral accommodations, sedation requirements, and facility accessibility constraints limit provider participation despite unmet demand.
Adult patient volume anchors current revenue. Seniors are gaining share fastest.
Facility Type:
Ownership structure and capital intensity separate high-volume institutional operators from owner-doctor practices with technology differentiation.
- Private Practices:Solo and small-group owner-operator models retain clinical autonomy but face procurement cost disadvantages against consolidated competitors. Texas and Florida independent practices increasingly adopt subscription-based equipment financing for chairside milling units.
- Dental Clinics:Multi-chair facilities with hygienist-heavy staffing models achieve scale economies in preventive throughput. Heartland Dental and Aspen Dental Management deploy standardized protocols and centralized purchasing across hundreds of affiliated locations.
- Hospitals:Operating room access and anesthesia support enable complex maxillofacial reconstruction and trauma management.
- Community Health Centers:Federally qualified health center designation unlocks Medicaid reimbursement for otherwise excluded adult populations.
Private practices hold the deepest installed base. Dental clinics are expanding most quickly.
Treatment Modality:
Physical proximity requirements and reimbursement legitimacy determine which modalities can penetrate geographic access gaps.
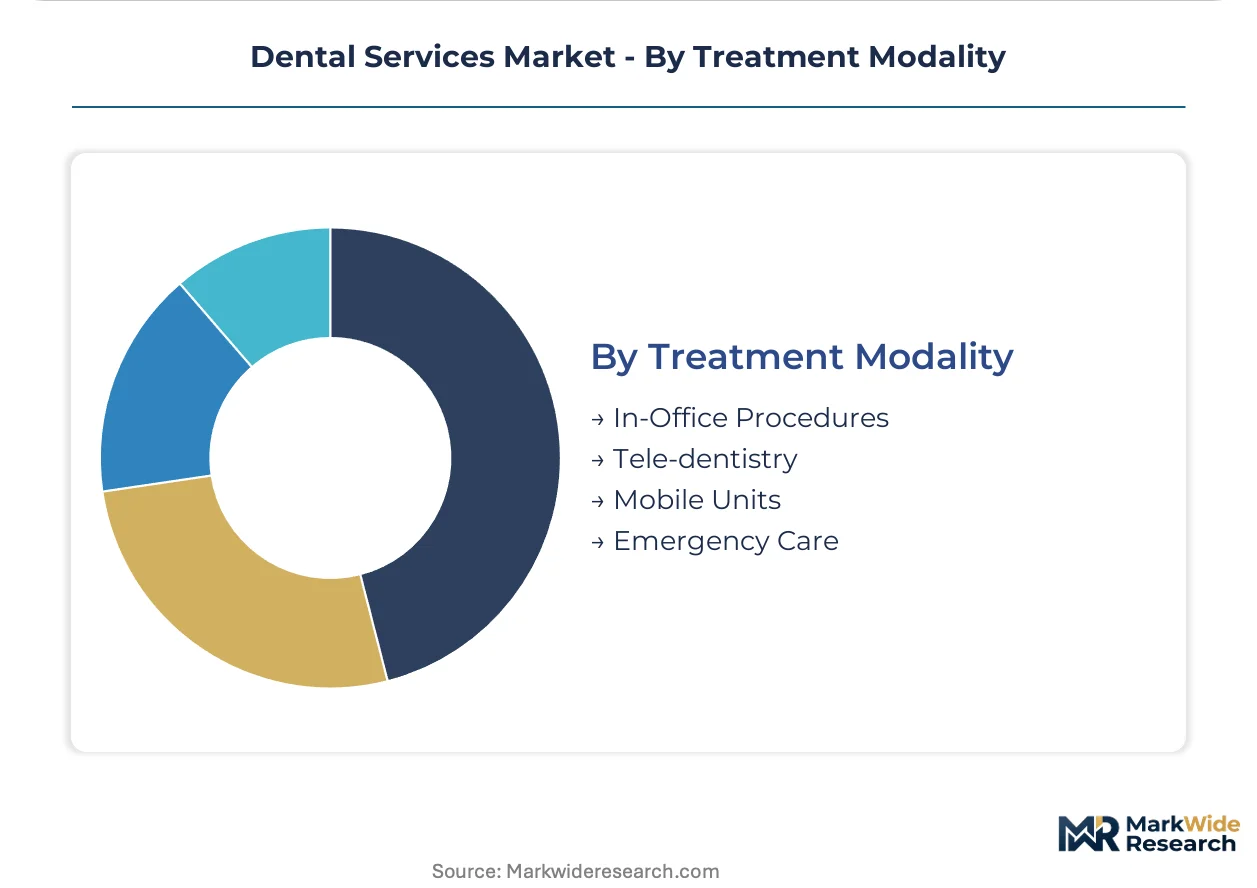
- In-Office Procedures:Chairside delivery using sterilized handpieces, radiographic imaging, and biocompatible materials remains the revenue and clinical standard. FDA 510(k) clearance acceleration for digital intraoral scanners compresses technology adoption cycles from years to months.
- Tele-dentistry:Asynchronous image review and remote consultation protocols reduce geographic barriers to specialist access. State-level Medicaid program adjustments in the United States legitimize asynchronous specialist consultation as a billable service category.
- Mobile Units:Portable equipment configurations serve school-based sealant programs and nursing home outreach.
- Emergency Care:After-hours and walk-in models address acute pain and trauma outside conventional appointment availability.
In-office delivery dominates current capacity. Tele-dentistry shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-based Heartland Dental anchors the most concentrated dental service organization network in North America, with procurement centralization models now diffusing into Germany's laboratory supply corridors and Japan's geriatric implant corridors.
United States
Private equity-backed dental service organizations multiply clinic networks across Texas, Florida, and the Midwest, compressing independent practice economics through standardized protocols. FDA 510(k) clearance acceleration for digital intraoral scanners shortens technology adoption cycles from years to months. Dallas and Chicago serve as headquarters clusters for multi-state DSO operations deploying centralized purchasing.
Japan
Super-aged population demographics drive prosthetic and implant service volumes beyond replacement rates in other developed economies, with late-life orthodontic demand preceding occlusal rehabilitation. PMDA medical device regulations govern CAD/CAM milling unit approvals, creating certification bottlenecks for imported chairside systems. Osaka and Nagoya concentrate zirconia blank distribution networks serving metropolitan implantology practices.
Germany
Biocompatible ceramic manufacturing clusters in Baden-Württemberg and Bavaria dominate zirconia and lithium disilicate blank supply for European chairside milling operations. EU Medical Device Regulation reclassification of 3D-printed surgical guides imposes clinical evidence requirements that strain smaller dental laboratories. Stuttgart and Munich anchor precision manufacturing corridors supplying dental laboratories across the continent.
Canada
Provincial dental benefit variations create reimbursement fragmentation between Ontario's employer-sponsored coverage and Quebec's public program structures. Health Canada regulates medical devices including cone-beam CT systems through pre-market licensing pathways. Toronto and Vancouver concentrate multi-specialty dental clinics serving immigrant populations with complex restorative needs.
United Kingdom
NHS dental contract reform debates reshape private practice conversion incentives across England, with mixed-income models displacing pure NHS delivery in London commuter belts. CQC inspection standards enforce infection control protocols that elevate facility compliance costs. Manchester and Birmingham emerge as DSO expansion targets following London market saturation.
Dental Services Market Key Industry Players
Global majors compete with regional champions across procurement scale and technology deployment velocity, with private equity consolidation compressing the independent practice model. Market structure tilts toward institutional operators with centralized supply chains and standardized clinical protocols. Three archetypes dominate: multi-state dental service organizations with private equity backing, owner-doctor networks with early technology adoption, and independent practices surviving through subscription-based equipment financing. Competitive moves concentrate on regional acquisition pipelines and AI diagnostic platform deployment.
Within the DSO archetype, Heartland Dental, Aspen Dental Management, and Pacific Dental Services exemplify divergent capital deployment strategies. Heartland Dental leverages centralized purchasing to compress supply costs across hundreds of affiliated practices. Aspen Dental Management anchors its model on standardized care protocols and consumer-facing brand uniformity. Pacific Dental Services sustains technology leadership through early deployment of AI-assisted diagnostic platforms in its owner-doctor network.
| Leading Market Players |
|---|
| Pacific Dental Services |
| Aspen Dental Management, Inc. |
| Heartland Dental |
| Dental Services Group |
| Coast Dental |
| Gentle Dental of New England |
| Abano Healthcare Group |
| Smile Brands Inc. |
| Dental Care Alliance |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up dental service organizations compress procurement costs through centralized purchasing agreements, translating supply scale into pricing discipline that independent owner-doctors cannot replicate without subscription-based equipment financing workarounds.
Pricing Analysis
Input-cost pass-through from zirconia blank manufacturers in Germany and Japan flows unevenly across service tiers. Three-tier pricing structure across premium, standard, and economy levels separates CAD/CAM-milled ceramic restorations from chairside composite repairs and basic amalgam fillings. Price differentiation rests on certification grade—FDA 510(k)-cleared digital workflows command material premiums over conventional impressions—and geographic delivery cost differentials between metropolitan DSO networks and rural independent practices. Cost compression in standard-tier preventive services is intensifying because Heartland Dental and Aspen Dental Management squeeze supplier margins through multi-state volume commitments. Medicaid-reimbursed pediatric sealant programs exhibit highest price sensitivity; cash-pay cosmetic orthodontics shows lowest.
Supply Chain Analysis
Direct-to-laboratory channels handle high-volume CAD/CAM blank demand from Heartland Dental's centralized milling operations, while distributor networks serve fragmented independent practices with mixed-material restoratives. Geographic supply concentrates in Germany, Japan, and the United States—Baden-Württemberg and Bavaria dominate zirconia and lithium disilicate blank production; Osaka and Nagoya anchor East Asian ceramic distribution; Texas and Florida concentrate North American dental laboratory clustering. Raw material dependencies include biocompatible ceramic powders, titanium implant fixtures, and cobalt-chrome alloy substrates. Single-source vulnerability runs through German and Japanese ceramic blank manufacturing clusters, where EU MDR reclassification and PMDA certification bottlenecks create regulatory friction for North American chairside milling operations. Distribution runs through dental service organization procurement consortia, independent practice group purchasing organizations, and direct manufacturer-to-laboratory agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental services pricing arbitrage exists between United States private-pay cosmetic corridors and European NHS-contracted preventive baselines, with reimbursement differentials exceeding material cost gaps for equivalent ceramic restoration procedures.
For Market Incumbents: Extend AI diagnostic platform deployment across affiliate networks before Pacific Dental Services consolidates technology differentiation, and defend procurement scale by locking multi-year zirconia blank offtake agreements with Baden-Württemberg manufacturers before EU MDR compliance costs concentrate supplier power. Vertical integration into chairside milling technician training pipelines addresses workforce scarcity threatening CAD/CAM throughput targets. For New Entrants and Emerging Players: The premium-to-economy price-point gap in adult clear aligner therapy creates entry space for tele-dentistry-native platforms targeting rural Mountain West and Great Plains geographies underserved by specialist orthodontists. Medicaid adult dental benefit restoration in states like Texas and Florida offers the most penetrable reimbursement expansion. Go-to-market through employer-sponsored dental benefit administrators bypasses DSO channel control. For Investors and Strategic Acquirers: Valuations sit cheapest among independent owner-doctor practices with subscription-financed chairside milling capacity but no AI diagnostic overlay—acquisition targets that fill technology gaps for roll-up strategies. Long-term viability favors DSOs with demonstrated HIPAA-compliant digital workflow integration and state-level Medicaid contracting depth. The signal to watch is FDA guidance on AI diagnostic tool classification, which would accelerate capital deployment toward early-moving platforms or strand late adopters in compliance remediation.| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Platform Deployment | Pacific Dental Services captures patient volume through differentiated chairside imaging interpretation ahead of FDA guidance finalization. |
| Centralized Procurement Consolidation | Heartland Dental compresses supply costs across hundreds of affiliated practices through multi-state volume commitments. |
| Tele-Dentistry Hub-and-Spoke Expansion | Asynchronous specialist consultation models penetrate rural Mountain West and Great Plains whitespace created by geographic access barriers. |
| Subscription-Based Equipment Financing | Texas and Florida independent practices smooth cash flow volatility through bundled maintenance and software update provisions. |
| EU MDR Compliance Pathway Investment | German and Swiss manufacturers dominate notified body certification for 3D-printed surgical guides, creating regulatory moats. |
Research Approach
Bottom-up patient visit modeling reconciled against top-down dental service organization capacity tracking forms the analytical core of this study. Primary interviews with dental service organization procurement executives, state dental board regulatory affairs officers, CAD/CAM equipment financiers, and Medicaid program administrators combined with secondary validation against FDA 510(k) clearance databases, CMS Medicare dental expenditure reports, state-level Medicaid benefit schedules, and PMDA medical device approval filings. Triangulation between bottom-up procedure volume estimates and top-down clinic network expansion data ensures cross-verified market sizing.
Historical trendline analysis of dental service organization acquisition velocity and technology adoption cycles informed projection frameworks across the analysis window. Segmentation dimensions modeled include service type complexity tier, facility ownership structure, patient life-stage reimbursement pathway, and treatment modality physical proximity requirement. CAGRs derived from fitted growth curves applied to procedure volume baselines, with dental laboratory automation penetration and tele-dentistry reimbursement legitimacy serving as industry-specific forecast sensitivity inputs.
Caveats apply where state-level Medicaid reimbursement adjustments, FDA AI diagnostic guidance revisions, or EU MDR enforcement variability could materially shift the outlook. Forecasts reflect documented assumptions regarding private equity consolidation pace and ceramic supply chain resiliency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
United States Dental Services Market
Dental Services
Global Dental Support Organizations Market
Dental Services
Microdontia Treatment Market
Dental Services
Dental Market
Dental Services
Dental Service Organization Market
Dental Services
Teledentistry Market
Dental Services
Periodontal Dental Service Market
Dental Services
US Dental Chains Market
Dental Services
Chronic Gingivostomatitis Treatment Market
Dental Services
EMEA Dental Service Organization Market
Dental Services
Dental Fluoride Treatment Market
Dental Services
Orthodontic Services Market