
 Periodontal Dental Service Market | 2026-2036
Periodontal Dental Service Market Size, Share, and Industry Trends Forecast 2026-2036
Periodontal Dental Service Market Analysis
Modular service bundling is repositioning periodontal care procurement as payers shift from fee-for-service reimbursement toward episode-based packages. Pacific Dental Services leverages its vertically integrated clinic network to control costs across preventive and surgical therapy workflows. Aspen Dental Management anchors its growth strategy in high-volume private practices across underserved U.S. markets. Apollo Hospitals Enterprise extends its periodontal service footprint through hospital-integrated dental centers in South Asia.
Periodontal dental services encompass diagnostic, preventive, and therapeutic interventions targeting the supporting structures of teeth—gingiva, periodontal ligament, and alveolar bone—typically involving scaling depth measurements, root surface debridement, and guided tissue regeneration protocols. These services prevent tooth loss, preserve masticatory function, and reduce systemic inflammation linked to cardiovascular and metabolic conditions. Surgical therapy commands the dominant share of revenue within service type segmentation due to higher reimbursement rates and specialized clinician training requirements. Dental clinics represent the fastest-expanding end-user channel as corporate chains consolidate independent practices and standardize periodontal protocols. Laser therapy technology is displacing conventional hand instrumentation in premium service tiers, though ultrasonic instruments sustain volume leadership across maintenance and scaling segments due to lower capital expenditure and broader clinician familiarity.
The FDA regulates laser therapy devices and ultrasonic instruments under Class II medical device pathways, while OSHA mandates bloodborne pathogen standards in U.S. periodontal clinics. The EU Medical Device Regulation imposes stricter clinical evidence requirements on imaging systems and surgical instruments marketed across Europe. Japan's Ministry of Health, Labour and Welfare oversees reimbursement pricing for periodontal procedures under its national health insurance framework. Stakeholders must monitor how reimbursement compression in public health systems and evolving device classification standards reshape capital allocation between technology acquisition and clinician workforce expansion.
Market Dynamics
Bundled preventive-maintenance packages are restructuring how employer-sponsored dental plans purchase periodontal care, compressing fee-for-service reimbursement into episode-based contracting models across United States markets.
Growth Catalysts
- Episode-Based Reimbursement Frameworks:United States employer dental plans are migrating toward bundled payment structures that incentivize preventive maintenance over surgical intervention, expanding covered patient populations.
- Laser Therapy Reclassification:FDA's updated Class II medical device pathway for periodontal laser systems accelerates clinical adoption of minimally invasive protocols in outpatient settings.
- Corporate Clinic Consolidation:Dental clinic chains in Germany, Japan, and Brazil are standardizing periodontal protocols across acquired independent practices, driving volume throughput.
Market Restraints
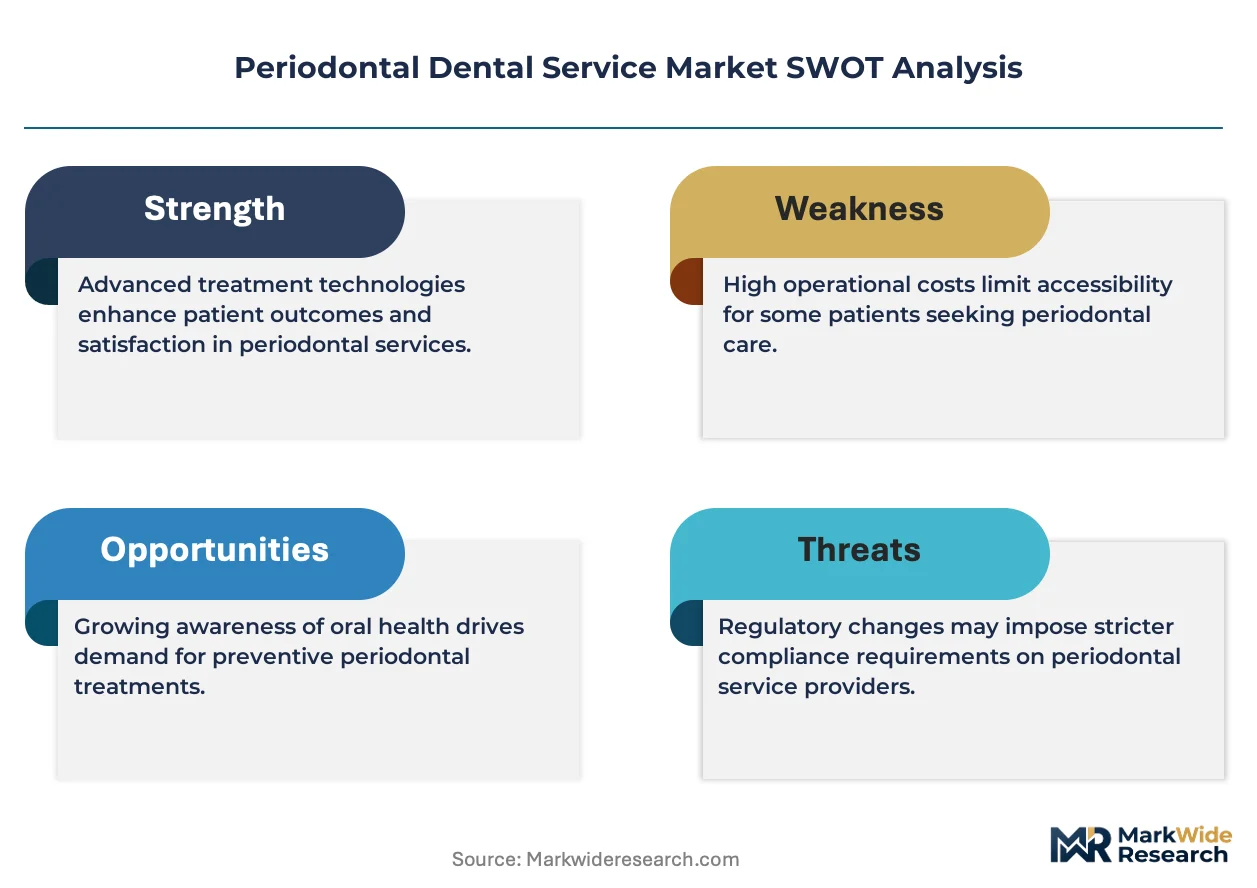
- Specialized Clinician Training Requirements:Surgical therapy segments face supply constraints from extended credentialing periods for guided tissue regeneration and implantology procedures.
- Capital Intensity of Laser Systems:Premium-tier laser equipment demands substantial upfront investment compared to ultrasonic instruments, limiting penetration in price-sensitive maintenance segments.
- Reimbursement Compression in Public Systems:Japan's Ministry of Health, Labour and Welfare periodically adjusts national health insurance pricing for periodontal procedures, constraining provider margins.
Strategic Opportunities
- Hospital-Integrated Dental Centers:South Asian markets present expansion potential for periodontal services embedded within tertiary care facilities, capturing systemic disease management referrals.
- EU Medical Device Regulation Harmonization:Stricter MDR clinical evidence requirements on imaging systems create competitive moats for compliant manufacturers entering European markets.
- Ultrasonic-Laser Hybrid Protocols:Convergence of established ultrasonic debridement with adjunctive laser therapy opens premium service tiers in maintenance and scaling workflows.
Industry Challenges
- Workforce Pipeline Constraints:Periodontist training programs produce insufficient specialists to match expanding clinic chain demand, particularly in underserved United States markets.
- Legacy Equipment Integration:Outpatient dental clinics face operational friction retrofitting existing operatories with laser therapy infrastructure while maintaining ultrasonic instrument throughput.
- OSHA Bloodborne Pathogen Compliance:United States periodontal clinics must continuously update sterilization protocols and staff training to meet evolving workplace safety mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Periodontal Dental Service Market |
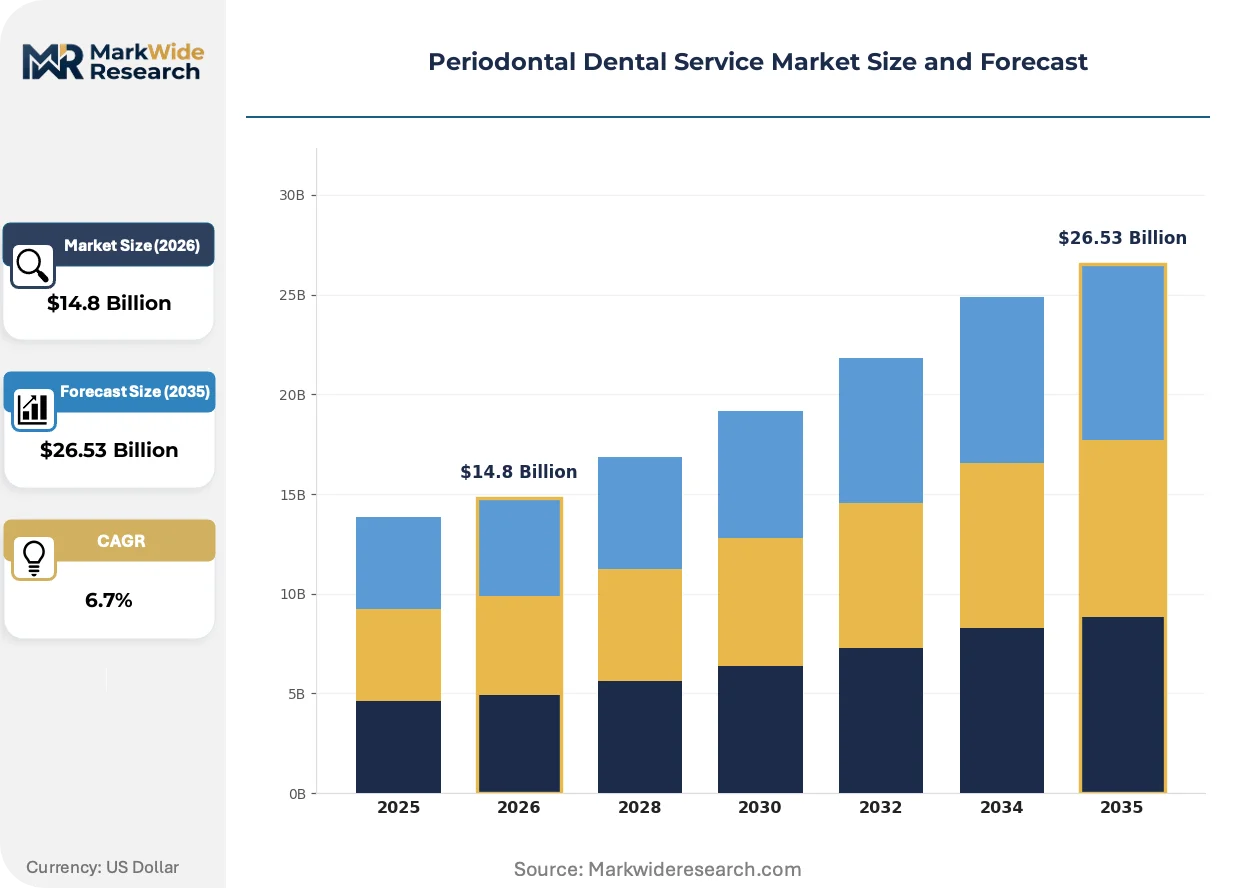
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Scaling, Root Planing, Surgical Therapy, Maintenance End User: Dentists, Dental Clinics, Hospitals, Private Practices Technology: Laser Therapy, Ultrasonic Instruments, Hand Instruments, Imaging Systems Treatment Plan: Preventive Care, Active Treatment, Post-Treatment Care, Re-evaluation |
| Companies Covered | Pacific Dental Services, Coast Dental Services, Aspen Dental Management, Apollo Hospitals Enterprise, Q & M Dental Group, Burlingame Dental Arts, Brighton Dental Group, 123Dentist, Highland Dental Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Periodontal Dental Service Market Emerging Trajectories
Digital workflow integration and minimally invasive instrumentation are compressing treatment timelines while elevating patient retention metrics across periodontal service delivery models.
Er,Cr:YSGG and diode laser systems are consolidating market position in premium periodontal therapy tiers by enabling selective photocoagulation of diseased soft tissue with reduced post-operative morbidity. Outpatient dental clinic chains in Germany and Japan are deploying these platforms at accelerated cadence to differentiate service offerings. The technology is consolidating surgical and maintenance workflows into unified protocol suites that reduce clinician chair time per procedure.
EU Medical Device Regulation imposes stricter clinical evidence requirements on periodontal imaging systems and surgical instruments marketed across European member states. Manufacturers must now submit comprehensive technical documentation and post-market surveillance data to notified bodies prior to CE marking authorization. Periodontal laser therapy devices face heightened scrutiny under this framework, delaying market entry for non-compliant suppliers while advantaging established players with robust quality management systems.
Employer-sponsored dental plans are restructuring periodontal benefit design around episode-based packages that cap reimbursement for complete treatment cycles rather than individual procedures. This purchasing pattern shift compresses administrative burden for self-insured corporations while transferring utilization risk to provider networks. The United States exhibits the most pronounced migration toward this contracting structure, with Pacific Dental Services and Aspen Dental Management adapting operational workflows to accommodate bundled payment terms.
Periodontal Dental Service Market Segmentation
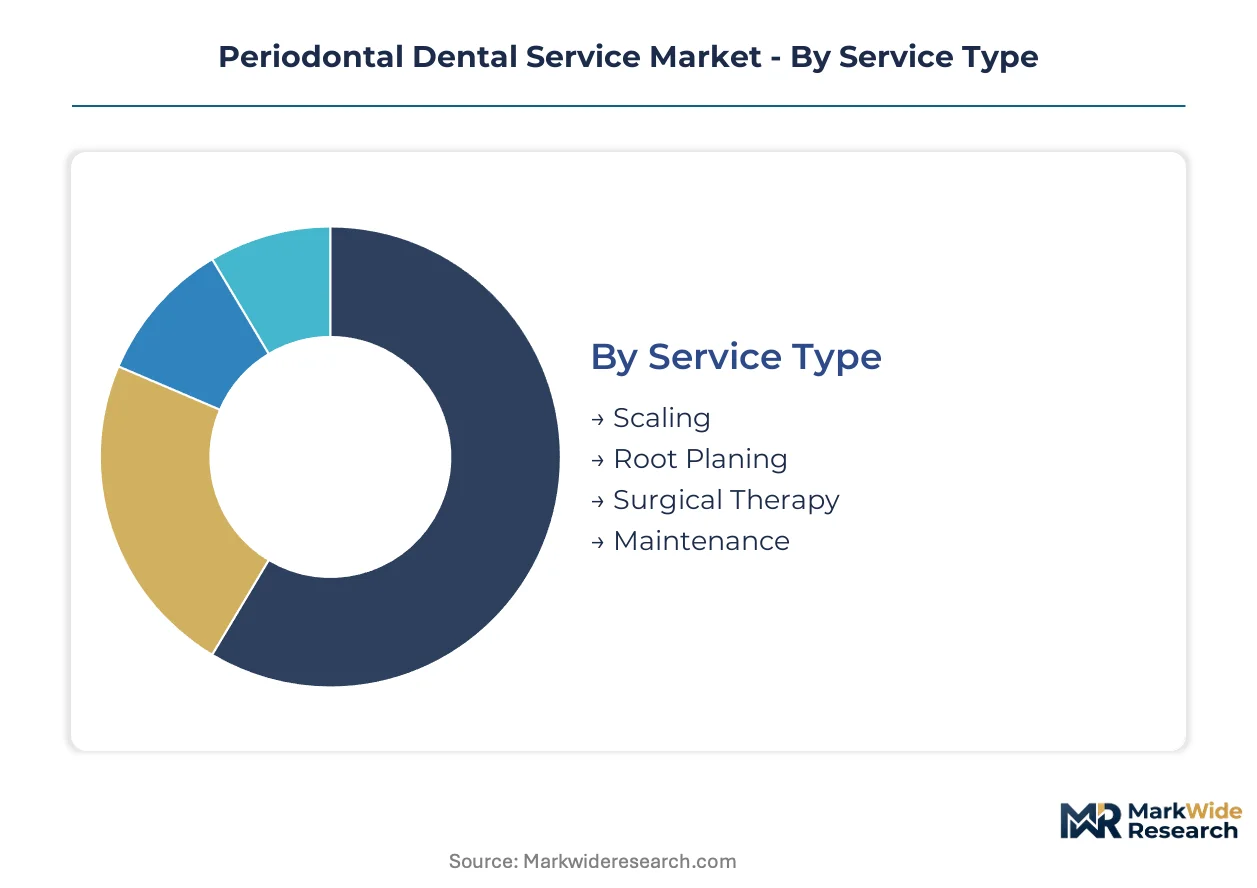
Periodontal service segmentation reveals how reimbursement models and technology adoption reshape procurement patterns across provider networks. Understanding these divisions illuminates where capital flows concentrate and which service configurations align with evolving payer preferences.
Service Type:
Upgrade and replacement cycles vary sharply across service categories, with maintenance protocols refreshing every 6-12 months while surgical equipment investments span 5-7 year horizons.
- Surgical Therapy:Invasive procedures including guided tissue regeneration and osseous surgery command premium reimbursement tiers. Demand clusters in corporate dental chains across Germany and Brazil where specialized periodontists handle complex cases requiring bone grafting and flap procedures.
- Maintenance:Recurring preventive protocols encompass prophylaxis and periodontal maintenance visits at 3-4 month intervals. Japanese dental clinics are expanding these service lines under national health insurance frameworks that incentivize early intervention over surgical escalation.
- Scaling:Non-surgical debridement removes calculus and plaque from tooth surfaces and subgingival pockets.
- Root Planing:Deep instrumentation smooths root surfaces to facilitate gingival reattachment and reduce pocket depth.
Surgical Therapy sits at the top of the volume ranking, with Maintenance climbing the fastest.
End User:
Cost tier stratification separates high-volume clinic chains from boutique private practices, with capital intensity determining which segments absorb new laser technology first.
- Dental Clinics:Corporate chains consolidate independent practices and standardize periodontal protocols across multi-site networks. Pacific Dental Services and Aspen Dental Management in the United States leverage vertical integration to control costs across preventive and surgical workflows.
- Hospitals:Tertiary care facilities embed periodontal services within systemic disease management pathways. Apollo Hospitals Enterprise in South Asia captures cardiovascular and diabetes referrals through hospital-integrated dental centers.
- Dentists:Individual practitioners deliver diagnostic and basic therapeutic services with referral networks for complex surgical cases.
- Private Practices:Independent offices maintain fee-for-service models with selective adoption of bundled payment structures.
Dental Clinics lead absolute patient throughput, with Hospitals expanding most quickly in emerging markets.
Technology:
Application intensity diverges between premium laser platforms and volume-driven ultrasonic systems, with reimbursement rates dictating which technologies penetrate which service tiers.
- Laser Therapy:Er,Cr:YSGG and diode systems enable selective photocoagulation with reduced post-operative morbidity. FDA's updated Class II medical device pathway accelerates adoption in United States outpatient settings where clinics differentiate through minimally invasive protocols.
- Ultrasonic Instruments:Piezoelectric and magnetostrictive scalers sustain volume leadership across maintenance and scaling segments due to lower capital expenditure and broader clinician familiarity in price-sensitive markets.
- Hand Instruments:Curettes and scalers remain essential for fine debridement in surgical and maintenance workflows.
- Imaging Systems:Digital radiography and CBCT platforms support diagnostic precision and treatment planning documentation.
Ultrasonic Instruments dominate procedure counts, with Laser Therapy gaining share fastest in premium service tiers.
Treatment Plan:
Customer type segmentation tracks how employer-sponsored plans, individual payers, and public systems distribute across episodic versus recurring care models.
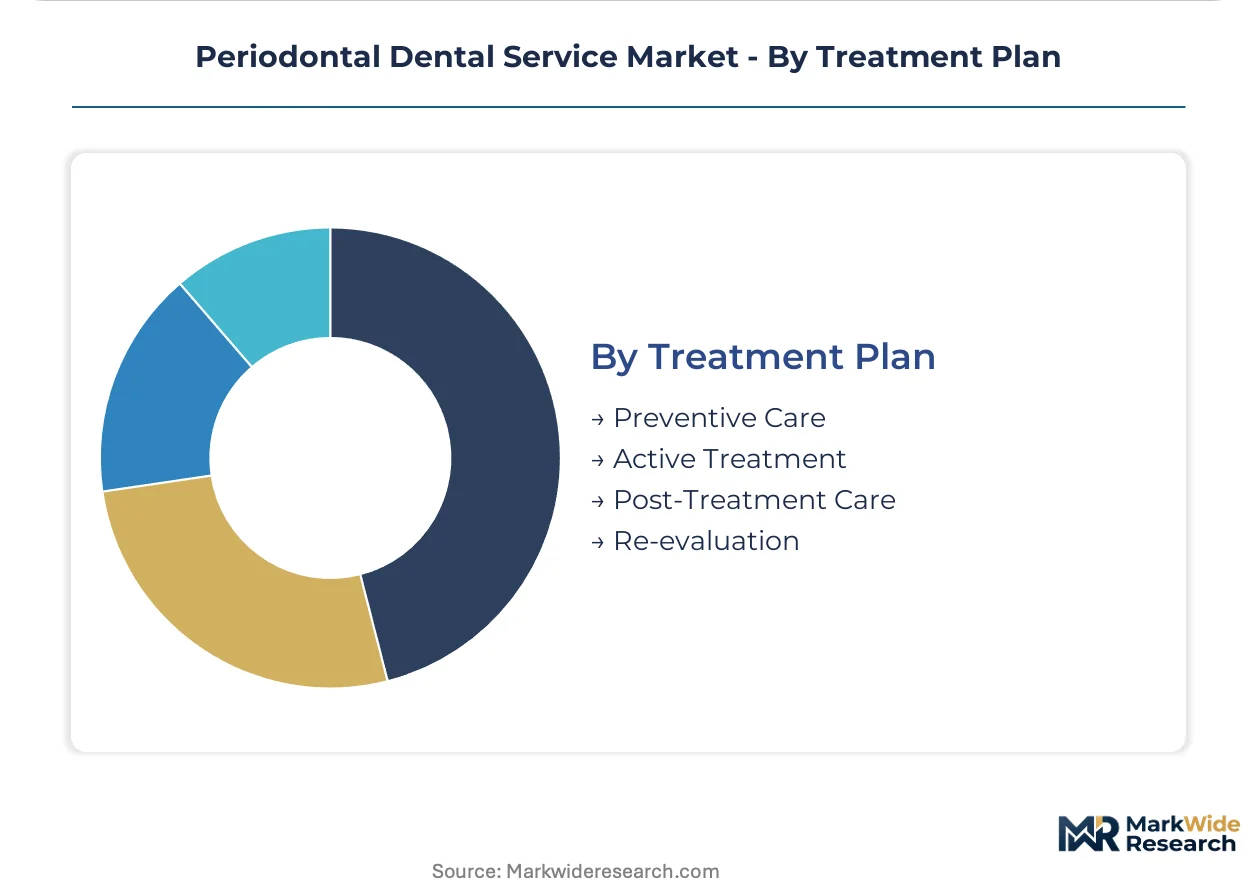
- Preventive Care:Initial examinations, risk assessments, and early intervention protocols target gingivitis before progression to periodontitis. United States employer dental plans are restructuring benefit design around episode-based packages that cap reimbursement for complete preventive cycles.
- Active Treatment:Definitive therapeutic interventions address established periodontal disease through surgical or non-surgical modalities. German dental clinic chains deploy standardized protocols across acquired practices to drive volume throughput in this segment.
- Post-Treatment Care:Supportive periodontal therapy maintains stability following active intervention.
- Re-evaluation:Periodic assessment visits determine treatment response and guide maintenance interval adjustments.
Preventive Care generates the highest visit frequency, with Active Treatment showing the steepest expansion trajectory as disease prevalence rises in aging populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Periodontal dental services first scaled through employer-sponsored benefit structures in the United States, with European and Asian markets subsequently adapting procurement models to local reimbursement frameworks. Geographic expansion now concentrates in outpatient clinic networks across Germany, Japan, and Brazil.
United States
Employer dental plans drive procurement volume through bundled episode-based packages that cap reimbursement for complete treatment cycles. OSHA mandates bloodborne pathogen standards across periodontal clinics, requiring continuous sterilization protocol updates. Pacific Dental Services and Aspen Dental Management anchor vertically integrated networks across underserved markets, standardizing preventive and surgical workflows.
Germany
Corporate dental clinic chains absorb independent practices and deploy standardized periodontal protocols at accelerated volume throughput. The EU Medical Device Regulation imposes stricter clinical evidence requirements on imaging systems and surgical instruments prior to CE marking authorization. Outpatient networks concentrate in Bavaria and North Rhine-Westphalia, where acquired practices convert to maintenance-focused service models.
Japan
National health insurance frameworks incentivize preventive maintenance visits over surgical escalation, expanding covered patient populations for recurring care. The Ministry of Health, Labour and Welfare periodically adjusts reimbursement pricing for periodontal procedures, constraining provider margins. Dental clinics in Tokyo and Osaka metropolitan areas deploy laser therapy platforms to differentiate premium service tiers.
Brazil
Rising disease prevalence in aging urban populations drives demand for surgical therapy segments including guided tissue regeneration. ANVISA oversees medical device registration for laser systems and ultrasonic instruments entering the market. São Paulo and Rio de Janeiro host consolidating clinic chains that standardize protocols across acquired independent practices.
India
Hospital-integrated dental centers capture cardiovascular and diabetes referrals through systemic disease management pathways. CDSCO regulates medical devices including imaging systems and surgical instruments under harmonized standards. Apollo Hospitals Enterprise extends periodontal service footprints through tertiary care facilities in South Asian metropolitan clusters.
Periodontal Dental Service Market Vendor Landscape
Premium-margin players sit above commodity-margin players across reimbursement tier access and technology infrastructure intensity. The market structures around three archetypes: vertically integrated clinic chains controlling costs across multi-site networks, hospital-integrated providers capturing systemic disease referrals, and independent private practices maintaining fee-for-service autonomy. Consolidation through practice acquisition and standardization of periodontal protocols represent dominant competitive vectors.
Within the vertically integrated chain archetype, Pacific Dental Services and Aspen Dental Management occupy positions across United States markets, while Apollo Hospitals Enterprise anchors hospital-integrated service delivery in South Asia. These entities exemplify contrasting scale models: clinic chains leverage multi-site standardization for cost control, whereas hospital-integrated providers capture referral volume through systemic care coordination.
| Leading Market Players |
|---|
| Pacific Dental Services |
| Coast Dental Services |
| Aspen Dental Management |
| Apollo Hospitals Enterprise |
| Q & M Dental Group |
| Burlingame Dental Arts |
| Brighton Dental Group |
| 123Dentist |
| Highland Dental Care |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up dental clinic specialists anchor supply concentration across United States markets, compressing procurement leverage into centralized purchasing consortia while feeding pricing discipline through standardized fee schedules negotiated with employer-sponsored plans.
Pricing Analysis
Episode-based bundled payment structures dominate periodontal service procurement across employer-sponsored dental plans in the United States. Price differentiation rests on certification tier of clinician staff and volume scale of clinic network membership, with Pacific Dental Services and Aspen Dental Management commanding premium positioning through multi-site standardization. Cost compression in maintenance segments is intensifying because Japanese national health insurance periodically adjusts reimbursement pricing downward. Individual private practices exhibit highest price sensitivity due to capital constraints on laser technology acquisition, while hospital-integrated dental centers in South Asia demonstrate lowest sensitivity through systemic disease referral capture.
Supply Chain Analysis
Dual-sourcing requirements for laser therapy devices and ultrasonic instruments mandate multi-supplier qualification across United States and German clinic networks. Manufacturing concentrates in Germany, Japan, and the United States for precision optical components, piezoelectric transducers, and surgical handpiece assemblies. Component dependencies include rare-earth elements for laser crystal fabrication, medical-grade stainless steel for instrument forging, and specialized ceramics for ultrasonic scaler tips. Single-source vulnerability concentrates in Er,Cr:YSGG laser crystal supply chains where qualified vendors remain limited. Distribution runs through authorized dental equipment dealers with direct-to-clinic service contracts for capital-intensive platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Periodontal service margins expand through laser technology premium-tier migration and consolidated procurement leverage across multi-site clinic networks, with episode-based contracting transferring utilization risk to providers while capping administrative burden.
For Market Incumbents: Extend protocol standardization across acquired practices to capture bundled payment efficiencies and compress per-procedure cost structures. Consolidate supplier relationships for ultrasonic instruments to offset margin pressure from Japanese reimbursement compression. Invest in clinician credentialing pipelines to address workforce constraints threatening surgical therapy throughput in underserved United States markets. For New Entrants and Emerging Players: Launch via hospital-integrated dental center partnerships in South Asian metropolitan clusters to capture cardiovascular and diabetes referral volume. Target preventive maintenance service lines in Japanese national health insurance frameworks where reimbursement stability exceeds surgical segment volatility. Deploy ultrasonic-laser hybrid protocols as differentiation wedge against established clinic chains. For Investors and Strategic Acquirers: Corporate dental clinic chains backed by private equity sponsors are the most active acquirers in this space, rolling up independent practices across Germany, Japan, and Brazil. Long-term viability hinges on successful conversion of fee-for-service revenue to episode-based contracts with employer-sponsored plans. Monitor FDA device classification updates for laser therapy systems as inflection indicator for technology substitution velocity and capital allocation shifts toward minimally invasive platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Clinic Network Consolidation | Pacific Dental Services and Aspen Dental Management compress costs through multi-site standardization across underserved United States markets. |
| Laser Technology Premium Tier Deployment | Er,Cr:YSGG and diode systems differentiate service offerings in German and Japanese outpatient clinic chains. |
| Hospital-Integrated Dental Center Expansion | Apollo Hospitals Enterprise captures systemic disease referrals through tertiary care facilities in South Asian metropolitan clusters. |
| Episode-Based Contracting Adaptation | Employer-sponsored plans in the United States migrate reimbursement toward bundled payment structures incentivizing preventive maintenance. |
| Clinician Workforce Pipeline Investment | Extended credentialing periods for guided tissue regeneration constrain surgical therapy supply across expanding clinic chain demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with periodontists, dental clinic operations directors, employer benefits managers, and biomedical equipment procurement specialists with secondary validation against FDA 510(k) filings, OSHA compliance databases, CMS Medicare dental expenditure reports, and Japanese Ministry of Health reimbursement pricing circulars. Bottom-up procedure volume estimates triangulated against top-down market sizing from national health insurance claims data.
Historical reference periods anchored the forecast window through documented adoption curves for laser therapy technology and bundled payment contracting penetration rates. The analytical framework modeled service type segmentation, end-user channel configuration, technology platform tier, and treatment plan category across the projection horizon. CAGRs derived from procedure volume growth trajectories, reimbursement rate evolution, and capital expenditure patterns for clinic infrastructure expansion. Industry-specific inputs included periodontist supply pipeline data from accredited training programs and employer-sponsored dental plan benefit design surveys.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt reimbursement compression in Japanese national health insurance or accelerated FDA device reclassification for laser therapy systems. Deviation in clinician workforce production rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
Teledentistry Market
Dental Services
Dental Market
Dental Services
US Dental Chains Market
Dental Services
United States Dental Services Market
Dental Services
Dental Fluoride Treatment Market
Dental Services
Dental Services Market
Dental Services
Chronic Gingivostomatitis Treatment Market
Dental Services
Dental Service Organization Market
Dental Services
EMEA Dental Service Organization Market
Dental Services
Global Dental Support Organizations Market
Dental Services
Orthodontic Services Market
Dental Services
Microdontia Treatment Market