
 Dental Market | 2026-2036
Dental Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Market Intelligence
Subscription-based CAD/CAM software and chairside milling maintenance contracts is rebalancing revenue models away from pure equipment sales. Align Technology leverages its proprietary scanner-to-aligner ecosystem to sustain recurring revenue streams. Dentsply Sirona anchors its position through integrated imaging and treatment planning platforms. Institut Straumann differentiates via end-to-end digital workflow solutions spanning surgical guides to final restorations.
Dentistry encompasses the diagnosis, prevention, and treatment of oral diseases using instruments fabricated from surgical-grade stainless steel, titanium alloys, zirconia ceramics, and light-cured resin composites measuring 2-25 micrometers in particle size for optimal polishability. Dental lasers operate at specific wavelengths—typically 810 nm, 980 nm, or 10,600 nm—to perform soft-tissue incision, hard-tissue ablation, and photobiomodulation with minimal thermal collateral damage. Implant systems and orthodontic appliances capture the dominant share of product-type revenue pools, while preventive care therapies exhibit the fastest trajectory as payors expand coverage for prophylactic interventions. Direct sales channels to dental clinics retain the highest margin profile, though group purchasing organizations are compressing pricing power across distributor networks.
FDA 510(k) premarket notification requirements govern Class II dental device clearance timelines, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards on implantable dental products entering European markets. ISO 13485 quality management certification has become a baseline predicate for supplier qualification across both regulated jurisdictions. Stakeholders must monitor how artificial intelligence diagnostic tools trigger new software-as-medical-device classification debates at FDA and notified body levels.
Market Dynamics
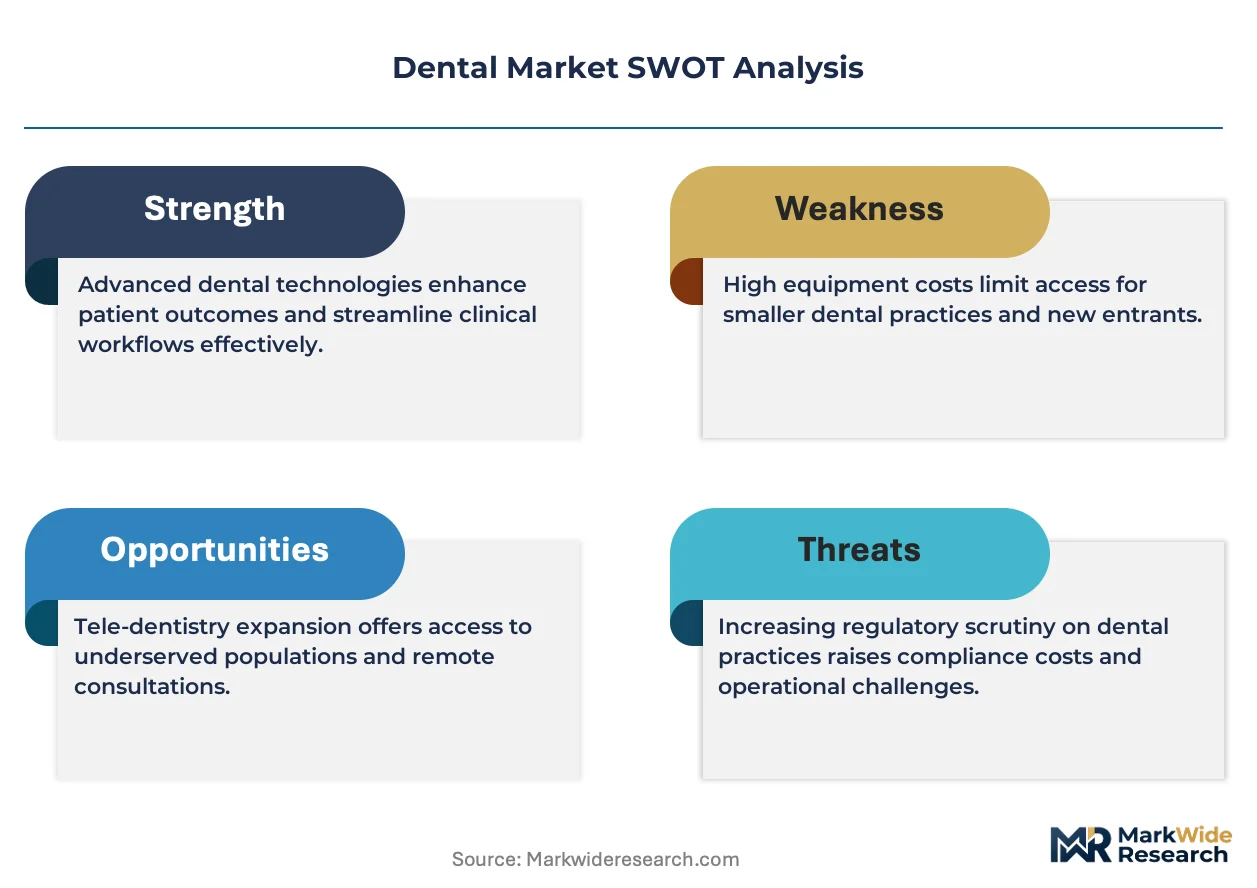
Clear aligner manufacturing is consolidating around proprietary intraoral scanner ecosystems, locking clinics into vertically integrated digital workflows that raise switching costs and compress third-party equipment margins.
Growth Catalysts
- FDA 510(k) pathway acceleration:Digital dentistry platforms achieve faster clearance through predicate device referencing, compressing development timelines for chairside milling systems.
- Adult orthodontic demand:Aesthetic-conscious patients aged 25-45 drive aligner volume in the United States, Germany, and China as employer-sponsored dental benefits expand.
- Titanium-zirconium alloy adoption:Implant manufacturers switch to higher-strength materials for narrow-diameter fixtures, enabling flapless surgical protocols in dense urban clinics.
Market Restraints
- Zirconia powder supply concentration:Ceramic precursor sourcing clusters in Chinese and Japanese chemical processors, exposing implant crown fabricators to freight cost volatility.
- EU MDR clinical evidence burden:Implantable dental products face extended notified body review timelines and mandatory post-market surveillance registries.
- Direct-to-consumer aligner substitution:Remote orthodontic platforms bypass traditional chairside diagnosis, capturing price-sensitive cosmetic cases from brick-and-mortar practices.
Strategic Opportunities
- Preventive therapy reimbursement expansion:German statutory health insurers now cover professional plaque removal and fluoride varnish for adults over 18, opening prophylactic service revenue pools.
- AI diagnostic tool integration:Convolutional neural networks for caries detection and periodontal staging converge with practice management software, triggering software-as-medical-device classification debates at FDA.
- Group purchasing organization penetration:Consolidated dental service organizations in the United States negotiate multi-year maintenance contracts for CAD/CAM equipment, displacing transactional distributor relationships.
Industry Challenges
- ISO 13485 certification bottlenecks:Smaller implant manufacturers face 12-18 month quality management system audits, delaying European market entry.
- Legacy analog workflow integration:Hybrid practices struggle to synchronize physical impression storage with cloud-based treatment planning platforms, creating data fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Market |
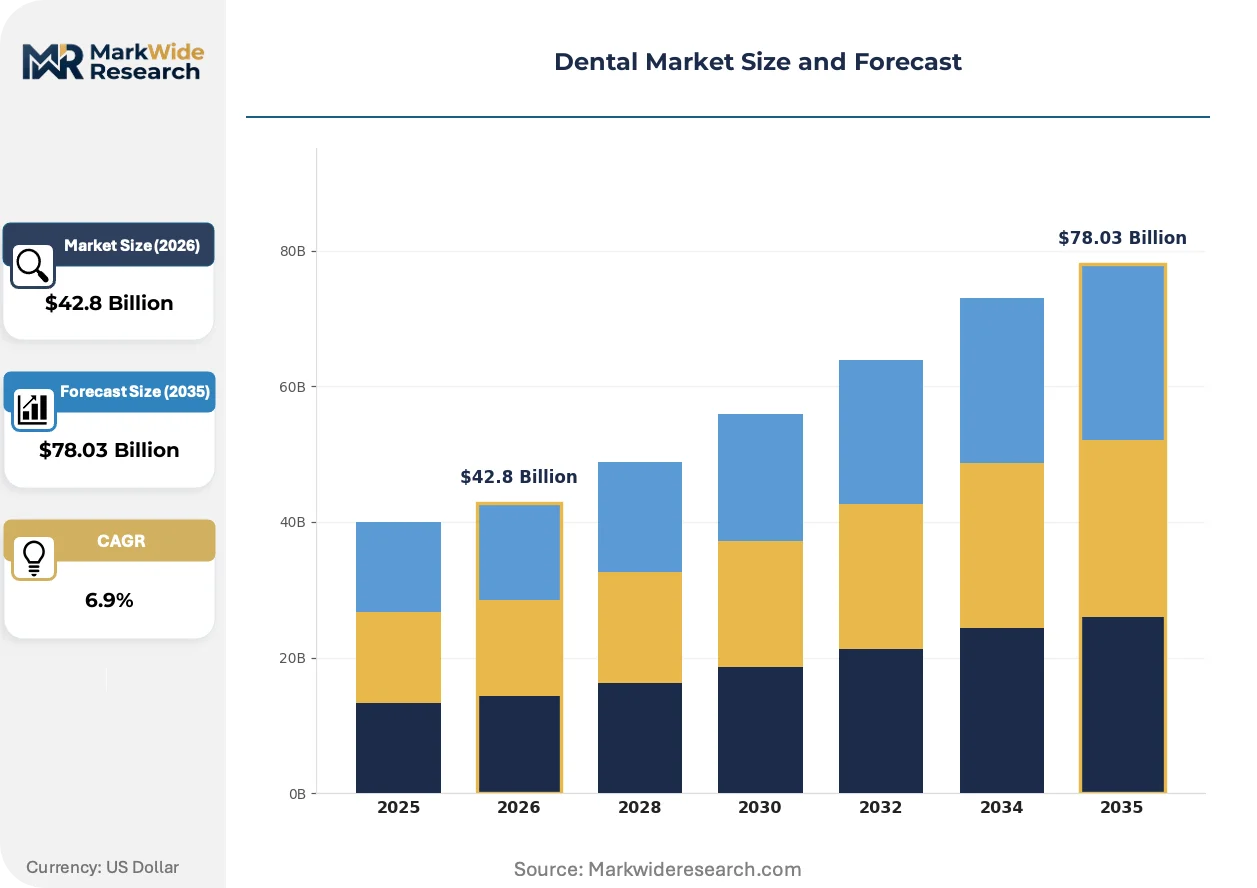
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $78.03 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handpieces, Implants, Orthodontic Appliances, Dental Lasers, Composites, Endodontic Tools Therapy Area: Preventive Care, Restorative Procedures, Orthodontics, Prosthodontics, Periodontics, Oral Surgery End User: Dental Clinics, Academic Institutions, Specialty Centers, Mobile Care Units, Research Laboratories, Dental Laboratories Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Dental Supply Stores, Wholesale Suppliers, Group Purchasing Organizations |
| Companies Covered | Align Technology, Envista Holdings Corporation, Dentsply Sirona, Institut Straumann, Zimmer Biomet, 3M, Straumann Holding, Biolase, Henry Schein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Market Strategic Shifts & Innovations
Digital manufacturing architectures are fragmenting traditional equipment categories into interoperable component layers, enabling clinics to assemble customized technology stacks rather than purchasing monolithic systems.
Intraoral scanning hardware is modularizing across price-performance tiers, allowing mid-size practices in Germany and China to acquire entry-level scanners for aligner case submission while reserving premium units for complex restorative workflows. Scanner-agnostic file formats are compressing vendor lock-in, though proprietary treatment planning software retains ecosystem control. This modularity is enabling third-party milling centers to compete directly with chairside systems on unit economics.
The EU Medical Device Regulation imposes stricter clinical evidence standards on implantable dental products entering European markets, forcing manufacturers to maintain post-market surveillance registries and periodic safety update reports. Notified bodies in Germany and France have extended review timelines for novel surface-treated fixtures. Implant companies are responding by pre-submission engagement with BSI and TÜV SÜD to clarify predicate device strategies.
Subscription billing for CAD/CAM software and predictive maintenance contracts is displacing capital expenditure models among United States dental service organizations. Group purchasing organizations negotiate multi-year agreements covering scanner calibration, milling bur replacement, and remote technical support. This shift concentrates vendor relationships at the DSO level rather than individual practice discretion, compressing pricing power for standalone equipment distributors.
Dental Market Segmentation
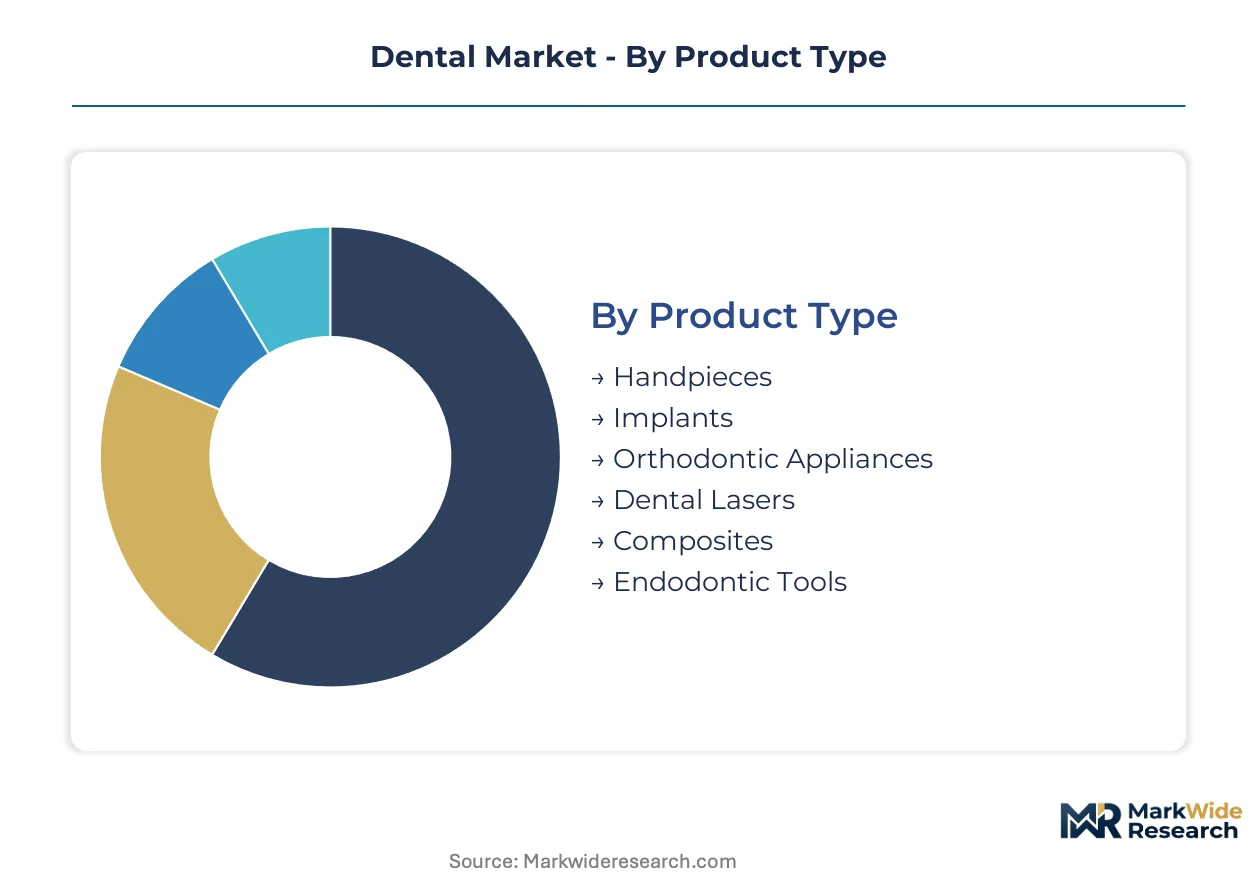
Dental market segmentation reveals distinct procurement patterns across clinical workflows and reimbursement environments. Technology specifications and regulatory classifications determine margin structures and vendor selection criteria.
Product Type:
Material composition and energy delivery specifications define performance tiers across equipment categories.
- Handpieces:Surgical-grade stainless steel and ceramic bearing assemblies rotate at 400,000 RPM for cavity preparation. Demand clusters in high-volume restorative practices across the United States and Germany where chairside throughput drives replacement cycles.
- Implants:Titanium-zirconium alloy fixtures with surface-etched topography enable osseointegration in narrow-diameter indications. Titanium-zirconium alloy adoption accelerates in dense urban clinics pursuing flapless surgical protocols.
- Orthodontic Appliances:Clear aligner systems fabricated from medical-grade thermoplastic polyurethane.
- Dental Lasers:Solid-state and CO2 platforms operating at 810 nm, 980 nm, or 10,600 nm wavelengths.
- Composites:Light-cured resin formulations with 2-25 micrometer particle size distributions.
- Endodontic Tools:Nickel-titanium rotary instruments with variable taper geometry.
Mature deployment sits with handpieces. Newer deployment is concentrated in implant systems.
Therapy Area:
Reimbursement expansion and aesthetic demand reshape procedure mix across service lines.
- Preventive Care:Professional plaque removal, fluoride varnish application, and sealant placement. German statutory health insurers now cover prophylactic interventions for adults over 18, opening service revenue pools.
- Restorative Procedures:Direct and indirect restorations using composite resins and ceramic inlays. Demand concentrates in employer-sponsored dental benefit networks across the United States.
- Orthodontics:Fixed appliances and removable aligner systems for malocclusion correction.
- Prosthodontics:Crown, bridge, and denture fabrication using CAD/CAM workflows.
- Periodontics:Soft-tissue management and regenerative therapies.
- Oral Surgery:Extraction, implant placement, and bone grafting procedures.
Volume leadership rests with restorative procedures. Preventive care exhibits the steepest expansion trajectory.
End User:
Capital intensity and case complexity determine technology adoption patterns across facility types.
- Dental Clinics:Private and group practices delivering comprehensive care. United States dental service organizations negotiate multi-year CAD/CAM maintenance contracts, displacing transactional distributor relationships.
- Academic Institutions:Dental schools and residency programs with training missions.
- Specialty Centers:Focused practices in orthodontics, periodontics, or oral surgery.
- Mobile Care Units:Transportable equipment for underserved populations.
- Research Laboratories:Biomaterials testing and clinical trial sites.
- Dental Laboratories:Off-site restoration fabrication using centralized milling.
Procurement consolidation is shifting toward dental service organizations.
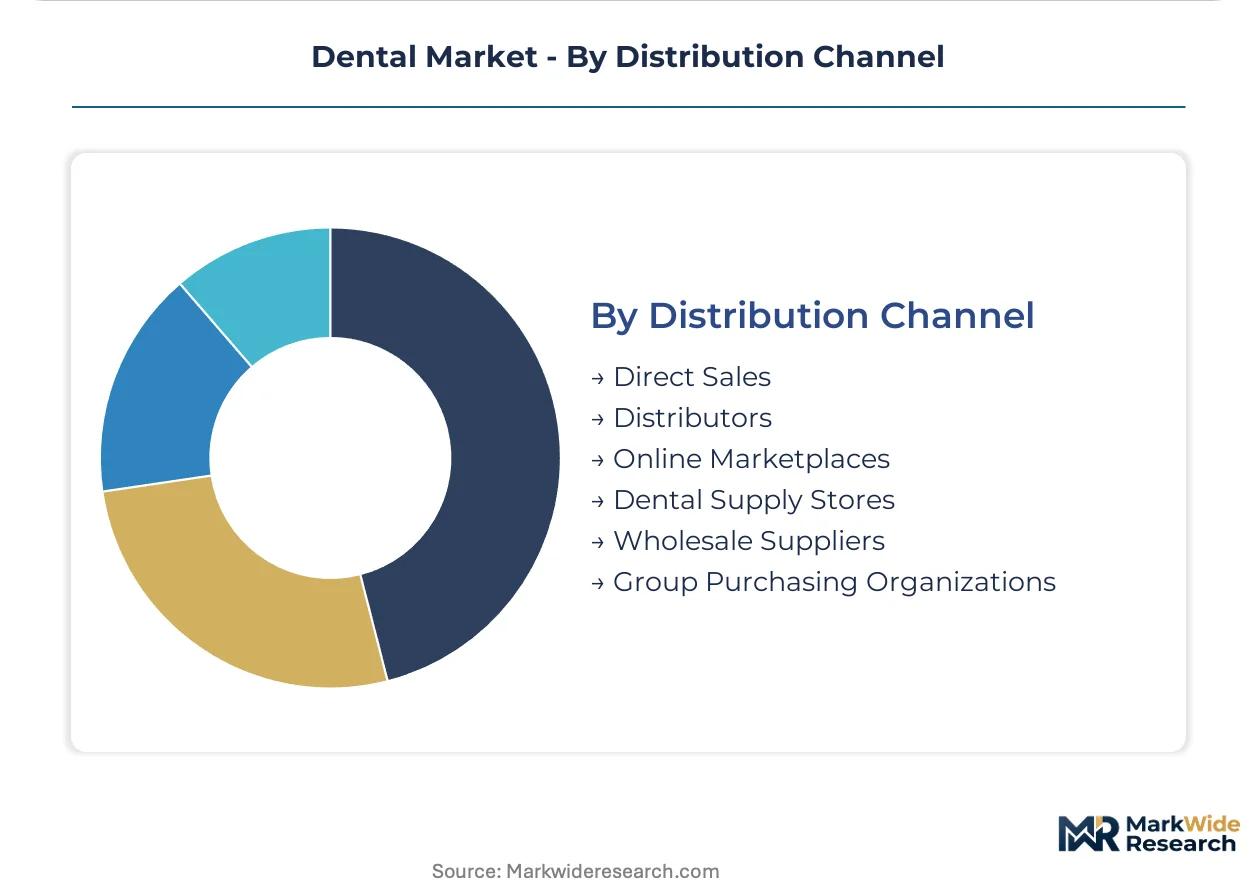
Distribution Channel:
Channel selection reflects equipment complexity and buyer scale.
- Direct Sales:Manufacturer-to-clinic relationships for capital equipment. Direct sales channels to dental clinics retain the highest margin profile.
- Distributors:Regional inventory and technical support networks.
- Online Marketplaces:E-commerce platforms for consumables and small equipment.
- Dental Supply Stores:Brick-and-mortar retailers with immediate availability.
- Wholesale Suppliers:Volume aggregators serving multi-location practices.
- Group Purchasing Organizations:Consolidated buying power across dental service organizations. Group purchasing organizations compress pricing power across distributor networks.
Traditional distributor relationships face displacement from group purchasing organization penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southern California's dental technology corridor hosts the densest concentration of clear aligner manufacturing and digital dentistry R&D facilities in the United States. The region anchors North American demand for chairside CAD/CAM systems and orthodontic appliance production.
United States
Employer-sponsored dental benefits expansion and aesthetic-conscious adult patients aged 25-45 drive aligner volume growth. FDA 510(k) premarket notification pathways compress clearance timelines for digital dentistry platforms. The Dallas-Fort Worth metroplex concentrates dental service organization headquarters negotiating multi-year CAD/CAM maintenance contracts.
Germany
German statutory health insurers now cover professional plaque removal and fluoride varnish for adults over 18, opening prophylactic service revenue pools. EU MDR imposes stricter clinical evidence standards on implantable dental products entering European markets. Stuttgart and Munich host precision milling centers serving centralized dental laboratory networks across Central Europe.
China
Domestic demand for orthodontic clear aligners accelerates among urban professional segments in tier-one cities. NMPA regulatory pathways govern Class II dental device approvals with predicate device referencing. Shanghai and Shenzhen cluster intraoral scanner assembly operations and zirconia powder processing facilities for regional implant crown fabrication.
Japan
Aging demographics expand demand for implant-supported prosthodontics and preventive periodontal therapies. PMDA maintains rigorous quality management system requirements for dental device market authorization. Osaka's medical device manufacturing zone concentrates titanium-zirconium alloy implant production for domestic and export markets.
Switzerland
Swissmedic oversees clinical evidence standards for high-value implantable dental products entering domestic and adjacent European markets. Precision manufacturing heritage supports end-to-end digital workflow solutions spanning surgical guides to final restorations. Basel and Zurich anchor research-intensive dental biomaterials development clusters.
Dental Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the dental technology stack. The market structure consolidates around vertically integrated scanner-to-aligner ecosystems and integrated imaging platforms. Three archetypes dominate: proprietary ecosystem orchestrators, modular component suppliers, and subscription-based software vendors. Competitive moves concentrate on M&A for digital workflow capabilities and multi-year service contract penetration at dental service organizations.
Among United States-based technology developers, Align Technology and Dentsply Sirona exemplify ecosystem orchestration archetypes. Swiss-incorporated Institut Straumann occupies a position within premium-tier implant and digital dentistry integration. Henry Schein represents distributor-scale procurement consolidation across North American dental clinics.
| Leading Market Players |
|---|
| Align Technology |
| Envista Holdings Corporation |
| Dentsply Sirona |
| Institut Straumann |
| Zimmer Biomet |
| 3M |
| Straumann Holding |
| Biolase |
| Henry Schein |
| Others |
Cost & Logistics Intelligence
Zirconia powder procurement costs cascade through implant crown fabrication tiers, with ceramic precursor sourcing clusters in Chinese and Japanese chemical processors transmitting freight volatility into margin compression for European and North American dental laboratories. This input-cost pathway shapes how pricing stratifies across premium, standard, and economy tiers for CAD/CAM-milled restorations.
Pricing Analysis
Per-procedure throughput anchors value-based pricing for chairside milling systems, with subscription models for scanner calibration and bur replacement displacing capital expenditure structures among United States dental service organizations. Price differentiation separates FDA-cleared premium fixtures from CE-marked standard tiers and economy imports lacking notified body certification. Cost compression in economy aligner segments intensifies because direct-to-consumer platforms bypass chairside diagnosis. Group purchasing organizations exhibit highest price sensitivity; boutique prosthodontic practices show lowest.
Supply Chain Analysis
ISO 13485 certification gating creates 12-18 month audit bottlenecks that constrain supplier qualification for European market entry, favoring incumbent manufacturers with established quality management systems. Titanium-zirconium alloy feedstock concentrates in Japan, China, and Switzerland; zirconia powder processing clusters in Chinese and Japanese chemical facilities; intraoral scanner assembly localizes in Shenzhen and Shanghai. Supply chain risk centers on single-source vulnerability for medical-grade thermoplastic polyurethane used in aligner fabrication. Distribution runs through manufacturer-direct relationships for capital equipment and regional distributors for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evidence burdens function as a cost-of-compliance moat, with mandatory post-market surveillance registries and extended notified body timelines filtering out undercapitalized implant manufacturers seeking European market access.
For Market Incumbents: Hedge against direct-to-consumer aligner substitution by deepening software companion development for practice management integration, and secure multi-year maintenance contracts with United States dental service organizations before group purchasing organization consolidation completes. Threat: Remote orthodontic platforms capturing cosmetic cases. Lever: Channel control through predictive service bundling. For New Entrants and Emerging Players: Mobile care units serving rural and underserved populations represent the most penetrable buyer archetype, with transportable intraoral scanning hardware enabling aligner case capture outside traditional brick-and-mortar density. White-space targets include tier-two Chinese cities and German statutory reimbursement expansion for adult preventive therapies. Go-to-market: Equipment-leasing models with embedded training protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular scanner-agnostic component suppliers in Germany and China facing pricing pressure from vertically integrated ecosystem orchestrators. Long-term viability frames around digital workflow interoperability rather than proprietary lock-in. Acquisition target: Third-party milling centers with ISO-certified quality systems. Signal to watch: FDA software-as-medical-device classification clarity for AI diagnostic tools.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR pre-submission engagement with BSI and TÜV SÜD accelerates implant clearance timelines. |
| Hospital System Partnership | Academic dental centers anchor training revenue and predicate device referencing for novel surface treatments. |
| Software Companion Development | Convolutional neural network integration with practice management platforms triggers FDA classification review. |
| Reimbursement Strategy | German statutory health insurer coverage expansion for adult prophylaxis opens preventive service revenue pools. |
| Backward Integration | In-house titanium-zirconium alloy processing secures narrow-diameter implant feedstock against Japanese supply concentration. |
Research Approach
Independent corroboration across FDA 510(k) clearance databases, EU notified body technical documentation, and German statutory health insurer reimbursement bulletins underwrites the qualitative findings. Primary interviews with dental clinic owners, biomedical engineers at implant manufacturers, GPO contracts managers, and regulatory affairs specialists at notified bodies combined with secondary validation from ISO 13485 audit records, customs trade data for zirconia powder shipments, and hospital procurement databases. Bottom-up scanner shipment tallies and top-down dental service organization revenue aggregates triangulate market sizing.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end-user facility scale, and distribution channel complexity. CAGRs derive from procedure volume elasticity to reimbursement expansion and equipment replacement cycle analysis. Industry-specific inputs encompass aligner case submission rates per scanner installed base and implant fixture surface treatment innovation cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software-as-medical-device classification rulings and EU MDR notified body capacity constraints. Forecasts reflect documented assumptions regarding reimbursement policy continuity and supply chain logistics stability. A model refresh is warranted upon material change in NMPA regulatory pathway timelines for Chinese market entry.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
Dental Service Organization Market
Dental Services
Teledentistry Market
Dental Services
EMEA Dental Service Organization Market
Dental Services
United States Dental Services Market
Dental Services
Orthodontic Services Market
Dental Services
Microdontia Treatment Market
Dental Services
Chronic Gingivostomatitis Treatment Market
Dental Services
Periodontal Dental Service Market
Dental Services
Dental Services Market
Dental Services
US Dental Chains Market
Dental Services
Global Dental Support Organizations Market
Dental Services
Dental Fluoride Treatment Market