
 US Burial Insurance Market | 2026-2036
US Burial Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
US Burial Insurance Market Intelligence
Digital underwriting automation is rewriting how burial insurance products reach end consumers, replacing paper-based medical questionnaires with algorithmic risk scoring and instant issue platforms. Mutual of Omaha leverages its captive agent network to sustain dominant shelf space in the final expense segment across rural and suburban markets. Gerber Life Insurance anchors its brand recognition in the pre-need policy category through decades of direct-mail continuity programs targeting young families. Ethos competes on streamlined digital acquisition, eliminating exam requirements through predictive mortality models that reduce friction in the senior customer journey.
Burial insurance constitutes a permanent or term life policy with death benefit amounts typically capped between $5,000 and $50,000, designed explicitly to cover funeral services, cemetery plots, and related end-of-life expenses rather than income replacement or estate transfer. Whole life final expense policies generate the thickest margin pools due to guaranteed level premiums and non-forfeiture provisions that lock in carrier liability for decades. Online platforms represent the fastest-growing distribution channel as seniors and adult children increasingly complete research and application workflows through mobile-optimized portals before agent contact. Pre-need policies sold through funeral homes retain structural importance despite channel compression, as state-regulated trust or insurance funding mechanisms create sticky relationships between mortuary operators and policyholders.
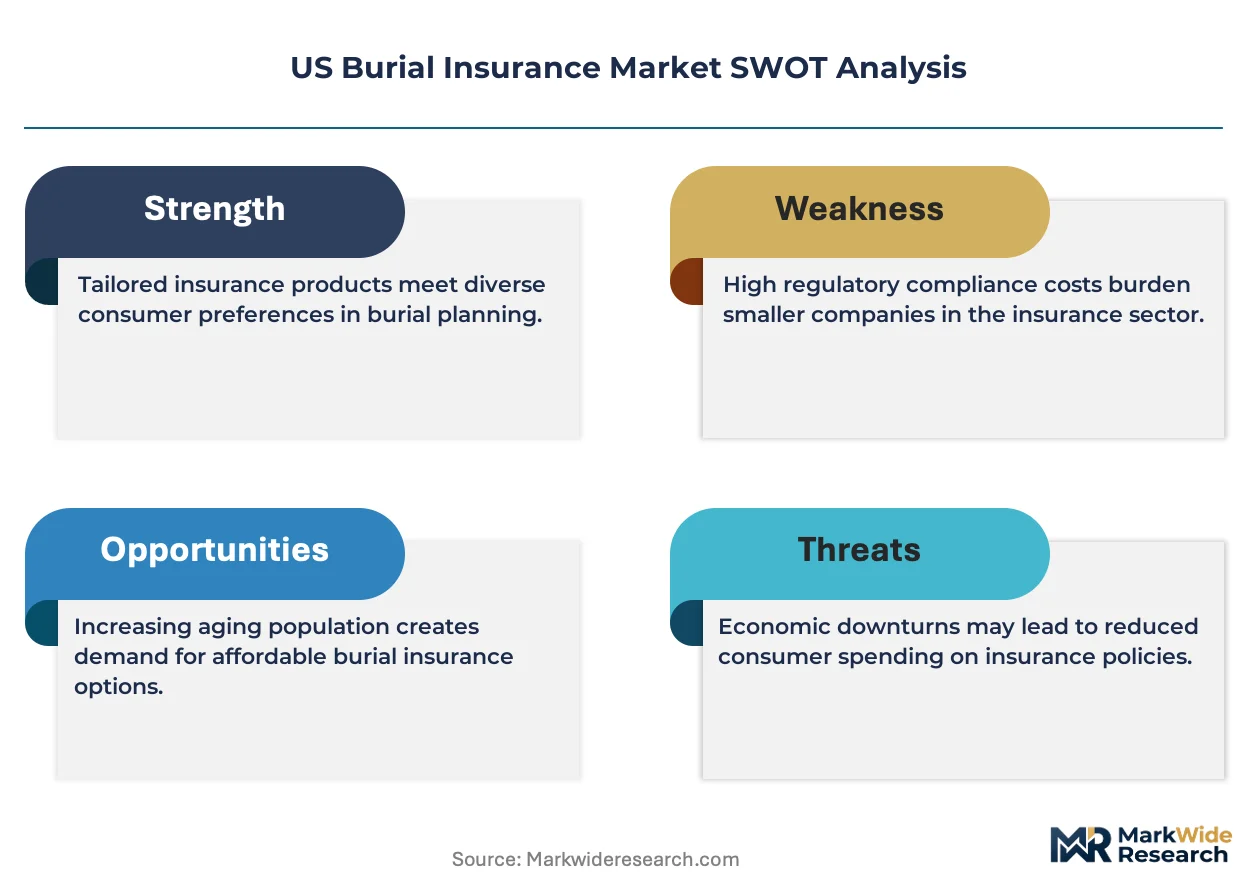
State insurance commissioners enforce NAIC model laws governing policy illustrations and replacement disclosures, while the SEC monitors securities-linked pre-need trust products that blur lines between insurance and investment vehicles. HIPAA privacy rules constrain how carriers share medical data with third-party underwriting services, adding compliance cost to accelerated digital transformation programs. Stakeholders must monitor whether state-level rate regulation tightens on guaranteed issue products as loss ratios deteriorate in regions experiencing rapid senior population influx.
Market Dynamics
Direct-to-consumer digital enrollment platforms are compressing traditional agent-mediated distribution cycles, forcing carriers to reconfigure underwriting infrastructure around algorithmic risk scoring and instant-issue workflows.
Growth Catalysts
- NAIC Model Regulation Revisions:Tightened underwriting transparency requirements are standardizing policy illustrations across state insurance departments, reducing consumer friction in cross-state purchases.
- Sun Belt Demographic Concentration:Florida, Texas, and Arizona are experiencing accelerated aging-in-place migration patterns that concentrate final expense demand in metropolitan clusters with established funeral home networks.
- Accelerated Underwriting Engines:Predictive mortality models using prescription history and credit data are eliminating paramedical exam requirements, collapsing issue timelines from weeks to minutes.
Market Restraints
- HIPAA Privacy Compliance Costs:Medical data sharing constraints between carriers and third-party underwriting services add operational overhead to digital transformation programs.
- Guaranteed Issue Loss Ratio Deterioration:Rapid senior population influx in select regions is compressing margins on no-exam products as adverse selection concentrates in high-growth markets.
- Pre-Need Trust Regulatory Fragmentation:State-level variations in funeral home trust funding mechanisms create compliance complexity for carriers operating across multiple jurisdictions.
Strategic Opportunities
- Adult Child Digital Research Workflows:Mobile-optimized portals targeting sandwich-generation decision-makers enable policy research completion before agent contact, shortening conversion funnels.
- SEC Securities-Linked Pre-Need Products:Hybrid trust structures that blend insurance and investment vehicles offer margin expansion in states with permissive funeral funding regulations.
- Rural Captive Agent Network Leverage:Suburban and exurban territories underserved by digital-first competitors retain shelf space value for carriers maintaining localized sales infrastructure.
Industry Challenges
- Legacy Policy Administration System Integration:Core system modernization required to support real-time digital enrollment conflicts with decades-old policy servicing platforms.
- Actuarial Talent Scarcity in Predictive Modeling:Shortage of professionals skilled in machine learning mortality forecasting constrains carrier ability to refine algorithmic underwriting.
- Multi-State Rate Filing Coordination:State insurance commissioner review timelines vary dramatically, complicating national product launches and pricing consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Burial Insurance Market |
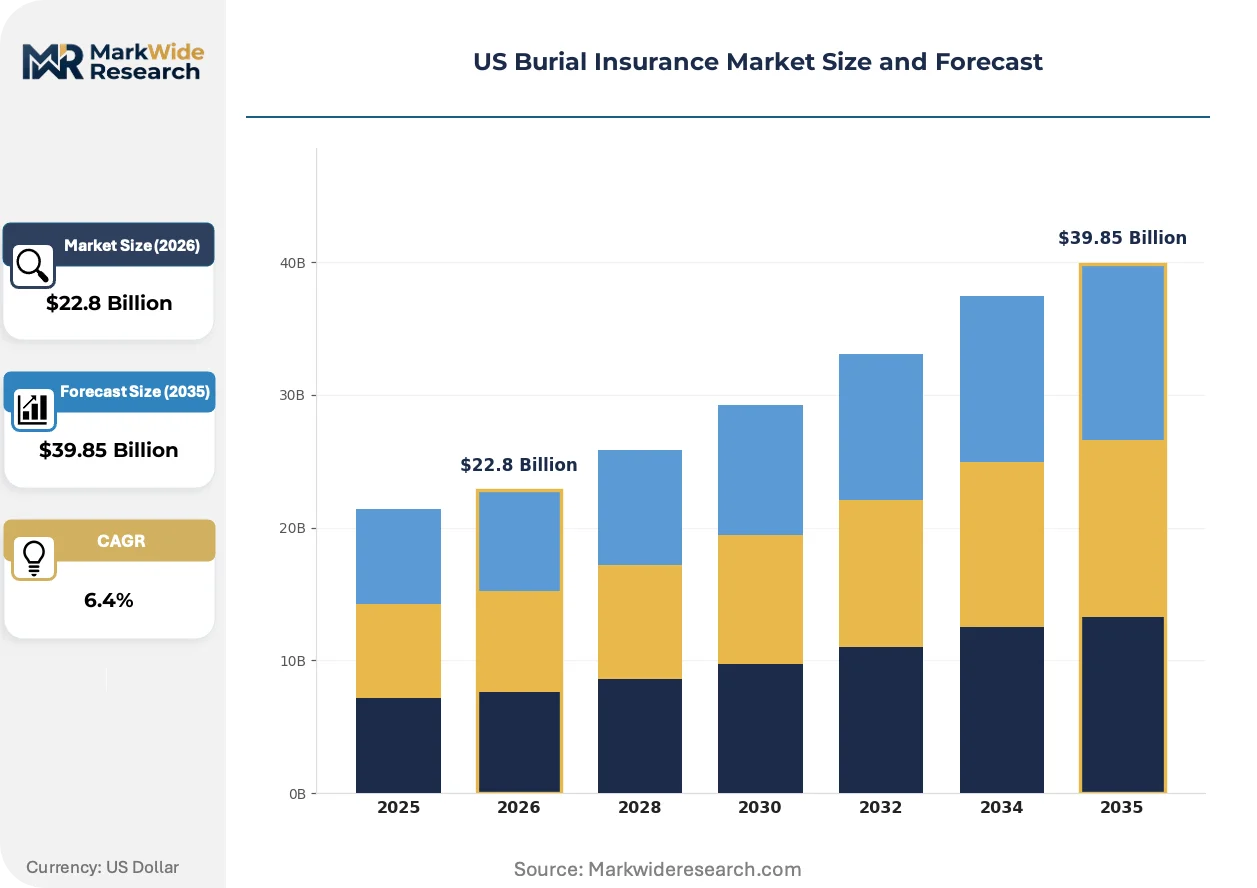
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Whole Life, Term Life, Pre-Need, Final Expense Distribution Channel: Insurance Agents, Online Platforms, Financial Advisors, Direct Mail Customer Type: Individuals, Families, Groups, Seniors Payment Structure: Single Premium, Installment Payments, Level Premium, Adjustable Premium |
| Companies Covered | Physicians Mutual, Transamerica, Mutual of Omaha, Gerber Life Insurance, Ethos, AARP/New York Life, Aflac, American Family, State Farm, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Burial Insurance Market Strategic Shifts & Innovations
Algorithmic decisioning and regulatory tightening are simultaneously reshaping how burial insurance products reach end consumers and how carriers manage long-duration liability.
Predictive analytics engines are migrating from traditional fluid-based underwriting to prescription history and behavioral data scoring. Senior households and their adult children are adopting instant-issue platforms at accelerating velocity. This compression of the application-to-issue cycle is eliminating paramedical examiner networks and reallocating carrier expense budgets toward digital acquisition channels.
State insurance commissioners are enforcing NAIC model laws governing policy replacement disclosures and illustration standards. This regulatory tightening is elevating compliance costs for carriers with multi-state footprints. The final expense segment is responding by centralizing rate filing operations and standardizing product chassis across jurisdictions.
Research workflows now originate on mobile-optimized portals rather than through agent-initiated contact. Adult children investigating final expense options for aging parents are completing application intake before speaking to licensed producers. This channel disintermediation is most pronounced in Sun Belt metropolitan areas where digital literacy among senior-adjacent demographics exceeds national baselines.
US Burial Insurance Market Segmentation
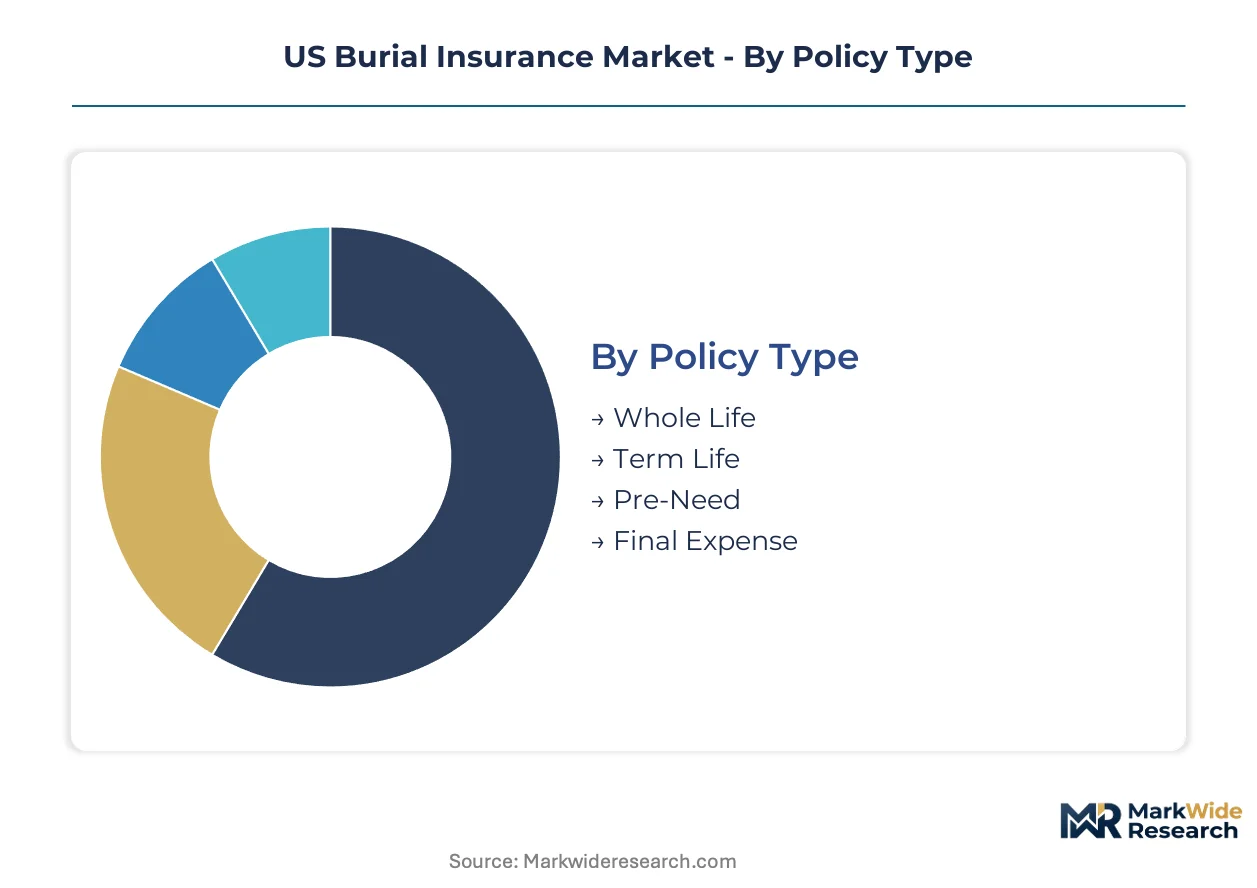
Burial insurance segmentation reveals how product architecture, channel economics, and buyer demographics intersect to create distinct profit pools. Carriers must align underwriting infrastructure with the specific friction points and decision-making patterns of each segment combination.
Policy Type:
Mature whole life products coexist with emerging algorithmic instant-issue formats, creating a bifurcated competitive landscape where legacy carriers defend embedded value while digital entrants capture friction-sensitive demand.
- Whole Life:Permanent coverage with guaranteed level premiums and cash value accumulation. Demand concentrates in Sun Belt states among seniors seeking predictable funeral funding without medical underwriting complexity. Whole life final expense policies generate the thickest margin pools due to non-forfeiture provisions locking in carrier liability for decades.
- Pre-Need:Policies sold through funeral homes with death benefits assigned directly to mortuary operators. Florida, Texas, and Arizona drive uptake where state-regulated trust mechanisms create sticky relationships between policyholders and funeral service providers. NAIC model regulation revisions are tightening illustration standards for these products.
- Final Expense:Simplified issue whole life with death benefits capped between $5,000 and $50,000 explicitly covering funeral services and cemetery plots.
- Term Life:Temporary coverage rarely marketed for burial purposes due to expiration risk mismatching end-of-life expense timing.
Whole life handles the majority of throughput; pre-need is expanding most quickly on share as funeral home networks deepen vertical integration into insurance distribution.
Distribution Channel:
Channel economics stratify sharply between high-touch agent networks and zero-touch digital platforms, with cost per acquisition varying by an order of magnitude across the spectrum.
- Insurance Agents:Captive and independent producers dominate rural and suburban territories where senior trust preferences favor face-to-face consultation. Mutual of Omaha leverages this infrastructure to sustain shelf space in exurban markets underserved by digital-first competitors. HIPAA compliance costs weigh heavier on agent-mediated workflows requiring medical data handling.
- Online Platforms:Mobile-optimized portals enable adult children to complete research and application workflows before licensed producer contact. Ethos and similar entrants compete on collapsing issue timelines from weeks to minutes through predictive mortality models. SEC oversight applies to securities-linked products distributed through these channels.
- Direct Mail:Gerber Life Insurance anchors decades of continuity programs targeting young families with pre-need policy solicitations.
- Financial Advisors:Fee-based planners incorporate final expense coverage into comprehensive estate planning for affluent senior households.
Insurance agents handle the majority of throughput; online platforms are climbing the fastest as sandwich-generation buyers shift research behavior to digital-first discovery.
Customer Type:
Buyer segmentation reflects divergent decision-making authority, with policy ownership often separated from premium payment responsibility across generational lines.
- Seniors:Primary insureds aged 65 and above seeking to eliminate funeral cost burden on surviving family members. Demand concentrates in aging-in-place migration destinations where Medicare eligibility and retirement income stability support premium affordability. Guaranteed issue products attract this segment despite compressed margins from adverse selection.
- Families:Adult children researching and funding policies for aging parents, often completing digital applications on behalf of cognitively declining seniors. This segment drives mobile-optimized portal traffic in metropolitan Sun Belt clusters where digital literacy exceeds national baselines.
- Individuals:Single buyers without dependent survivors purchasing modest coverage for direct funeral expense assignment.
- Groups:Employer-sponsored or association-affiliated burial benefit programs with simplified enrollment.
Seniors handle the majority of throughput; families are gaining share fastest as adult children assume decision-making authority for aging parent care.
Payment Structure:
Premium financing architecture determines carrier cash flow patterns and policy persistency rates, with single premium products front-loading liability recognition.
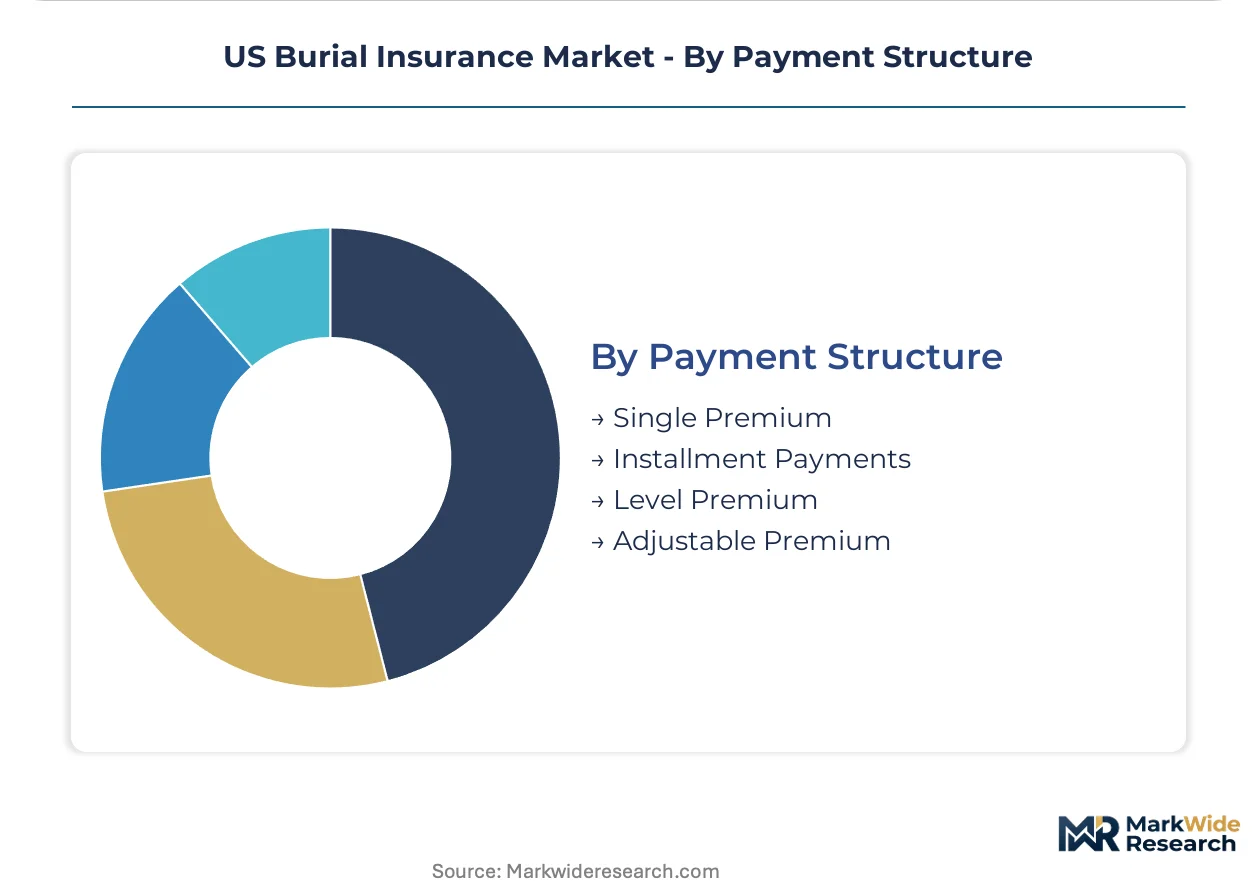
- Level Premium:Fixed periodic payments guaranteed not to increase over the policy duration, creating predictable policyholder budgeting and stable carrier revenue recognition. Whole life final expense products overwhelmingly adopt this structure to align with fixed-income senior household constraints. State insurance commissioners scrutinize level premium illustrations under NAIC model regulations.
- Single Premium:One-time payment eliminating future premium obligation and maximizing immediate cash value accumulation. High-net-worth seniors in Florida and Arizona utilize this structure to deploy retirement account distributions for funeral prefunding.
- Installment Payments:Flexible periodic contributions without guaranteed premium stability, common in pre-need funeral home arrangements.
- Adjustable Premium:Carrier reserve modification rights permitting rate increases under specified mortality experience conditions.
Level premium handles the majority of throughput; single premium is the fastest mover on share as affluent seniors seek to eliminate future payment obligation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Final expense carriers route capital through Sun Belt state trust mechanisms to capture aging-in-place migration flows concentrated in metropolitan funeral service clusters.
Florida
Senior household migration from Midwest and Northeast corridors drives pre-need policy uptake in Tampa and Orlando metropolitan zones. State insurance commissioner oversight enforces NAIC model illustration standards for funeral home trust products. Miami-Dade and Broward counties concentrate carrier back-office operations serving Latin American immigrant communities with bilingual policy servicing.
Texas
Houston and Dallas-Fort Worth metroplexes absorb retiree inflows from California and Rust Belt states seeking lower cost-of-living final expense options. Texas Department of Insurance maintains strict reserve requirements for guaranteed issue products sold through captive agent networks. San Antonio anchors direct-to-consumer digital enrollment testing for carriers refining mobile-optimized senior workflows.
Arizona
Phoenix and Tucson retirement communities generate concentrated demand for single-premium whole life policies funding cemetery plot pre-purchases. Arizona Department of Insurance coordinates with funeral board regulators on pre-need trust funding adequacy reviews. Scottsdale digital literacy rates among adult children exceed national baselines, accelerating mobile portal adoption for parent-sourced policy research.
California
Los Angeles and San Francisco Bay Area ethnic enclaves sustain demand for culturally specific funeral funding arrangements requiring carrier multilingual capabilities. California Department of Insurance enforces stringent replacement disclosure rules under Proposition 103 rate regulation framework. Sacramento hosts regional compliance centers managing HIPAA-constrained medical data sharing with third-party underwriting services.
North Carolina
Charlotte and Raleigh-Durham transplant corridors attract Northeast retirees seeking lower premium final expense products with guaranteed issue features. North Carolina Department of Insurance participates in NAIC working groups standardizing accelerated underwriting engine approval protocols. Greensboro captive agent networks retain shelf space in exurban territories where face-to-face consultation preferences persist among senior households.
US Burial Insurance Market Key Industry Players
Channel-controlling players compete with product-specialist players across a bifurcated structure where captive agent networks defend rural shelf space against digital-first entrants compressing acquisition costs. The competitive terrain stratifies between legacy carriers with decades-old policy administration infrastructure and algorithmic underwriters eliminating paramedical requirements. Three archetypes dominate: mutual insurers leveraging membership structures, stock carriers optimizing for digital conversion velocity, and funeral home verticals integrating pre-need distribution. Consolidation pressure manifests through captive agent network acquisitions and accelerated underwriting engine licensing arrangements.
Among established mutual carriers, Mutual of Omaha and Physicians Mutual occupy positions anchored in agent-mediated distribution across suburban and exurban territories. Gerber Life Insurance exemplifies the direct-mail continuity archetype targeting young families with pre-need solicitations built on decades of brand recognition. Ethos represents the algorithmic instant-issue vector, collapsing traditional underwriting timelines through predictive mortality models and mobile-optimized acquisition flows.
| Leading Market Players |
|---|
| Physicians Mutual |
| Transamerica |
| Mutual of Omaha |
| Gerber Life Insurance |
| Ethos |
| AARP/New York Life |
| Aflac |
| American Family |
| State Farm |
| Others |
Cost & Logistics Intelligence
Actuarial talent concentration in predictive modeling hubs determines where carriers capture margin on algorithmic underwriting products. Digital enrollment infrastructure investments flow disproportionately toward carriers with captive data science capabilities, compressing pricing power for legacy players dependent on third-party mortality scoring services.
Pricing Analysis
Legacy paper-based underwriting commands premium pricing against instant-issue algorithmic products, with the technology-generation gap widening as predictive mortality models mature. Three-tier pricing structure across premium, standard, and economy levels segments buyers by medical disclosure depth and issue speed requirements. Price differentiation rests on exam requirements and data source breadth—prescription history scoring sits below full medical record review. Pricing pressure stems from guaranteed issue loss ratio deterioration in Sun Belt migration corridors. Adult children researching digitally exhibit highest price sensitivity; affluent seniors purchasing single-premium products show lowest.
Supply Chain Analysis
Extended payment terms from funeral home operators to pre-need carriers compress working capital cycles and reshape carrier liquidity management. Mortuary network concentration in Florida, Texas, and Arizona creates geographic supply dependencies for pre-need distribution. Raw material inputs include third-party mortality data from prescription history aggregators, credit bureau scoring services, and HIPAA-compliant medical record clearinghouses. Supply chain risk centers on single-source vulnerability in algorithmic underwriting engine licensing. Distribution runs through captive agent networks in rural territories and mobile-optimized portals in metropolitan Sun Belt clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US burial insurance market exhibits cyclical recovery characteristics as aging-in-place migration patterns concentrate demand in Sun Belt states. Medicare eligibility expansion and retirement income stability support premium affordability through successive economic cycles.
For Market Incumbents: Entrench algorithmic underwriting capabilities through captive data science hiring or targeted mortality model licensing arrangements. Defend rural shelf space by maintaining localized agent infrastructure against digital-first competitors. Consolidate pre-need funeral home relationships through exclusive trust funding arrangements in high-migration states. For New Entrants and Emerging Players: Sandwich-generation adult children in Scottsdale, Tampa, and Dallas-Fort Worth represent the most penetrable entry point for mobile-optimized final expense platforms. Rural exurban territories in North Carolina and Arizona retain white-space opportunity where face-to-face consultation preferences persist. Go-to-market execution should prioritize predictive mortality model accuracy over broad product portfolio breadth. For Investors and Strategic Acquirers: Capital is best deployed toward carriers with established captive agent networks and proprietary underwriting engines rather than pure digital acquisition plays. Long-term viability favors mutual structures with embedded policyholder bases over venture-backed instant-issue specialists. Monitor NAIC model regulation adoption timelines across state insurance departments as inflection indicator for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Underwriting Engine Development | Predictive mortality models using prescription history eliminate paramedical exam requirements and compress issue timelines. |
| Pre-Need Funeral Home Partnership | Exclusive trust funding arrangements with mortuary operators create sticky policyholder relationships in Sun Belt states. |
| Mobile Portal Optimization | Adult children completing parent-sourced policy research on smartphones drive conversion funnel compression. |
| Captive Agent Network Expansion | Localized sales infrastructure retains shelf space value in rural territories underserved by digital competitors. |
| Multi-State Rate Filing Centralization | Standardized product chassis across jurisdictions reduces compliance overhead from NAIC model regulation variations. |
Research Approach
A standing panel of actuarial executives, state insurance commissioners, funeral home operators, and digital enrollment platform product managers provided ongoing calibration throughout the study period. Primary interviews with final expense carrier underwriting heads and pre-need trust administrators combined with secondary validation from NAIC model law filings, state insurance department rate filing databases, and SEC pre-need trust disclosures. Bottom-up policy issuance data triangulated against top-down demographic migration statistics.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions including policy type, distribution channel, customer archetype, and payment structure. CAGRs derived from cohort-level persistency modeling and premium recognition patterns. Forecast inputs incorporated Medicare eligibility trajectories, Sun Belt population projections, and digital adoption curves among senior-adjacent demographics.
Practitioners should monitor guaranteed issue loss ratio deterioration and NAIC model regulation adoption velocity for early signals of margin compression. Forecasts reflect assumptions regarding aging-in-place migration stability and predictive mortality model accuracy improvement. Macroeconomic deviation affecting retirement income security, regulatory shifts in pre-need trust funding requirements, or technological disruption in algorithmic underwriting would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Argentina Life and Non-Life Insurance Market
Life and Non Life Insurance
Brazil Life and Non-Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
Norway Life and Non-Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market
Life and Non Life Insurance
Group Life Insurance Market
Life and Non Life Insurance
Czech Republic Life & Non-Life Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market
Life and Non Life Insurance
Children Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
Denmark Life and Non-Life Insurance Market
Life and Non Life Insurance
Finland Life and Non-Life Insurance Market
Life and Non Life Insurance
France Life and Non-Life Insurance Market
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
South Korea Life & Non-Life Insurance Market