
 Children Life Insurance Market | 2026-2036
Children Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Children Life Insurance Market Insights
Capital-intensity divergence between legacy carriers and digital-first entrants is collapsing as cloud-native policy administration platforms slash fixed infrastructure requirements. Allianz leverages its multi-country agency footprint to sustain premium collection density across European and Asian markets. Ping An dominates in China through integrated health-and-wealth ecosystems that embed child coverage within family financial planning portals. Gerber Life Insurance specializes in direct-to-consumer juvenile whole life products that anchor brand recognition among first-time parent demographics.
Children life insurance constitutes a risk-transfer contract where an insurer promises a death benefit upon the covered minor's passing, with whole life variants building cash value through guaranteed crediting rates and participating dividends. The product serves primarily as a long-term financial instrument for funeral expense coverage, future insability locks, and supplemental family wealth accumulation. Term life policies for minors occupy the largest premium pool due to low entry costs, while whole life and endowment structures capture the deepest margin concentration from cash-value accumulation riders. Online platforms and embedded bancassurance channels represent the fastest-growing distribution vectors as embedded finance APIs reduce friction in policy origination.
US state insurance commissioners enforce reserve adequacy and illustration standards under NAIC model laws, while China's NMPA and banking regulators supervise product filing and sales conduct for minor-targeted policies. The EU's Insurance Distribution Directive and GDPR-compliant data handling requirements shape cross-border digital marketing and policy servicing protocols. Stakeholders must monitor evolving suitability standards for juvenile policy recommendations and the pace of regulatory acceptance for algorithmic underwriting in minor risk assessment.
Market Dynamics
Digital underwriting platforms are collapsing policy issuance timelines from weeks to minutes, forcing legacy carriers to abandon paper-based medical exams and agent-driven sales workflows for API-enabled embedded distribution.
Growth Catalysts
- NAIC Model Laws:Standardized illustration regulations across US state insurance commissioners reduce compliance fragmentation for carriers expanding multi-state juvenile product lines.
- Embedded Finance APIs:Bancassurance channels integrate child coverage into family banking portals, capturing parents during routine wealth management transactions.
- Working Parent Demographics:Dual-income households with dependent minors prioritize guaranteed insurability locks as core financial planning instruments.
Market Restraints
- Interest Rate Sensitivity:Guaranteed crediting rates on whole life cash value components compress margins when central bank policy rates diverge from actuarial assumptions.
- Legacy Core Systems:Mainframe-based policy administration platforms at established carriers resist real-time data integration with digital distribution partners.
- Moral Hazard Perception:Consumer advocacy scrutiny of juvenile death benefit motivations limits mass-market advertising channels and social media targeting.
Strategic Opportunities
- India's Bancassurance Expansion:RBI-supervised banking networks remain underpenetrated for child-centric protection products relative to adult life coverage saturation.
- Health-Wealth Convergence:Integration of pediatric wellness tracking with policy premium discounts creates stickier family ecosystem relationships.
- Simplified Issue Algorithms:Predictive mortality models using prescription history and credit data enable instant underwriting without medical exams.
Industry Challenges
- Actuarial Talent Scarcity:Juvenile mortality table expertise concentrates among retiring practitioners, constraining product development velocity.
- State-by-State Filing Complexity:Product form approvals require navigating divergent illustration standards across 56 US jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Children Life Insurance Market |
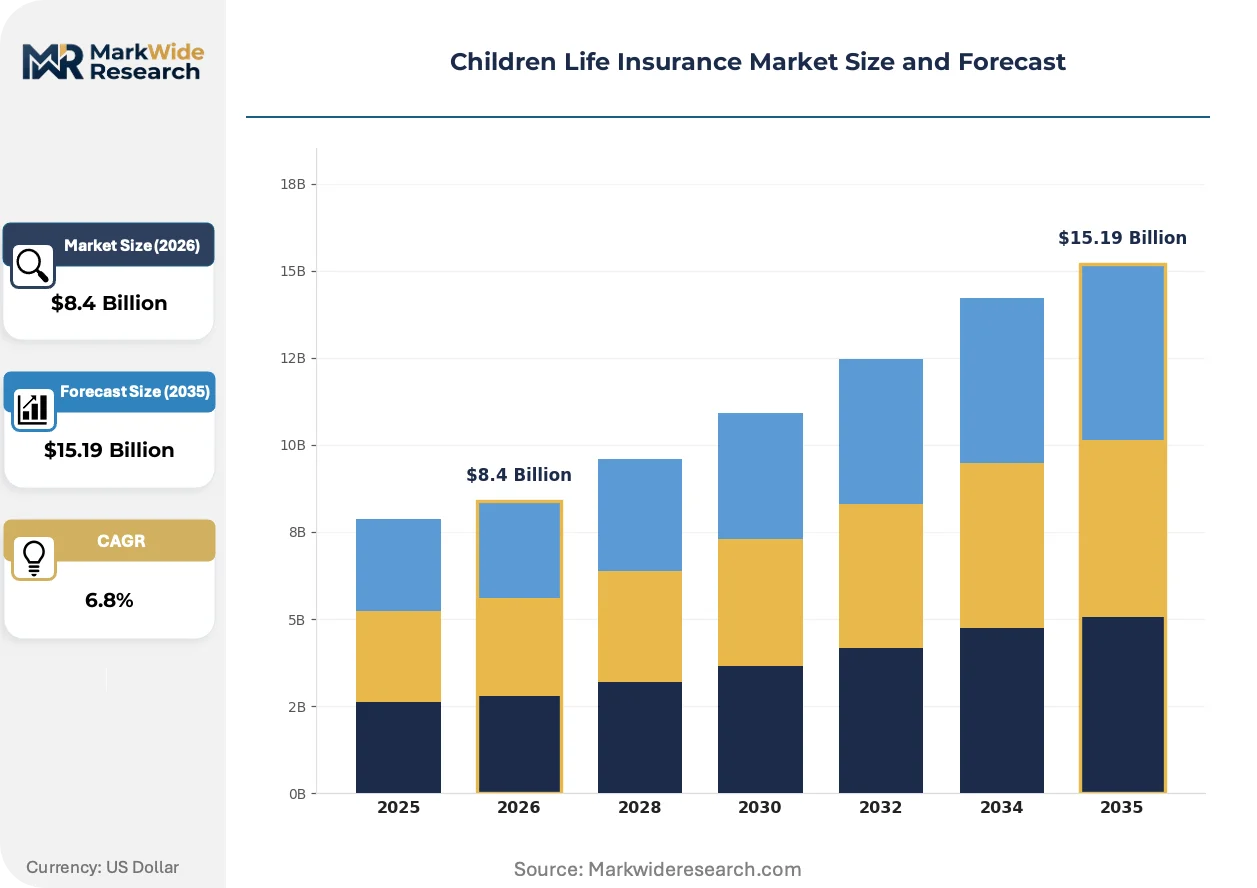
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Term Life, Whole Life, Endowment, Universal Life, Variable Life Distribution Channel: Agent/Broker, Bancassurance, Direct Sales, Online Platforms, Telemarketing Benefit Rider: Critical Illness, Accidental Death, Disability, Waiver of Premium, Hospital Cash Customer Segment: Parents, Guardians, Grandparents, Relatives |
| Companies Covered | Allianz, MetLife, China Life Insurance, Ping An, Assicurazioni Generali, AXA, Gerber Life Insurance, AIG, Sumitomo Life Insurance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Children Life Insurance Market Trends and Innovations
Algorithmic risk assessment is dismantling traditional underwriting hierarchies while embedded distribution architectures embed insurance into non-insurance customer journeys.
Telematics-enabled wellness monitoring is fragmenting the standard mortality risk pool. Wearable devices tracking pediatric activity and sleep patterns allow carriers to price policies using continuous behavioral data rather than static demographic tables. Millennial parents adopting these devices for health management now expect premium adjustments reflecting actual lifestyle metrics, compressing the uniform pricing models that sustained traditional juvenile whole life products.
China's NMPA supervision of minor-targeted policy sales conduct is tightening disclosure requirements for cash-value illustrations. The regulator now mandates plain-language benefit explanations and cooling-off period extensions for policies sold through digital channels. Domestic carriers are responding by restructuring product designs toward shorter premium payment periods and more transparent surrender value schedules.
Direct-to-consumer platforms are displacing agent-mediated acquisition for first-time parent segments. Insurtech portals offering side-by-side whole life comparisons capture buyers researching options during pregnancy planning phases. This shift is most pronounced in suburban US markets where time-constrained dual-income households prioritize digital self-service over scheduled agent consultations.
Children Life Insurance Market Segmentation
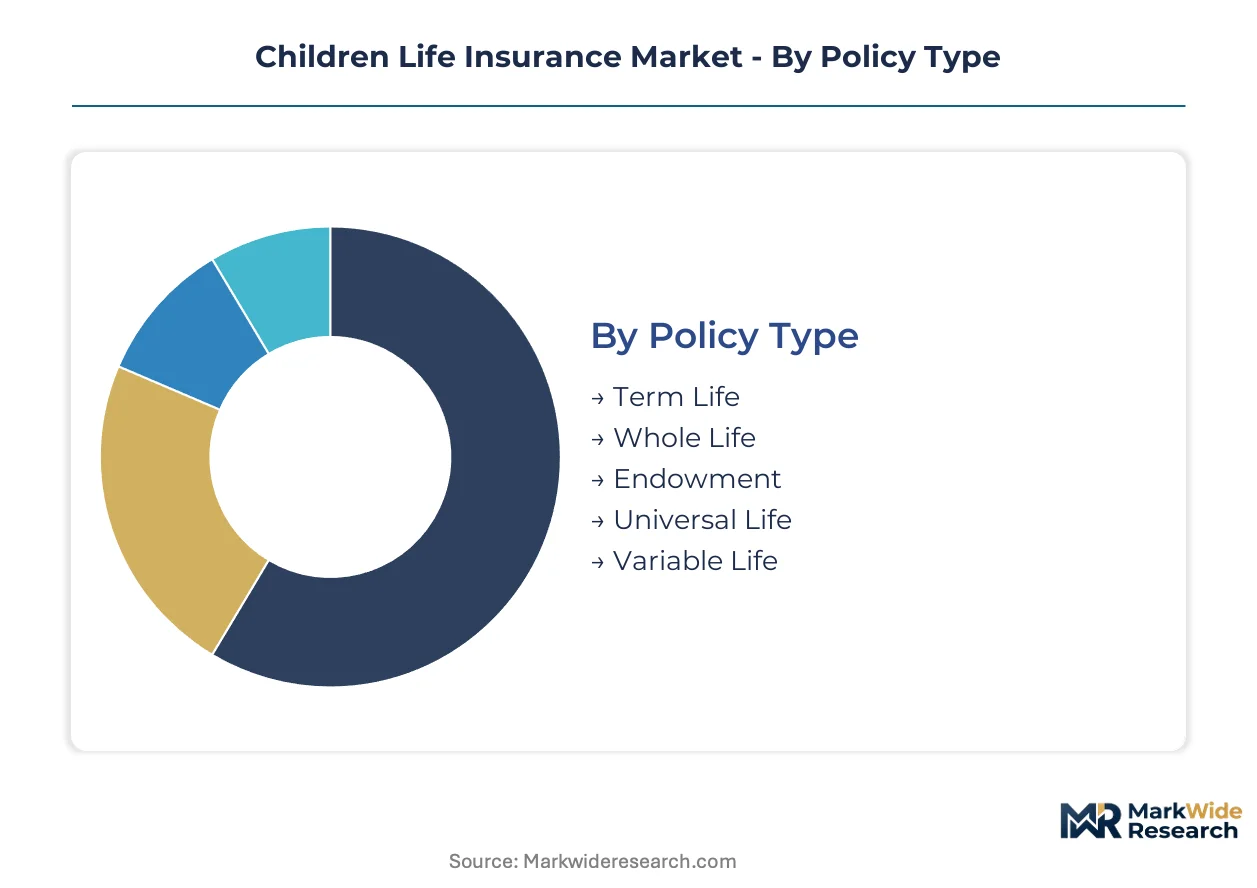
Children life insurance products fragment across policy structures, distribution modalities, benefit configurations, and purchaser relationships. Each dimension carries distinct margin profiles and regulatory exposure that shape carrier portfolio strategy.
Policy Type:
Margin pools concentrate in cash-value products where guaranteed crediting rates and participating dividends generate spread income, while term structures compete on premium volume.
- Whole Life:Permanent coverage with guaranteed death benefit and cash value accumulation through fixed crediting rates. Demand clusters among dual-income households in suburban US markets seeking guaranteed insurability locks and supplemental family wealth accumulation.
- Term Life:Pure death benefit protection with no cash value component, typically featuring level premiums for fixed durations. This segment commands the largest premium pool due to low entry costs, attracting first-time parents prioritizing funeral expense coverage over investment features.
- Endowment:Hybrid structure combining life protection with maturity payouts, popular in Asian markets where savings-linked protection dominates household financial planning.
- Universal Life:Flexible premium and adjustable death benefit designs allowing policyholder control over cash value growth.
- Variable Life:Cash value tied to separate account investments, subject to securities regulation and market risk disclosure requirements.
The dominant share belongs to Term Life, while Whole Life is closing the gap fastest through simplified issue digital distribution.
Distribution Channel:
Cost tier differentiation separates high-touch agent relationships from zero-touch digital acquisition, with embedded finance APIs collapsing the middle ground.
- Online Platforms:Direct-to-consumer portals enabling side-by-side product comparison and instant underwriting through algorithmic risk assessment. These channels are expanding most quickly among millennial parents researching options during pregnancy planning phases.
- Agent/Broker:Traditional face-to-face consultation model sustaining premium collection density through trust-based advisory relationships, particularly for whole life products requiring explanation of cash value mechanics.
- Bancassurance:Embedded distribution through banking networks capturing parents during routine wealth management transactions, with RBI-supervised Indian banks showing particular underpenetration relative to adult coverage saturation.
- Direct Sales:Carrier-owned outbound operations targeting existing customer bases for cross-sell expansion.
- Telemarketing:Scripted phone-based acquisition, increasingly restricted by GDPR-compliant data handling requirements and consumer protection scrutiny.
Agent/Broker retains the dominant share, though Online Platforms are gaining share fastest through API-enabled embedded distribution.
Benefit Rider:
Application-specific attachments transform base policies into comprehensive family protection instruments, with health-linked riders commanding premium pricing.
- Critical Illness:Lump-sum payment upon diagnosis of specified pediatric conditions, increasingly integrated with wellness tracking devices for premium discount eligibility.
- Waiver of Premium:Continues policy coverage without premium payments during policyholder disability, a standard inclusion in parent-purchased juvenile contracts.
- Accidental Death:Supplemental benefit for death resulting from covered accidents, common in term life base structures.
- Disability:Income replacement or benefit acceleration for covered minor disabilities.
- Hospital Cash:Daily indemnity for inpatient stays, popular in markets with high out-of-pocket medical exposure.
Critical Illness holds the dominant share, while Waiver of Premium is climbing the fastest as working parents prioritize income protection.
Customer Segment:
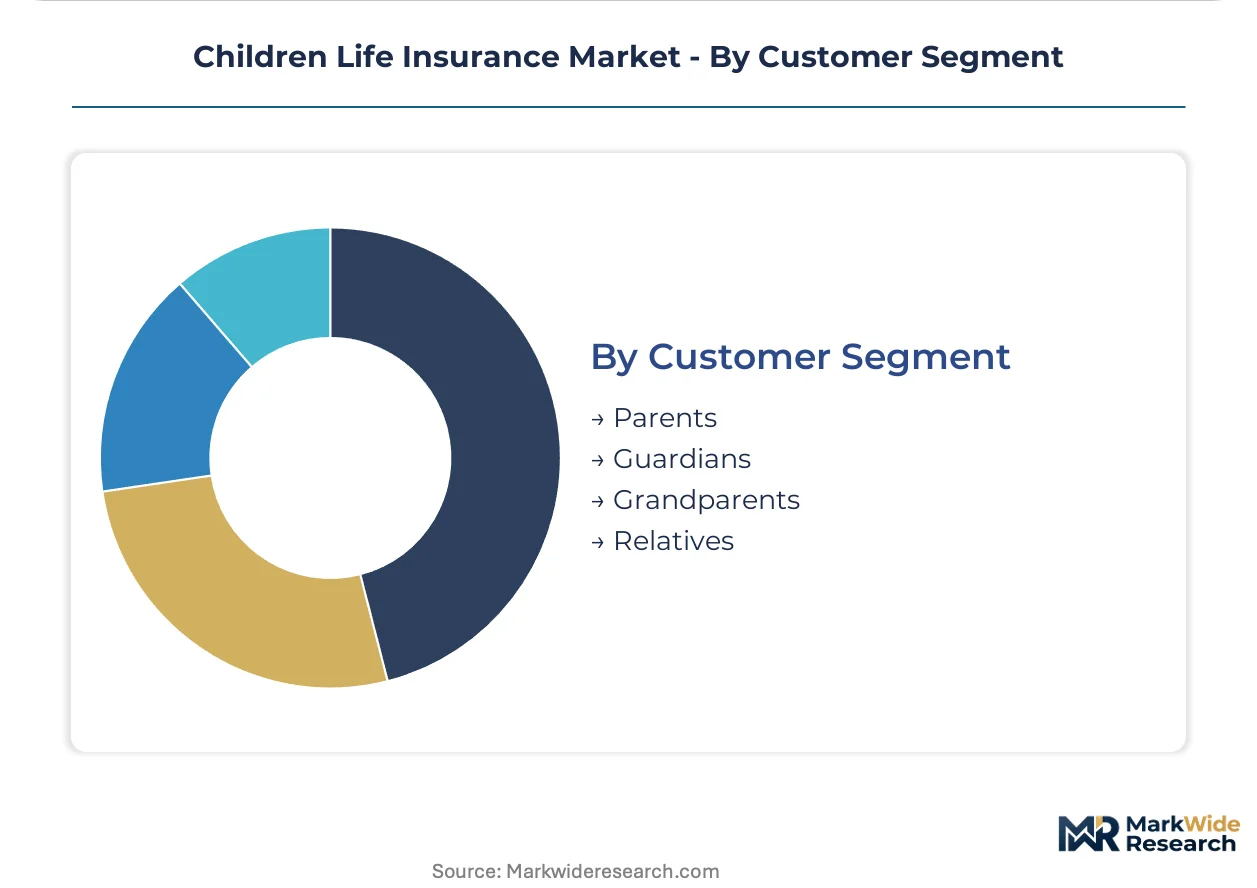
Purchaser relationship to the insured minor determines policy motivation, premium capacity, and regulatory suitability scrutiny intensity.
- Parents:Biological or adoptive parents representing the core buyer segment, with working parent demographics driving fastest expansion as dual-income households formalize child-centric financial planning.
- Grandparents:Intergenerational purchasers motivated by estate planning and guaranteed insurability gifts, concentrated in markets with strong multigenerational household traditions.
- Guardians:Legal custodians purchasing coverage for wards, subject to enhanced disclosure requirements regarding insurable interest documentation.
- Relatives:Extended family members including aunts, uncles, and siblings, a segment constrained by moral hazard perception and suitability standard enforcement.
Parents command the dominant share, while Grandparents are expanding most quickly as estate tax planning integrates juvenile policies into wealth transfer strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in the United States while China's regulatory environment compresses distribution margins. European carriers navigate fragmented national regulations that sustain higher compliance costs. India's bancassurance penetration lags adult coverage saturation, creating expansion headroom.
United States
Dual-income suburban households drive demand for guaranteed insurability locks and cash-value accumulation products. State insurance commissioners enforce NAIC model laws governing reserve adequacy and illustration standards across 56 jurisdictions. Digital underwriting platforms in California and Texas are collapsing policy issuance timelines from weeks to minutes.
China
Ping An's integrated health-and-wealth ecosystems embed child coverage within family financial planning portals. The NMPA mandates plain-language benefit explanations and cooling-off period extensions for digitally sold policies. Domestic carriers in Shanghai and Shenzhen are restructuring products toward shorter premium payment periods.
India
RBI-supervised banking networks remain underpenetrated for child-centric protection relative to adult life coverage saturation. The central bank's bancassurance guidelines shape product filing and sales conduct for minor-targeted policies. Mumbai and Delhi clusters show accelerating embedded finance API adoption for policy origination.
Germany
Allianz leverages its multi-country agency footprint to sustain premium collection density across European markets. The EU's Insurance Distribution Directive and GDPR-compliant data handling requirements shape cross-border digital marketing protocols. Frankfurt and Munich insurance clusters concentrate actuarial expertise for juvenile mortality table development.
Japan
Sumitomo Life Insurance anchors distribution through traditional agent networks serving multigenerational household traditions. METI supervision and JIS standards govern product transparency and suitability documentation. Tokyo and Osaka metropolitan areas concentrate demand for endowment-linked juvenile protection products.
Children Life Insurance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the children life insurance market. Legacy carriers with established agency networks sustain premium collection density through trust-based advisory relationships. Digital-first entrants capture millennial parents through API-enabled embedded distribution and algorithmic underwriting. The competitive terrain rewards two dominant moves: strategic partnerships with banking networks for bancassurance expansion, and portfolio diversification into health-wealth convergence products.
Among global multi-line carriers, Allianz and MetLife exemplify the established archetype with geographic diversification across European and North American markets. Within the Asia-Pacific concentration, Ping An and China Life Insurance occupy positions reflecting integrated ecosystem strategies. Gerber Life Insurance represents the specialist archetype focused on direct-to-consumer juvenile whole life products. These named players anchor the competitive structure without exhausting its full composition.
| Leading Market Players |
|---|
| Allianz |
| MetLife |
| China Life Insurance |
| Ping An |
| Assicurazioni Generali |
| AXA |
| Gerber Life Insurance |
| AIG |
| Sumitomo Life Insurance |
| Others |
Pricing and Supply Chain Analysis
Cloud-native policy administration platforms slash fixed infrastructure requirements for digital-first carriers, collapsing the capital-intensity gap with legacy players and compressing price floors across distribution tiers. This scale-driven cost compression reshapes competitive positioning as algorithmic underwriting eliminates medical exam overhead and embedded finance APIs reduce acquisition expenses.
Pricing Analysis
The customization-premium spread separates configured-to-order whole life policies with cash-value riders from standardized term life products. Pricing stratifies across premium, standard, and economy tiers based on underwriting complexity and distribution channel cost. Cost compression in term life is intensifying because embedded bancassurance channels eliminate agent commission layers. First-time parents researching during pregnancy planning phases show highest price sensitivity, while grandparents purchasing guaranteed insurability gifts demonstrate lowest sensitivity to premium differentials.
Supply Chain Analysis
Strategic stockpiling of actuarial talent and mortality table expertise dominates inventory strategy as juvenile specialization concentrates among retiring practitioners. Policy administration technology draws from the United States, Ireland, and India for cloud infrastructure and software development. Raw material dependencies center on mortality data licensing, reinsurance capacity, and regulatory compliance systems. Single-source vulnerability in actuarial expertise constrains product development velocity. Distribution runs through API-enabled embedded finance partnerships with banking networks and direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents early-cycle expansion as embedded finance APIs penetrate bancassurance channels previously dependent on branch-based sales workflows. Working parent demographics formalizing child-centric financial planning anchor this penetration tailwind.
For Market Incumbents: Secure algorithmic underwriting capabilities through strategic technology partnerships to defend against insurtech entrants collapsing issuance timelines. Acquire cloud-native policy administration platforms to eliminate mainframe integration friction with digital distribution partners. Channel control through exclusive bancassurance relationships with RBI-supervised Indian banks offers defensive positioning in underpenetrated markets. For New Entrants and Emerging Players: Lead with simplified issue whole life products targeting suburban dual-income households during pregnancy planning phases. India's bancassurance expansion presents the most penetrable geography given adult coverage saturation and regulatory openness to embedded finance APIs. Direct-to-consumer comparison portals with side-by-side product visualization offer the strongest go-to-market angle against agent-mediated acquisition. For Investors and Strategic Acquirers: Specialist juvenile carriers with established direct-to-consumer brand recognition and proprietary mortality data assets represent priority acquisition targets. Long-term viability hinges on health-wealth convergence capabilities integrating pediatric wellness tracking with policy structures. Watch NMPA regulatory acceptance of algorithmic underwriting in minor risk assessment as the critical inflection signal for digital-first valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Bancassurance Partnership | Captures parents during routine wealth management transactions through API-enabled policy origination. |
| Algorithmic Underwriting Deployment | Collapses issuance timelines from weeks to minutes using prescription history and credit data models. |
| Health-Wealth Platform Integration | Creates sticky family ecosystem relationships through pediatric wellness tracking and premium discounts. |
| Simplified Issue Product Launch | Targets time-constrained millennial parents prioritizing digital self-service over agent consultations. |
| Actuarial Talent Acquisition | Addresses expertise scarcity constraining juvenile mortality table development and product velocity. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with insurance product development executives, actuarial directors, bancassurance channel managers, and digital distribution platform engineers; and secondary validation through NAIC model law filings, NMPA product registration databases, RBI bancassurance circulars, carrier statutory financial statements, and embedded finance API documentation. Bottom-up policy issuance volume estimates triangulated against top-down premium pool calculations derived from regulatory filings and industry association aggregates.
Across the analysis window, forecasts model policy type segmentation, distribution channel evolution, benefit rider attachment rates, and purchaser relationship dynamics. CAGRs derive from regression analysis of historical issuance patterns against demographic and regulatory drivers. Key inputs include working parent household formation rates, cloud infrastructure cost curves, and algorithmic underwriting adoption trajectories.
Forecasts assume regulatory continuity in NAIC-model US state regimes, NMPA supervision frameworks, and RBI bancassurance guidelines; material policy shifts would require re-modeling. Moral hazard scrutiny of juvenile death benefit motivations and interest rate divergence from guaranteed crediting assumptions constitute specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market
Life and Non Life Insurance
USA Life and Non-Life Insurance Market
Life and Non Life Insurance
Brazil Life and Non-Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Uruguay Life and Non-Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Asia Pacific Life & Non-Life Insurance Market
Life and Non Life Insurance
Norway Life and Non-Life Insurance Market
Life and Non Life Insurance
Iran Property and Casualty Insurance Market
Life and Non Life Insurance
UAE Life and Annuity Insurance Market
Life and Non Life Insurance
Peru Life and Non-Life Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
Life Reinsurance Market
Life and Non Life Insurance
Asia Life and Non-Life Insurance Market