
 Norway Life and Non-Life Insurance Market | 2026-2036
Norway Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Life and Non-Life Insurance Market Analytics
Bancassurance channels is rewriting distribution economics across Norway's insurance sector. Storebrand Forsikring leverages its banking parent network to dominate life policy origination through branch advisors. Gjensidige Forsikring ASA anchors its non-life portfolio in rural agency networks while competing aggressively in digital direct sales. Tryg Forsikring specializes in commercial property lines, sustaining premium flow from Oslo's construction and maritime clusters.
Norway life and non-life insurance constitutes contractual risk transfer instruments where insurers pool premiums to indemnify policyholders against mortality, morbidity, property damage, or liability events, governed by Solvency II capital adequacy ratios and local tariff regulations. The product type dimension splits into life insurance, health insurance, property insurance, and liability insurance, with property and health lines capturing accelerated premium growth as climate exposure and outpatient cost inflation intensify. Customer type segmentation spans individual policyholders, corporate clients, SMEs, and non-profits, where SME buyers generate the fastest policy count expansion yet corporate clients retain the deepest per-account revenue pools.
Finanstilsynet, Norway's financial supervisory authority, enforces Solvency II-derived capital requirements that shape product pricing and reserve adequacy across domestic underwriters. The EU Green Deal's sustainable finance taxonomy increasingly conditions investment-linked life products, pressuring insurers to restructure underlying asset portfolios. Stakeholders must monitor how Finanstilsynet interprets forthcoming EIOPA guidelines on climate scenario stress testing, as this will determine which product lines require repricing or coverage restriction.
Market Dynamics
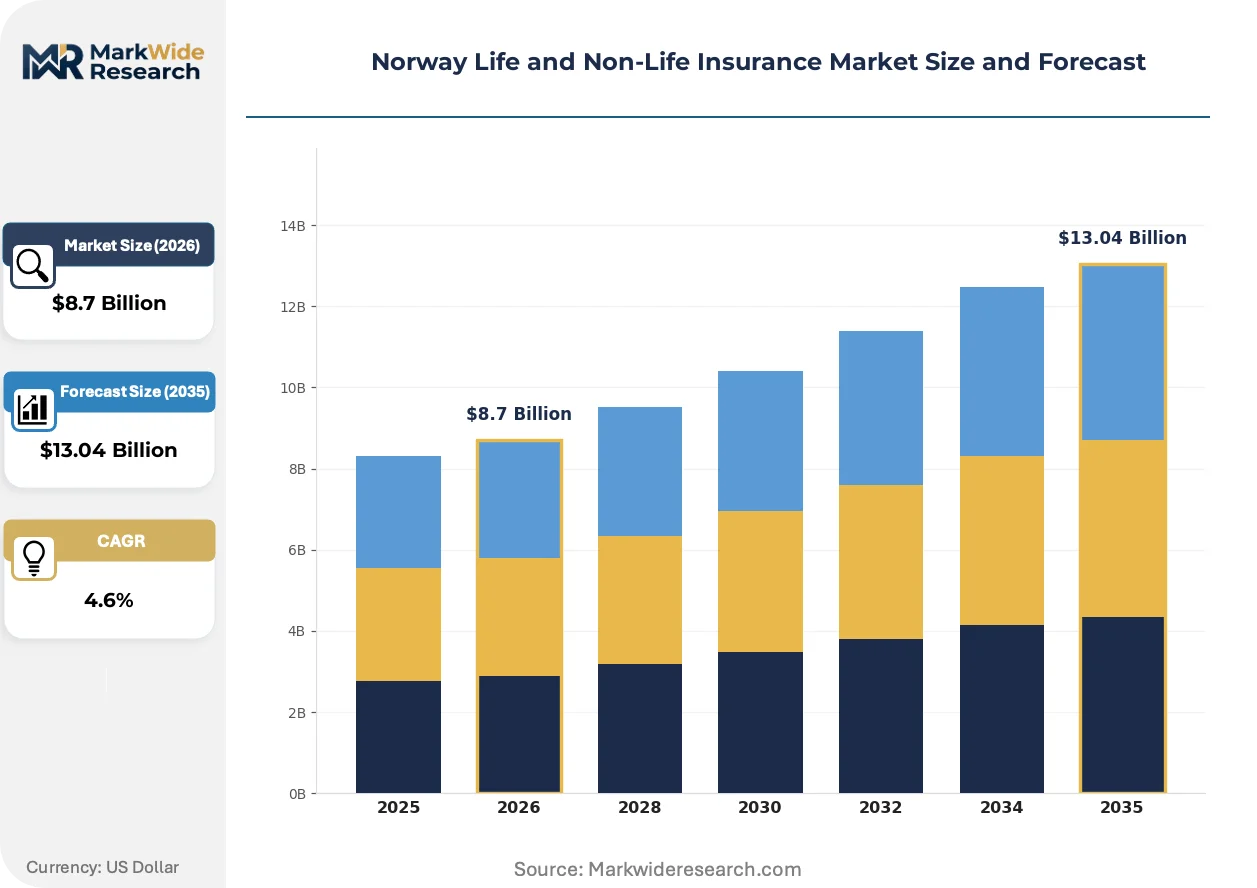
Finanstilsynet's phased implementation of EIOPA climate stress-testing guidelines is compressing capital allocation timelines across Norwegian underwriters, forcing rapid repricing of coastal property portfolios and fossil-linked investment products before the 2027 deadline.
Growth Catalysts
- EU Green Deal taxonomy alignment:Investment-linked life products must restructure underlying asset portfolios toward sustainable finance categories, creating product innovation cycles as insurers develop climate-certified annuity structures.
- Oslo SME digital adoption:Small and medium enterprises in Norway's capital region are migrating policy procurement to broker platforms, expanding addressable premium pools through reduced friction in commercial lines placement.
- Solvency II capital optimization:Norwegian carriers are redesigning reinsurance treaties and liability durations to improve solvency ratios, releasing trapped capital for geographic expansion within Nordic markets.
Market Restraints
- Coastal catastrophe exposure concentration:Western Norway's fjord-adjacent property stock faces unmodeled avalanche and storm-surge accumulation, limiting reinsurance capacity availability for regional non-life writers.
- Long-duration guarantee drag:Legacy life policies with minimum return promises written during higher interest rate regimes continue consuming statutory reserves, constraining new business capital deployment.
- Substitution by pension fund self-insurance:Large Norwegian corporate pension schemes are internalizing mortality risk through captive structures, bypassing traditional group life carriers for covered employee populations.
Strategic Opportunities
- Northern Norway underpenetration:Troms and Finnmark counties exhibit sub-60 percent household insurance penetration versus Oslo's saturation, offering whitespace for micro-policy distribution through mobile-first platforms.
- Maritime cyber liability emergence:Oslo's shipping clusters are generating demand for vessel operational technology coverage as IMO cybersecurity mandates expand, creating specialized line expansion for marine underwriters.
- API-enabled embedded insurance:Norwegian fintech-bank partnerships are integrating property and travel coverage into mortgage and payment workflows, capturing policyholders at point-of-transaction rather than renewal cycles.
Industry Challenges
- Actuarial climate modeling capability gaps:Norwegian carriers lack sufficient geospatial data science talent to parameterize EIOPA-mandated scenario analysis, forcing reliance on external vendor models with opaque assumptions.
- Core system modernization debt:Policy administration platforms dating from the 1990s require multimillion-krone replacement to support real-time premium adjustment and automated claims triage, straining IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Life and Non-Life Insurance Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, Property Insurance, Liability Insurance Customer Type: Individual Policyholders, Corporate Clients, SMEs, Non-Profits Service Model: Direct Sales, Online Platforms, Agents, Brokers Coverage Type: Comprehensive Coverage, Basic Coverage, Add-Ons, Exclusions |
| Companies Covered | Fremtind Forsikring AS, Storebrand Forsikring, Gjensidige Forsikring ASA, Frende Forsikring, Protector Forsikring ASA, If Skadeforsikring, SpareBank 1 Forsikring AS, KLP Skadeforsikring, Tryg Forsikring, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Life and Non-Life Insurance Market Evolving Landscape
Digitization is collapsing traditional intermediation layers across Norwegian insurance, while regulatory climate mandates and shifting buyer expectations are redefining product architecture and distribution economics simultaneously.
Telematics-enabled usage-based motor coverage is virtualizing risk assessment from annual pooling to real-time individual behavior pricing. Younger drivers in Bergen and Stavanger are adopting pay-per-kilometer policies through smartphone-app data capture. This granular segmentation is compressing cross-subsidy structures that historically balanced portfolio profitability across demographic cohorts.
Finanstilsynet's interpretation of forthcoming EIOPA climate scenario guidelines is forcing premature reserve strengthening for coastal property and energy transition-exposed commercial lines. Domestic underwriters are responding by restricting coverage terms in Vestland county flood zones and demanding elevated deductibles for oil-service contractor liability. The regulatory pressure is accelerating product withdrawal decisions ahead of formal compliance deadlines.
Norwegian corporate risk managers are unbundling insurance placement from traditional broker relationships, establishing direct digital interfaces with underwriters for mid-market commercial accounts. Manufacturing SMEs in Drammen and Fredrikstad are piloting self-service policy configuration tools that bypass advisory layers entirely. This disintermediation is most pronounced in property and general liability lines where coverage standardization permits algorithmic quoting without manual underwriting intervention.
Norway Life and Non-Life Insurance Market Segmentation
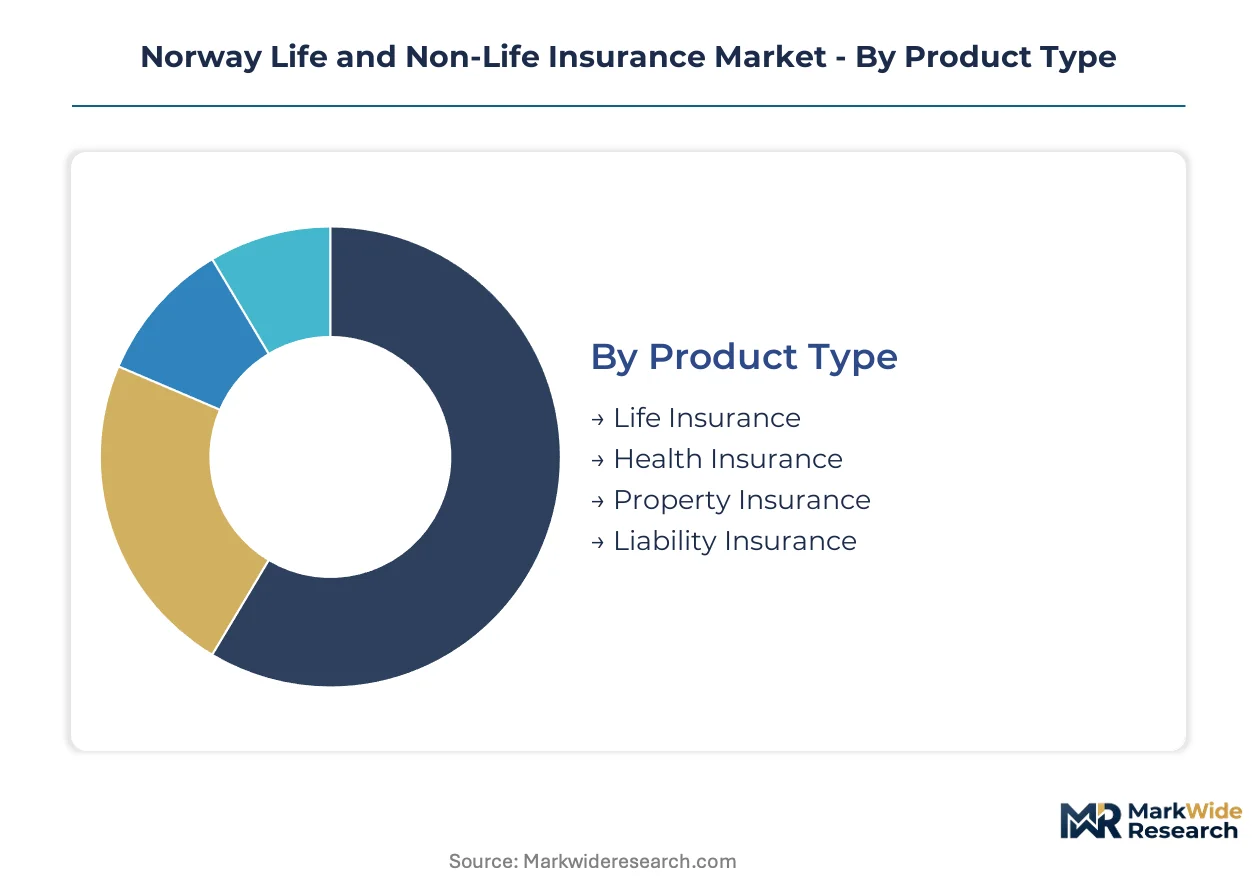
Segmentation in Norway's insurance sector reveals how capital allocation, regulatory pressure, and buyer sophistication fragment premium flows across distinct risk pools. Understanding these divisions exposes where Finanstilsynet's solvency rules bite hardest and where distribution innovation unlocks margin expansion.
Product Type:
After-sales service intensity varies dramatically across product lines, with life and health policies demanding sustained policyholder engagement through beneficiary updates and claims advocacy, while property lines require rapid loss adjustment and reconstruction coordination.
- Life Insurance:Long-duration contracts pool mortality risk through guaranteed benefit structures and investment-linked wrappers. Oslo's financial district concentrates demand for unit-linked products as wealth managers seek tax-advantaged accumulation vehicles for high-net-worth clients facing Solvency II capital charge scrutiny.
- Health Insurance:Outpatient cost reimbursement and supplementary hospital coverage dominate this segment. Bergen's private clinic networks drive supplemental policy uptake as public queue times extend, particularly among corporate group schemes seeking employee retention leverage.
- Property Insurance:Coastal exposure concentration in Vestland and Møre og Romsdal shapes coverage terms and reinsurance placement.
- Liability Insurance:Professional indemnity and directors' coverage expands with Oslo's fintech incorporation boom.
Life Insurance holds the largest share; momentum sits with Health Insurance as outpatient cost inflation accelerates policy attachment rates.
Customer Type:
Cost tier stratification separates this dimension, with corporate clients commanding bespoke risk engineering and captive feasibility studies while individual buyers navigate standardized product shelves.
- Individual Policyholders:Retail buyers purchase through bank branches, digital direct channels, and comparison platforms. Oslo and Akershus counties exhibit saturation-level penetration for core life and property lines, forcing carriers toward cross-sell sophistication rather than new customer acquisition.
- Corporate Clients:Large enterprises negotiate multi-line global programs with local admitted paper requirements. Stavanger's energy sector and Oslo's maritime clusters generate complex casualty and marine liability placements demanding specialized underwriting capacity.
- SMEs:Drammen and Fredrikstad manufacturing clusters migrate toward self-service digital procurement.
- Non-Profits:Volunteer liability and property coverage for cultural institutions in Trondheim and Bergen.
Corporate Clients contribute the deepest per-account revenue; SMEs are climbing the fastest as digital distribution reduces placement friction.
Service Model:
Volume concentration patterns distinguish distribution economics, with bancassurance channels capturing premium scale through embedded origination while digital platforms compete on acquisition cost efficiency.
- Direct Sales:Carrier-employed advisors and telephone operations target simple product categories. Gjensidige Forsikring ASA maintains rural direct sales presence where agency density remains insufficient for physical distribution.
- Online Platforms:Comparison aggregators and insurer-owned portals enable self-service quoting. Younger demographics in Bergen and Stavanger adopt smartphone-app policy management for motor and travel coverage.
- Agents:Tied and multi-tied representatives provide advisory depth for complex life and commercial lines.
- Brokers:Independent intermediaries handle corporate risk placement and program design.
Direct Sales retains the largest premium volume; Online Platforms are gaining share fastest as SME buyers bypass traditional advisory layers.
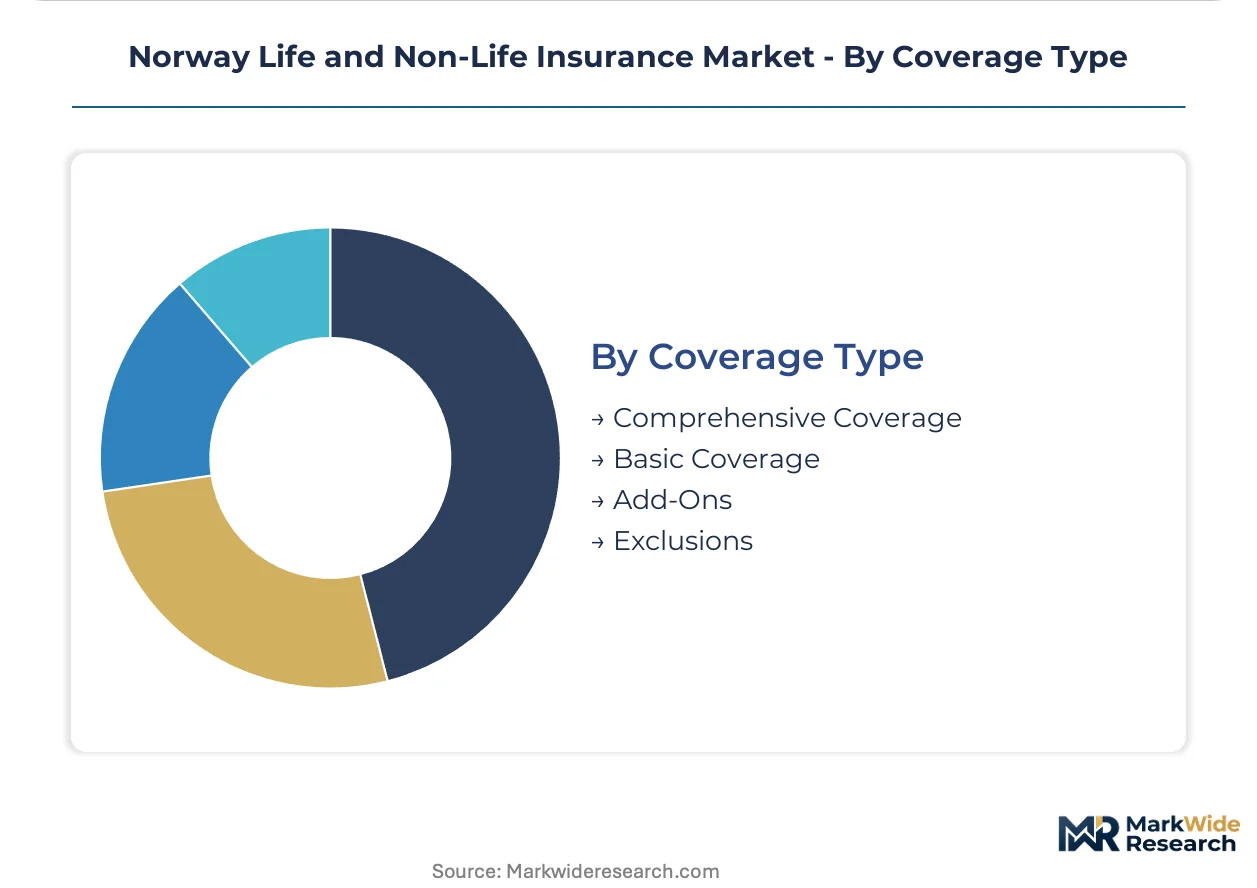
Coverage Type:
Margin architecture separates this dimension, with comprehensive offerings capturing full premium per risk unit while add-ons generate incremental attachment revenue without proportional acquisition cost.
- Comprehensive Coverage:All-risk property and bundled life-health combinations dominate corporate placement. Oslo commercial real estate portfolios demand broad peril protection including business interruption and contingent liability extensions.
- Basic Coverage:Named-peril fire and statutory minimum motor liability serve price-sensitive segments. Northern Norway household penetration relies on stripped-down products distributed through mobile-first platforms.
- Add-Ons:Cyber extensions, legal expense, and travel disruption riders attach to base policies.
- Exclusions:Explicit carve-outs for flood, earthquake, and terrorism shape pricing clarity.
Comprehensive Coverage commands the largest premium base; Add-Ons show the steepest expansion trajectory as carriers monetize existing policyholder relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finanstilsynet's Solvency II implementation anchors Norway's insurance regulatory framework, shaping capital allocation across domestic underwriters and conditioning product availability in coastal and metropolitan zones.
Oslo and Akershus
Corporate group life schemes and investment-linked products concentrate in the capital region's financial district. Finanstilsynet's capital adequacy reviews pressure insurers to reserve against long-duration guarantee obligations. Digital broker platforms capture SME commercial lines placement as manufacturing and maritime clusters seek streamlined procurement.
Vestland
Coastal property exposure drives non-life premium intensity in Bergen and surrounding fjord municipalities. EU Green Deal taxonomy alignment forces restructured investment portfolios for locally domiciled underwriters. Avalanche and storm-surge accumulation risks limit reinsurance capacity, compressing coverage terms for waterfront commercial real estate.
Rogaland
Stavanger's energy sector generates complex casualty and marine liability demand. Corporate pension schemes internalize mortality risk through captive structures, bypassing traditional group life carriers. Offshore contractor liability lines face elevated deductibles as climate transition exposure intensifies.
Trøndelag
Trondheim's public sector and educational institutions anchor non-profit liability and property coverage. Rural agency networks retain distribution relevance where digital penetration lags metropolitan benchmarks. Regional health insurance attachment rises as private clinic networks expand outpatient service capacity.
Troms and Finnmark
Sub-60 percent household insurance penetration creates whitespace for micro-policy distribution through mobile-first platforms. Arctic construction and logistics clusters generate specialized commercial lines demand. Geographic isolation elevates claims adjustment costs, conditioning pricing structures for remote property coverage.
Norway Life and Non-Life Insurance Market Competitive Landscape
Bancassurance networks and rural agency systems split the market between embedded origination and traditional advisory distribution. Tiered concentration prevails: banking-affiliated carriers leverage branch infrastructure for life policy scale, while independent underwriters compete on commercial lines specialization and digital direct acquisition efficiency. Strategic moves center on reinsurance treaty redesign for Solvency II optimization and API-enabled embedded insurance partnerships with fintech platforms.
Within the bancassurance tier, Storebrand Forsikring and SpareBank 1 Forsikring AS occupy positions anchored to parent banking networks. Gjensidige Forsikring ASA exemplifies the hybrid archetype, maintaining rural agency density while competing in digital direct channels. Tryg Forsikring represents commercial specialization, with positioning tied to Oslo's maritime and construction clusters. These three carriers illustrate how distribution heritage and sectoral focus stratify competitive positioning across Norway's regulated landscape.
| Leading Market Players |
|---|
| Fremtind Forsikring AS |
| Storebrand Forsikring |
| Gjensidige Forsikring ASA |
| Frende Forsikring |
| Protector Forsikring ASA |
| If Skadeforsikring |
| SpareBank 1 Forsikring AS |
| KLP Skadeforsikring |
| Tryg Forsikring |
| Others |
Value Network & Pricing Analysis
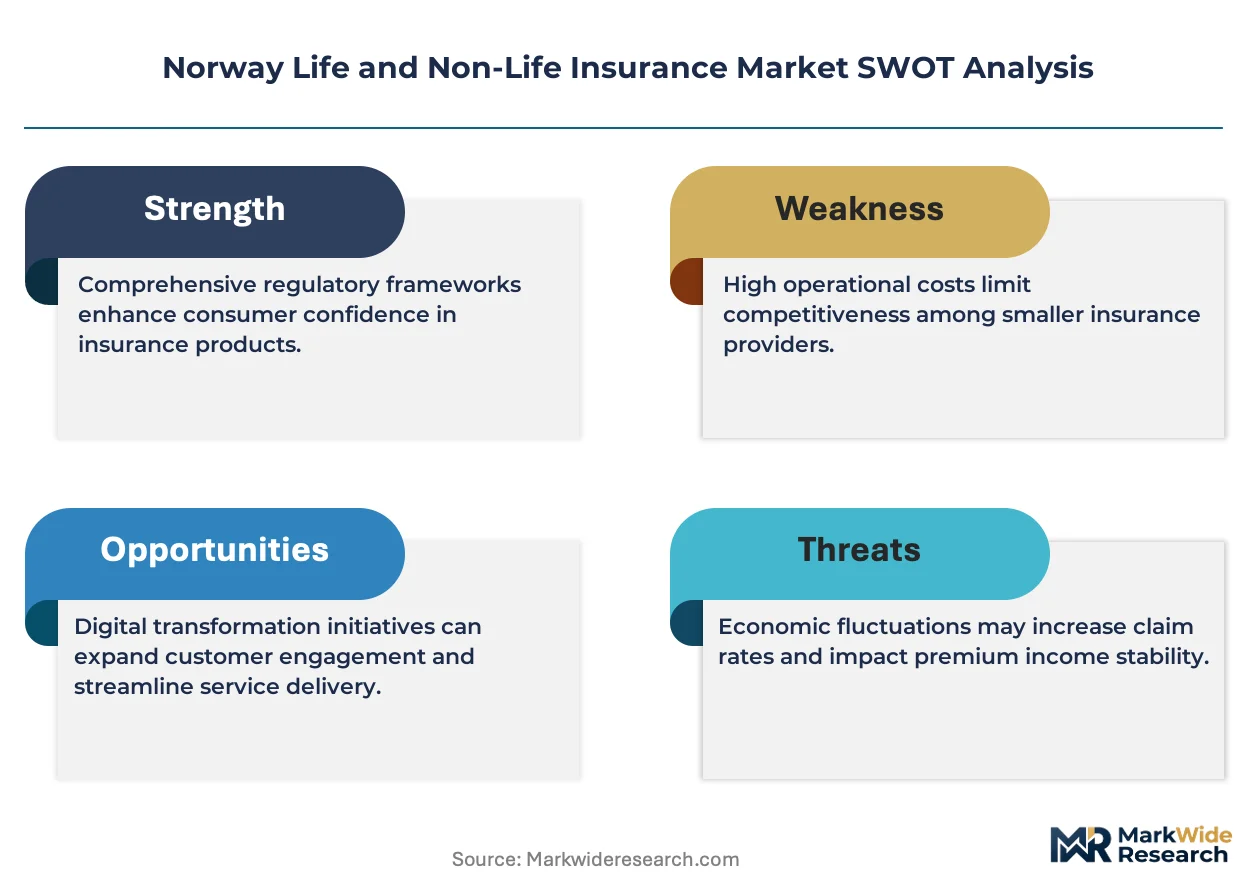
Finanstilsynet's Solvency II capital adequacy requirements constitute the dominant regulatory chokepoint determining both premium tier spreads and distribution infrastructure shape across Norwegian insurance. The authority's risk-based capital charges compress margins on long-duration life guarantees while elevating pricing power for short-tail commercial lines, forcing carriers to restructure reinsurance placement and agency compensation simultaneously.
Pricing Analysis
The customization-premium spread separates configured-to-order corporate global programs from standardized individual policies. Three-tier pricing structure across premium, standard, and economy levels dominates, with price differentiation driven by Solvency II capital intensity and geographic delivery cost. Pricing pressure stems from legacy guarantee drag consuming statutory reserves. Corporate buyers exhibit lowest price sensitivity; Northern Norway households show highest sensitivity.
Supply Chain Analysis
Reinsurance capacity concentration in Germany, Switzerland, and Bermuda anchors Norwegian carriers' risk transfer arrangements. Cedents draw from Lloyd's syndicates, continental European reinsurers, and Bermudian property catastrophe specialists for coastal exposure coverage. Single-source vulnerability concentrates in avalanche and storm-surge modeling vendors. Distribution runs through bancassurance networks, rural agency systems, and emergent API-enabled embedded partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as SME buyers disaggregate from traditional broker relationships and demand self-service digital procurement. This demand-side unbundling creates niche openings for specialized underwriters and technology-enabled distributors.
For Market Incumbents: Entrench through reinsurance treaty redesign optimizing Solvency II solvency ratios and captive in-house climate modeling capability building. Counter emerging digital-native distributors by tightening API partnership exclusivity with fintech platforms. Prioritize vertical integration into geospatial data science talent acquisition. For New Entrants and Emerging Players: Troms and Finnmark counties' sub-60 percent household penetration offers whitespace for mobile-first micro-policy distribution. Target maritime cyber liability in Oslo's shipping clusters where IMO mandates expand coverage gaps. Pursue API-enabled embedded insurance integration with mortgage and payment workflows as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors carriers with proprietary climate risk data assets and Solvency II optimization expertise. Long-term viability across the projection horizon hinges on regulatory interpretation agility and technology infrastructure modernization. Monitor Finanstilsynet's EIOPA climate stress-testing implementation timeline as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Reinsurance Treaty Redesign | Optimizes Solvency II capital ratios and releases trapped premium capacity for Nordic expansion. |
| Climate Modeling Capability Buildout | Reduces dependency on opaque external vendor assumptions for EIOPA scenario compliance. |
| API-Enabled Embedded Partnership | Captures policyholders at mortgage origination and payment transaction points rather than renewal cycles. |
| Core System Modernization | Replaces 1990s-era policy administration platforms to support real-time premium adjustment automation. |
| Mobile-First Distribution Platform | Penetrates Northern Norway's underinsured households through smartphone-native micro-policy sales. |
Research Methodology
A spread of perspectives from chief risk officers, actuarial directors, Finanstilsynet supervisory staff, reinsurance placement brokers, and SME procurement managers converged on the working assumptions. Primary interview insights combined with secondary validation from Finanstilsynet solvency reports, EIOPA regulatory guidelines, Norwegian Insurance Association statistical publications, and carrier annual disclosures. Bottom-up premium flow analysis triangulated against top-down macroeconomic scenario testing.
Demand-supply-balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled encompass product type, customer archetype, service model, and coverage tier, with geographic exposure concentration and regulatory capital treatment as industry-specific overlays. CAGRs derived from premium growth trajectory analysis adjusted for reinsurance capacity constraints and legacy reserve absorption rates. Climate scenario stress-testing implementation timelines and digital distribution adoption curves served as forecast sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by insurtech platforms or captive pension self-insurance expansion would shift outcomes. Quarterly review of Finanstilsynet regulatory circulars and reinsurance renewal pricing trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
Poland Life and Non-Life Insurance Market
Life and Non Life Insurance
Australia Life and Non-Life Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
Argentina Life and Non-Life Insurance Market
Life and Non Life Insurance
Germany Life and Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
France Life and Non-Life Insurance Market
Life and Non Life Insurance
Life Insurance Policy Administration System Market
Life and Non Life Insurance
Russia Life and Non-Life Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market