
 Brazil Life and Non-Life Insurance Market | 2026-2036
Brazil Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Life and Non-Life Insurance Market Insights
Actuarial data science talent scarcity is redrawing competitive boundaries among Brazilian insurers. Bradesco Seguros leverages its captive banking network to sustain premium flow through embedded product offerings. SulAmérica anchors its position through specialized health underwriting expertise. MAPFRE VIDA competes via international reinsurance backing that extends capital capacity for long-duration life liabilities.
Brazil life and non-life insurance encompasses risk-transfer contracts where insurers pool premiums to indemnify policyholders against mortality, morbidity, property damage, or liability exposures, with technical reserves held against future claims obligations and regulated solvency margins ensuring contractual performance. The sector's primary commercial purpose centers on converting uncertain individual losses into predictable pooled costs, enabling productive investment and consumption continuity across households and enterprises. Term life products dominate individual protection volumes due to accessible entry pricing, while health coverage under corporate group policies captures the fastest-growing premium pool as employer-sponsored benefits expand. Motor insurance retains mature, margin-compressed characteristics amid intense price competition, though telematics-linked pricing is emerging as a differentiation vector.
SUSEP, Brazil's private insurance superintendence, mandates minimum capital requirements and product filing approvals that shape market access timelines for new entrants. ANS, the national supplementary health agency, imposes benefit-package minimums and tariff adjustment limits that constrain health insurer pricing flexibility. The Central Bank of Brazil oversees PIX infrastructure standards that insurers must adopt for premium and claims flows. Stakeholders should monitor regulatory convergence between SUSEP and international solvency standards as a determinant of capital deployment efficiency and foreign reinsurer participation terms.
Market Dynamics
PIX instant-payment infrastructure is compressing settlement cycles across Brazil's insurance value chain, forcing incumbents to rebuild core systems around real-time liquidity while new entrants exploit API-native architectures to bypass legacy batch-processing constraints.
Growth Catalysts
- Central Bank PIX Mandate:SUSEP-aligned adoption of instant-payment rails accelerates premium collection velocity and claims disbursement speed, reducing policyholder friction in São Paulo's bancassurance corridors.
- Agribusiness Risk Transfer:Mato Grosso soybean and corn operations are expanding parametric crop coverage as climate volatility intensifies, pulling specialized underwriters into Brazil's interior.
- Embedded Distribution:Digital banking platforms are integrating microinsurance products at transaction touchpoints, converting payment behavior into protection sales without dedicated agent networks.
Market Restraints
- Solvency Capital Lockup:SUSEP-mandated technical reserve requirements tie up substantial float in low-yielding government securities, compressing investment income during Brazil's rate normalization cycle.
- Reinsurance Supply Concentration:International reinsurer appetite for Brazilian longevity risk fluctuates with global capital market conditions, creating capacity squeezes for life insurers writing long-duration annuities.
- Legacy Core System Debt:COBOL-based policy administration platforms at established carriers impose integration costs that exceed greenfield technology investments, slowing product iteration cycles.
Strategic Opportunities
- Northeast Regional Underpenetration:Ceará and Pernambuco exhibit protection gaps relative to southeast income levels, creating whitespace for simplified term-life products distributed through retail correspondent banking.
- Telematics-Linked Motor Pricing:Usage-based insurance models using smartphone-enabled driving behavior scoring are displacing traditional risk-pooling in São Paulo's congested urban corridors.
- Corporate Wellness Convergence:ANS-regulated group health policies are absorbing preventive care and mental health modules, expanding premium per employee beyond indemnification into subscription-like service bundles.
Industry Challenges
- Actuarial Data Science Scarcity:Brazilian universities produce insufficient graduates combining statistical modeling with insurance domain expertise, forcing carriers to poach from fintech analytics teams at wage premiums.
- PIX Integration Complexity:Real-time payment reconciliation demands API overhauls of policy administration systems originally architected for monthly batch cycles, straining IT delivery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Life and Non-Life Insurance Market |
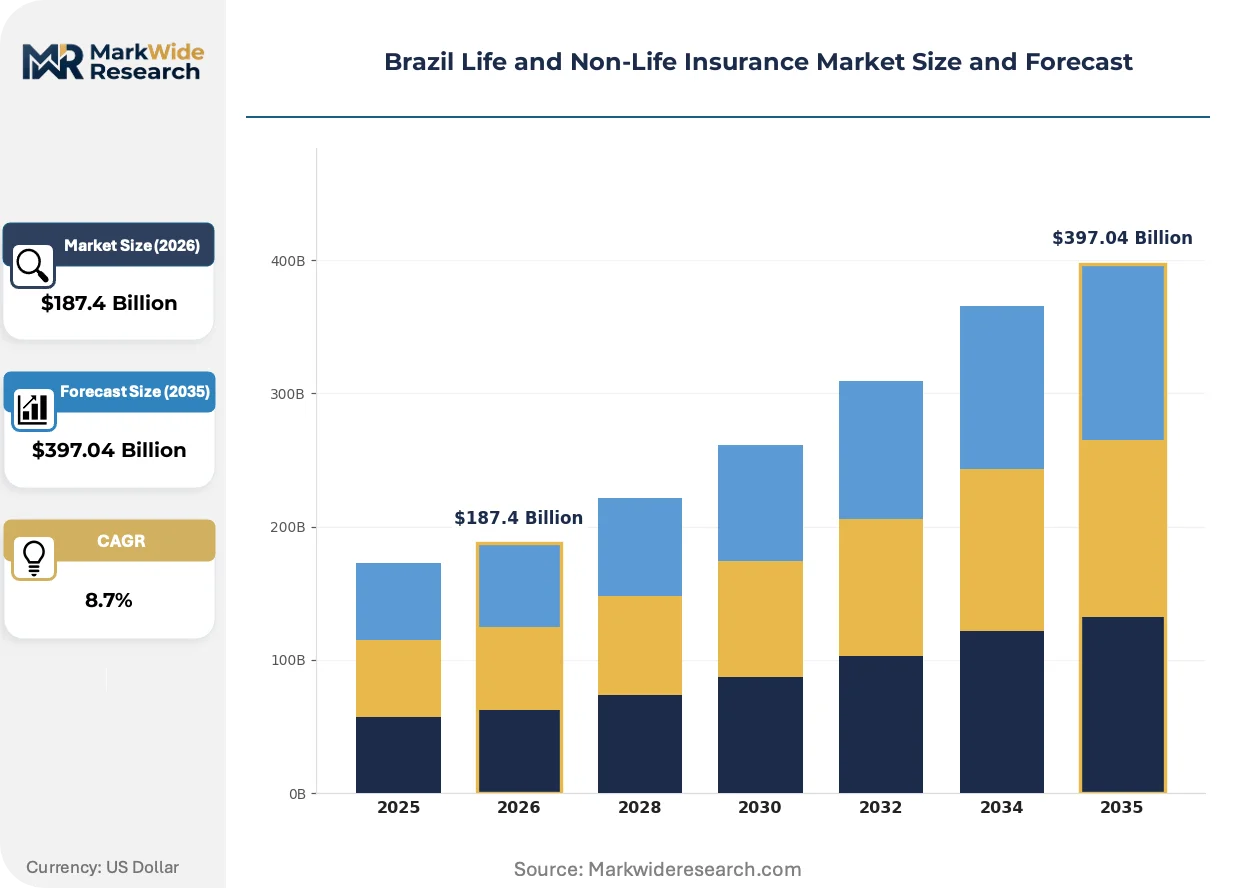
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Term Life, Whole Life, Universal Life, Endowment Insurance Coverage Type: Health, Property, Motor, Liability Distribution Channel: Direct Sales, Brokers, Online Platforms, Agents Customer Type: Individuals, Corporates, SMEs, Institutions |
| Companies Covered | BrasilSeg, Bradesco Seguros, SulAmérica, Porto Seguro, Caixa Seguridade, MAPFRE VIDA, Tókio Marine Seguradora, Itaú Seguros, Allianz Seguros, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Life and Non-Life Insurance Market Trends and Innovations
Algorithmic underwriting and open-finance data sharing are dismantling traditional risk-assessment bottlenecks, while regulatory pressure on interoperability accelerates platform consolidation across Brazil's fragmented insurance distribution layer.
Telematics-enabled motor pricing is displacing traditional actuarial tables in Brazil's auto insurance segment. Fleet operators in São Paulo's logistics corridor are adopting smartphone-based driving behavior scoring to secure premium discounts. This displacement compresses cross-subsidization between safe and risky drivers, eroding the pooled-risk model that sustained incumbent market share.
SUSEP's convergence roadmap with international solvency standards is tightening capital adequacy disclosure requirements for Brazilian insurers. Foreign reinsurers are demanding granular asset-liability matching data before extending capacity for long-duration life products. The life insurance segment is responding by shortening product durations and accelerating reserve de-risking into inflation-linked government bonds.
Employers in Brazil's formal sector are unbundling traditional group health packages into modular, employee-selected coverage tiers. Corporate benefits administrators in Rio de Janeiro and São Paulo are replacing one-size-fits-all policies with cafeteria-style selections where workers trade premium levels against deductible and network breadth. This fragmentation is most visible in technology and financial services verticals where talent competition demands personalized benefits positioning.
Brazil Life and Non-Life Insurance Market Segmentation
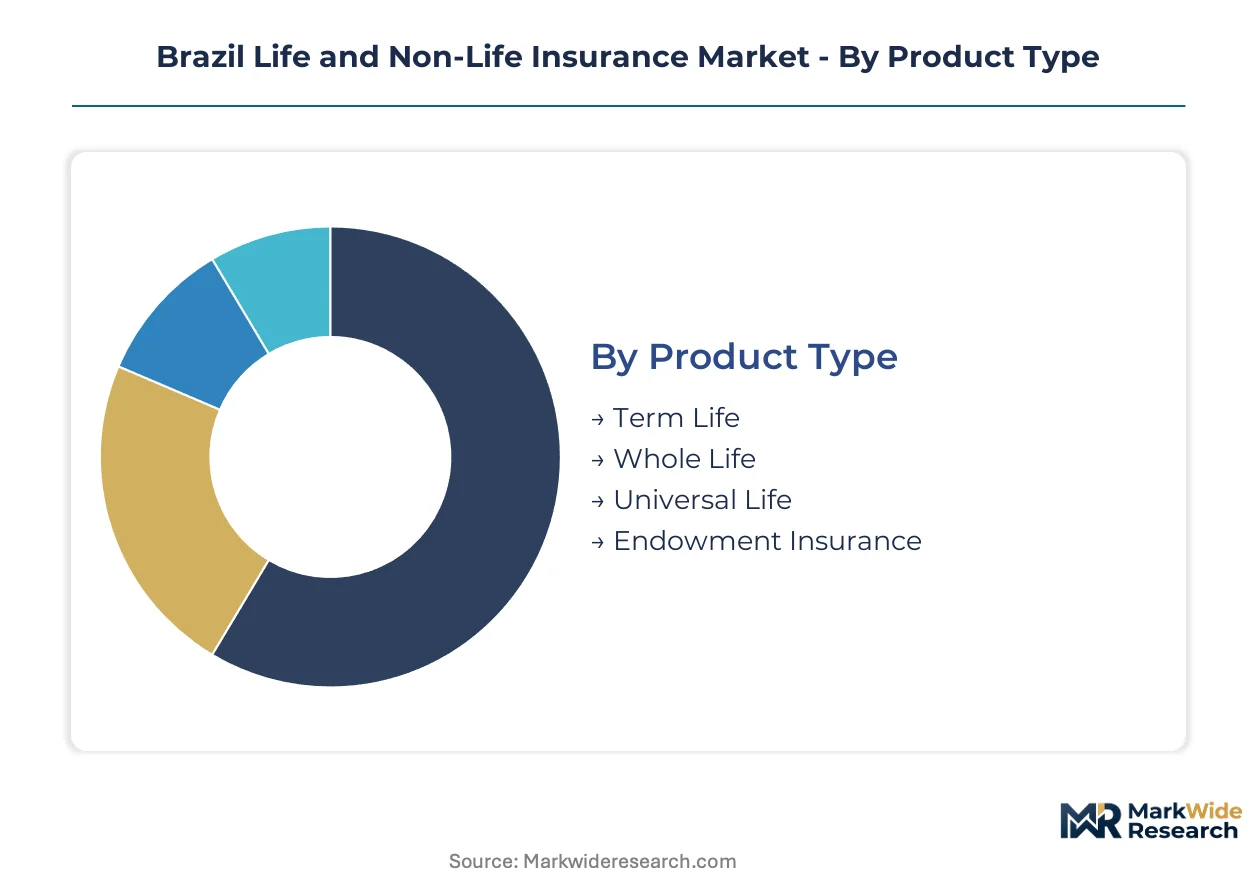
Segmentation in Brazil's insurance sector exposes where capital efficiency diverges across product structures, risk pools, and distribution economics. Understanding these fault lines clarifies why certain carriers concentrate in specific verticals while others pursue diversified portfolios.
Product Type:
Margin pools concentrate in products with longer duration and lower lapse sensitivity, where investment income compounds against technical reserves.
- Term Life:Pure mortality protection with no cash value accumulation and fixed premium periods. Demand clusters among São Paulo's formal sector employees seeking accessible entry pricing, though lapse rates spike during economic contractions.
- Whole Life:Permanent coverage combining guaranteed death benefit with conservative cash value growth backed by insurer general account assets. Corporate benefits administrators in Rio de Janeiro favor this structure for executive retention packages due to stable reserve mechanics.
- Universal Life:Flexible premium and adjustable death benefit products tied to declared crediting rates. SUSEP disclosure requirements on illustrated versus guaranteed returns constrain sales velocity.
- Endowment Insurance:Savings-linked contracts paying lump sums at maturity or death, historically popular among Brazilian middle-income households. Regulatory pressure on embedded commission structures is compressing distributor enthusiasm.
Whole Life holds installed capacity. Term Life is rotating up the share rankings.
Coverage Type:
Application concentration tracks Brazil's economic structure, with agribusiness property exposure and urban motor liability commanding distinct underwriting skill sets.
- Health:ANS-regulated supplementary medical coverage spanning hospitalization, outpatient procedures, and preventive care. Employer-sponsored group policies in São Paulo's financial corridor absorb the steepest expansion trajectory as talent competition intensifies.
- Property:Physical asset protection against fire, natural catastrophe, and theft exposures. Mato Grosso soybean operators are expanding parametric crop coverage as climate volatility intensifies, pulling specialized underwriters into Brazil's interior.
- Motor:Compulsory third-party liability and optional comprehensive vehicle coverage. Telematics-linked pricing using smartphone-enabled driving behavior scoring is displacing traditional risk-pooling in congested urban corridors.
- Liability:Professional indemnity, directors and officers, and product liability protections. Demand from Brazilian exporters facing international contractual requirements is climbing fastest.
Health maintains the dominant premium share. Liability is climbing fastest.
Distribution Channel:
Cost tier differentiation separates high-touch advisory relationships from automated transaction capture, with technology investment requirements widening the competitive moat.
- Direct Sales:Insurer-controlled channels including captive agents and proprietary call centers. Bradesco Seguros leverages its captive banking network to sustain premium flow through embedded product offerings.
- Brokers:Independent intermediaries advising on complex commercial risks and placement into reinsurance markets. SulAmérica anchors relationships through specialized health underwriting expertise.
- Online Platforms:Digital-native distribution with API-driven quote-to-bind workflows. PIX instant-payment integration enables real-time premium collection without legacy batch-processing constraints.
- Agents:Tied representatives with exclusive or preferred carrier arrangements. Regulatory pressure on commission disclosure is eroding traditional incentive structures.
Direct Sales retains scale advantages. Online Platforms are gaining share fastest.
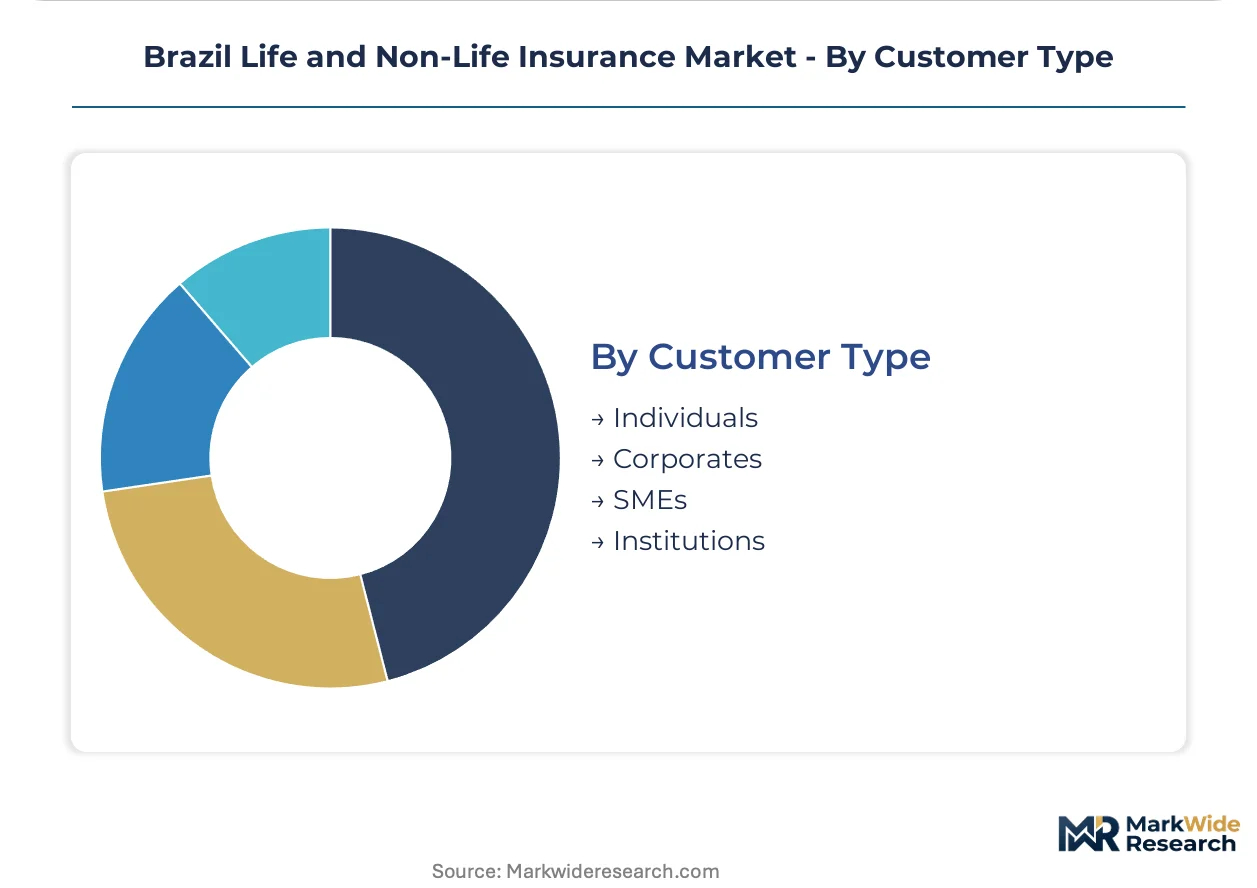
Customer Type:
Volume concentration reflects Brazil's formal-informal labor market divide, with payroll-linked group coverage subsidizing retail distribution economics.
- Individuals:Retail purchasers of personal life, health, and property protections. Northeast regional underpenetration in Ceará and Pernambuco creates whitespace for simplified products distributed through retail correspondent banking.
- Corporates:Large employers structuring group health and executive benefit programs. Cafeteria-style unbundling into modular coverage tiers is fragmenting traditional one-size-fits-all policies.
- SMEs:Small and medium enterprises with constrained risk management staff seeking packaged coverage. Digital platforms are integrating microinsurance at transaction touchpoints, converting payment behavior into protection sales.
- Institutions:Pension funds, foundations, and religious organizations with long-duration liability matching requirements. MAPFRE VIDA competes via international reinsurance backing that extends capital capacity.
Corporates dominate premium volume. SMEs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SUSEP's regulatory framework anchors insurance activity in São Paulo's metropolitan corridor, where bancassurance networks concentrate premium flow and PIX instant-payment infrastructure reshapes settlement velocity across the federation.
São Paulo
Formal sector employees in São Paulo's financial district drive term life and group health expansion as employer-sponsored benefits intensify talent competition. SUSEP's product filing requirements create compliance bottlenecks for new entrants seeking access to this premium pool. Bradesco Seguros leverages its captive banking presence to embed protection products at transaction touchpoints across the metropolitan region.
Rio de Janeiro
Corporate benefits administrators in Rio de Janeiro are unbundling traditional group health into modular cafeteria-style tiers for technology and financial services employers. ANS benefit-package minimums constrain pricing flexibility for carriers writing in this corridor. SulAmérica anchors relationships through specialized health underwriting expertise targeting executive retention packages.
Minas Gerais
SMEs in Belo Horizonte's industrial belt seek packaged coverage solutions as digital platforms integrate microinsurance at payment touchpoints. The Central Bank's PIX infrastructure standards enable real-time premium collection without legacy batch constraints. Caixa Seguridade distributes through correspondent banking networks penetrating underbanked segments.
Mato Grosso
Soybean and corn operators are expanding parametric crop coverage as climate volatility intensifies agricultural risk transfer demand. SUSEP's technical reserve requirements shape capital deployment for specialized underwriters entering Brazil's interior. MAPFRE VIDA competes via international reinsurance backing that extends capacity for long-duration rural liabilities.
Bahia
Northeast regional underpenetration creates whitespace for simplified term-life products distributed through retail correspondent banking in Salvador and surrounding municipalities. ANS tariff adjustment limits compress margin recovery for health insurers operating in lower-income segments. Porto Seguro tests digital-native distribution architectures to bypass traditional agent networks.
Brazil Life and Non-Life Insurance Market Competitive Landscape
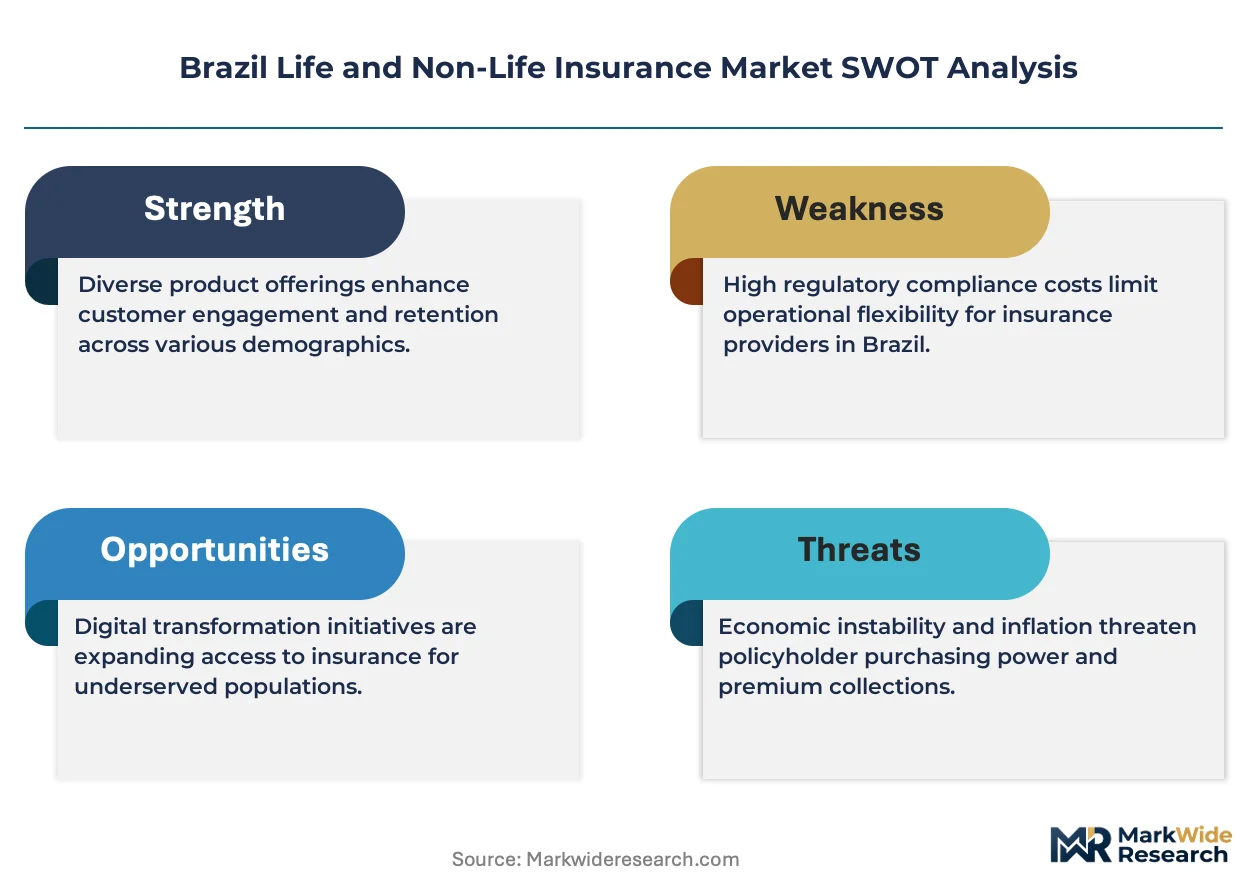
Technology leadership and cost leadership are held by different player archetypes across Brazil's insurance sector. The market structures around tiered competitive positions where banking-captive distributors, specialized health underwriters, and international reinsurance-backed carriers occupy distinct strategic territories. Three archetypes dominate: embedded distributors leveraging captive financial networks, specialists concentrating on ANS-regulated health segments, and capital-heavy life writers accessing global reinsurance capacity. M&A activity concentrates on digital platform acquisitions, while portfolio diversification moves target corporate wellness convergence and agribusiness parametric products.
Within the banking-captive tier, Bradesco Seguros and Itaú Seguros exemplify embedded distribution models converting payment relationships into protection sales without dedicated agent infrastructure. SulAmérica occupies a specialist position anchored in health underwriting expertise. MAPFRE VIDA represents the international reinsurance-backed archetype extending capital capacity for long-duration life liabilities through global risk-pooling relationships. These three patterns illustrate how competitive positioning fragments across distribution economics, regulatory specialization, and capital access vectors rather than consolidating around unified scale advantages.
| Leading Market Players |
|---|
| BrasilSeg |
| Bradesco Seguros |
| SulAmérica |
| Porto Seguro |
| Caixa Seguridade |
| MAPFRE VIDA |
| Tókio Marine Seguradora |
| Itaú Seguros |
| Allianz Seguros |
| Others |
Pricing and Supply Chain Analysis
SUSEP solvency capital requirements gate both insurer qualification and product pricing tiers simultaneously, forcing carriers to lock technical reserves in low-yielding government bonds while passing opportunity costs through premium structures. This regulatory architecture compresses investment income during Brazil's rate normalization, squeezing margins across term-life and health segments where reserve intensity runs highest.
Pricing Analysis
São Paulo's metropolitan corridor commands premium pricing 15-20% above Northeast regional levels, reflecting bancassurance network density and formal-sector payroll linkage. Three-tier pricing structure across premium, standard, and economy levels stratifies by distribution channel sophistication and policyholder data richness. Cost compression in standard-tier motor coverage is intensifying because telematics-enabled competitors displace traditional risk-pooling with usage-based models. SMEs exhibit highest price sensitivity, while corporate group health purchasers trade premium levels against network breadth and deductible structures.
Supply Chain Analysis
Brazil and the United States anchor reinsurance capacity and actuarial talent production respectively, with London and Bermuda markets extending catastrophe and longevity risk absorption. Domestic carriers draw from international reinsurance relationships, domestic banking distribution networks, and PIX instant-payment infrastructure as core inputs. Single-source vulnerability concentrates in global reinsurer appetite for Brazilian longevity risk, which fluctuates with international capital market conditions. Distribution runs through captive bancassurance channels, independent broker networks, and emerging API-native digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's insurance sector faces substitution pressure from embedded fintech protection products that convert payment behavior into coverage without traditional agent infrastructure. Incumbents must defend against disintermediation while rebuilding core systems around real-time settlement rails.
For Market Incumbents: Compound defensive positioning through backward integration into PIX-native technology stacks and captive distribution control via banking network deepening. Reinsurance relationship diversification mitigates capacity squeeze risks from international market volatility. Reserve de-risking into inflation-linked government bonds addresses SUSEP solvency pressure.
For New Entrants and Emerging Players: Anchor in Northeast regional underpenetration across Ceará and Pernambuco, where simplified term-life products distributed through retail correspondent banking face minimal incumbent saturation. SME microinsurance at digital transaction touchpoints offers fastest share accumulation velocity. API-first architectures bypass legacy COBOL system constraints that slow established carrier product iteration.
For Investors and Strategic Acquirers: SUSEP convergence with international solvency standards reshapes the acquisition landscape by tightening capital adequacy disclosure requirements and favoring carriers with granular asset-liability matching capabilities. Long-term viability centers on technology-enabled distribution economics and health underwriting specialization. Monitor PIX adoption penetration rates as inflection indicator for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| PIX-Native Core System Migration | Real-time premium collection and claims disbursement reduces policyholder friction in São Paulo's bancassurance corridors. |
| Parametric Crop Coverage Expansion | Mato Grosso soybean operators pull specialized underwriters into Brazil's interior as climate volatility intensifies. |
| Corporate Wellness Module Integration | ANS-regulated group health policies absorb preventive care and mental health into subscription-like service bundles. |
| Telematics-Linked Motor Pricing | Smartphone-enabled driving behavior scoring displaces traditional risk-pooling in congested urban corridors. |
| International Reinsurance Capacity Diversification | Global risk-pooling relationships extend capital deployment flexibility for long-duration life liabilities. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with SUSEP regulatory affairs officers, chief actuaries at major carriers, corporate benefits administrators, and digital distribution platform architects; and secondary validation through SUSEP regulatory filings, ANS benefit-package databases, Central Bank PIX infrastructure disclosures, and reinsurance market capacity reports. Bottom-up policy-level data triangulated against top-down macroeconomic and demographic projections.
Across the analysis window, forecasts segment by product type, coverage category, distribution channel, and customer archetype, with additional dimensioning by regional regulatory cluster and reserve intensity tier. CAGRs derive from premium volume trajectory modeling against population coverage penetration curves and formal-sector employment expansion patterns. Forecast inputs incorporate PIX adoption velocity, agribusiness climate risk transfer demand, and corporate wellness convergence trends.
Decision-makers should treat outputs as directional under sustained SUSEP regulatory framework stability and PIX infrastructure scaling assumptions; material deviation in international reinsurance capacity or domestic rate normalization trajectories would warrant model refresh. Recalibration cycles align with material shifts in regulatory convergence timelines and embedded distribution penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Children Life Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
Asia Pacific Life & Non-Life Insurance Market
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market
Life and Non Life Insurance
Australia Life and Non-Life Insurance Market
Life and Non Life Insurance
Iran Property and Casualty Insurance Market
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
Singapore Life and Non-Life Insurance Market
Life and Non Life Insurance
France Life and Non-Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market
Life and Non Life Insurance
Argentina Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia Life and Non-Life Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market