
 Sweden Life and Non-Life Insurance Market | 2026-2036
Sweden Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Life and Non-Life Insurance Market Analytics
Actuarial talent scarcity is collapsing underwriting capacity across specialized life segments. Länsförsäkringar leverages its mutual structure to sustain pricing power in property lines. Trygg-Hansa anchors marine and commercial portfolios through Nordic broker networks.
Sweden Life and Non-Life Insurance encompasses risk transfer contracts covering mortality, morbidity, property damage, and liability exposures, with technical reserves calculated via stochastic mortality tables and discount rate curves prescribed by Finansinspektionen. Life Insurance dominates premium volume through occupational pension schemes tied to Sweden's collective bargaining framework. Online Platforms represent the fastest-growing distribution vector as IFD-compliant robo-advisory tools reduce acquisition costs for term products. Property Insurance maintains stable margins despite climate-exposed northern geographies.
Finansinspektionen enforces Solvency II capital requirements while the Swedish Consumer Agency monitors policy transparency under EU Insurance Distribution Directive standards. GDPR constraints limit cross-selling of health data between life and non-life entities. Stakeholders must monitor EU Green Deal alignment in property underwriting as flood and wildfire risk models recalibrate Nordic exposure assumptions.
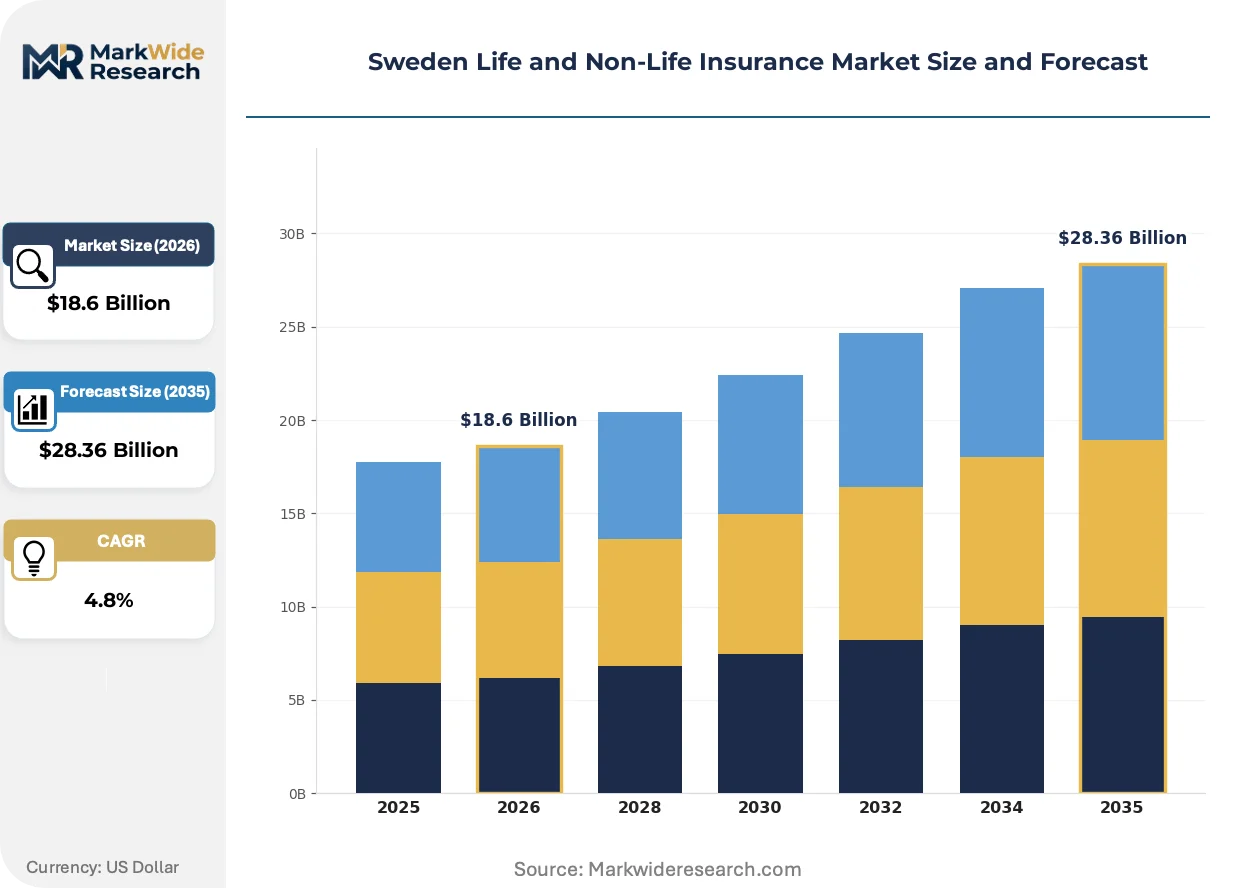
Market Dynamics
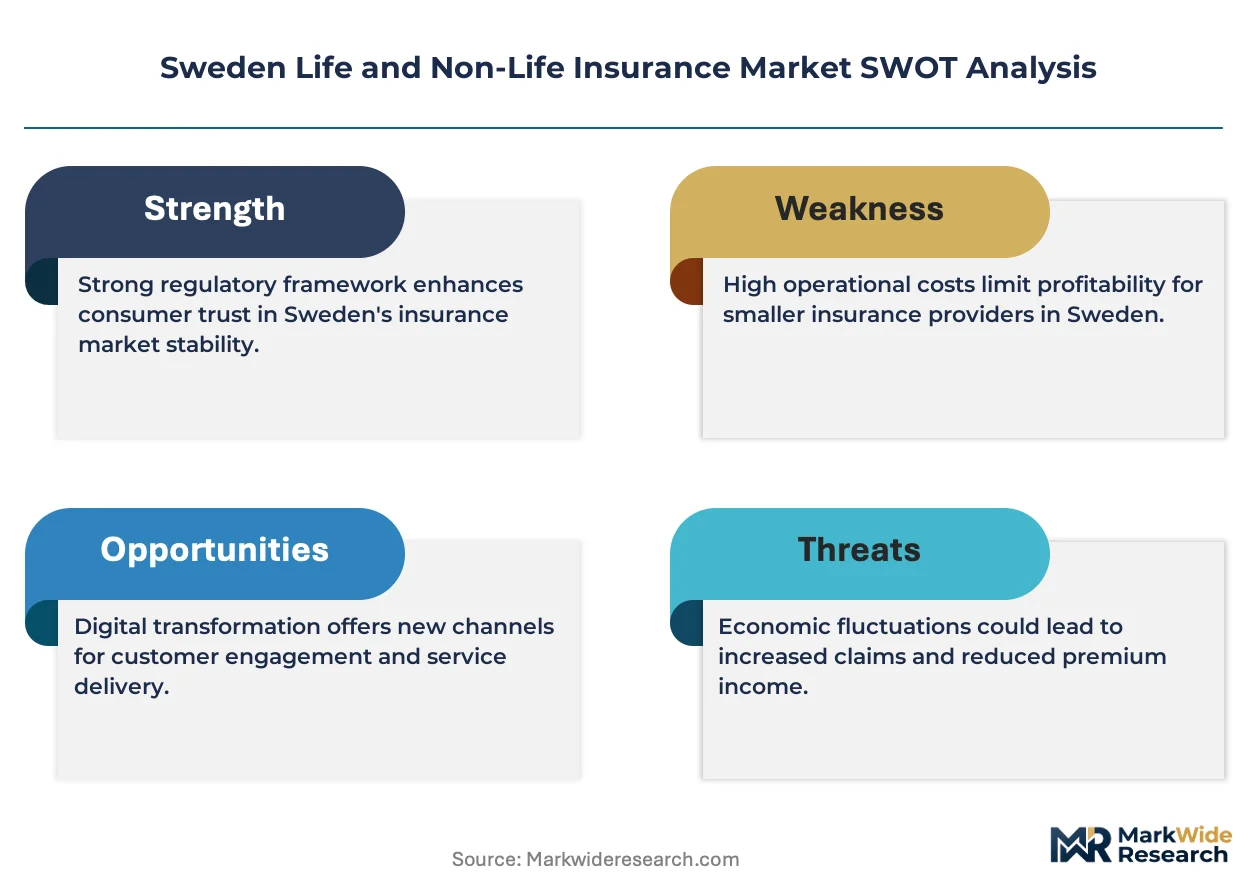
Finansinspektionen's Solvency II implementation is compressing capital buffers across Swedish insurers, forcing selective portfolio pruning while digital distribution platforms capture premium flow from traditional broker networks.
Growth Catalysts
- IFD-Compliant Robo-Advisory:Automated underwriting engines reduce term life acquisition costs while expanding reach into underpenetrated younger demographics through mobile-first interfaces.
- Sweden's Collective Bargaining Framework:Mandatory occupational pension contributions sustain institutional premium volumes regardless of individual discretionary purchase cycles.
- Nordic Corporate Pension Clustering:Stockholm's concentration of multinational headquarters generates concentrated demand for cross-border group life and disability coverage.
Market Restraints
- Actuarial Talent Scarcity:Specialized mortality modeling expertise concentrates among retiring practitioners, collapsing underwriting capacity in longevity-linked products.
- GDPR Health Data Friction:Cross-selling constraints between life and non-life entities under EU data protection rules fragment customer intelligence and inflate acquisition costs.
- Climate Exposure Recalibration:Northern flood and wildfire risk models are forcing reserve strengthening in property lines without corresponding premium elasticity.
Strategic Opportunities
- EU Green Deal Alignment:Sustainable property underwriting standards create first-mover positioning for insurers embedding carbon transition risk into commercial coverage.
- Digital Broker Platform Expansion:Aggregator models capturing household policy consolidation represent uncaptured premium flow outside traditional tied-agent channels.
- Parametric Climate Products:Index-based triggers for agricultural and commercial property exposure address coverage gaps where conventional indemnity structures fail.
Industry Challenges
- Legacy Core System Migration:Policy administration platforms from the 1990s resist real-time data integration with cloud-native distribution layers.
- Stochastic Reserve Volatility:Finansinspektionen's prescribed discount rate curves amplify balance sheet sensitivity to macro rate shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Life and Non-Life Insurance Market |
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $28.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Life Insurance, Property Insurance, Liability Insurance, Health Insurance Distribution Channel: Direct Sales, Brokers, Agents, Online Platforms Customer Type: Individuals, Corporates, SMEs, Government Policy Type: Term Life, Whole Life, Endowment, Universal Life |
| Companies Covered | Trygg-Hansa, Alecta, Länsförsäkringar, SEB Pension & Försäkring, SPP, Folksam, Skandia, ICA Försäkring, If Skadeforsäkring, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Life and Non-Life Insurance Market Evolving Landscape
Swedish insurance distribution is fragmenting across embedded finance partnerships and API-driven policy origination, compressing traditional broker economics while elevating data-centric underwriting capabilities.
Telematics-enabled motor and property coverage is miniaturizing risk assessment from annual policy cycles to real-time behavioral pricing. Commercial fleet operators in Gothenburg's logistics corridor are piloting usage-based contracts with granular mileage and driving-pattern inputs. This granularity is miniaturizing the traditional pooled-risk model into individualized exposure units that compress cross-subsidy between risk tiers.
Finansinspektionen's alignment with EU Insurance Distribution Directive transparency mandates is forcing commission disclosure reforms across tied-agent networks. The Swedish Consumer Agency's enforcement of standardized product information documents is elevating direct-to-consumer digital channels. Term life and simple property products are migrating fastest toward self-service platforms where comparison friction is lowest.
Household policy consolidation through digital aggregators is displacing single-line loyalty patterns that sustained traditional mutual structures. Younger demographics in Stockholm and Malmö metropolitan zones are bundling home, motor, and pet coverage through platform interfaces rather than branch relationships. This concentration of purchase authority is shifting commission economics toward volume-based platform fees and away from per-policy tied-agent compensation.
Sweden Life and Non-Life Insurance Market Segmentation
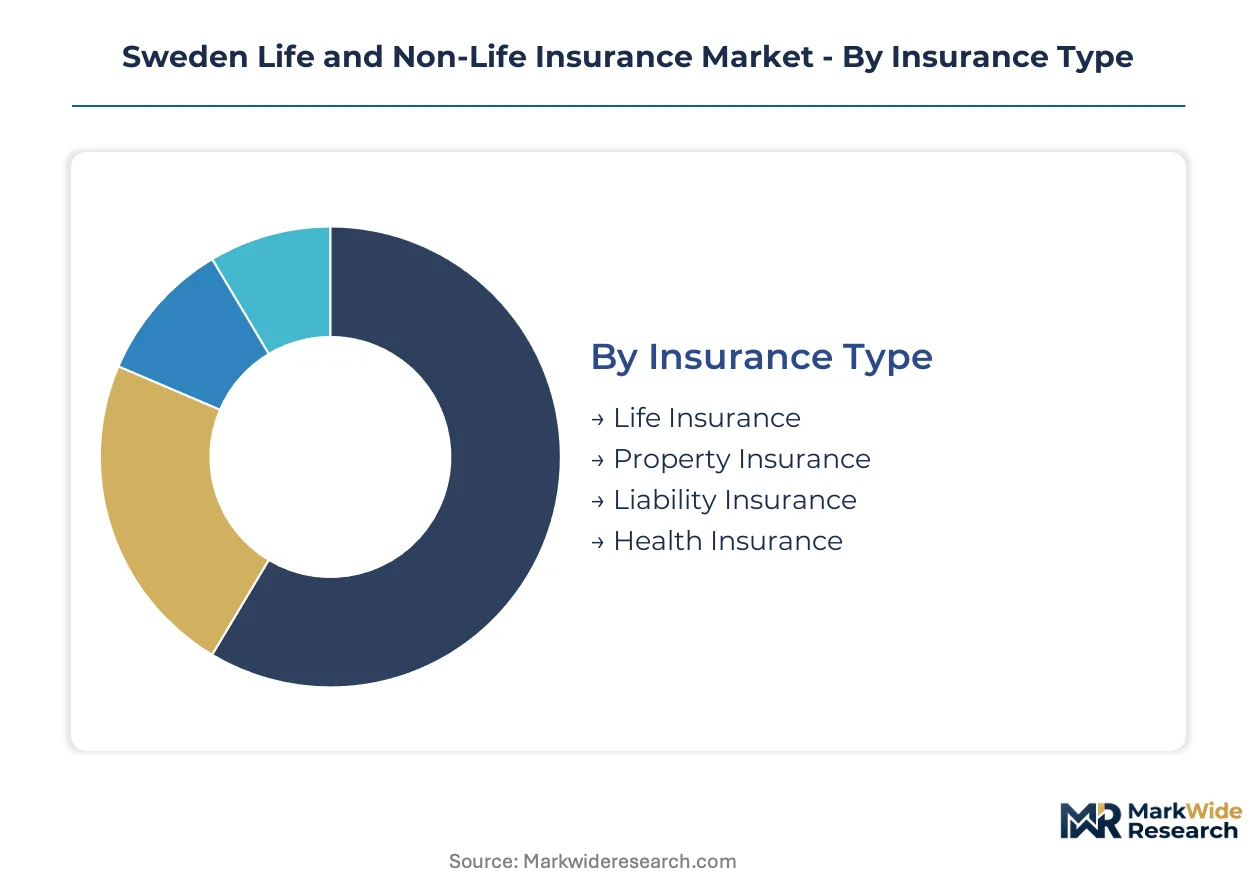
Swedish insurance segmentation reveals divergent growth mechanics across life and non-life pools. Finansinspektionen's capital rules compress margins differently by product complexity, while distribution channel fragmentation creates tiered access economics.
Insurance Type:
Domestic demand concentrates in Stockholm's corporate pension cluster and Gothenburg's industrial property corridors. Export-linked marine and commercial liability lines serve Nordic cross-border operations.
- Life Insurance:Occupational pension schemes dominate premium volume through Sweden's collective bargaining framework. Stockholm's multinational headquarters generate concentrated demand for cross-border group life and disability coverage.
- Property Insurance:Climate-exposed northern geographies force reserve strengthening without corresponding premium elasticity. Commercial portfolios in Gothenburg's logistics corridor anchor stable underwriting margins despite weather volatility.
- Liability Insurance:Professional and product liability coverage expands through SME commercialization in Malmö metropolitan zones.
- Health Insurance:Supplementary coverage fills gaps in Sweden's public healthcare system, with demand clustering among high-income urban households.
Life Insurance commands the established base. The steepest expansion runs through Property Insurance.
Distribution Channel:
Cost tier differentiation separates legacy tied-agent networks from digital acquisition engines. Commission disclosure mandates under EU Insurance Distribution Directive accelerate channel migration.
- Online Platforms:IFD-compliant robo-advisory tools reduce term life acquisition costs while expanding reach into underpenetrated younger demographics through mobile-first interfaces. Stockholm and Malmö metropolitan zones show fastest platform adoption.
- Brokers:Nordic networks anchor marine and commercial portfolios through relationship-based placement. Trygg-Hansa leverages this channel for complex commercial risks requiring tailored structuring.
- Direct Sales:Self-service platforms capture simple term life and property products where comparison friction is lowest.
- Agents:Tied-agent networks face commission compression as standardized product information documents elevate price transparency.
Brokers retain the commercial core. Online Platforms are climbing the fastest.
Customer Type:
Volume concentration splits between institutional occupational schemes and fragmented household acquisition. Government procurement creates stable but low-margin annuity flows.
- Corporates:Mandatory occupational pension contributions sustain institutional premium volumes regardless of individual discretionary purchase cycles. Stockholm's concentration of multinational headquarters drives cross-border group coverage demand.
- Individuals:Household policy consolidation through digital aggregators displaces single-line loyalty patterns. Younger demographics bundle home, motor, and pet coverage through platform interfaces.
- SMEs:Commercial liability and property coverage expands through Malmö and Gothenburg entrepreneurial corridors.
- Government:Public sector risk pools generate stable annuity flows with standardized procurement terms.
Corporates anchor premium volume. Individuals are gaining share fastest.
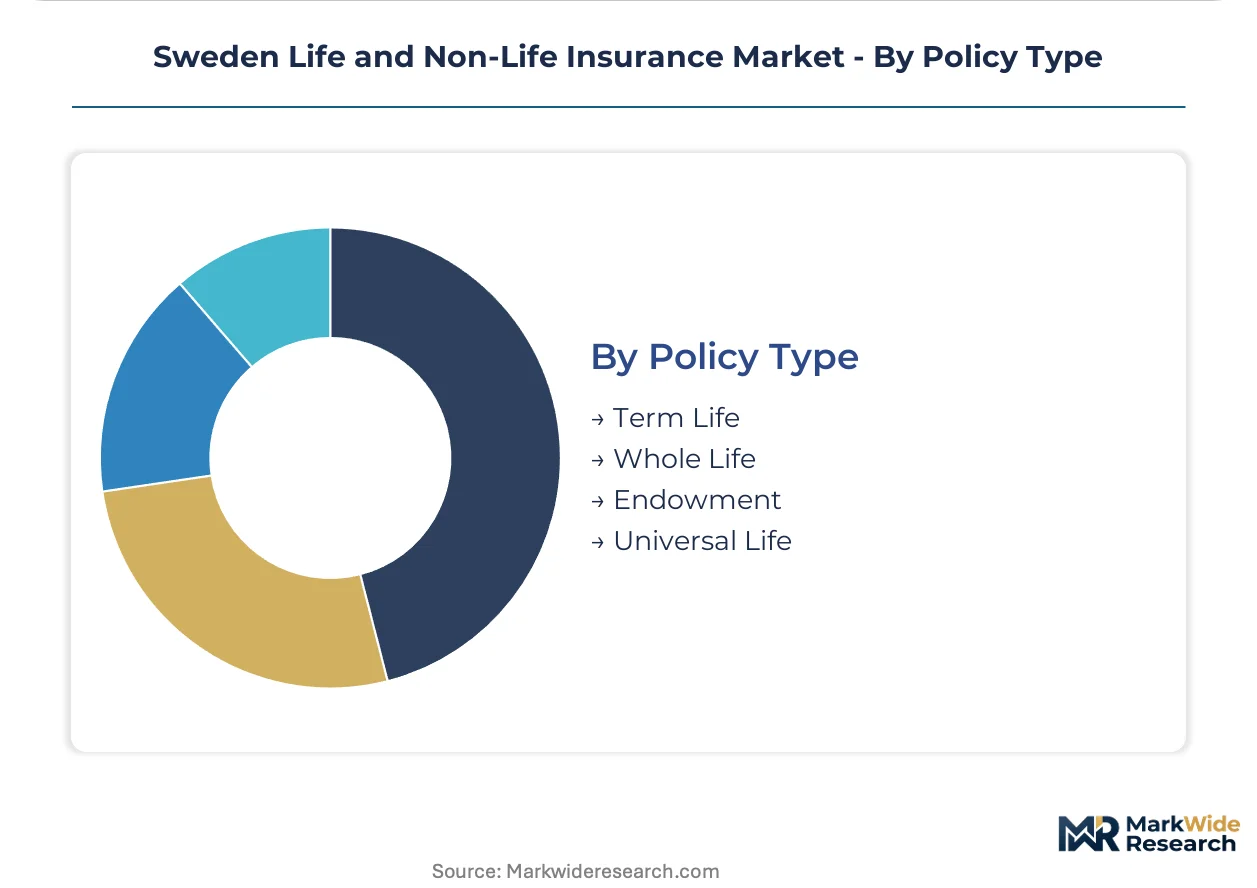
Policy Type:
Maturity differentiation separates simple term products from complex savings-linked contracts. Technical reserve calculations vary sharply across duration and guarantee structures.
- Term Life:Pure risk coverage with no savings component migrates fastest toward self-service digital channels. Finansinspektionen's prescribed discount rate curves amplify balance sheet sensitivity for short-duration products.
- Whole Life:Guaranteed lifetime coverage with cash value accumulation requires specialized actuarial capacity concentrated among retiring practitioners.
- Endowment:Savings-linked contracts with maturity benefits face distribution friction under EU transparency mandates.
- Universal Life:Flexible premium and death benefit structures demand real-time policy administration that legacy core systems struggle to support.
Term Life dominates new business flow. Universal Life shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finansinspektionen anchors capital adequacy requirements across Sweden's insurance sector, with occupational pension schemes and corporate risk pools driving geographic concentration toward metropolitan economic corridors.
Stockholm
Multinational headquarters cluster in Stockholm's corporate pension hub, generating concentrated demand for cross-border group life and disability coverage. Finansinspektionen's Solvency II implementation shapes reserve calculations for institutional schemes. The Stockholm metropolitan zone anchors Sweden's highest density of occupational pension administration.
Gothenburg
Commercial fleet operators and logistics corridors drive property and motor coverage expansion through telematics-enabled contracts. EU Insurance Distribution Directive transparency mandates accelerate digital platform adoption. Gothenburg's industrial zones sustain stable underwriting margins in commercial portfolios despite climate volatility.
Malmö
SME commercialization in Malmö's entrepreneurial corridors expands professional and product liability coverage demand. GDPR constraints fragment customer intelligence between life and non-life entities. The Malmö metropolitan zone shows fastest adoption of household policy consolidation through digital aggregators.
Norrland
Climate-exposed northern geographies force reserve strengthening in property lines without corresponding premium elasticity. Flood and wildfire risk models recalibrate exposure assumptions under EU Green Deal alignment pressures. Agricultural and commercial property in Norrland's rural zones pilot parametric index-based coverage.
Sweden Life and Non-Life Insurance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Sweden's insurance sector. Mutual structures and stock-owned entities coexist in a tiered market where capital efficiency separates sustainable pricing power from compressed margins. Three archetypes dominate: mutual insurers leveraging member-owned governance, bank-affiliated pension administrators with distribution integration, and digital-native platforms capturing younger demographics through mobile-first acquisition. Competitive moves concentrate on digital broker platform expansion and legacy core system modernization.
Among mutual specialists, Länsförsäkringar and Folksam exemplify member-owned governance structures that sustain pricing power in property lines through localized risk pooling. Trygg-Hansa anchors marine and commercial portfolios through Nordic broker networks, occupying a position that relationship-based placement sustains. Skandia represents the bank-affiliated archetype with integrated pension administration capabilities.
| Leading Market Players |
|---|
| Trygg-Hansa |
| Alecta |
| Länsförsäkringar |
| SEB Pension & Försäkring |
| SPP |
| Folksam |
| Skandia |
| ICA Försäkring |
| If Skadeforsäkring |
| Others |
Value Network & Pricing Analysis
Scale economies in actuarial modeling capacity concentrate pricing power among mutual insurers with localized risk pooling, compressing margins for stock-owned competitors while elevating price floors in property lines where climate-exposed geographies demand reserve strengthening. This concentration reshapes supply chain choices as insurers prioritize in-house mortality table development over third-party vendor licensing to defend technical reserve accuracy.
Pricing Analysis
Geographic price spreads between Stockholm's corporate pension hub and Norrland's rural property markets reflect divergent risk-cost structures, with northern climate exposure forcing premium elevation without corresponding demand elasticity. Three-tier pricing structure across premium, standard, and economy levels separates occupational scheme administrators from direct-to-consumer platforms and mutual property specialists. Cost compression in term life products stems from IFD-compliant robo-advisory distribution, while SMEs in Malmö's entrepreneurial corridors show highest price sensitivity due to fragmented broker access.
Supply Chain Analysis
Sweden and Denmark anchor Nordic actuarial talent pools and mortality data infrastructure, with Finland and Norway contributing supplementary risk modeling capabilities for cross-border group coverage. Technical reserve calculations draw from stochastic mortality tables, Finansinspektionen-prescribed discount rate curves, and climate risk datasets for northern flood and wildfire exposure. Single-source vulnerability concentrates in retiring actuarial practitioners specialized in longevity-linked products. Distribution runs through digital broker platforms capturing household policy consolidation outside traditional tied-agent networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's insurance market rewards service-attach strategies as policy administration and claims management layers expand faster than premium growth, with recurring fee structures from digital platform integration outpacing transactional underwriting margins.
For Market Incumbents: Compound data-centric underwriting capabilities through cloud-native policy administration investments that bypass legacy core system constraints. Deepen vertical integration into parametric climate product development to capture agricultural and commercial property exposure gaps in Norrland. Defend against digital-native platform entrants by embedding robo-advisory tools within existing occupational pension administration relationships. For New Entrants and Emerging Players: Differentiate on API-driven policy origination that embeds insurance within non-financial customer journeys such as property rental platforms and mobility services. Target underpenetrated younger demographics in Malmö and Stockholm metropolitan zones through mobile-first term life acquisition. Pursue white-label distribution partnerships with digital aggregators consolidating household coverage bundles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mutual insurers with embedded member governance structures that sustain pricing power through localized risk pooling. Long-term viability favors acquisition targets with modernized core systems capable of real-time data integration. Watch Finansinspektionen Solvency II implementation intensity as the inflection indicator for capital adequacy pressure and forced portfolio pruning.| Strategic Initiative | Industry Significance |
|---|---|
| Legacy Core System Modernization | Cloud-native policy administration enables real-time integration with IFD-compliant distribution layers. |
| Parametric Climate Product Development | Index-based triggers address coverage gaps where conventional indemnity structures fail in Norrland. |
| Digital Broker Platform Expansion | Aggregator models capture household policy consolidation outside traditional tied-agent commission structures. |
| Actuarial Talent Acquisition | Specialized mortality modeling expertise anchors underwriting capacity in longevity-linked products. |
| EU Green Deal Alignment Investment | Sustainable underwriting standards embed carbon transition risk into commercial property coverage. |
Research Methodology
The analysis maps life insurance, non-life insurance, and distribution channel sub-sectors, each validated through chief underwriting officers, digital platform product managers, Finansinspektionen regulatory affairs leads, and mutual insurer actuarial directors. Primary interview findings triangulate against Finansinspektionen solvency disclosures, Swedish Consumer Agency enforcement records, EU Insurance Distribution Directive implementation reports, and occupational pension scheme administrative data. Bottom-up premium flow modeling and top-down macroeconomic scenario testing ensure cross-validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions include insurance type, distribution channel, customer archetype, and policy maturity structure, with CAGRs derived from stochastic modeling of mortality improvement trends and climate exposure recalibration. Forecast inputs incorporate Finansinspektionen discount rate curve sensitivity and digital platform adoption elasticity in metropolitan zones.
Material uncertainties — Finansinspektionen regulatory recalibration, actuarial talent availability shocks, and climate model revision cycles — sit outside the modeled envelope. Forecasts reflect assumptions about Solvency II implementation stability and GDPR cross-selling constraint persistence. Recalibration cycles align with material shifts in EU Green Deal alignment mandates and Nordic broker network restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
South Korea Life & Non-Life Insurance Market
Life and Non Life Insurance
Argentina Life and Non-Life Insurance Market
Life and Non Life Insurance
Colombia Life and Non-Life Insurance Market
Life and Non Life Insurance
Finland Life and Non-Life Insurance Market
Life and Non Life Insurance
Brazil Life and Non-Life Insurance Market
Life and Non Life Insurance
Denmark Life and Non-Life Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
UAE Life and Annuity Insurance Market
Life and Non Life Insurance
Australia Life and Non-Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
USA Life and Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
Group Life Insurance Market