
 Denmark Life and Non-Life Insurance Market | 2026-2036
Denmark Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Life and Non-Life Insurance Market Outlook
Agent networks is narrowing as digital direct channels capture premium flow from traditional intermediaries. Tryg leverages its proprietary digital platform to control customer acquisition costs. Danica Pension anchors group pension contracts through employer-sponsored distribution. Gjensidige competes on commercial lines specialization for Nordic mid-market firms.
Denmark Life and Non-Life Insurance encompasses risk-pooling contracts where insurers collect premiums to fund future claims, regulated under Solvency II capital adequacy ratios requiring matched assets against technical provisions. The primary purpose spans income replacement for beneficiaries, health cost indemnification, asset protection against property damage, and liability coverage for legal exposures. Life Insurance and Health Insurance carry the deepest premium pools due to Denmark's aging demographic structure and mandatory occupational pension architecture. Online Platforms represent the fastest-growing distribution vector as policyholders migrate from broker-mediated placement to algorithmic quoting engines. Property Insurance retains mature, cyclical characteristics tied to construction activity and climate loss patterns.
Finanstilsynet enforces Solvency II compliance and consumer protection standards, while EU-wide EIOPA guidelines harmonize cross-border reserve methodologies. Danish insurers face escalating climate disclosure obligations under evolving CSRD sustainability reporting mandates. Stakeholders must monitor how Finanstilsynet interprets forthcoming EU insurance recovery and resolution directives affecting capital flexibility.
Market Dynamics
Denmark's insurance sector faces structural pressure from Finanstilsynet's escalating climate disclosure mandates under CSRD, forcing insurers to revalue asset portfolios and technical provisions against transition risk scenarios.
Growth Catalysts
- Solvency II Capital Framework:The EU's risk-based capital requirements push Danish insurers toward sophisticated asset-liability matching, deepening demand for actuarial analytics and reinsurance partnerships.
- Occupational Pension Architecture:Mandatory employer-sponsored schemes sustain premium inflows into life and health segments as Denmark's workforce ages and contribution rates adjust.
- Copenhagen Corporate Cluster:Concentrated mid-market and large enterprise headquarters in the capital region generate commercial lines demand spanning property, liability, and directors-and-officers coverage.
Market Restraints
- Low Interest Rate Environment:Sustained monetary policy compression erodes investment yields on guaranteed life products, squeezing spread-based profitability across Danish life insurers' traditional portfolios.
- Climate Loss Volatility:Intensifying storm and flood frequency in Jutland and Zealand coastal zones drives property claims unpredictability, forcing reinsurance cost escalation.
- Digital Intermediary Displacement:Algorithmic quoting engines and direct-to-consumer platforms strip commission revenue from traditional agent networks, compressing distribution economics.
Strategic Opportunities
- Embedded Insurance Integration:Partnerships with Danish fintech platforms and neobanks enable point-of-sale policy attachment for travel, gadget, and subscription-based coverage.
- Parametric Climate Products:Index-triggered structures bypass claims adjustment friction for agricultural and renewable energy exposures in Denmark's coastal wind farm zones.
- Pension Decumulation Services:Shifting demographics create advisory demand as baby-boom cohorts transition from accumulation to drawdown phases, requiring income guarantee products.
Industry Challenges
- Actuarial Talent Scarcity:Competition for quantitative risk professionals intensifies as insurers, consultancies, and fintechs vie for expertise in stochastic modeling and climate scenario analysis.
- Legacy System Modernization:Core policy administration platforms built on decades-old architectures impede real-time data integration for personalized pricing and automated underwriting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Life and Non-Life Insurance Market |
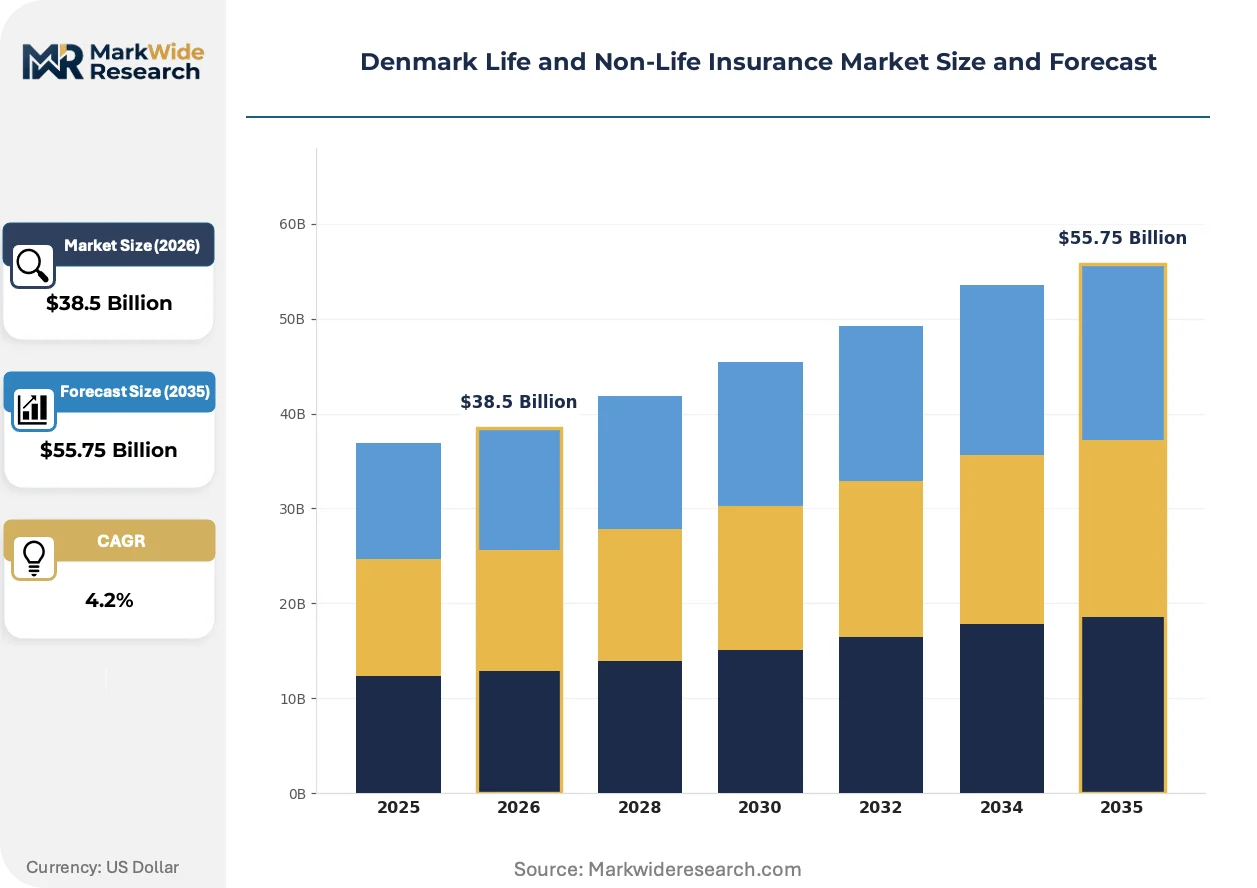
| Market Size in 2026 | $38.5 Billion |
| Market Size in 2035 | $55.75 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Life Insurance, Health Insurance, Property Insurance, Liability Insurance Customer Segment: Individuals, Corporates, SMEs, Non-Profit Organizations Distribution Channel: Direct Sales, Brokers, Agents, Online Platforms Policy Type: Term Life, Whole Life, Universal Life, Critical Illness |
| Companies Covered | Alm. Brand, Gjensidige, Tryg, Danica Pension, If P&C Insurance, PFA Pension, Codan, ATP, Topdanmark, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Life and Non-Life Insurance Market Strategic Shifts
Danish insurers confront simultaneous pressure from regulatory climate mandates and distribution channel fragmentation, forcing technology investment priorities toward automation and sustainability-linked product design.
Artificial intelligence-powered claims assessment is rendering obsolete manual damage evaluation workflows for motor and property lines. Tryg and regional competitors deploy computer vision algorithms to estimate repair costs from smartphone imagery, compressing settlement cycles from weeks to hours. This automation is rendering obsolete traditional loss adjuster field deployment for standard claims categories.
CSRD sustainability reporting mandates from Finanstilsynet require insurers to disclose Scope 3 financed emissions and climate risk exposure across underwriting portfolios. Danish life insurers must reclassify carbon-intensive holdings and model transition pathways for technical provision adequacy. Commercial property underwriters face heightened scrutiny on coastal flood zone exposure concentration.
Policyholders in Zealand and Jutland municipalities increasingly bypass broker-mediated placement for algorithmic comparison platforms. Digital-native consumers expect instant quote generation and policy binding without intermediary consultation. Copenhagen's corporate risk managers similarly demand direct API connectivity for fleet and property program administration.
Denmark Life and Non-Life Insurance Market Segmentation
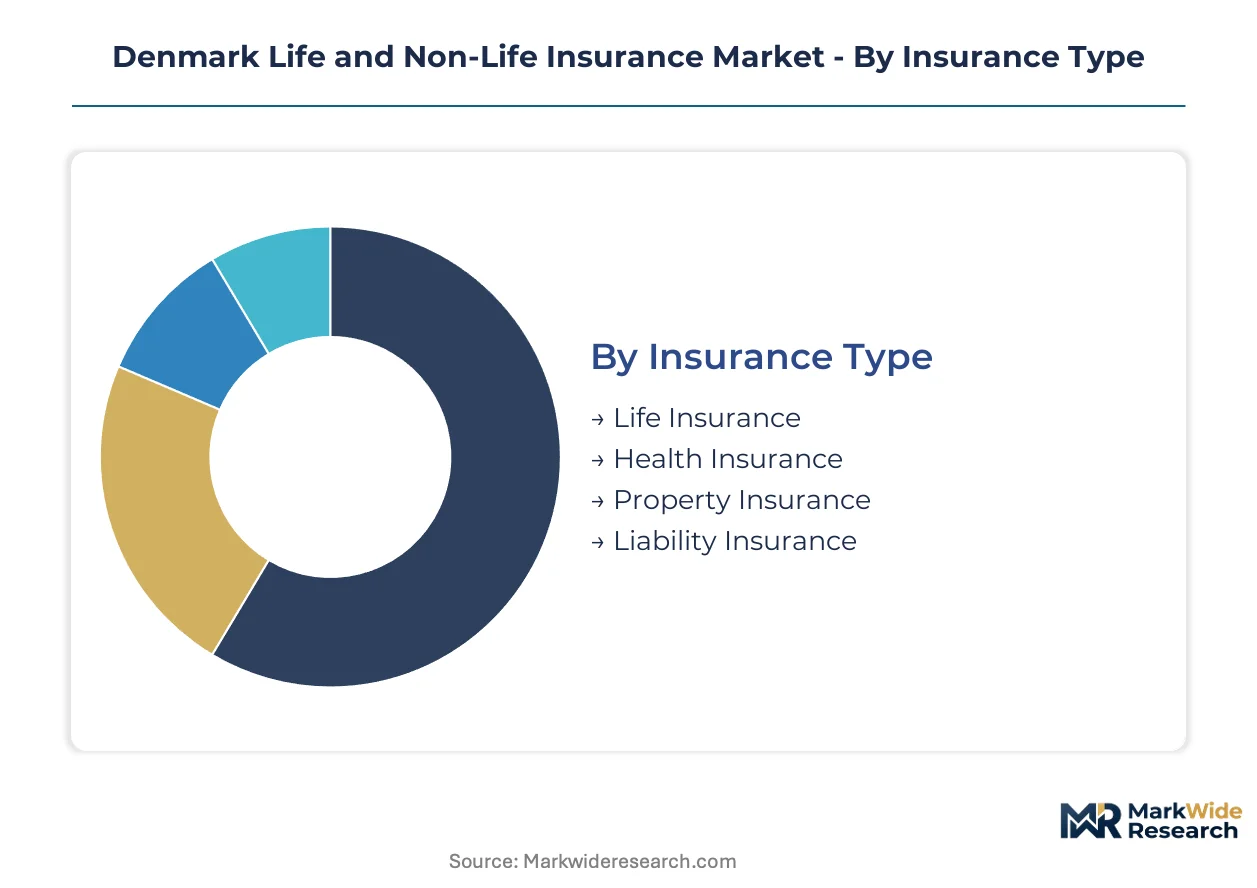
Segmentation in Denmark's insurance market reveals divergent service intensity requirements across life and non-life lines. Life and pension products demand sustained advisory relationships through decumulation phases, while property and liability coverage prioritize rapid claims response. Distribution economics vary sharply by channel, with digital platforms compressing servicing costs for standardized risks.
Insurance Type:
After-sales service intensity varies dramatically across insurance lines, with life products requiring decades-long policy administration and non-life lines demanding event-driven claims responsiveness.
- Life Insurance:Long-duration contracts with guaranteed benefit obligations require ongoing policy servicing, premium collection, and beneficiary administration across multi-decade horizons. Copenhagen's corporate pension clusters generate concentrated demand for group life arrangements tied to occupational schemes.
- Health Insurance:Supplementary medical coverage fills gaps in Denmark's universal healthcare system, with claims processing focused on elective procedures and specialized treatments. Zealand's aging municipalities drive demand for extended care and hospitalization benefits.
- Property Insurance:Cyclical exposure to Jutland storm damage and Zealand flood zones necessitates rapid loss adjustment and reinsurance coordination.
- Liability Insurance:Professional and directors-and-officers coverage serves Copenhagen's dense corporate headquarters concentration with claims-made policy structures.
By volume, Life Insurance leads. By growth pace, Health Insurance is ahead.
Customer Segment:
Premium scale and servicing economics diverge sharply across customer types, from mass-market individual policies to bespoke corporate risk programs.
- Individuals:Personal lines span term life, home contents, and motor coverage with standardized policy wordings and digital servicing preferences.
- Corporates:Large enterprises in Copenhagen's financial district require complex multi-line programs with captive feasibility studies and international fronting arrangements.
- SMEs:Mid-market firms across Denmark's regional cities drive commercial package policy demand with limited risk management staffing.
- Non-Profit Organizations:Associations and foundations carry specialized fiduciary liability and event cancellation exposures requiring tailored coverage structures.
Corporates command the highest premium per policy. SMEs are expanding most quickly as commercial coverage penetration deepens.
Distribution Channel:
Channel economics reflect divergent customer acquisition costs and persistency rates across intermediary and direct models.
- Direct Sales:Insurer-controlled channels capture savings from eliminated commission loads, particularly effective for simple term life and motor products.
- Brokers:Independent intermediaries dominate commercial lines placement, leveraging market access and coverage design expertise for corporate risk managers.
- Agents:Tied distribution networks retain strength in rural Jutland municipalities where relationship-based selling persists despite digital encroachment.
- Online Platforms:Algorithmic comparison engines and direct-to-consumer portals are gaining share fastest among digitally native demographics in urban Zealand.
Brokers still place the largest premium volume. Online Platforms show the steepest expansion trajectory.
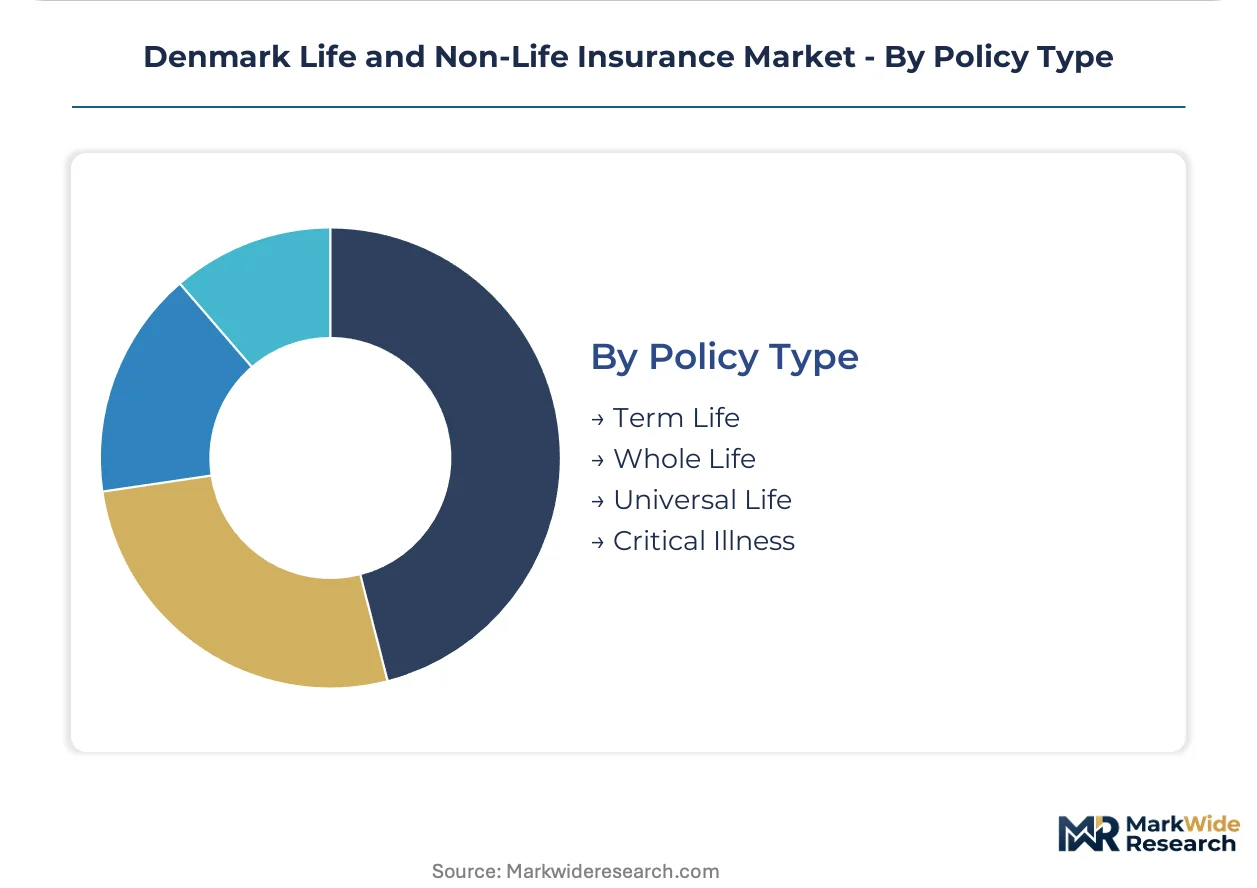
Policy Type:
Product architecture determines capital intensity, with guaranteed products imposing heavier Solvency II reserve requirements than risk-only structures.
- Term Life:Pure risk coverage without savings components carries minimal capital requirements and appeals to price-sensitive younger policyholders.
- Whole Life:Guaranteed death benefits with fixed premiums demand long-duration asset-liability matching against Denmark's low-rate environment.
- Universal Life:Flexible premium and benefit structures allow policyholders to adjust coverage as income profiles shift across career stages.
- Critical Illness:Lump-sum payments upon diagnosis of specified conditions address out-of-pocket medical costs and income interruption.
Term Life dominates policy count. Universal Life is climbing the fastest as flexibility preferences intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finanstilsynet's Solvency II implementation creates differentiated capital requirements across Nordic insurance markets, with Denmark's occupational pension architecture generating distinct demand patterns compared to neighboring jurisdictions.
Germany
BaFin enforces stricter own funds requirements for German life insurers than Danish counterparts, compressing guaranteed product offerings. The EU's Solvency II review drives German carriers toward unit-linked structures. Frankfurt's asset management cluster concentrates cross-border reinsurance placement for Danish property risks.
Sweden
Swedish insurers face parallel Finansinspektionen climate disclosure mandates under CSRD, synchronizing Nordic regulatory pressure. The country's premium pension system competes with Danish occupational schemes for cross-border corporate contracts. Stockholm's fintech corridor enables embedded insurance partnerships reaching Danish digital banking platforms.
United Kingdom
Prudential Regulation Authority capital requirements diverge from Solvency II post-Brexit, creating arbitrage complexity for Danish insurers with UK operations. London's Lloyd's market provides specialist capacity for Danish wind farm and marine construction exposures. UK pension reform timelines influence Danish decumulation product development.
Netherlands
DNB's sustainable finance taxonomy intersects with Danish CSRD implementation, harmonizing ESG reporting burdens across Benelux-Nordic corridors. Amsterdam's insurtech ecosystem supplies algorithmic underwriting tools deployed by Danish direct channels. Dutch pension fund scale enables reinsurance partnerships for Danish longevity risk transfer.
Norway
Finanstilsynet Oslo aligns climate stress testing with Danish regulatory timelines, creating coordinated Nordic supervisory expectations. Norway's sovereign wealth fund investment policies influence Danish insurer asset allocation toward green bonds. Oslo's corporate headquarters generate commercial lines demand serviced by Danish brokers.
Denmark Life and Non-Life Insurance Market Competitive Environment
On the supply side, the industry is consolidating around digital platform capabilities and occupational pension scale, with three archetypes dominating: integrated bancassurance groups, specialized commercial lines underwriters, and algorithmic direct-to-consumer operators. M&A activity concentrates on technology-enabled distribution assets, while portfolio diversification moves target health and pension adjacencies.
Within the integrated pension-provider tier, Danica Pension and PFA Pension exemplify scale-driven occupational scheme dominance, anchoring employer-sponsored distribution networks against direct-channel encroachment. Tryg occupies a position as the algorithmic underwriting archetype, its proprietary platform representing capital-efficient customer acquisition. Gjensidige sits within the Nordic commercial specialization vector, its regional footprint enabling cross-border mid-market service capabilities.
| Leading Market Players |
|---|
| Alm. Brand |
| Gjensidige |
| Tryg |
| Danica Pension |
| If P&C Insurance |
| PFA Pension |
| Codan |
| ATP |
| Topdanmark |
| Others |
Value Chain & Pricing Dynamics
Copenhagen's corporate insurance cluster concentrates underwriting capacity and actuarial talent, granting Danish life and non-life insurers pricing leverage over regional competitors while compressing margins for standardized personal lines distributed through algorithmic channels.
Pricing Analysis
Certification level under Solvency II capital adequacy tiers creates the primary spread between premium and standard pricing bands. Three-tier pricing structure across premium, standard, and economy levels dominates life and pension products, with guaranteed benefit obligations commanding capital-loaded premiums. Price differentiation rests on actuarial sophistication and reinsurance backing quality. Cost compression in personal motor and home contents lines is intensifying because direct-to-consumer platforms strip intermediary commissions. SMEs exhibit highest price sensitivity for commercial package policies, while Copenhagen's corporate risk managers prioritize coverage breadth over premium minimization.
Supply Chain Analysis
Reinsurance capacity concentration between Germany and the United Kingdom dominates Danish insurers' risk transfer dependencies. Primary carriers draw from Lloyd's of London, Munich Re, and Swiss Re for property catastrophe coverage, alongside Nordic regional pools for longevity risk. Single-source vulnerability in climate risk modeling software creates systemic exposure as Danish underwriters rely on identical vendor platforms for Jutland flood zone assessments. Distribution runs through employer-sponsored pension networks for life products and broker-mediated placement for commercial lines, with direct digital channels gaining share fastest in standardized personal risks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
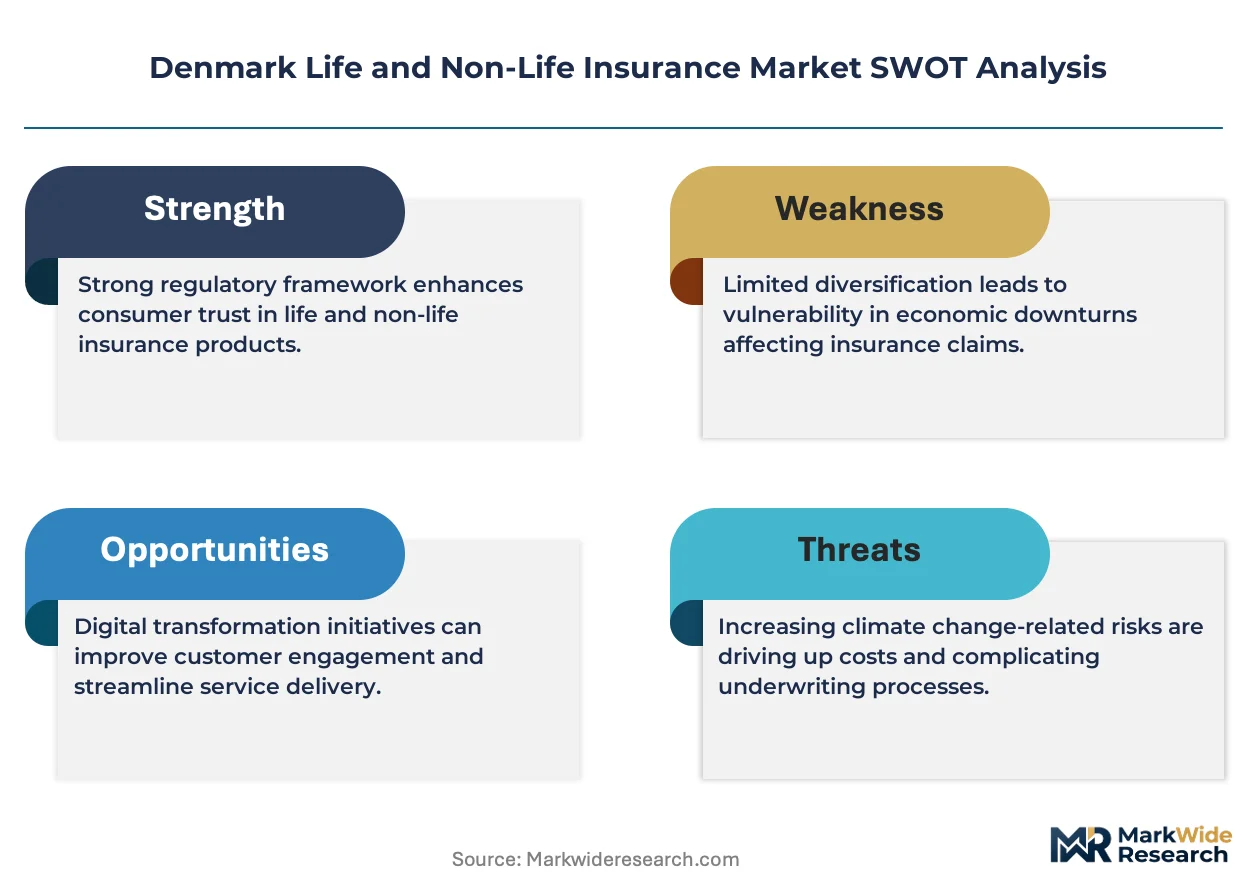
This market functions as a defensive-moat story anchored in regulatory entrenchment—Solvency II capital requirements and Finanstilsynet licensing create barriers that protect incumbent positions against unlicensed digital challengers.
For Market Incumbents: Pre-empt embedded insurance partnerships with Danish fintech platforms and neobanks before specialist insurtechs capture point-of-sale distribution. Fortify proprietary data assets in climate risk modeling to differentiate underwriting precision as storm frequency escalates across Zealand coastal zones. Channel control through employer-sponsored pension networks remains the priority lever against direct-channel encroachment. For New Entrants and Emerging Players: Pursue parametric climate product white space in agricultural and renewable energy exposures, where index-triggered structures bypass incumbent claims adjustment infrastructure. Target SME commercial package policies in Denmark's regional cities outside Copenhagen, where broker relationships dominate but digital servicing gaps persist. A go-to-market angle through API-first fleet administration tools for mid-market logistics operators offers lowest customer acquisition friction. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because occupational pension scale advantages compound through employer switching costs and multi-decade policy administration relationships. Acquisition targets should emphasize algorithmic underwriting platforms with demonstrated customer acquisition cost control. The signal to watch is Finanstilsynet's interpretation of forthcoming EU insurance recovery and resolution directives, which will reshape capital flexibility and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Insurance Partnership | Point-of-sale policy attachment through Danish neobank platforms captures digitally native policyholders before traditional broker engagement. |
| Parametric Product Development | Index-triggered structures for wind farm and agricultural exposures bypass claims friction while aligning with CSRD climate disclosure mandates. |
| Pension Decumulation Service Launch | Income guarantee products for baby-boom cohort transitions address advisory gaps as occupational schemes shift from accumulation to drawdown. |
| Climate Risk Model Investment | Proprietary flood and storm damage algorithms differentiate underwriting precision as Finanstilsynet escalates scenario disclosure requirements. |
| Direct Channel API Expansion | Real-time quote connectivity for Copenhagen corporate risk managers reduces broker dependency in mid-market commercial lines. |
Study Parameters
The analysis maps life insurance, health insurance, property insurance, and liability insurance segments, each validated through chief underwriting officers, actuarial directors, reinsurance placement specialists, and Finanstilsynet supervisory staff. Primary fieldwork combined structured interviews with secondary validation through EIOPA regulatory filings, Danish Insurance Association statistical releases, Solvency II public disclosure reports, and occupational pension fund annual statements. Bottom-up premium volume estimates triangulated against top-down GDP-insurance penetration benchmarks.
Assumptions held fixed include Solvency II regulatory continuity, Danish occupational pension contribution rates, and EU climate disclosure trajectory. Variables incorporated across the analysis window encompass interest rate environment shifts, storm loss frequency patterns, and digital channel adoption curves. Segmentation modeling covered insurance type, customer segment, distribution channel, and policy architecture dimensions. CAGRs derived from historical premium growth patterns adjusted for demographic transition effects and reinsurance cost inflation.
Macroeconomic conditions sit as an overlay; deviation in Danish monetary policy stance, EU regulatory harmonization pace, or Nordic storm severity would shift the trajectory. Forecasts reflect documented assumptions regarding capital adequacy interpretation and climate scenario modeling standards. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Norway Life and Non-Life Insurance Market
Life and Non Life Insurance
Poland Life and Non-Life Insurance Market
Life and Non Life Insurance
South Korea Life & Non-Life Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia Pacific Life & Non-Life Insurance Market
Life and Non Life Insurance
Life Insurance Policy Administration System Market
Life and Non Life Insurance
Peru Life and Non-Life Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
USA Life and Non-Life Insurance Market
Life and Non Life Insurance
Russia Life and Non-Life Insurance Market
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
Children Life Insurance Market