
 GCC Payment Gateway Market | 2026-2036
GCC Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Payment Gateway Market Intelligence
Market Context
Platform licensing revenue is tilting from pure transaction processing toward value-added merchant services across the GCC. Network International leverages its acquiring license across the UAE and Egypt to sustain merchant relationships beyond gateway functions. Saudi Payments anchors domestic routing infrastructure through its control of the mada network. HyperPay competes on localized Arabic-language checkout experiences for mid-market e-commerce operators.
Technical Definition and Structural Segments
A payment gateway is a technology layer that encrypts, routes, and authorizes financial transactions between merchants and acquiring banks, typically processing data through TLS 1.3 channels and tokenization vaults to reduce PCI-DSS scope for merchants. Mobile wallet integration within the Payment Method dimension leads transaction volume growth as Apple Pay and stc pay penetration deepens across Gulf markets, while the API segment under Integration Type captures the fastest expansion as SaaS platforms demand headless checkout architectures. The Large Transactions category maintains the highest per-transaction margin pool despite lower velocity, particularly in B2B trade finance applications.
Regulatory Frame and Outlook
SAMA's open banking regulations and the UAE Central Bank's stored value facility licensing framework reshape product standards for data residency and consumer protection across Saudi Arabia and the Emirates. SAMR-aligned cybersecurity certifications and PCI-DSS 4.0 compliance timelines determine market access for international vendors seeking local operating authority. Stakeholders must monitor how real-time payment scheme interoperability between Bahrain's Benefit and Saudi Arabia's mada systems redirects gateway routing economics.
Market Dynamics
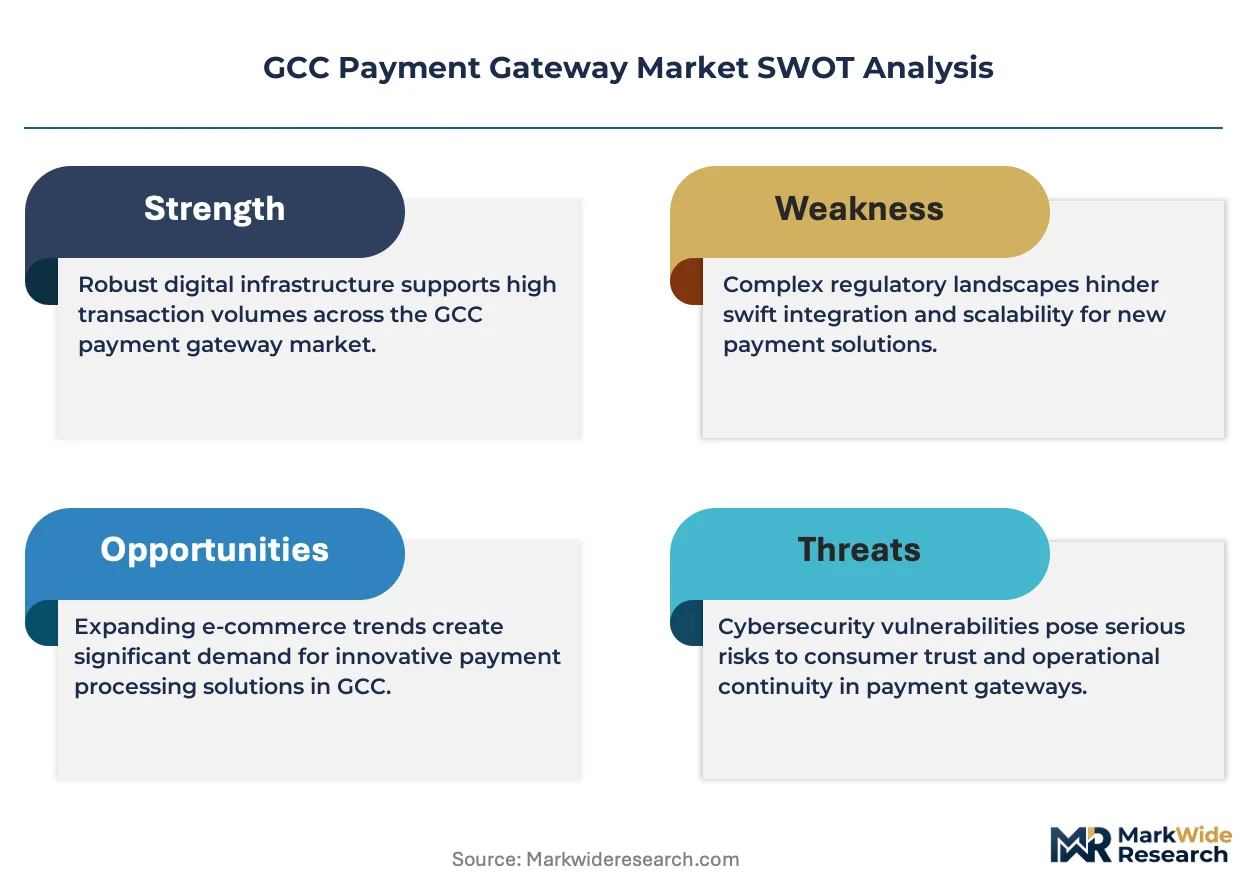
The Saudi Central Bank's open banking framework is forcing gateway providers to rebuild their data architectures around localized tokenization vaults, while SAMR-aligned cybersecurity certifications are creating tiered vendor access tiers that favor domestic infrastructure operators.
Growth Catalysts
- SAMA Open Banking Mandate:The regulatory framework requires banks to expose APIs for third-party payment initiation, expanding gateway integration points for fintech aggregators across Saudi Arabia.
- Mobile Wallet Proliferation:stc pay and Apple Pay penetration in the UAE and Saudi Arabia is generating transaction volume that demands real-time gateway capacity expansion.
- E-commerce Infrastructure Buildout:Dubai Internet City and Riyadh's fintech corridor are concentrating merchant onboarding, creating density economies for gateway providers serving mid-market retailers.
Market Restraints
- Data Localization Compliance Costs:SAMR requirements for in-country data residency are forcing international vendors to deploy separate infrastructure stacks, raising operational overhead.
- Acquiring License Concentration:Network International and Saudi Payments control critical domestic routing licenses, limiting independent gateway access to direct bank relationships.
- PCI-DSS 4.0 Migration Timeline:The certification upgrade demands substantial engineering resources, compressing vendor margins during the transition window.
Strategic Opportunities
- Bahrain-Oman Corridor Expansion:Real-time payment interoperability between BenefitPay and regional schemes creates cross-border gateway routing opportunities outside the UAE-Saudi duopoly.
- B2B Trade Finance Digitization:Large transaction categories in corporate procurement remain underpenetrated by modern checkout infrastructure, offering margin expansion potential.
- Arabic-Language Checkout Optimization:Right-to-left interface localization and local payment method integration represent service differentiation white space for mid-market SaaS platforms.
Industry Challenges
- Certified Engineering Talent Scarcity:PCI-DSS QSA and SAMR cybersecurity auditor credentials are concentrated among a small pool of regional specialists, slowing vendor scaling.
- Legacy Core Banking Integration:Many UAE and Saudi banks operate on decades-old mainframe architectures, requiring costly middleware development for modern API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Payment Gateway Market |
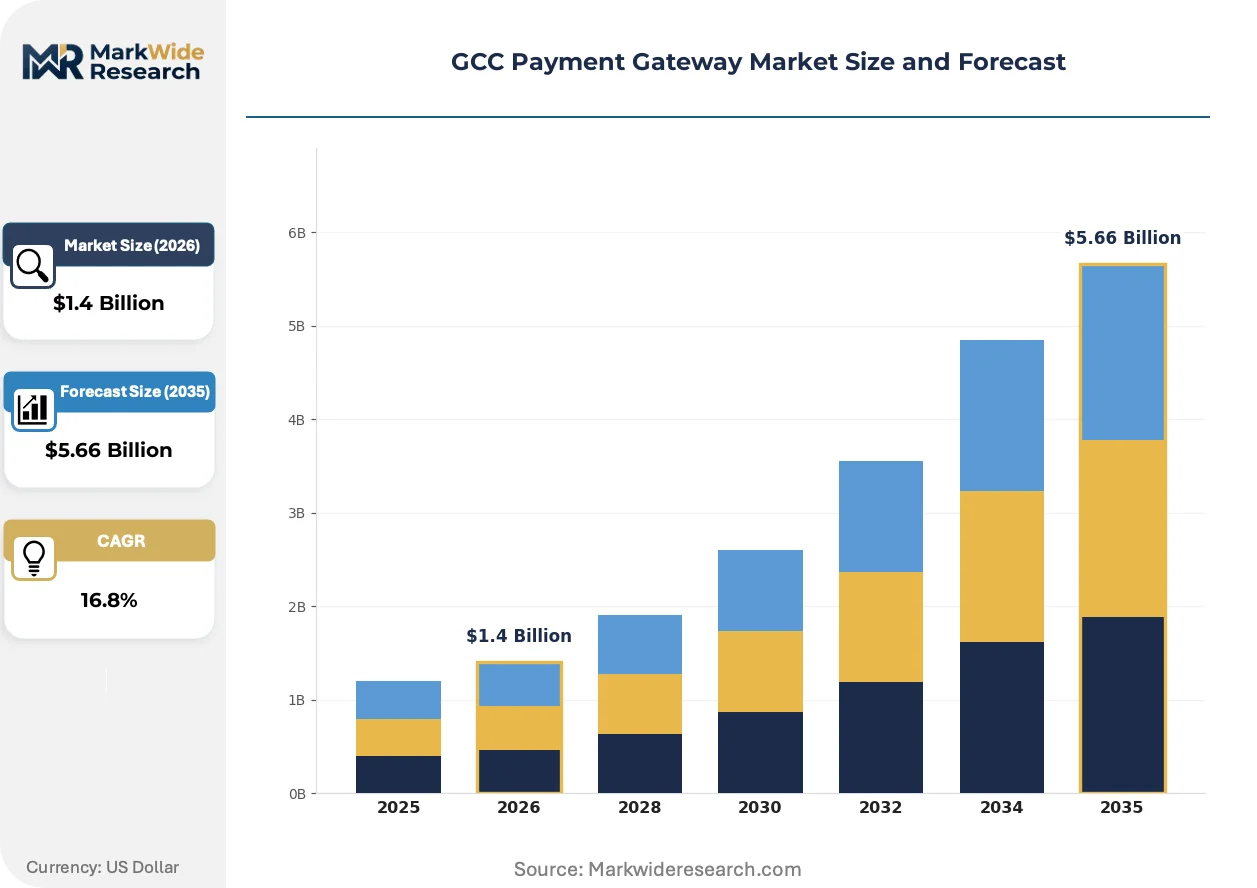
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $5.66 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer End User: Retail, E-commerce, Hospitality, Education Integration Type: Hosted, API, Server-Side, Client-Side Transaction Size: Micro Transactions, Small Transactions, Medium Transactions, Large Transactions |
| Companies Covered | JPMorgan Chase, HyperPay, Elavon, Saudi Payments, Emirates Payment Gateways, Worldpay, Network International, PayFort, Bank of America, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Payment Gateway Market Strategic Shifts & Innovations
Gateway architectures are fragmenting from monolithic platforms into composable service layers, with merchant demand tilting toward embedded finance capabilities and headless checkout experiences that decouple front-end presentation from back-end routing.
Tokenization vault technology is virtualizing merchant PCI-DSS compliance scope by shifting card data storage away from merchant environments. Mid-market e-commerce operators in the UAE are adopting this architecture fastest, drawn by reduced audit burdens. The technology is virtualizing the traditional boundary between gateway and merchant infrastructure, compressing vendor differentiation around value-added services rather than core routing.
SAMA's open banking regulations are mandating standardized API specifications for account information and payment initiation services. Gateway providers must now certify against these protocols to maintain bank connectivity, reshaping product roadmaps. Saudi Arabian fintech corridors are responding with specialized compliance engineering teams that bridge regulatory interpretation and technical implementation.
Merchant procurement of payment infrastructure is consolidating around platform ecosystems rather than standalone gateway contracts. Shopify and WooCommerce aggregators in Dubai Internet City are bundling checkout services, displacing direct vendor relationships. This pattern is most visible among digitally native retailers in the UAE's free zone clusters, where platform dependency is accelerating.
GCC Payment Gateway Market Segmentation
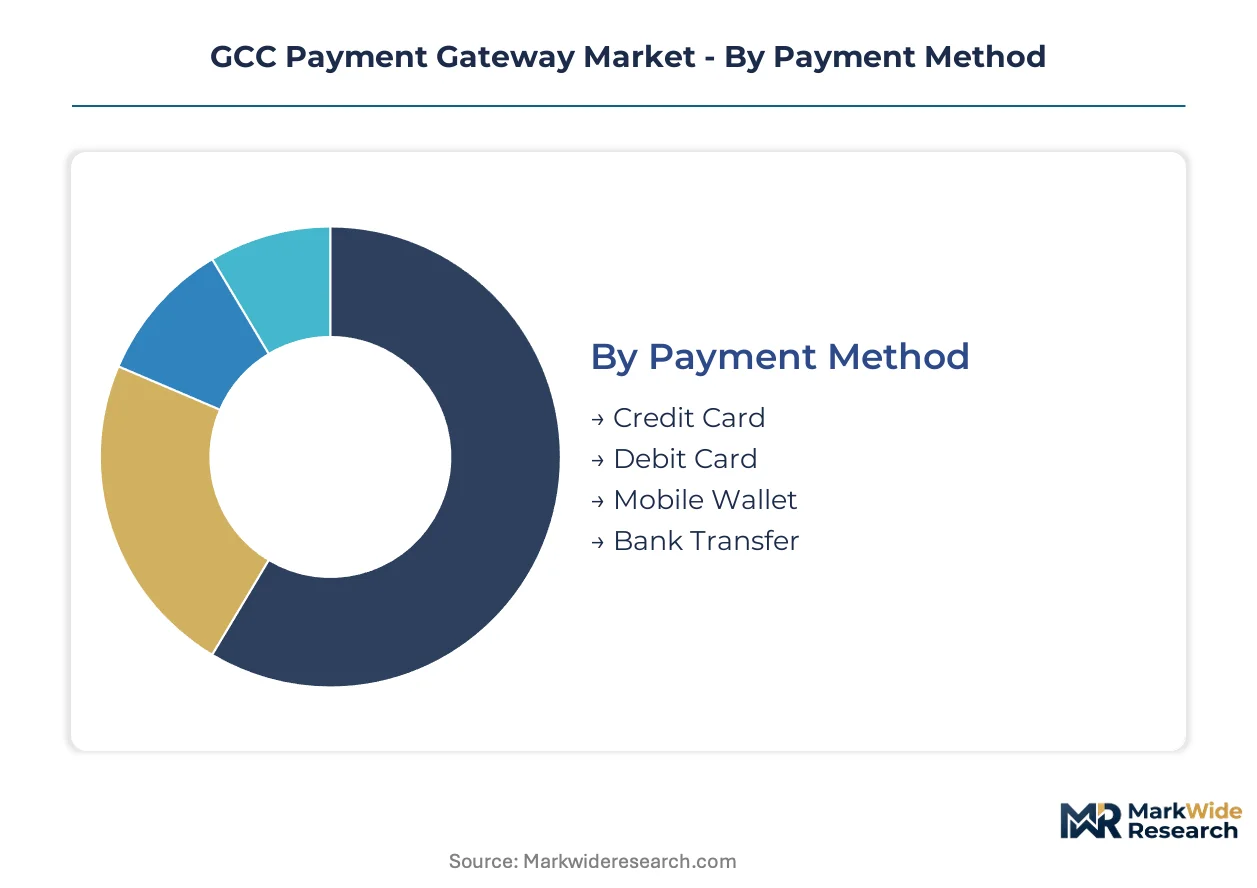
Gateway providers in the GCC configure product roadmaps around four structural dimensions that determine routing economics, compliance scope, and merchant acquisition costs. Each segment carries distinct technical requirements and regulatory touchpoints across Saudi Arabia and the Emirates.
Payment Method:
After-sales service intensity varies sharply across payment rails, with mobile wallets demanding continuous token vault maintenance and scheme certification updates that credit card infrastructure does not require.
- Mobile Wallet:stc Pay and Apple Pay integration requires real-time token provisioning and scheme-specific certification cycles. Demand clusters among Dubai Internet City e-commerce operators seeking reduced checkout abandonment through biometric authentication.
- Credit Card:Visa and Mastercard routing remains the revenue foundation for UAE acquiring banks, though interchange compression is redirecting merchant preference toward alternative rails. Saudi Arabia's mada network competes for domestic volume.
- Debit Card:Direct bank account debiting through mada and UAE domestic schemes offers lower processing costs for high-frequency merchants.
- Bank Transfer:Account-to-account settlement through SAMA's open banking APIs is gaining traction among B2B trade finance applications.
By volume, credit card processing leads. By growth pace, mobile wallet integration is ahead.
End User:
Cost tier stratification separates enterprise-grade hospitality deployments from lean retail configurations, with e-commerce occupying the middle ground on implementation complexity.
- E-commerce:Headless checkout architectures and Arabic-language localization dominate merchant requirements. Riyadh's fintech corridor is concentrating mid-market platform demand for API-first gateway integration.
- Retail:Point-of-sale terminal integration with unified commerce capabilities drives procurement decisions among UAE mall operators.
- Hospitality:Property management system connectivity and multi-currency settlement for international guests define technical specifications.
- Education:Recurring billing for tuition and fee collection requires subscription management tooling that pure transaction gateways rarely provide.
E-commerce captures the steepest expansion trajectory as merchant onboarding accelerates across Saudi Arabia's digital economy initiatives.
Integration Type:
Volume concentration tilts toward hosted solutions among smaller merchants, while API adoption climbs fastest among platform-native retailers seeking checkout customization.
- API:Headless architectures decouple front-end presentation from back-end routing, enabling SaaS platforms to embed payment flows within proprietary interfaces. Dubai Internet City aggregators are standardizing on this model.
- Hosted:Redirect-based checkout minimizes PCI-DSS scope for merchants lacking dedicated security engineering. This configuration dominates among traditional retailers in the Emirates.
- Server-Side:Direct server-to-server integration suits large enterprises with existing token vault infrastructure.
- Client-Side:JavaScript SDK implementations balance customization against compliance burden for mid-market operators.
Hosted solutions maintain volume leadership. API integration is climbing fastest as platform ecosystems consolidate merchant procurement.
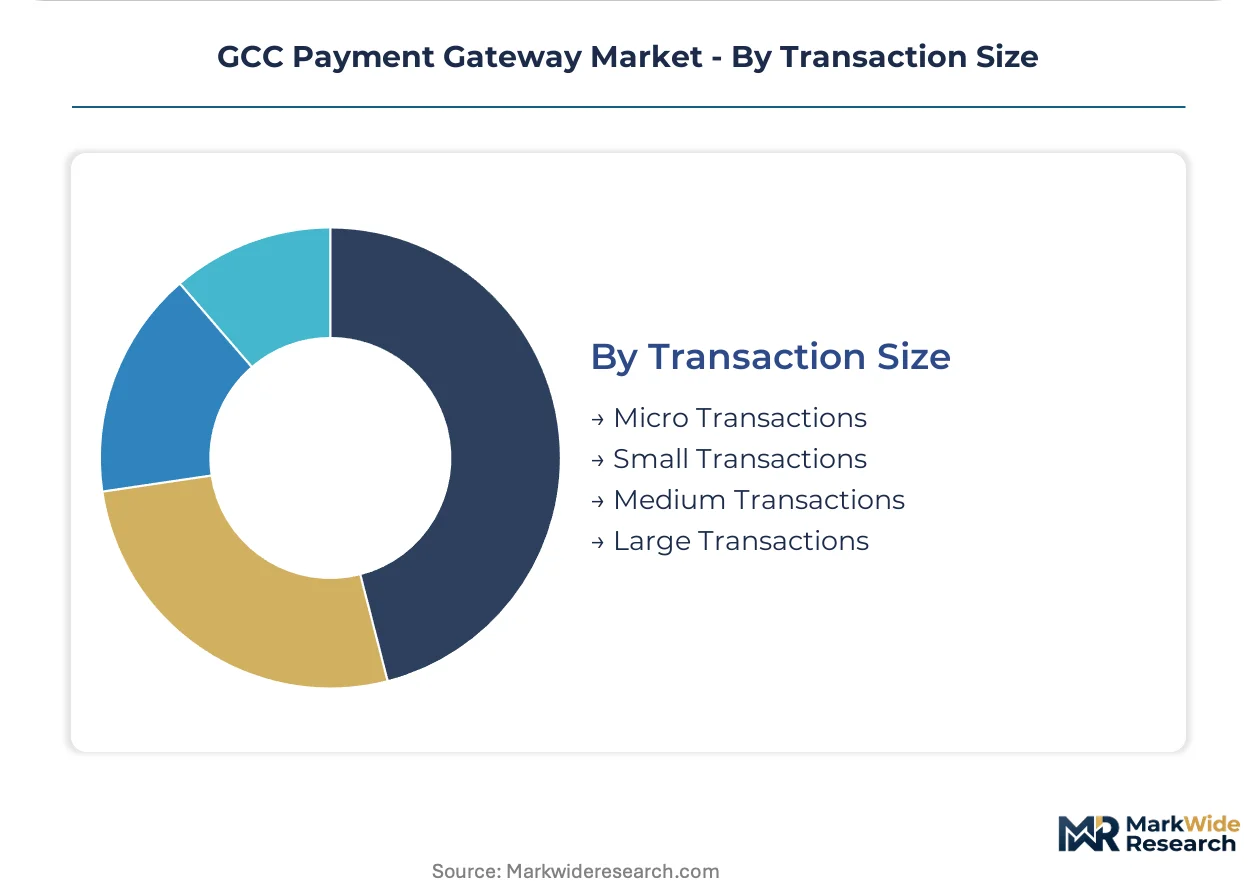
Transaction Size:
Margin structure inverts across transaction tiers, with large-value B2B settlements commanding premium processing fees despite lower velocity than consumer micro-payments.
- Large Transactions:Corporate trade finance and procurement payments exceed standard consumer interchange thresholds, requiring enhanced underwriting and delayed settlement protocols. Saudi Arabia's industrial zones generate concentrated demand.
- Micro Transactions:Sub-five-dirham digital content and transit payments demand specialized routing to avoid minimum fee erosion. UAE mobility apps are driving adoption.
- Small Transactions:Quick-service retail and convenience purchases represent high-velocity, thin-margin processing.
- Medium Transactions:Standard e-commerce basket values occupy the competitive center of gateway pricing tables.
Micro transactions lead by volume. Large transactions are expanding most quickly as corporate digitization penetrates Gulf trade corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE deploy payment gateways for high-velocity e-commerce checkout, while Bahrain and Oman concentrate on cross-border B2B settlement corridors. Kuwait and Qatar prioritize luxury hospitality and premium retail configurations.
Saudi Arabia
Riyadh's fintech corridor drives merchant onboarding for mid-market e-commerce platforms. The Saudi Central Bank's open banking framework mandates API standardization for payment initiation services. Jeddah's logistics hubs concentrate fulfillment-integrated checkout demand from fast-fashion retailers.
United Arab Emirates
Dubai Internet City clusters SaaS aggregators seeking headless gateway architectures for platform-native merchants. The UAE Central Bank's stored value facility licensing framework imposes data residency requirements on international vendors. Abu Dhabi's sovereign wealth-backed fintech initiatives are anchoring enterprise-grade tokenization infrastructure.
Bahrain
The Benefit real-time payment scheme generates cross-border routing demand from Saudi-connected trade finance. The country's national financial regulator maintains interoperability standards with regional clearing systems. Manama's banking district concentrates Islamic finance institutions requiring Sharia-compliant settlement gateways.
Kuwait
Premium retail and hospitality sectors drive high-value transaction processing requirements. The central bank's consumer protection framework shapes merchant certification timelines. Kuwait City's mall operators deploy unified commerce gateways linking point-of-sale and e-commerce channels.
Oman
Logistics corridor digitization creates B2B procurement gateway demand from port-connected enterprises. The national payment system modernization program expands real-time settlement infrastructure. Muscat's free zone clusters attract cross-border e-commerce operators seeking Gulf-wide routing access.
GCC Payment Gateway Market Key Industry Players
Capability concentration sits with domestic infrastructure operators holding acquiring licenses; scale advantage sits with international processors with regional certification depth. The market structures around three tiers: bank-owned domestic schemes, regional specialists with multi-country licensing, and global processors serving multinational merchants. Dominant competitive moves include strategic partnerships with e-commerce platforms and geographic expansion through regulatory sandbox entry.
Within the domestic infrastructure tier, Saudi Payments and Network International exemplify operators controlling critical routing licenses across their home markets. HyperPay occupies a position among regional specialists competing on Arabic-language checkout localization for mid-market merchants. JPMorgan Chase and Bank of America represent global banking processors anchoring enterprise relationships through integrated treasury services.
| Leading Market Players |
|---|
| JPMorgan Chase |
| HyperPay |
| Elavon |
| Saudi Payments |
| Emirates Payment Gateways |
| Worldpay |
| Network International |
| PayFort |
| Bank of America |
| Others |
Cost & Logistics Intelligence
Overcapacity in UAE-based tokenization infrastructure is compressing per-transaction margins for gateway providers while simultaneously accelerating merchant acquisition spending across Saudi Arabia's fintech corridor, creating divergent pricing postures between volume-leaders and specialist operators.
Pricing Analysis
Long-term SaaS contracts dominate merchant relationships in the GCC, with tiered subscription structures anchoring revenue for platform-integrated providers. Price differentiation rests on PCI-DSS certification grade and Arabic-language localization depth, with certified vendors commanding premium positioning. Cost compression in micro-transaction processing is intensifying because mobile wallet minimum fees are eroding margins at high velocity. Mid-market e-commerce operators in Dubai Internet City exhibit the highest price sensitivity, while enterprise hospitality deployments in Kuwait show the least.
Supply Chain Analysis
Upstream cryptographic hardware and token vault software feed primarily from vendors in the United States, Germany, and Israel, with TLS certificate authorities and HSM manufacturers anchoring the technology stack. Raw material dependencies center on semiconductor-grade silicon for secure enclaves, specialized firmware for payment terminals, and cloud compute capacity from hyperscale providers. Single-source vulnerability in SAMR-certified cybersecurity auditor credentials creates bottleneck risk for vendor scaling. Distribution runs through bank-owned acquiring networks and SaaS platform aggregators, with direct merchant relationships fragmenting toward embedded finance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the GCC payment gateway market creates entry niches as SAMA's open banking mandate splinters bank connectivity requirements and merchant procurement consolidates around platform ecosystems rather than standalone vendors.
For Market Incumbents: Insulate core acquiring relationships by deepening vertical integration into tokenization vault infrastructure and preemptively certifying against PCI-DSS 4.0 timelines before compliance windows compress engineering resources. The threat of SaaS platform disintermediation demands channel control through exclusive Shopify and WooCommerce partnership structures. For New Entrants and Emerging Players: Mid-market B2B trade finance applications in Saudi Arabia's industrial zones represent the most penetrable entry point, with underdeveloped checkout infrastructure for large-value corporate procurement. Bahrain-Oman cross-border routing corridors offer secondary expansion terrain outside the UAE-Saudi duopoly. A compliance-engineering-first go-to-market angle bridging SAMR interpretation and technical implementation accelerates bank connectivity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across open banking API infrastructure as certification requirements multiply engineering headcount needs. Long-term viability over the coming decade favors acquisition targets with multi-country licensing depth and existing SAMA or UAE Central Bank regulatory relationships. The signal to watch is real-time payment scheme interoperability announcements between Benefit, mada, and regional clearing systems.| Strategic Initiative | Industry Significance |
|---|---|
| API Standardization Investment | SAMA certification requirements reshape product roadmaps for bank connectivity maintenance. |
| Tokenization Vault Expansion | Virtualized PCI-DSS scope reduces merchant audit burdens and anchors recurring revenue. |
| Arabic Localization Development | Right-to-left checkout interfaces differentiate mid-market offerings in Riyadh's corridor. |
| Cross-Border Routing Partnership | Benefit-mada interoperability creates arbitrage opportunities outside dominant UAE-Saudi channels. |
| Platform Ecosystem Integration | Shopify and WooCommerce bundling captures merchant procurement consolidation in Dubai Internet City. |
Research Approach
Operator-level perspectives from gateway engineering directors, merchant platform CTOs, SAMA regulatory affairs leads, and UAE Central Bank licensing officers anchored the qualitative base. Primary interview insights combined with secondary validation against SAMA open banking framework documentation, UAE Central Bank stored value facility licensing records, PCI Security Standards Council certification databases, and hyperscaler cloud region expansion disclosures. Bottom-up transaction volume modeling and top-down market sizing triangulation established value estimates.
Scenario-bracketing around regulatory implementation timelines and mobile wallet penetration curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include payment method, integration type, end-user vertical, transaction size tier, and regulatory jurisdiction cluster. CAGRs derived from historical volume trajectories and policy-driven inflection points incorporated SAMA API mandate compliance schedules and real-time payment scheme interoperability announcements as industry-specific inputs.
Practitioners should monitor SAMA cybersecurity certification queue lengths and PCI-DSS 4.0 auditor availability for early signals of vendor scaling constraints. Forecasts reflect assumptions about open banking API adoption velocity and platform ecosystem consolidation patterns. Cross-checking against UAE Central Bank quarterly licensing disclosures and Saudi Payments mada network volume reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
QR Codes Payment Market
Payments
Face-Swiping Payment Market
Payments
Europe Payment Analytics Software Market
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Singapore Remittance Market
Payments
In-Vehicle Payment Services Market
Payments
Hong Kong Credit Cards Market
Payments
Cross-Border Payment Platform Market
Payments
Payment Analytics Software Market
Payments
Egypt Mobile Payments Market
Payments
Netherlands Mobile Payments Market
Payments
Malaysia Payments Market
Payments
Spain Payment Gateway Market
Payments
Enterprise Payment Software Market
Payments
Ghana Mobile Money Market