
 Norway Mobile Payments Market | 2026-2036
Norway Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Mobile Payments Market Analytics
Revenue-based merchant service agreements is rewriting competitive entry thresholds in Norwegian digital payments. Vipps leverages its domestic bank consortium backing to sustain ubiquitous consumer reach. MobilePay anchors Nordic cross-border transaction flows. DNB competes through direct issuer-processor integration.
Norway mobile payments encompass contactless value transfer protocols operating on NFC-enabled devices, QR code standards, and real-time bank transfer rails, with transaction authentication requiring biometric verification or PIN entry alongside tokenized credential exchange. The primary commercial purpose centers on displacing physical currency and card-present interactions across retail, transit, and peer-to-peer contexts. Mobile wallets lead transaction volume due to embedded loyalty and transit integration, while QR code payments represent the fastest-growing interface as smaller merchants bypass terminal hardware costs. Fraud detection services command premium positioning within the service type dimension as regulatory liability frameworks tighten.
Norges Bank shapes infrastructure requirements through real-time gross settlement system mandates, while the Norwegian Data Protection Authority enforces GDPR-aligned consent protocols for transaction data processing. The Financial Supervisory Authority of Norway imposes capital reserve and operational resilience standards on payment service providers. Stakeholders must monitor interoperability negotiations between domestic wallet schemes and incoming EU payment service directives.
Market Dynamics
Norges Bank's real-time gross settlement mandates are compressing transaction clearing windows from days to seconds, forcing payment service providers to rebuild core infrastructure around instant settlement rails rather than batch processing architectures.
Growth Catalysts
- Contactless terminal mandates:Norwegian retailers face accelerating consumer expectations for tap-to-pay acceptance, driving terminal hardware refresh cycles across grocery and transit verticals.
- GDPR-aligned consent frameworks:The Norwegian Data Protection Authority enforces granular transaction data permissions, creating competitive differentiation for providers with privacy-by-design architectures.
- Oslo fintech cluster density:Concentrated developer talent pools enable rapid pilot-to-production pipelines for wallet feature rollouts and merchant integration tooling.
Market Restraints
- Terminal hardware cost barriers:Small merchants in rural Norway face capital constraints preventing NFC-enabled point-of-sale adoption, perpetuating cash dependency in dispersed populations.
- Bank consortium governance friction:Vipps' shared ownership structure across competing domestic banks creates decision latency for pricing and feature prioritization.
- Biometric authentication hardware dependencies:Fingerprint and facial recognition components concentrate supply among Asian semiconductor fabricators, exposing wallet providers to shipping volatility.
Strategic Opportunities
- Nordic cross-border wallet interoperability:MobilePay's Danish-Swedish-Footprint creates template for Norwegian wallet participation in unified Scandinavian payment zones.
- QR code merchant onboarding:Software-only acceptance solutions bypass terminal procurement entirely, opening rural and micro-merchant segments previously excluded from digital payment networks.
- Transit authority open-loop integration:Ruter and Vy rail systems are piloting bank card and wallet acceptance directly at fare gates, displacing closed-loop transit card silos.
Industry Challenges
- Real-time settlement engineering scarcity:Norway's domestic talent pool lacks sufficient distributed systems architects capable of building sub-second clearing engines at scale.
- Legacy core banking integration complexity:DNB and regional banks operate decades-old mainframe architectures, forcing wallet providers to maintain expensive middleware abstraction layers.
- PSD2 compliance timeline pressure:The Financial Supervisory Authority of Norway mandates open banking interfaces with strict operational resilience testing, consuming substantial development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Mobile Payments Market |
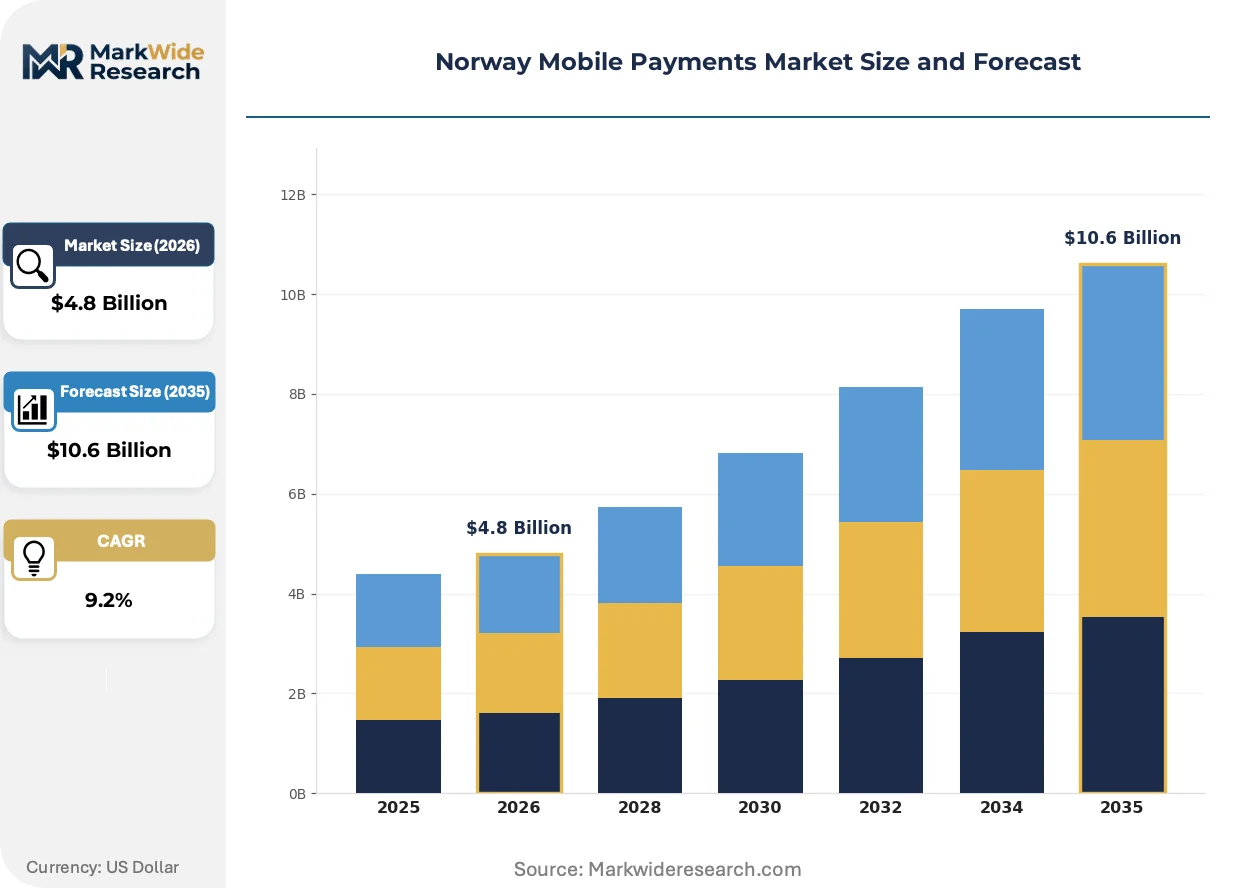
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Card Payments, Mobile Wallets, Bank Transfers, QR Code Payments End User: Consumers, Merchants, Retailers, Corporates Technology: NFC, Contactless, Online Payments, In-App Payments Service Type: Payment Gateway, Fraud Detection, Mobile Banking, P2P Transfers |
| Companies Covered | Vipps, MobilePay, Apple Pay, Google Pay, PayPal, BankAxept, mCash, DNB, Tidypay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Mobile Payments Market Evolving Landscape
Tokenized credential exchange is displacing static card numbers across Norwegian payment flows, with biometric binding and device-specific cryptography creating authentication architectures that resist replay attacks and credential stuffing.
SoftPOS technology is hybridizing smartphone hardware into payment acceptance terminals. Norwegian fintechs deploy apps converting standard Android devices into PIN-capable acceptance points. Small merchants in Bergen and Trondheim adopt these solutions to avoid dedicated terminal leases. The technology is compressing merchant acquisition costs and accelerating micro-business digital onboarding.
Norges Bank's settlement infrastructure roadmap mandates 24/7 real-time gross settlement availability by 2028. Payment service providers must reengineer liquidity management and fraud detection systems for continuous operation. The retail and peer-to-peer segments face the steepest adaptation curves as batch-based reconciliation practices become non-compliant.
Consumer preference is rotating toward consolidated super-app experiences. Norwegian wallet users increasingly expect embedded loyalty point redemption, transit ticketing, and identity credential storage within single interfaces. Merchants in Oslo's retail core report higher conversion rates when checkout flows surface personalized offers through these integrated environments.
Norway Mobile Payments Market Segmentation
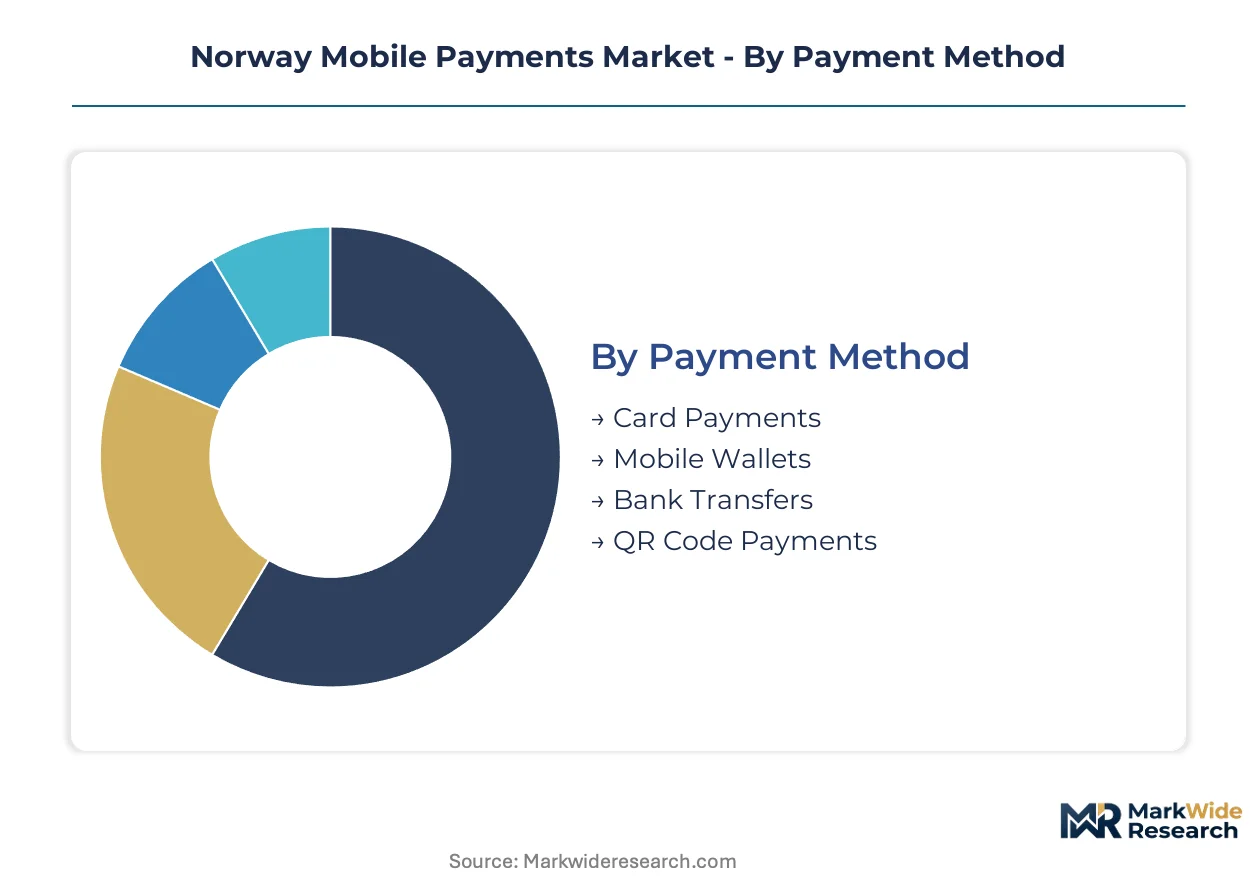
Segmentation in Norway's mobile payments landscape reveals how infrastructure investments, regulatory mandates, and merchant adoption curves distribute value across distinct operational layers. Each category exposes different competitive moats and capital intensity thresholds.
Payment Method:
Transaction velocity varies dramatically across methods, with tap-to-pay interactions clearing in under 300 milliseconds while QR-based settlements introduce multi-step authentication delays.
- Card Payments:Tokenized credential exchange dominates Oslo's retail core, where contactless terminal penetration exceeds rural Norway by wide margins. Transit authority open-loop pilots at Ruter and Vy are accelerating displacement of legacy closed-loop systems.
- Mobile Wallets:Embedded loyalty programs and municipal transit integration create sticky user ecosystems. Vipps leverages bank consortium density to maintain ubiquity across grocery and fuel verticals.
- Bank Transfers:Norges Bank's real-time gross settlement mandates compress clearing windows to seconds, forcing middleware rebuilds for providers serving corporate treasury functions.
- QR Code Payments:Software-only acceptance solutions bypass terminal procurement barriers, opening rural micro-merchant segments previously excluded from digital networks.
Card Payments dominates installed base. QR Code Payments is where expansion concentrates.
End User:
Customer acquisition economics diverge sharply, with merchant onboarding costs running multiples of consumer wallet activation due to terminal hardware and integration complexity.
- Consumers:Biometric authentication expectations are hardening, with fingerprint and facial recognition becoming default requirements for transaction authorization above threshold amounts.
- Merchants:SoftPOS deployments on standard Android hardware are compressing acquisition costs for Bergen and Trondheim micro-businesses seeking to avoid dedicated terminal leases.
- Retailers:Grocery and transit verticals face accelerating refresh cycles as contactless mandates tighten, with regional chains prioritizing PIN-capable terminal upgrades.
- Corporates:Treasury departments demand API-native reconciliation tools aligned with Norges Bank's 24/7 settlement availability roadmap.
Consumers anchor transaction volume. Merchants represent the steepest expansion trajectory as rural digitization accelerates.
Technology:
Hardware dependencies create supply vulnerability, with biometric sensor fabrication concentrated among Asian semiconductor suppliers exposing Norwegian wallet providers to shipping volatility.
- NFC:Near-field communication protocols enable sub-second credential exchange at physical point-of-sale, with terminal mandates driving grocery and fuel adoption.
- Contactless:Tap-to-pay interfaces are becoming baseline consumer expectation, forcing hardware refresh cycles across merchant tiers.
- Online Payments:Browser-based checkout flows require robust fraud detection layers as transaction liability frameworks tighten under Financial Supervisory Authority guidelines.
- In-App Payments:Native SDK integrations enable one-tap checkout within super-app environments combining loyalty, transit, and identity credential storage.
NFC commands terminal infrastructure investment. In-App Payments is climbing the fastest as consolidated wallet experiences reshape consumer preferences.
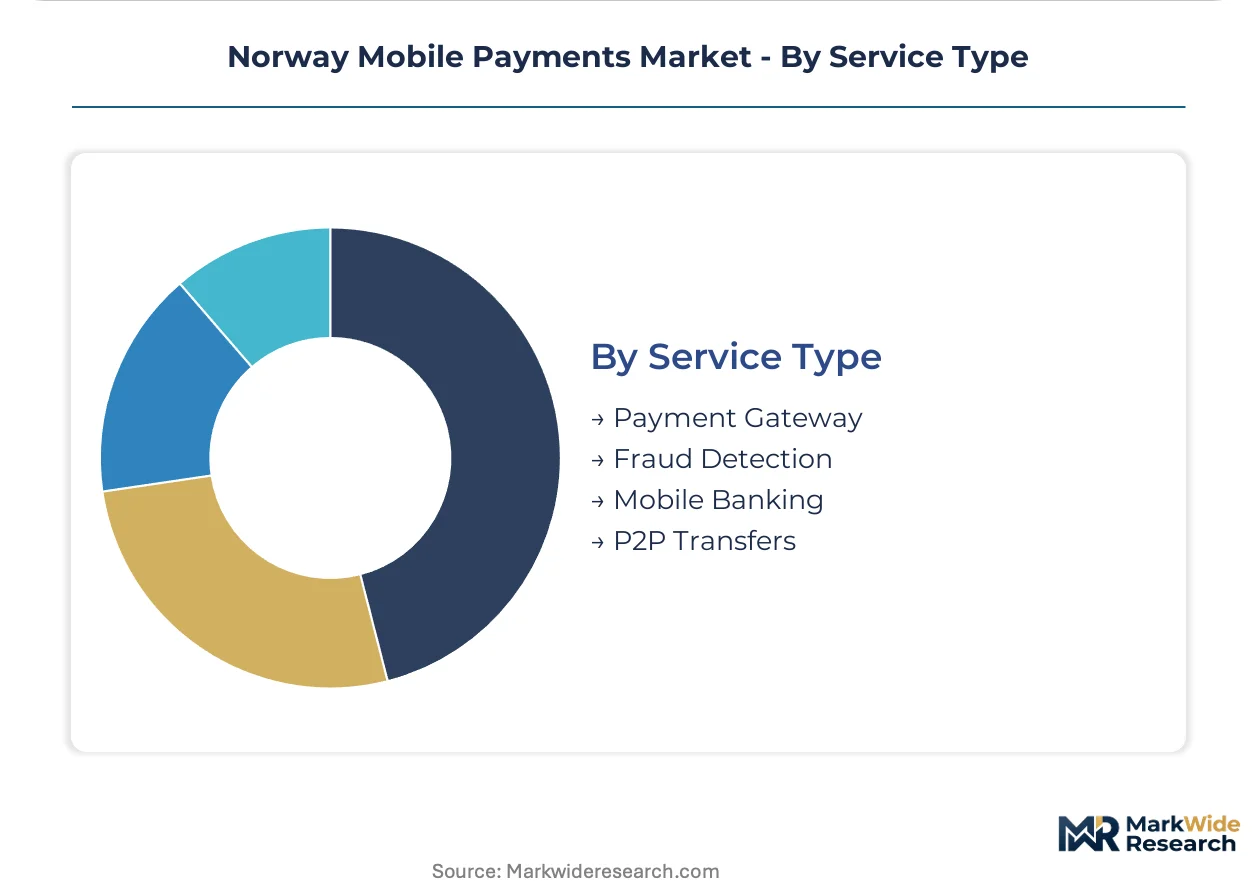
Service Type:
Margin structures invert across service layers, with fraud detection commanding premium positioning as regulatory liability frameworks impose stricter operational resilience standards.
- Payment Gateway:Middleware abstraction layers bridge legacy core banking architectures at DNB and regional institutions, consuming substantial integration bandwidth.
- Fraud Detection:Real-time risk scoring engines require sub-100 millisecond decision latency, with machine learning models trained on Norwegian transaction pattern specificity.
- Mobile Banking:Direct issuer-processor integration strategies at DNB compete against wallet consortium approaches, creating divergent technical roadmaps.
- P2P Transfers:Peer-to-peer flows concentrate in social payment contexts, with settlement speed becoming primary competitive differentiator.
Payment Gateway anchors merchant service revenue. Fraud Detection is gaining share fastest as liability frameworks tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's mobile payments sector operates as a net importer of terminal hardware and semiconductor components, while exporting software architectures and fintech expertise to neighboring Nordic markets. The country's settlement infrastructure commands regional influence through Norges Bank's real-time gross settlement mandates.
Oslo
Oslo concentrates developer talent pools and pilot-to-production pipelines for wallet feature rollouts. The Norwegian Data Protection Authority enforces GDPR-aligned consent protocols for transaction data processing. Ruter transit authority pilots bank card and wallet acceptance directly at fare gates, displacing closed-loop transit card silos.
Bergen
Bergen micro-businesses adopt SoftPOS deployments on standard Android hardware to avoid dedicated terminal leases. The Financial Supervisory Authority of Norway imposes capital reserve standards on payment service providers serving western coastal merchants. Regional grocery chains prioritize PIN-capable terminal upgrades as contactless mandates tighten.
Trondheim
Trondheim's merchant acquisition costs compress through smartphone-based acceptance solutions accelerating digital onboarding. Norges Bank's 2028 real-time gross settlement availability roadmap forces local providers to reengineer liquidity management systems. The city's technical university feeds engineering talent into distributed systems architecture roles.
Stavanger
Stavanger's energy sector corporates demand API-native reconciliation tools aligned with continuous settlement availability. Regional banks operate decades-old mainframe architectures forcing wallet providers to maintain expensive middleware abstraction layers. The municipality's procurement policies favor privacy-by-design payment architectures.
Tromsø
Tromsø's dispersed rural populations face terminal hardware cost barriers perpetuating cash dependency in Arctic merchant segments. QR code software-only acceptance solutions bypass terminal procurement entirely, opening previously excluded micro-merchants. The Norwegian Data Protection Authority's granular transaction data permissions create competitive differentiation for compliant providers.
Norway Mobile Payments Market Competitive Landscape
On the supply side, the industry is structured around three distinct strategic tiers: domestic bank consortium wallets, Nordic cross-border payment networks, and global technology platform providers. Market concentration reflects the dominance of Vipps through its shared ownership structure across competing domestic banks. Strategic archetypes include issuer-processor integrated banks, middleware abstraction layer specialists, and super-app experience consolidators. Dominant competitive moves center on merchant acquisition cost compression through SoftPOS technology and cross-border wallet interoperability negotiations.
Within the domestic consortium tier, Vipps exemplifies bank-backed ubiquitous consumer reach through its shared ownership model. MobilePay occupies a position anchoring Nordic cross-border transaction flows across Danish-Swedish-Norwegian corridors. DNB represents issuer-processor integration strategies competing against wallet consortium approaches through direct infrastructure control.
| Leading Market Players |
|---|
| Vipps |
| MobilePay |
| Apple Pay |
| Google Pay |
| PayPal |
| BankAxept |
| mCash |
| DNB |
| Tidypay |
| Others |
Value Network & Pricing Analysis
Oslo's fintech cluster concentrates payment infrastructure development capacity, with terminal hardware procurement costs and software licensing fees flowing downstream to merchant service pricing. Norges Bank's real-time settlement mandates compress clearing economics while Asian semiconductor fabrication concentration shapes biometric authentication component costs.
Pricing Analysis
Merchant acquirers anchor transaction-based pricing structures with per-tap fees scaling by settlement speed tier. Price differentiation rests on terminal integration complexity and fraud detection service bundling. Cost compression in rural merchant segments intensifies because SoftPOS solutions bypass hardware lease structures. Micro-merchants in Bergen and Trondheim exhibit highest price sensitivity; corporate treasury departments at Stavanger energy firms demonstrate lowest.
Supply Chain Analysis
Extended payment terms from Taiwanese and South Korean semiconductor fabricators shape working capital requirements for Norwegian wallet providers. Biometric sensor modules, NFC controller chips, and secure element hardware draw from concentrated Asian manufacturing. Single-source vulnerability in fingerprint component supply exposes providers to shipping volatility. Distribution runs through Oslo-based systems integrators and regional bank technology procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norwegian mobile payments operates as a cash displacement defense, with physical currency and closed-loop transit cards representing persistent substitute threats that infrastructure investments must neutralize.
For Market Incumbents: Build switching-cost moats through embedded transit and loyalty program integration. Deepen API-native reconciliation capabilities for corporate treasury segments facing Norges Bank's continuous settlement mandates. Consolidate merchant acquisition relationships before SoftPOS technology commoditizes terminal hardware differentiation. For New Entrants and Emerging Players: Rural Tromsø micro-merchants present underpenetrated white-space where QR code software-only solutions bypass terminal procurement barriers. Target agricultural cooperative payment flows with cooperative-structured wallet architectures. Pursue white-label fraud detection service licensing to established regional banks. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure consolidation play because real-time settlement engineering scarcity and legacy core banking integration complexity create durable capability gaps. Target middleware abstraction layer specialists bridging decades-old mainframe architectures. Monitor Norges Bank interoperability negotiation outcomes with EU payment directives as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| SoftPOS Technology Deployment | Smartphone-based acceptance compresses merchant acquisition costs in Bergen and Trondheim micro-business segments. |
| Transit Authority Open-Loop Integration | Ruter and Vy rail pilots displace closed-loop transit card silos with bank credential acceptance. |
| Real-Time Settlement Engine Rebuild | Norges Bank's 2028 availability mandate forces liquidity management system reengineering. |
| Nordic Cross-Border Wallet Interoperability | MobilePay's Danish-Swedish footprint creates template for unified Scandinavian payment zone participation. |
| Privacy-by-Design Architecture Investment | Norwegian Data Protection Authority GDPR enforcement creates competitive differentiation for compliant providers. |
Research Methodology
Cross-validation between payment service provider executive interviews and Norges Bank infrastructure disclosure documents anchors the qualitative findings. Primary fieldwork encompassed wallet platform engineers, merchant acquisition directors at domestic banks, transit authority technology procurement leads, and fintech startup CTOs within Oslo's cluster. Secondary sources included Financial Supervisory Authority of Norway regulatory filings, Norges Bank settlement system roadmaps, and European Banking Authority payment statistics. Bottom-up transaction volume modeling and top-down GDP-linked payment flow estimates provided triangulation.
Calibration against historical terminal deployment rates and real-time settlement adoption curves across Nordic markets shaped projection parameters. Segmentation dimensions encompassed payment method, end-user archetype, enabling technology, and service type layers. CAGRs derived from logistic diffusion modeling of contactless terminal penetration and merchant digital onboarding velocity. Fraud detection service growth assumptions incorporated Financial Supervisory Authority liability framework tightening timelines.
Practitioners should monitor Norges Bank-EU payment directive interoperability negotiations and Asian semiconductor supply chain disruption indicators for early signals. Forecasts reflect assumptions regarding terminal hardware cost curves and rural merchant digitization willingness. Macroeconomic contraction, regulatory deviation from real-time settlement timelines, or biometric component supply interruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Tanzania Mobile Money Market
Payments
Global Mobile Payment Technology Market
Payments
Buy Now Pay Later Market
Payments
Russia Payments Market
Payments
Cash Management Software Market
Payments
Germany Real Time Payments Market
Payments
Germany Payments Market
Payments
Payment Service Provider Market
Payments
Southeast Asia POS Terminal Market
Payments
Japan Prepaid Cards Market
Payments
North America Real Time Payment Market
Payments
United States Electronic Toll Collection Market
Payments
UAE POS Terminal Market
Payments
Payment Processing Solutions Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Global Wearable Payment Device Market