
 UAE Life & Non-Life Insurance Market | 2026-2036
UAE Life & Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Life & Non-Life Insurance Market Insights
Bancassurance distribution is fragmenting as UAE banks diversify partner panels and direct digital channels capture younger policyholders. Abu Dhabi National Insurance Company anchors the non-life segment through extensive commercial lines capacity and government contract access. Orient Insurance leverages its takaful expertise to compete in Shariah-compliant product niches. MetLife sustains group life dominance through multinational corporate accounts with cross-border coverage needs.
UAE life and non-life insurance constitutes a risk-transfer mechanism where insurers pool premiums across life, health, home, and auto exposures to indemnify policyholders against defined perils. Capital adequacy ratios and actuarial reserving standards govern solvency, while products span term life, whole life, universal life, and critical illness structures designed for wealth protection and income replacement. Health insurance leads premium generation due to mandatory employer-sponsored coverage in Dubai and Abu Dhabi emirates. Auto insurance maintains mature, price-competitive dynamics with regulated tariff floors. Online platforms represent the fastest-growing distribution vector as insurtech aggregators reduce acquisition friction for individual customers and SMEs.
MOHAP and the UAE Insurance Authority shape product standards, capital requirements, and consumer protection mandates across the federation. Mandatory health insurance regulations in Dubai and Abu Dhabi emirates create baseline demand floors while SAMA-aligned prudential rules govern insurer solvency. Stakeholders must monitor how embedded insurance partnerships and open architecture distribution licenses redraw competitive boundaries without eroding intermediary commissions.
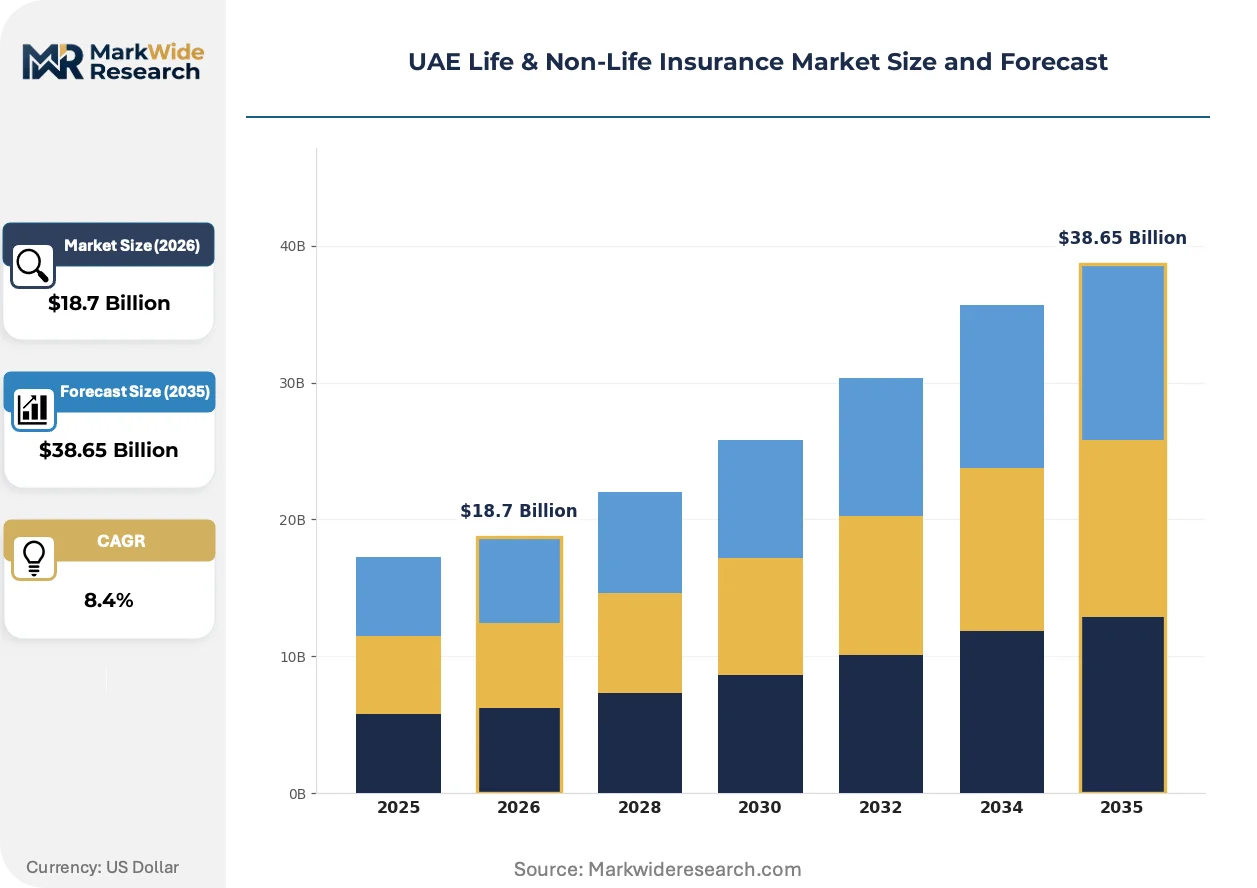
Market Dynamics
MOHAP's mandatory health insurance mandates in Dubai and Abu Dhabi are compressing distribution timelines while digital aggregators capture policyholder acquisition from traditional broker networks.
Growth Catalysts
- MOHAP Employer Mandates:Dubai and Abu Dhabi emirates require employer-sponsored health coverage, creating baseline demand floors that sustain premium inflows across group policies.
- Expatriate Workforce Expansion:Corporate visa sponsorship programs concentrate risk pools in employer-sponsored group life and health structures.
- Embedded Insurance Partnerships:Digital banking platforms integrate policy issuance at transaction points, reducing friction for auto and travel coverage uptake.
Market Restraints
- Actuarial Talent Scarcity:The UAE's limited pool of credentialed actuaries constrains product development velocity and pricing sophistication.
- Reinsurance Capacity Concentration:Regional catastrophe exposure limits access to international reinsurance markets for property and marine lines.
- Regulatory Fragmentation Across Emirates:Differing implementation timelines between Dubai Health Authority and Abu Dhabi Department of Health create compliance complexity.
Strategic Opportunities
- Northern Emirates Underpenetration:Sharjah, Ajman, and Ras Al Khaimah lack mandatory health insurance requirements, presenting white-space expansion for voluntary product uptake.
- Parametric Coverage Convergence:Satellite data and IoT sensors enable index-based triggers for crop and property policies, bypassing traditional loss-adjustment costs.
- Takaful-Compliant Pensions:Shariah-compliant retirement products align with federal savings initiatives targeting Emirati nationals.
Industry Challenges
- Legacy Core System Integration:Incumbent insurers face technical debt when connecting policy administration platforms to digital distribution APIs.
- Anti-Money Laundering Compliance:UAE Insurance Authority transaction monitoring requirements demand enhanced know-your-customer infrastructure for high-net-worth policies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Life & Non-Life Insurance Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Life Insurance, Health Insurance, Home Insurance, Auto Insurance Product Type: Term Life, Whole Life, Universal Life, Critical Illness Distribution Channel: Direct Sales, Insurance Brokers, Bancassurance, Online Platforms Customer Type: Individual Customers, SMEs, Corporates, Government Entities |
| Companies Covered | Orient Insurance, Abu Dhabi National Insurance Company, MetLife, AIG, AXA, Allianz, Alliance Insurance, National General Insurance, Union Insurance Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Life & Non-Life Insurance Market Trends and Innovations
Digital distribution infrastructure is compressing policy acquisition costs while regulatory data mandates force core system modernization across incumbent carriers.
AI-powered claims triage is rendering obsolete manual loss-adjustment workflows for auto and property lines. Mid-market insurers deploy computer vision for damage assessment, cutting settlement cycles from weeks to hours. Traditional field adjuster networks face structural compression as automated valuation models gain regulatory acceptance.
MOHAP's electronic health record interoperability mandates are reshaping data-sharing protocols between insurers and healthcare providers. Dubai Health Authority requires real-time claims submission through standardized APIs, eliminating paper-based pre-authorization. Group policy administrators must reconfigure provider networks to comply with these connectivity standards.
Direct-to-consumer platforms are disintermediating traditional broker channels for individual lines. Younger policyholders in Dubai's commercial districts purchase term life and critical illness coverage through mobile-first aggregators, bypassing face-to-face advice. Commission compression forces intermediaries to pivot toward complex commercial risk placement where advisory relationships retain value.
UAE Life & Non-Life Insurance Market Segmentation
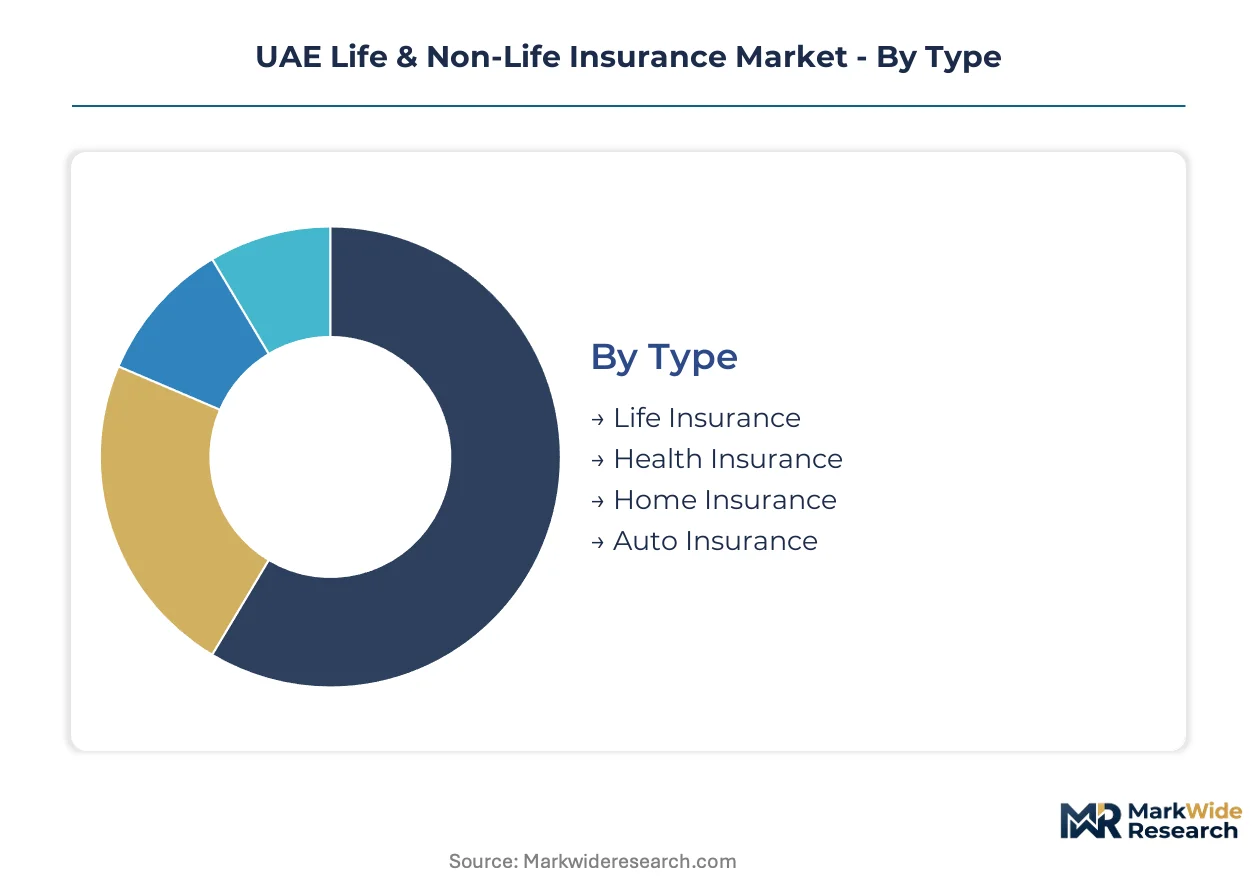
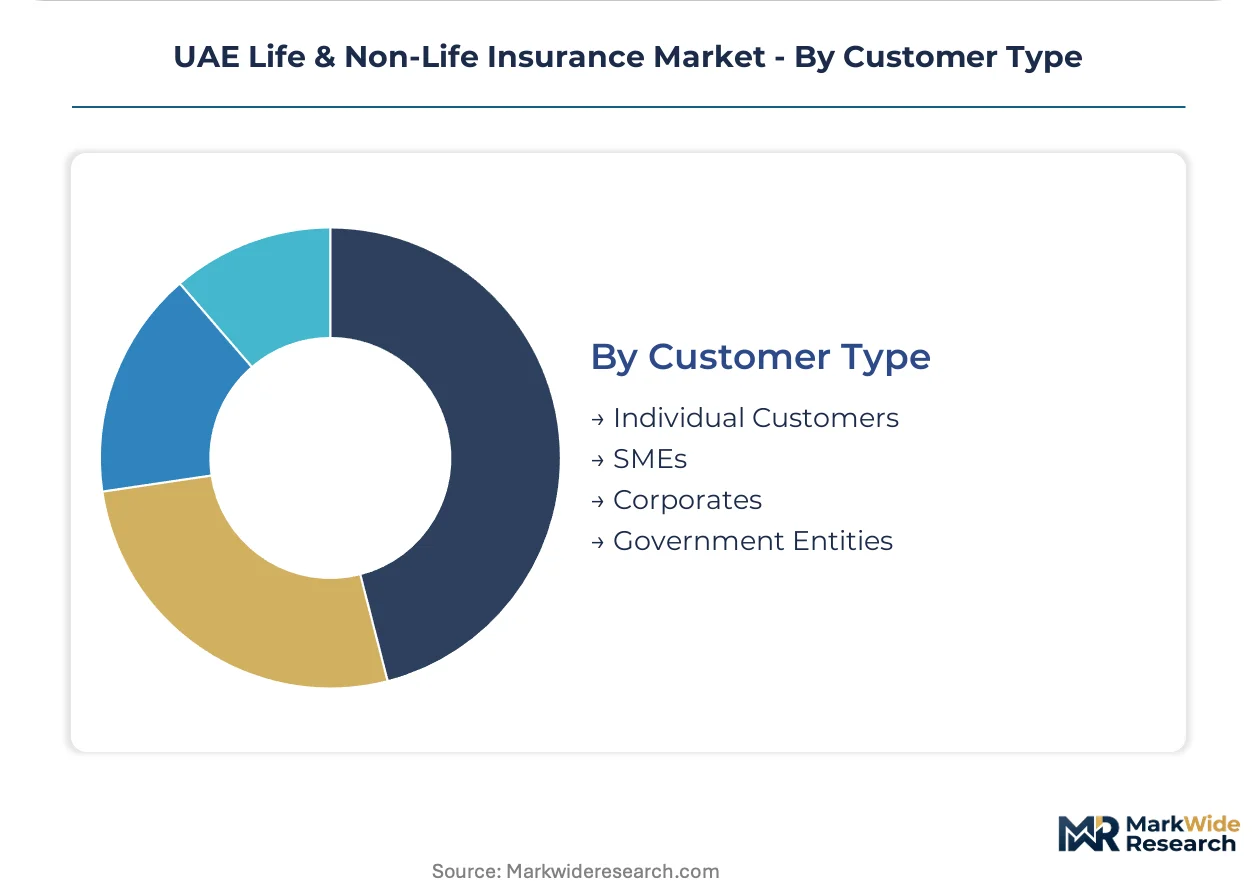
UAE insurance segmentation reveals how mandatory health mandates, expatriate workforce structures, and digital distribution preferences concentrate premium flows across distinct risk pools and customer profiles.
Type:
Life, health, home, and auto coverage each address discrete risk-transfer needs across individual wealth protection, medical expense indemnification, property damage, and vehicle liability.
- Life Insurance:Term, whole, and universal life structures provide death benefit protection and cash value accumulation for wealth preservation. Demand concentrates among high-net-worth expatriates in Dubai's financial district seeking cross-border estate planning instruments.
- Health Insurance:Medical expense reimbursement and cashless hospitalization coverage dominates premium generation. Dubai and Abu Dhabi employer mandates sustain group policy inflows, while individual portability requirements reshape policy design.
- Home Insurance:Property damage and contents coverage protects against fire, theft, and natural perils. Villa owners in Emirates Hills and Arabian Ranches drive uptake for high-value dwelling protection.
- Auto Insurance:Third-party liability and comprehensive vehicle coverage operates under regulated tariff floors. Fleet operators and individual policyholders in Dubai's dense commercial corridors sustain mature, price-sensitive dynamics.
Established volume favors health insurance; emerging adoption favors life insurance as wealth accumulation products gain traction among younger Emirati professionals.
Product Type:
Product architecture varies by duration flexibility, investment linkage, and benefit trigger mechanisms that align with customer liquidity preferences and risk tolerance.
- Term Life:Pure death benefit protection without cash value accumulation offers lowest-cost coverage for defined periods. Young professionals in Dubai's technology and finance sectors favor this structure for income replacement during peak earning years.
- Whole Life:Guaranteed death benefit with fixed premiums and participating dividends provides lifetime protection. Family offices and multi-generational households in Abu Dhabi deploy these instruments for intergenerational wealth transfer.
- Universal Life:Flexible premiums and adjustable death benefits with interest-crediting mechanisms. Sophisticated buyers seeking premium payment holidays during career transitions drive niche demand.
- Critical Illness:Lump-sum payouts upon diagnosis of specified conditions including cancer, stroke, and cardiac events. Expatriates lacking comprehensive employer coverage purchase standalone policies to bridge protection gaps.
Term life commands the largest policy count; critical illness exhibits the steepest expansion trajectory as medical cost inflation accelerates benefit adequacy concerns.
Distribution Channel:
Channel economics reflect customer acquisition cost differentials, advisory intensity requirements, and regulatory commission structures that favor certain product-channel pairings.
- Direct Sales:Insurer-employed agents and captive channels target affinity groups and existing policyholder bases. ADNIC and Orient Insurance deploy direct forces for government contract penetration and commercial renewals.
- Insurance Brokers:Independent intermediaries provide comparative advice across carrier panels. Complex commercial risk placement and multinational program structuring sustain broker relevance despite digital encroachment.
- Bancassurance:Bank branch networks and relationship manager referrals distribute simple, standardized products. Emirates NBD and First Abu Dhabi Bank partnerships concentrate credit-life and mortgage-linked coverage distribution.
- Online Platforms:Digital aggregators and direct-to-consumer portals reduce friction for term life, auto, and travel coverage. Policybazaar UAE and regional insurtechs capture younger demographics in Dubai's commercial districts.
Broker networks retain commercial dominance; online platforms are climbing the fastest as mobile-first purchasing becomes normalized among individual lines buyers.
Customer Type:
Risk pooling economics and contract scale vary dramatically across individual, small business, corporate, and sovereign purchasers with diverging negotiation leverage and customization requirements.
- Individual Customers:Retail policyholders purchasing single-life, single-vehicle, or single-property coverage. Dubai's expatriate professionals and Emirati nationals drive voluntary life and home insurance uptake beyond mandatory health requirements.
- SMEs:Small and medium enterprises with 10-250 employees seeking group health, key person life, and commercial property bundles. Ras Al Khaimah and Sharjah manufacturing clusters represent underpenetrated expansion targets.
- Corporates:Large employers with multinational operations requiring centralized program management and cross-border coverage consistency. Dubai International Financial Centre headquarters sustain group life and health premium concentration.
- Government Entities:Federal and emirate-level ministries, authorities, and state-owned enterprises with bespoke tender requirements. Abu Dhabi sovereign contracts demand extensive local capacity and shariah-compliant structures.
Corporate accounts deliver premium concentration; SME penetration offers the deepest runway as voluntary coverage expands beyond mandatory floors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai commands premium pricing power through concentrated corporate risk placement, while Abu Dhabi's sovereign contract access creates divergent margin structures across the emirates.
Dubai
Dubai International Financial Centre headquarters sustain group life and health premium concentration. Dubai Health Authority mandates real-time claims submission through standardized APIs. DIFC-based multinational corporate accounts drive cross-border coverage consistency requirements.
Abu Dhabi
Abu Dhabi Department of Health tightens compliance standards for employer-sponsored coverage. Federal and emirate-level ministries demand bespoke tender structures with shariah-compliant elements. Sovereign contracts concentrate around government entities and state-owned enterprises.
Sharjah
Manufacturing clusters in Sharjah represent underpenetrated expansion targets for voluntary product uptake. Absence of mandatory health insurance requirements creates white-space opportunities. Industrial zones near Sharjah International Airport attract SME risk placement.
Ras Al Khaimah
Ras Al Khaimah's hospitality and manufacturing sectors lack baseline demand floors seen in southern emirates. Free zone enterprises seek competitive group policy alternatives. Jebel Jais development projects generate construction-related commercial lines demand.
Northern Emirates
Ajman and Fujairah present nascent distribution infrastructure for digital aggregators. Port operations at Fujairah generate marine and cargo insurance requirements. Expatriate workforce enrollment in these emirates operates outside mandatory coverage frameworks.
UAE Life & Non-Life Insurance Market Competitive Landscape
Government-affiliated carriers and multinational specialists split the market along sovereign contract access versus cross-border expertise lines. Incumbent domestic players leverage regulatory relationships and local capacity. Three strategic archetypes dominate: state-linked insurers with government contract pipelines, global carriers with multinational program capabilities, and takaful specialists with shariah-compliant product suites. Competitive moves center on embedded insurance partnerships and digital distribution licensing rather than traditional capacity expansion.
Among UAE-based incumbents, Abu Dhabi National Insurance Company and Orient Insurance exemplify the state-linked and takaful archetypes respectively. MetLife anchors the multinational specialist tier through group life dominance. These three occupy positions across distinct competitive vectors without overlapping core account bases.
| Leading Market Players |
|---|
| Orient Insurance |
| Abu Dhabi National Insurance Company |
| MetLife |
| AIG |
| AXA |
| Allianz |
| Alliance Insurance |
| National General Insurance |
| Union Insurance Company |
| Others |
Pricing and Supply Chain Analysis
International reinsurance capacity concentration in London, Bermuda, and Singapore directly determines where underwriting margin pools accumulate across the UAE insurance value chain. Regional catastrophe exposure limits force primary carriers to accept less favorable terms, compressing domestic retention ratios while ceding commissions flow offshore.
Pricing Analysis
Customization-premium spreads separate bespoke corporate program pricing from standardized retail product tariffs. Three-tier pricing structure across premium, standard, and economy levels governs individual lines, with brand reputation and distribution channel after-sales service driving differentiation. Cost compression in the auto segment intensifies because regulated tariff floors prevent downward adjustment despite loss ratio deterioration. SMEs exhibit highest price sensitivity due to thin operating margins, while sovereign entities accept premium positioning for shariah-compliant structures.
Supply Chain Analysis
Upstream feedstock for risk capital draws from London, Bermuda, and Zurich reinsurance markets where global capacity concentrates. Treaty renewals hinge on property catastrophe modeling outputs and marine hull loss experience. Single-source vulnerability around peak terrorism and natural peril coverage creates renewal timing risk every January. Distribution runs through broker networks for commercial placements and direct digital platforms for individual policy acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE insurance market sits in a cyclical recovery phase as expatriate workforce enrollment rebounds post-pandemic and MOHAP mandate enforcement tightens compliance-driven premium inflows.
For Market Incumbents: Entrench government contract pipelines through enhanced shariah-compliant product development and real-time claims API connectivity with Dubai Health Authority systems. Digital aggregator encroachment on individual lines demands defensive investment in embedded insurance partnerships with banking platforms. Vertical integration into healthcare provider networks offers sticky retention mechanics against price-based switching.
For New Entrants and Emerging Players: Northern Emirates underpenetration presents the most accessible white-space expansion corridor, with Sharjah and Ras Al Khaimah manufacturing clusters lacking mandatory coverage floors. Parametric coverage convergence using satellite data enables index-based product differentiation without legacy loss-adjustment infrastructure. Direct digital acquisition targeting SME group policies bypasses incumbent broker relationship advantages.
For Investors and Strategic Acquirers: Capital is best deployed toward takaful specialists with compliant product suites and established Northern Emirates distribution licenses. Long-term viability across the analysis window favors carriers with embedded banking partnerships and API-first core systems. Monitor MOHAP mandate expansion timing into Ajman and Fujairah as the key inflection signal for baseline demand floor extension.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Insurance Partnership | Banking platform integration captures policyholders at transaction points, reducing acquisition friction for auto coverage. |
| Core System Modernization | API-first policy administration enables real-time Dubai Health Authority claims submission compliance. |
| Takaful Product Expansion | Shariah-compliant structures align with Abu Dhabi sovereign contract requirements and Emirati national savings initiatives. |
| Parametric Coverage Development | Satellite-triggered index products bypass traditional loss-adjustment costs for property and crop lines. |
| Digital Aggregator Licensing | Direct-to-consumer platforms capture younger demographics in Dubai's commercial districts away from broker channels. |
Research Methodology
Cross-validation between primary fieldwork and regulatory filing analysis anchors the qualitative findings across the UAE insurance landscape. Underwriting executives, actuarial directors, broker network heads, and MOHAP compliance officers provided structured input. Secondary validation drew from UAE Insurance Authority circulars, DHA mandate documentation, ADNIC and Orient Insurance financial disclosures, and SAMA prudential framework updates. Bottom-up policy count estimates triangulate against top-down premium flow analysis from federation-level regulatory aggregates.
Calibration against historical premium growth patterns and mandate implementation timelines shaped the projection framework. Segmentation dimensions span insurance type, product architecture, distribution channel, and customer tier across the modeling period. CAGRs derive from compounding annual adjustments to baseline enrollment figures, expatriate workforce projections, and digital channel penetration curves. Medical cost inflation assumptions and reinsurance renewal pricing cycles feed directly into health and property line forecasts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by insurtech aggregators or regulatory mandate acceleration would shift outcomes materially. Cross-checking against UAE Central Bank insurance sector statistics and DHA enrollment dashboards is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Norway Life and Non-Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
Singapore Life and Non-Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Australia Life and Non-Life Insurance Market
Life and Non Life Insurance
Israel Life and Non-Life Insurance Market
Life and Non Life Insurance
USA Life and Non-Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia Pacific Life & Non-Life Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
Iran Property and Casualty Insurance Market