
 France Life and Non-Life Insurance Market | 2026-2036
France Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
France Life and Non-Life Insurance Market Foresight
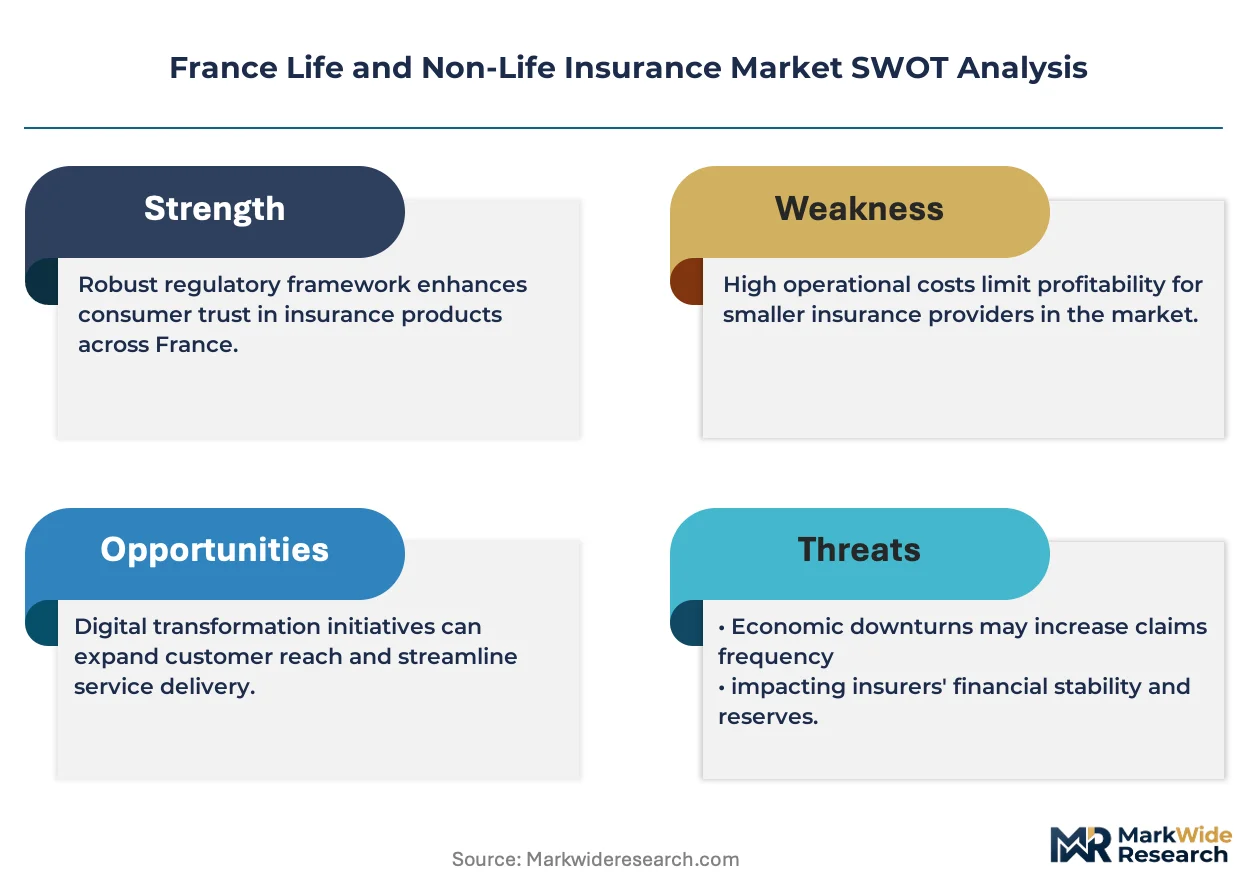
The EU Green Deal is broadening the scope of mandatory climate risk disclosure across French insurance portfolios. Crédit Mutuel Assurances leverages its cooperative structure to dominate mutualist coverage in rural départements. Groupama sustains agricultural risk expertise that anchors its position in climate-vulnerable sectors. Axa France leads commercial property and casualty lines through extensive broker networks.
France life and non-life insurance encompasses risk transfer contracts covering mortality, morbidity, property damage, and liability exposure, with technical provisions calculated through actuarial reserving methods and Solvency II capital requirements. Its primary commercial purpose pools individual and corporate risks to prevent catastrophic financial loss. Term life and health segments within insurance type command stable premium volumes from aging demographics, while bancassurance as a distribution channel retains structural importance through Crédit Agricole Assurances and BPCE Assurances banking affiliations. Online platforms represent the fastest-growing distribution vector as digital onboarding reduces acquisition costs.
ACPR, the French prudential supervisor, enforces Solvency II compliance that dictates capital adequacy and risk management frameworks across all domestic carriers. ANSM and CNIL intersect with insurance operations where health data processing and medical privacy standards constrain product design and claims administration. Stakeholders must monitor how the EU AI Act's algorithmic transparency rules will reshape automated underwriting and pricing models in coming regulatory cycles.
Market Dynamics
The EU Green Deal's mandatory climate risk disclosure requirements are forcing French insurers to rebuild underwriting models around physical and transition risk quantification. Solvency II technical provisions must now incorporate forward-looking climate scenarios, altering capital allocation across property and casualty portfolios.
Growth Catalysts
- Small business regulatory complexity:Rising compliance burdens in labor law and environmental standards drive demand for packaged commercial coverage among French SMEs.
- EU AI Act algorithmic transparency:Automated underwriting system audits create consulting and system upgrade revenue streams for technology-enabled carriers.
- Ile-de-France corporate concentration:Headquarters clustering of CAC 40 firms and asset managers sustains demand for high-limit directors and officers liability coverage.
Market Restraints
- Sovereign bond yield compression:Solvency II eligible own funds rely heavily on French government debt returns, squeezing risk-free rate assumptions in liability valuation.
- Rural mutualist supply concentration:Crédit Mutuel Assurances dominates cooperative coverage in peripheral départements, limiting price competition outside urban broker markets.
- Legacy core system technical debt:Policy administration platforms built on 1990s architectures constrain real-time data integration for parametric product development.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur climate vulnerability:Flood and wildfire risk modeling services present white space as regional property coverage gaps widen.
- Bancassurance digital onboarding:Crédit Agricole Assurances and BPCE Assurances affiliate networks enable embedded insurance at point of lending with reduced acquisition cost.
- CSRD sustainability disclosure alignment:Corporate client demand for insurance-linked ESG data creates advisory service expansion beyond risk transfer.
Industry Challenges
- Actuarial climate scenario expertise:Shortage of professionals capable of integrating NGFS transition pathways into Solvency II ORSA reporting delays product approvals.
- CNIL health data governance:Medical information processing for life and health claims requires consent architecture upgrades that fragment customer journey design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Life and Non-Life Insurance Market |
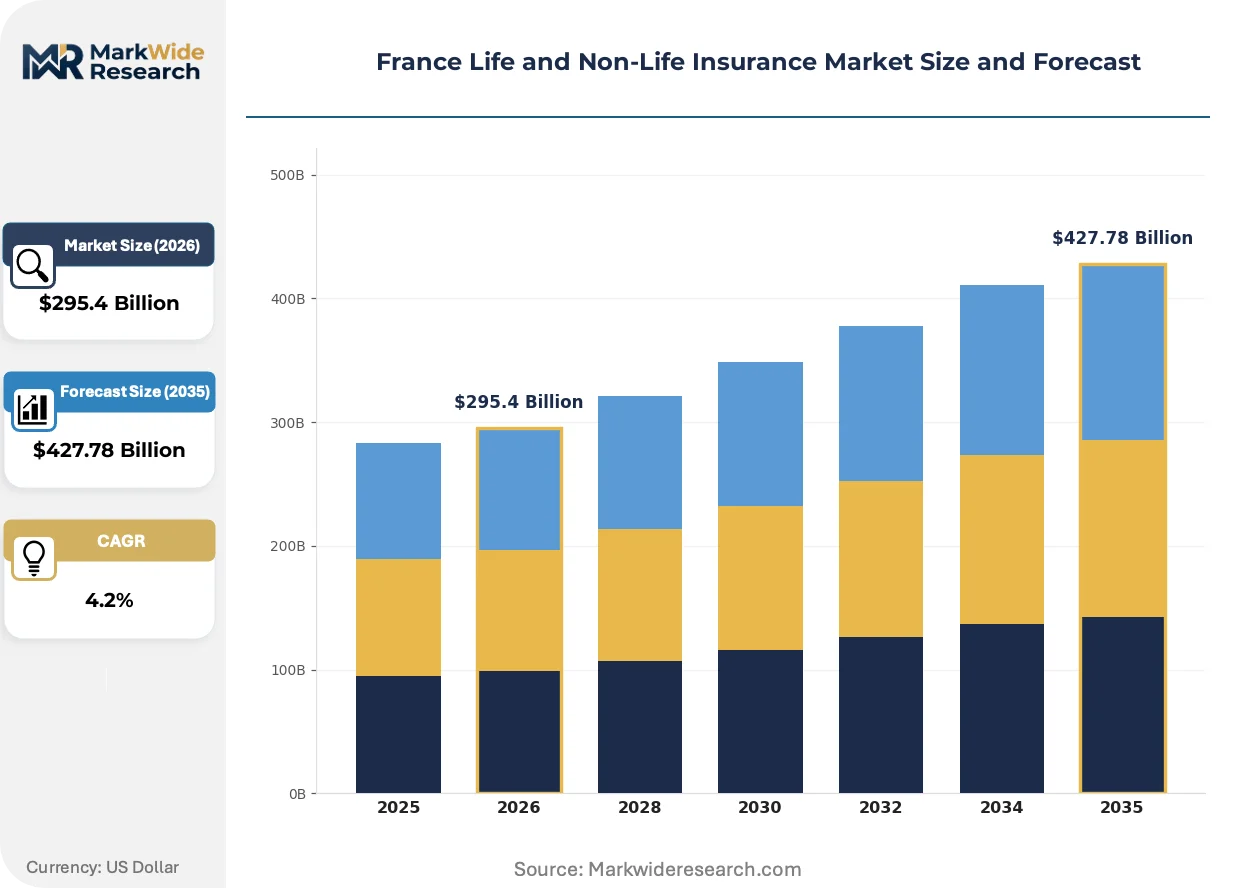
| Market Size in 2026 | $295.4 Billion |
| Market Size in 2035 | $427.78 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
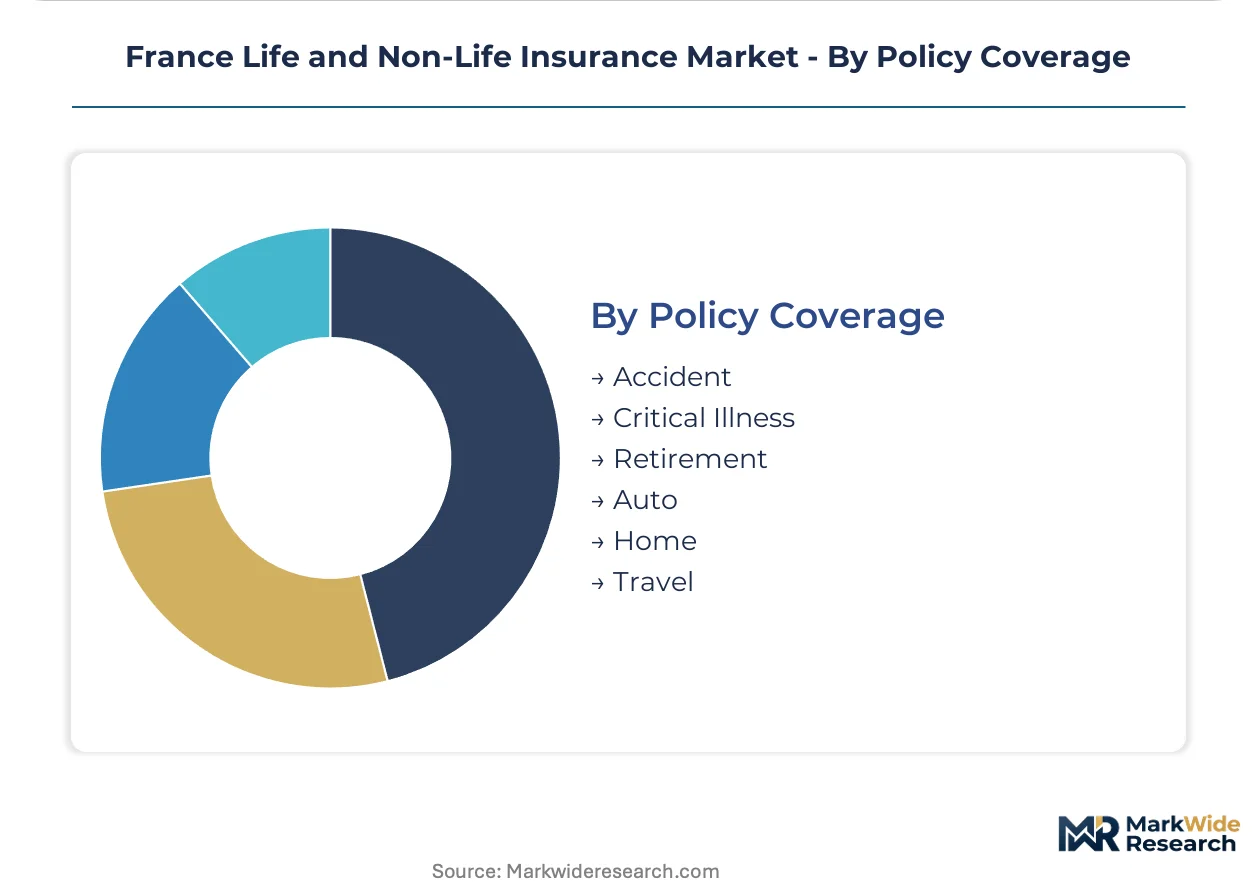
| Segmentation | Insurance Type: Term Life, Whole Life, Health, Property, Casualty, Liability Distribution Channel: Direct Sales, Brokers, Bancassurance, Online Platforms, Agents, Call Centers Customer Type: Individual, Small Business, Large Corporations, Nonprofit Organizations, Freelancers Policy Coverage: Accident, Critical Illness, Retirement, Auto, Home, Travel |
| Companies Covered | Crédit Mutuel Assurances, Groupama, Crédit Agricole Assurances, BNP Paribas Cardif, BPCE Assurances, CNP Assurances, Covéa, Macif, Axa France, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Life and Non-Life Insurance Market Shifts & Advancements
Algorithmic underwriting and sustainability-linked coverage structures are compressing traditional risk assessment timelines while embedding climate metrics into policy terms. French carriers are racing to deploy machine learning tools ahead of EU AI Act enforcement deadlines.
Machine learning models trained on satellite imagery and building permit databases are automating property risk scoring for commercial real estate portfolios. Mid-market brokers in Lyon and Marseille are adopting these tools to quote complex industrial facilities within hours rather than weeks. The compression of manual survey dependencies is reallocating underwriter capacity toward catastrophe model calibration and client advisory functions.
EU AI Act algorithmic transparency mandates will require French insurers to document automated decision logic for pricing and claims adjudication by 2026. ACPR supervisory expectations are already tightening around model governance frameworks, with particular scrutiny of health and motor lines where protected characteristics intersect with risk variables. Carriers are responding by building in-house explainability layers and segregating training data environments.
Digital distribution platforms are capturing share from traditional broker channels as self-service policy configuration tools reduce friction for standardized coverage. Young professionals in urban centers increasingly complete term life and supplemental health purchases without intermediary consultation. This channel rotation is most pronounced in the Grand Est and Occitanie regions where banking branch density has declined sharply.
France Life and Non-Life Insurance Market Segmentation
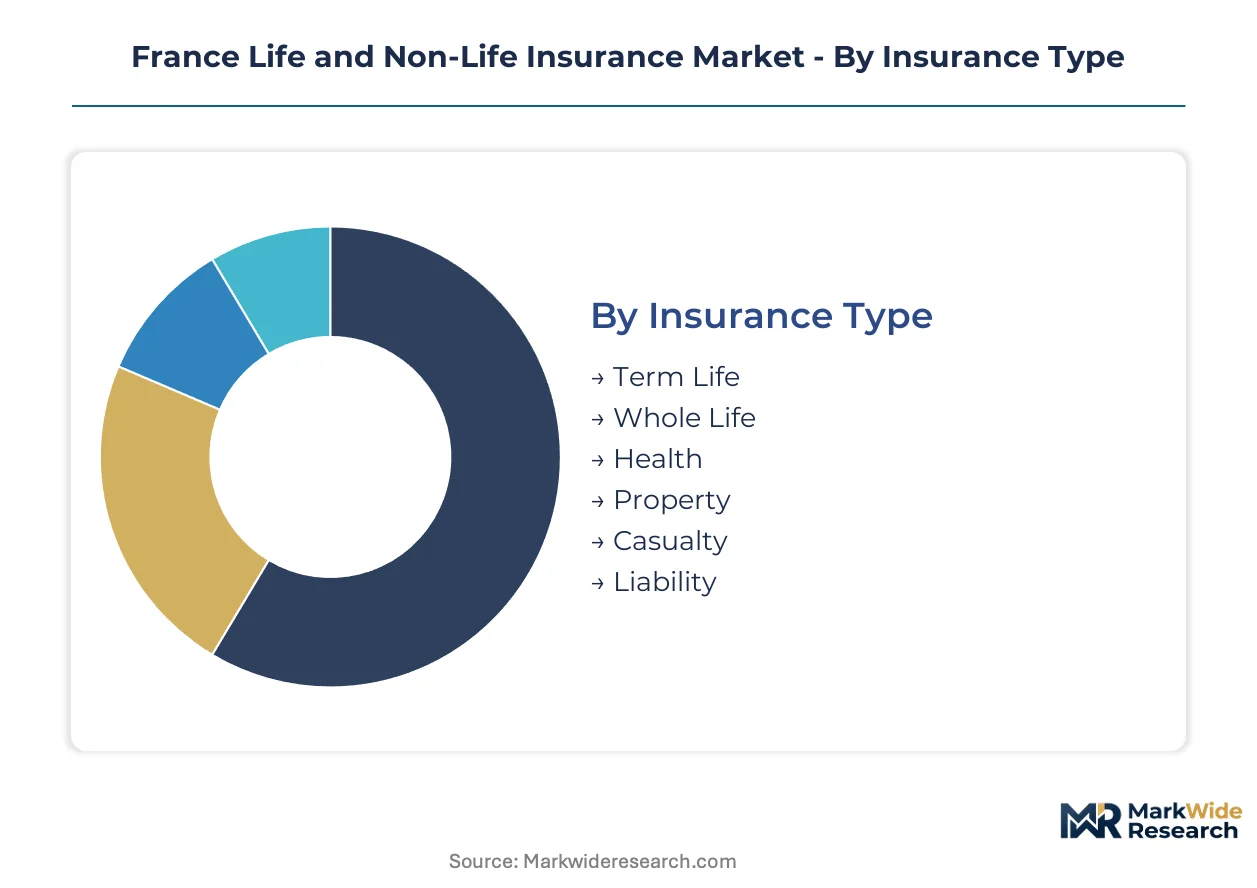
Insurance product design in France varies dramatically across risk transfer mechanisms and distribution economics. Segment boundaries determine capital allocation under Solvency II and shape how ACPR supervisory intensity applies to different carrier portfolios.
Insurance Type:
Standardized mortality tables dominate term products while health and property lines demand bespoke underwriting infrastructure.
- Term Life:Fixed-duration mortality coverage with premiums indexed to INSEE life expectancy tables. Demand concentrates among young professionals in Ile-de-France seeking mortgage protection, constrained by bancassurance bundling that limits price transparency.
- Health:Complementary coverage filling statutory healthcare gaps through mutuelle structures. Enrollment clusters among SME employees in manufacturing-heavy Grand Est, driven by mandatory employer contribution rules and ANSM therapeutic cost inflation.
- Whole Life:Permanent coverage with savings components tied to insurer general fund returns. Axa France and BNP Paribas Cardif dominate distribution through captive banking networks.
- Property:Physical asset protection against fire, flood, and natural catastrophe. Crédit Mutuel Assurances leverages cooperative member data for granular pricing in climate-vulnerable Provence-Alpes-Côte d'Azur.
- Casualty:Third-party liability coverage for professional and personal activities. Groupama sustains agricultural expertise that anchors farm fleet policies.
- Liability:Directors and officers coverage for corporate governance exposure. CAC 40 headquarters concentration in Paris drives demand for high-limit international programs.
Leading the category by volume: Health. Growing fastest: Liability.
Distribution Channel:
Cost-to-acquire spreads determine channel viability across product complexity tiers.
- Bancassurance:Embedded distribution through Crédit Agricole Assurances and BPCE Assurances affiliate networks. Captures term life and property policies at lending origination with minimal marginal acquisition cost.
- Online Platforms:Self-service quotation engines reducing friction for standardized coverage. Young professionals in Lyon and Marseille complete supplemental health purchases without intermediary consultation, though CNIL consent architecture fragments onboarding flows.
- Brokers:Independent intermediaries placing complex commercial risks. Axa France maintains extensive broker relationships for corporate property and casualty placement.
- Direct Sales:Carrier-employed representatives targeting affinity groups and employer-sponsored programs.
- Agents:Tied representatives with exclusive territorial appointments, concentrated in rural départements where branch density has declined.
- Call Centers:Outbound and inbound telemarketing for renewal retention and cross-selling campaigns.
Dominant by premium volume: Bancassurance. Expanding most quickly: Online Platforms.
Customer Type:
Risk pooling efficiency varies with account size and data availability for underwriting.
- Individual:Retail policyholders purchasing protection for mortality, health, and personal asset exposure. Aging demographics in Nouvelle-Aquitaine sustain stable premium flows for long-term care riders.
- Small Business:SMEs seeking packaged commercial coverage for property, liability, and employee benefits. Rising labor law and environmental compliance burdens in Occitanie drive demand for integrated risk transfer solutions.
- Large Corporations:CAC 40 firms and mid-caps requiring international program structures and captive fronting. Ile-de-France headquarters clustering sustains demand for sophisticated risk financing.
- Freelancers:Self-employed professionals needing portable coverage outside employer-sponsored pools.
- Nonprofit Organizations:Associations and foundations with specialized governance and volunteer liability exposures.
Largest premium contributor: Individual. Steepest expansion trajectory: Small Business.
Policy Coverage:
Frequency-severity profiles dictate reserving methodology and reinsurance placement strategy.
- Auto:Motor third-party liability and own-damage coverage. Telematics adoption is accelerating in urban centers, though legacy core systems constrain real-time data integration for usage-based pricing.
- Home:Residential property protection against named perils. Flood risk modeling gaps in Provence-Alpes-Côte d'Azur create coverage availability constraints.
- Accident:Fixed-benefit coverage for bodily injury events regardless of fault. Groupama and Macif dominate through mutualist distribution.
- Critical Illness:Lump-sum payment upon diagnosis of specified conditions. ANSM therapeutic innovation timelines complicate benefit definition updates.
- Retirement:Annuity and drawdown products for post-employment income. Sovereign bond yield compression squeezes guaranteed return assumptions.
- Travel:Short-duration coverage for medical evacuation and trip cancellation. Online platforms capture share through embedded booking site partnerships.
Highest policy count: Auto. Gaining share fastest: Critical Illness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors French insurance activity through CAC 40 headquarters concentration and high-net-worth individual clustering in Ile-de-France. The metropolitan area generates disproportionate demand for sophisticated liability and property coverage. Regional variation across France reflects demographic aging, climate exposure, and cooperative banking network density.
Ile-de-France
Corporate headquarters clustering drives demand for directors and officers liability coverage among CAC 40 firms and asset managers. ACPR supervisory intensity concentrates here given systemic importance of Paris-based carriers. La Défense business district sustains broker networks placing complex international programs for multinationals.
Auvergne-Rhône-Alpes
Lyon's manufacturing base generates commercial property and casualty demand from industrial facilities. EU AI Act algorithmic transparency requirements are prompting technology upgrades among regional underwriters. The Grenoble-Annecy corridor attracts insurtech startups developing satellite-based risk scoring tools.
Provence-Alpes-Côte d'Azur
Flood and wildfire exposure is widening property coverage gaps as climate risk models strain. ANSM therapeutic cost inflation drives health mutuelle enrollment among service sector employees. Nice-Marseille urban corridor sees accelerating telematics adoption in auto lines despite legacy system constraints.
Nouvelle-Aquitaine
Aging demographics in rural départements sustain stable premium flows for long-term care riders. Crédit Mutuel Assurances dominates cooperative coverage through member data advantages. Bordeaux's wine industry anchors specialized agricultural risk transfer expertise.
Occitanie
Rising labor law and environmental compliance burdens drive SME demand for packaged commercial coverage. Toulouse's aerospace cluster generates specialized liability and property requirements. Digital distribution platforms capture share as banking branch density declines in peripheral zones.
France Life and Non-Life Insurance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across distribution channel sophistication and risk selection capability. The French market exhibits tiered concentration with mutualist cooperatives dominating rural coverage and listed carriers controlling commercial lines in metropolitan centers. Three archetypes prevail: banking-affiliated bancassurance specialists, mutualist cooperatives with member-data advantages, and broker-oriented commercial lines leaders. Consolidation pressure is accelerating through technology investment requirements and Solvency II compliance costs.
Within the cooperative tier, Crédit Mutuel Assurances and Groupama exemplify member-owned structures that leverage granular local data for pricing in climate-vulnerable regions. Axa France occupies a position on the broker-facing commercial vector, anchoring high-limit property and casualty placement through intermediary relationships. These three carriers represent distinct competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| Crédit Mutuel Assurances |
| Groupama |
| Crédit Agricole Assurances |
| BNP Paribas Cardif |
| BPCE Assurances |
| CNP Assurances |
| Covéa |
| Macif |
| Axa France |
| Others |
Supply & Pricing Matrix
Actuarial labor costs in Paris and Lyon flow through Solvency II technical provision calculations into premium tiers for commercial property and casualty lines. Axa France and broker networks translate these specialized underwriting expenses into value-based pricing for CAC 40 directors and officers liability programs.
Pricing Analysis
Value-based pricing anchored to claims outcome predictability dominates French commercial lines, with premiums scaling to historical loss ratios and forward-looking climate risk exposure. Price differentiation rests on Solvency II capital charge tiering and geographic concentration of insured assets, with Ile-de-France corporate headquarters commanding premium multiples over peripheral département coverage. Pricing pressure stems from sovereign bond yield compression squeezing risk-free rate assumptions in liability valuation. Small business buyers in Occitanie exhibit highest price sensitivity due to regulatory compliance cost stacking, while CAC 40 risk managers prioritize coverage breadth over premium minimization.
Supply Chain Analysis
Reverse-logistics flows for policy documentation and claims evidence move through Crédit Mutuel Assurances cooperative networks and Axa France broker channels back to centralized ACPR reporting repositories. Geographic supply concentration draws from France, Belgium, and Luxembourg for reinsurance capacity and actuarial talent pools. Raw material dependencies include mortality table data from INSEE, satellite imagery for property risk scoring, and medical cost benchmarks from ANSM therapeutic databases. Single-source vulnerability concentrates in legacy core system vendors maintaining 1990s policy administration architectures. Distribution runs through bancassurance affiliate networks, independent broker relationships, and direct digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
French carriers face a vertical-integration race to capture algorithmic underwriting capabilities and climate risk modeling expertise before EU AI Act enforcement tightens. Backward integration into proprietary data assets and forward integration into advisory services represent the critical levers.
For Market Incumbents: Deepen captive data advantages by acquiring satellite imagery analytics capabilities and building in-house NGFS scenario modeling teams. Defend mutualist market share in Provence-Alpes-Côte d'Azur through granular flood risk databases that generic competitors cannot replicate. Solvency II compliance cost escalation threatens smaller cooperative carriers, creating consolidation opportunities for well-capitalized players. For New Entrants and Emerging Players: Embedded insurance APIs at point of lending through Crédit Agricole Assurances and BPCE Assurances affiliate networks offer the lowest-friction customer acquisition route. White space concentrates in parametric climate coverage for Provence-Alpes-Côte d'Azur wine producers and aerospace suppliers in Occitanie. Target SME commercial packages in Grand Est manufacturing corridors where legacy broker relationships have weakened. For Investors and Strategic Acquirers: ACPR approval of machine learning models for health and motor lines is the leading indicator that algorithmic underwriting capabilities have achieved regulatory defensibility. Long-term viability favors carriers with proprietary climate risk datasets and explainable AI governance frameworks already operational. Acquisition targets should display in-house actuarial climate expertise and established CNIL-compliant consent architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Climate Risk Model Development | NGFS scenario integration enables Solvency II ORSA compliance ahead of regulatory deadlines. |
| Digital Onboarding Platform Launch | Self-service policy configuration reduces acquisition costs for standardized term life coverage. |
| Reinsurance Partnership Restructuring | Alternative capital from Luxembourg structures diversifies peak catastrophe exposure. |
| Mutualist Network Consolidation | Member data advantages in rural départements create pricing moats against urban brokers. |
| EU AI Act Compliance Program | Explainable AI layers satisfy ACPR model governance expectations for automated underwriting. |
Research Methodology
Independent corroboration across ACPR supervisory filings, ANSM therapeutic cost databases, and INSEE demographic projections underwrites the qualitative findings in this study. Primary interviews with chief actuaries, risk modelers at Ile-de-France carriers, and broker network heads in Lyon and Marseille combined with secondary validation from Solvency II public disclosure reports and EU Green Deal regulatory texts. Bottom-up premium volume estimates triangulate against top-down macroeconomic indicators and sectoral employment data.
Rate-of-change decomposition across insurance type, distribution channel, and customer type dimensions structures the analytical framework. CAGRs derive from segmented growth trajectory modeling incorporating aging demographic shifts, regulatory compliance burden expansion, and climate risk disclosure mandates. Industry-specific forecast inputs include INSEE life expectancy table revisions, CNIL consent architecture implementation timelines, and ACPR model governance expectation tightening.
The model holds under stable Solvency II capital requirement regimes and gradual sovereign bond yield normalization; deviation in acute climate catastrophe frequency or abrupt regulatory timeline acceleration would shift premium growth trajectories. Practitioners should monitor ACPR circulars on algorithmic transparency and ANSM therapeutic innovation cost indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
South Korea Life & Non-Life Insurance Market
Life and Non Life Insurance
Asia Life and Non-Life Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market
Life and Non Life Insurance
UAE Life and Annuity Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
Poland Life and Non-Life Insurance Market
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
Colombia Life and Non-Life Insurance Market
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
Life Reinsurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Czech Republic Life & Non-Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market