
 Predictive Analytics in Banking Market | 2026-2036
Predictive Analytics in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Predictive Analytics in Banking Market Outlook
Retail banking is broadening its share of predictive analytics deployment as institutions automate loan origination and churn prediction. DataRobot leverages cloud-native architecture to serve mid-tier banks with limited in-house data science teams. SAS Viya anchors enterprise-grade deployments across North American financial institutions with deep regulatory reporting integration. IBM SPSS Modeler competes in legacy environments where banks prioritize statistical interpretability over black-box neural methods.
Predictive analytics in banking encompasses statistical and machine learning techniques applied to structured transaction data, unstructured customer communications, and macroeconomic indicators to forecast credit default probability, fraudulent transaction patterns, and lifetime customer value. These systems typically process batch and streaming data through feature engineering pipelines that transform raw account activity into risk scores with sub-second inference latency for payment authorization. Fraud detection applications command the largest current revenue pool due to real-time infrastructure requirements and regulatory liability for unauthorized transactions. Machine learning technology is expanding fastest as gradient-boosted frameworks and transformer architectures displace traditional logistic regression in production environments. Customer insights solutions sit at the margin premium tier where banks pay for psychographic segmentation models that link digital behavior to product propensity.
The Federal Reserve's model risk management guidance (SR 11-7) and the European Banking Authority's expectations for AI governance create compliance burdens that favor vendors with documented validation frameworks. GDPR and the EU AI Act restrict automated decision-making for credit and insurance products, forcing banks to maintain human-in-the-loop architectures and explainability modules. Stakeholders must monitor how divergent supervisory approaches between the US prudential framework and European risk-based regulation affect vendor certification requirements and cross-border deployment feasibility.
Market Dynamics
Open banking mandates and real-time payment infrastructure are compressing decision windows from days to milliseconds, forcing banks to rebuild analytics stacks around streaming inference rather than batch scoring.
Growth Catalysts
- SR 11-7 model risk guidance:US prudential regulators mandate documented validation pipelines, creating procurement pull for vendors with pre-built compliance frameworks.
- Gradient-boosted machine learning:XGBoost and LightGBM implementations deliver superior predictive accuracy on tabular credit data versus legacy logistic regression.
- Real-time payment networks:FedNow and SEPA Instant Credit Transfer require sub-second fraud scoring, driving infrastructure refresh cycles.
Market Restraints
- GPU compute cost volatility:Training transformer-based models for customer insights segments requires sustained cloud expenditure that mid-tier banks cannot absorb.
- EU AI Act automated decision restrictions:Credit and insurance scoring systems face human-in-the-loop mandates that increase operational overhead and latency.
- Legacy core banking integration:COBOL-based transaction engines lack API-native interfaces, forcing expensive middleware layers for streaming data ingestion.
Strategic Opportunities
- Embedded finance partnerships:Non-bank platforms in India and Brazil seek white-label credit decisioning APIs, opening distribution beyond traditional branch networks.
- Climate risk stress testing:ECB and Bank of England supervisory expectations create demand for predictive models linking loan portfolios to transition and physical risk scenarios.
- Federated learning architectures:Privacy-preserving techniques enable cross-institutional model training without raw data sharing, unlocking consortia approaches previously blocked by GDPR.
Industry Challenges
- MLOps talent scarcity:Production-grade feature engineering and model monitoring require skill sets concentrated at technology firms, not traditional financial services.
- Explainability tooling gaps:SHAP and LIME implementations for transformer models remain computationally expensive, complicating regulatory audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Predictive Analytics in Banking Market |
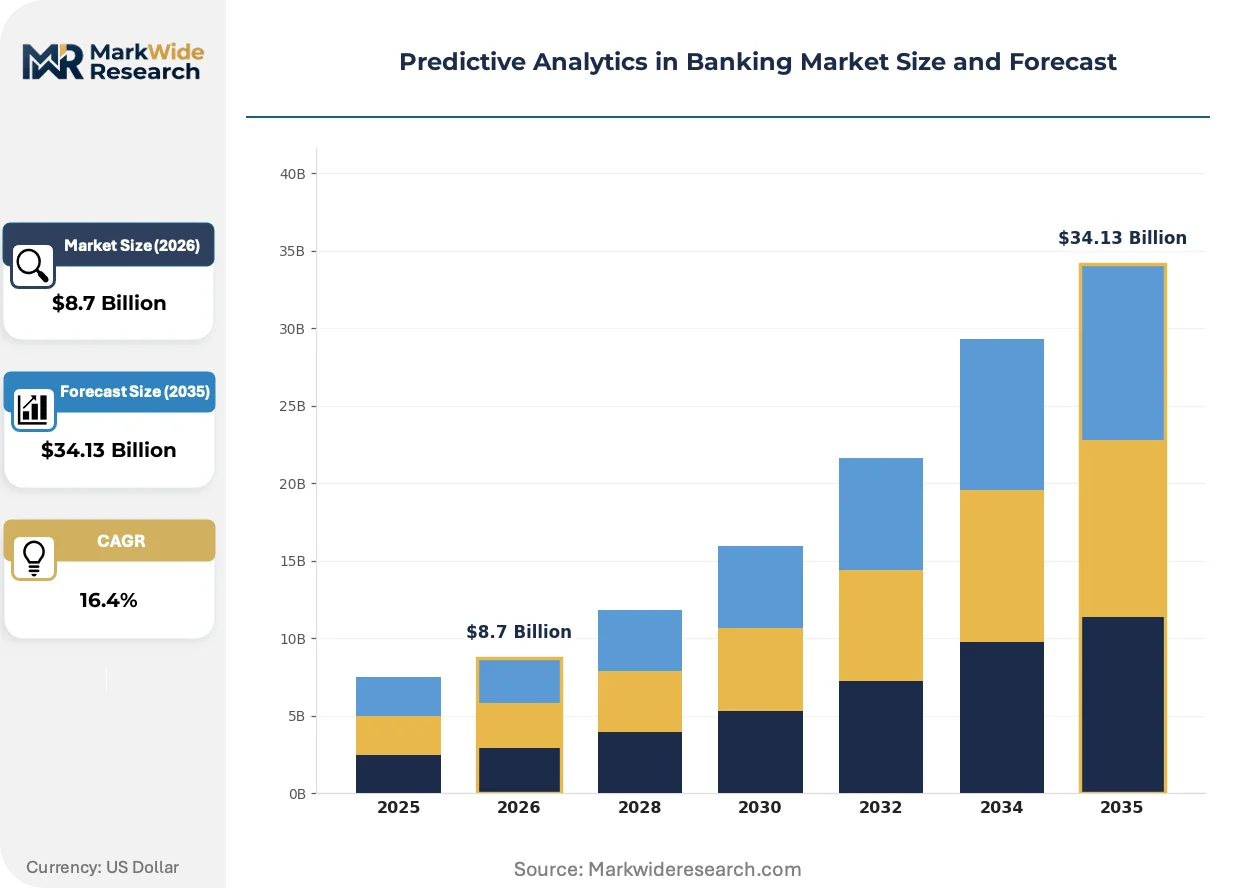
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Risk Management, Credit Scoring, Fraud Detection, Customer Segmentation Technology: Machine Learning, Data Mining, Artificial Intelligence, Big Data End User: Retail Banks, Investment Banks, Credit Unions, Online Lenders Solution: Predictive Modeling, Customer Insights, Transaction Monitoring, Compliance Analytics |
| Companies Covered | Algoscale, Wildnet Edge, DataRobot, Vention, InData Labs, SAS Viya, RapidMiner, Exadel, IBM SPSS Modeler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Predictive Analytics in Banking Market Strategic Shifts
Transformer architectures originally developed for natural language processing are migrating into transaction sequence modeling, while regulatory divergence between Washington and Brussels forces dual-track compliance investments.
Transformer-based sequence models are electrifying fraud detection by capturing long-range dependencies across account activity timelines that gradient-boosted trees miss. Tier-1 US banks deploy these architectures for authorized push payment fraud, compressing false positive rates while maintaining sub-100ms inference latency. The shift is electrifying competitive positioning in real-time payment corridors where latency and accuracy trade-offs determine customer attrition.
The EU AI Act's risk-based classification system imposes conformity assessment requirements on credit scoring algorithms deemed high-risk, forcing banks to maintain technical documentation and human oversight protocols. US institutions face no equivalent federal mandate, creating asymmetrical compliance burdens for cross-border operators. European banks are responding by embedding explainability modules earlier in development pipelines, increasing time-to-production for new models.
Buyers are consolidating vendor relationships around full-stack platforms that unify data engineering, model development, and regulatory reporting. Mid-tier institutions previously stitched together point solutions from multiple providers now favor integrated suites with pre-built connectors to core banking systems. This consolidation is most visible in the United States, where regional banks face pressure to match the real-time capabilities of money-center competitors without comparable IT headcount.
Predictive Analytics in Banking Market Segmentation

Banking institutions deploy predictive analytics through layered architectures where standalone systems serve specialized functions and embedded modules integrate into core transaction engines. Segmentation clarity determines procurement strategy, vendor selection, and compliance pathway alignment.
Application:
Fraud Detection operates as the deepest integration layer, embedding directly into payment authorization streams with sub-second latency requirements. Credit Scoring and Risk Management function in hybrid modes, supporting both batch portfolio reviews and real-time origination decisions. Customer Segmentation typically remains standalone, feeding marketing automation platforms without touching transactional infrastructure.
- Fraud Detection:Real-time scoring engines analyze transaction velocity, device fingerprints, and behavioral biometrics to block authorized push payment fraud before settlement. Tier-1 US banks and European payment processors drive infrastructure spending here, constrained by regulatory liability for unauthorized transactions and FedNow latency mandates.
- Credit Scoring:Gradient-boosted models evaluate default probability from structured bureau data and alternative digital footprints, deployed at loan origination and portfolio monitoring stages. Demand concentrates among online lenders in India and Brazil seeking automated decisioning for thin-file borrowers, though EU AI Act human-in-the-loop requirements add operational friction.
- Risk Management:Stress testing and concentration risk analytics for regulatory capital calculations.
- Customer Segmentation:Psychographic clustering for product propensity and churn prediction.
Volume placements concentrate in Fraud Detection; the faster expansion belongs to Credit Scoring.
Technology:
Technology selection tracks computational cost curves and regulatory explainability demands. Machine Learning dominates production deployments, while Big Data infrastructure enables the underlying feature pipelines.
- Machine Learning:XGBoost and LightGBM frameworks deliver superior accuracy on tabular banking data, displacing logistic regression in credit and fraud applications. US regional banks and European institutions prioritize these implementations for their balance of performance and interpretability, though GPU training costs strain mid-tier budgets.
- Artificial Intelligence:Transformer architectures sequence transaction histories to capture long-range dependencies in account behavior, deployed for authorized push payment fraud by money-center banks. Inference latency requirements and cloud compute volatility limit adoption outside the largest institutions.
- Data Mining:Pattern discovery in unstructured customer communications and alternative data sources.
- Big Data:Distributed processing infrastructure for feature engineering at scale.
Deployment density peaks with Machine Learning; Artificial Intelligence claims the steepest expansion trajectory.
End User:
Institutional type determines integration complexity, regulatory exposure, and vendor relationship structure. Retail banks present the largest addressable base, while online lenders drive growth in embedded finance distribution.
- Retail Banks:Full-stack deployments spanning fraud, credit, and customer analytics with deep core banking integration. Large US commercial banks and European universal banks anchor procurement volumes, modernizing COBOL-based transaction engines through expensive middleware layers to enable streaming inference.
- Online Lenders:Cloud-native, API-first implementations prioritizing speed-to-decision over legacy system compatibility. Brazilian fintechs and Indian non-bank financial companies represent the fastest-growing demand pool, seeking white-label credit decisioning for embedded finance partnerships.
- Investment Banks:Counterparty risk and trading analytics for capital markets operations.
- Credit Unions:Constrained deployments focused on member retention and basic fraud prevention.
Procurement scale concentrates with Retail Banks; Online Lenders are gaining share fastest.
Solution:
Solution packaging reflects buyer consolidation around integrated platforms versus point-solution stitching. Predictive Modeling anchors most deployments, while Compliance Analytics responds to divergent supervisory frameworks.
- Predictive Modeling:Core statistical and machine learning infrastructure for scorecard development, validation, and monitoring. North American financial institutions favor vendors with pre-built SR 11-7 compliance frameworks, while European banks prioritize explainability modules for EU AI Act conformity assessments.
- Compliance Analytics:Automated regulatory reporting, model risk documentation, and audit trail generation. Cross-border operators in the US and European Union face asymmetrical requirements, forcing dual-track investments in validation pipelines and human-in-the-loop architectures.
- Customer Insights:Psychographic segmentation and lifetime value modeling for marketing optimization.
- Transaction Monitoring:Real-time surveillance for anti-money laundering and sanctions screening.
Revenue concentration sits with Predictive Modeling; Compliance Analytics shows the quickest climb.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for financial technology in Singapore and Dubai are concentrating predictive analytics infrastructure investment. Tax incentives for AI R&D in these jurisdictions pull vendor operations and bank technology centers away from traditional Western headquarters locations.
United States
Money-center banks in New York and San Francisco drive real-time payment fraud detection spending. The Federal Reserve's SR 11-7 model risk guidance mandates documented validation pipelines. Charlotte anchors regional bank modernization efforts as institutions rebuild COBOL-based cores for streaming inference.
United Kingdom
London's fintech cluster demands embedded finance APIs for non-bank credit decisioning. The Bank of England's climate risk stress testing expectations create procurement pull for transition risk models. The Manchester-Leeds corridor hosts mid-tier bank technology centers modernizing legacy infrastructure.
Germany
Frankfurt's universal banks face ECB supervisory expectations for AI governance in credit scoring. The EU AI Act's high-risk system classification forces human-in-the-loop architectures. Munich anchors InsurTech crossover demand as bancassurance groups unify analytics stacks.
India
Mumbai and Bangalore anchor non-bank financial company demand for thin-file credit decisioning. RBI open banking guidelines expand data portability for alternative scoring models. The Hyderabad fintech cluster specializes in white-label lending APIs for embedded finance partnerships.
Brazil
São Paulo's digital banks and fintechs drive cloud-native credit scoring deployment. Central Bank of Brazil Pix instant payment infrastructure mandates real-time fraud detection. The Rio de Janeiro-Florianópolis corridor concentrates data science talent for gradient-boosted model development.
Predictive Analytics in Banking Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with full-stack platforms capturing procurement consolidation among mid-tier banks while point-solution vendors defend niches in regulatory reporting. The vendor base arranges into three tiers: enterprise suites with pre-built compliance frameworks, cloud-native challengers serving online lenders, and legacy statistical tools maintaining presence in interpretability-sensitive environments. Competitive moves concentrate on M&A for MLOps talent acquisition and strategic partnerships with core banking modernization providers.
Among enterprise-grade analytics providers, DataRobot exemplifies the cloud-native archetype targeting institutions with limited in-house data science capacity. SAS Viya occupies a position within the regulatory-integrated tier, anchoring North American financial institution deployments with deep compliance reporting functionality. IBM SPSS Modeler represents the interpretability-focused segment where statistical transparency outweighs neural network performance.
| Leading Market Players |
|---|
| Algoscale |
| Wildnet Edge |
| DataRobot |
| Vention |
| InData Labs |
| SAS Viya |
| RapidMiner |
| Exadel |
| IBM SPSS Modeler |
| Others |
Value Chain & Pricing Dynamics
Cloud compute spot price indices cascade through predictive analytics vendor pricing tiers, compressing margins for GPU-dependent model training while rewarding CPU-optimized inference architectures with pricing stability across mid-tier bank procurement cycles.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent deployment premiums from standard SaaS subscription tiers, with FedNow compliance deadlines commanding implementation surcharges. Pricing stratifies across enterprise-grade platforms with pre-built SR 11-7 frameworks, mid-market cloud-native suites, and open-source toolkits requiring heavy customization. GPU training cost volatility is intensifying because transformer model development demands sustained cloud expenditure. Online lenders in Brazil and India exhibit highest price sensitivity, while US money-center banks prioritize latency guarantees over license fees.
Supply Chain Analysis
Dual-sourcing requirements from tier-1 US banks mandate multi-cloud qualification across AWS, Azure, and Google Cloud Platform for resilience against regional outages. Compute infrastructure concentrates in the United States, Ireland, and Singapore, drawing from NVIDIA GPU silicon, high-bandwidth memory modules, and specialized AI accelerators. Single-source vulnerability in advanced semiconductor fabrication threatens model training capacity. Distribution runs through direct enterprise sales teams for large institutions and API marketplaces for embedded finance partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive analytics in banking has become a vertical-integration race, with vendors pursuing downstream control over core banking modernization partnerships to lock in streaming inference deployment.
For Market Incumbents: Anchor compliance-integrated platform positions by acquiring MLOps talent pools concentrated in technology hubs, defending against cloud-native challengers eroding mid-market share. Deepen embedded finance API distribution through white-label partnerships with Brazilian and Indian non-bank platforms, securing origination volume outside traditional branch networks. For New Entrants and Emerging Players: The premium-to-economy pricing gap in explainability tooling offers entry points for SHAP-optimized lightweight implementations targeting European banks facing EU AI Act audit requirements. Focus initial penetration on credit unions and regional banks in the US Southeast lacking in-house data science capacity, selling through channel partners with existing core banking relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor federated learning specialists in Germany and France, where GDPR constraints and ECB supervisory expectations create acquisition targets with privacy-preserving IP. Monitor central bank instant payment infrastructure rollout velocity as the inflection signal for fraud detection hardware refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| MLOps Talent Acquisition | Production-grade feature engineering capabilities anchor competitive differentiation against cloud-native challengers. |
| Federated Learning Partnership | Privacy-preserving architectures unlock cross-institutional model training previously blocked by GDPR data sharing restrictions. |
| Core Banking Modernization Alliance | Streaming inference deployment requires API-native interfaces replacing COBOL-based transaction engines. |
| Embedded Finance API Launch | White-label credit decisioning opens distribution channels beyond traditional branch networks in India and Brazil. |
| Climate Risk Model Development | ECB and Bank of England supervisory expectations create procurement pull for transition risk analytics. |
Study Parameters
Document review covered SEC 10-K filings from publicly traded financial institutions, vendor financial disclosures, and regulatory guidance documents from the Federal Reserve and European Banking Authority, complemented by interviews with chief risk officers, model validation leads, and procurement directors at tier-1 and regional banks. Primary fieldwork included discussions with MLOps engineers at cloud service providers and integration specialists at core banking modernization firms. Secondary validation drew from FFIEC call report data, ECB statistical releases, and trade association technology spending surveys. Bottom-up segmentation analysis triangulated against top-down market sizing from banking IT expenditure benchmarks.
Segment-level revenue estimates were produced across deployment models, institutional tiers, application types, and regulatory framework clusters, with CAGRs derived from technology adoption curves and infrastructure replacement cycles. Model inputs incorporated FedNow and SEPA Instant payment network expansion timelines, GPU compute cost trajectories, and divergence between US prudential and European risk-based supervision approaches throughout the projection horizon.
Inputs from vendor financial disclosures and regulatory filings were available through the study window; gaps in private fintech expenditure data introduce uncertainty bands around online lender segment estimates. Forecasts reflect assumptions regarding open banking mandate implementation pace and central bank instant payment adoption curves. Deviation in EU AI Act enforcement intensity or Federal Reserve SR 11-7 guidance expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Germany Neobanking Market
Banking
Europe Machine Learning in Banking Market
Banking
Cybersecurity in Banking Market
Banking
Bank Management Software Market
Banking
Japan Trade Finance Market
Banking
US Retail Banking Market
Banking
Banking-As-A-Service (Baas) Platform Market
Banking
Virtual Teller Machine (VTM) Market
Banking
UK Retail Banking Market
Banking
China Retail Banking System Market
Banking
Global Chatbot for Banking Market
Banking
Global IoT in Banking and Financial Services Market
Banking
China Data Analytics in Banking Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
Asia-Pacific Islamic Finance Market
Banking
Data Analytics in Banking Market