
 Teenager Life Insurance Market | 2026-2036
Teenager Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Teenager Life Insurance Market Insights
Agent networks is reconfiguring how teenager life insurance reaches households, blending in-person trust-building with digital quoting tools. Allianz leverages its bancassurance partnerships across European retail banking channels to sustain premium flow from family-oriented products. MetLife anchors its competitive stance through employer-sponsored juvenile coverage programs that extend group benefits to dependents.
Teenager life insurance constitutes a risk-transfer contract where an insurer pays a death benefit upon the covered minor's passing, with policies typically featuring guaranteed insurability riders and convertible term structures that lock in future coverage without medical requalification. The primary commercial purpose centers on protecting families against funeral expenses and securing lifelong affordable premiums through early-age entry. Whole life policies dominate the policy type segment due to their cash-value accumulation and parental preference for guaranteed outcomes, while online platforms within the distribution channel segment represent the fastest-growing structural pocket as insurtech platforms reduce friction for digitally native parents. Term life maintains a mature position among budget-conscious buyers seeking pure protection without savings components.
FDA oversight of digital health data integration, state insurance commissioner rate approvals, and HIPAA privacy frameworks collectively shape product design and distribution compliance for teenager life insurance in the United States. China's NMPA and SAMR monitor health data usage in underwriting algorithms, while India's IRDAI mandates solvency reserves and disclosure standards for juvenile policy sales. Stakeholders must monitor how generative AI in underwriting affects regulatory scrutiny of age-based risk classification.
Market Dynamics
Digital underwriting platforms are compressing policy issuance timelines from weeks to minutes, fundamentally restructuring how insurers acquire teenage policyholders and reshaping distribution economics across the value chain.
Growth Catalysts
- Guaranteed Insurability Riders:Convertible term structures allow parents to lock in lifelong coverage without future medical requalification, removing underwriting friction for families with hereditary health conditions.
- HIPAA Privacy Frameworks:Streamlined health data consent protocols enable insurers to access pediatric medical records for accelerated risk assessment while maintaining parental control over sensitive information.
- Employer-Sponsored Juvenile Programs:Group benefit extensions to dependent coverage create automated enrollment pathways that capture families during open enrollment periods without individual solicitation.
Market Restraints
- State Insurance Commissioner Rate Approvals:Prior authorization requirements for premium adjustments create pricing rigidity that prevents rapid response to mortality table improvements or investment yield fluctuations.
- Funeral Cost Inflation Volatility:Cemetery and mortuary service price unpredictability complicates benefit adequacy calculations for whole life products with fixed face amounts.
- Agent Network Concentration:Distribution dependence on licensed producers in suburban and rural ZIP codes limits penetration in underbanked urban corridors where digital literacy outpaces insurance access.
Strategic Opportunities
- Embedded Distribution via Pediatric Care:Partnerships with children's hospitals and family practice networks create policy touchpoints during well-child visits, capturing parents at moments of heightened mortality awareness.
- India's IRDAI Juvenile Disclosure Standards:Mandated transparency in policy illustrations creates competitive differentiation for insurers with superior lapse-rate histories and guaranteed crediting rates.
- Convergence of Wearables and Underwriting:Integration of adolescent fitness trackers with accelerated underwriting algorithms enables preferred risk classification for active teenagers without invasive medical exams.
Industry Challenges
- Actuarial Talent Scarcity:Specialized expertise in juvenile mortality modeling and pediatric morbidity forecasting remains concentrated among legacy insurers, constraining product innovation at newer entrants.
- Legacy Policy Administration Systems:Core platform architectures designed for adult life products require expensive modification to accommodate minor beneficiary designations, custodial account structures, and age-triggered conversion features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Teenager Life Insurance Market |
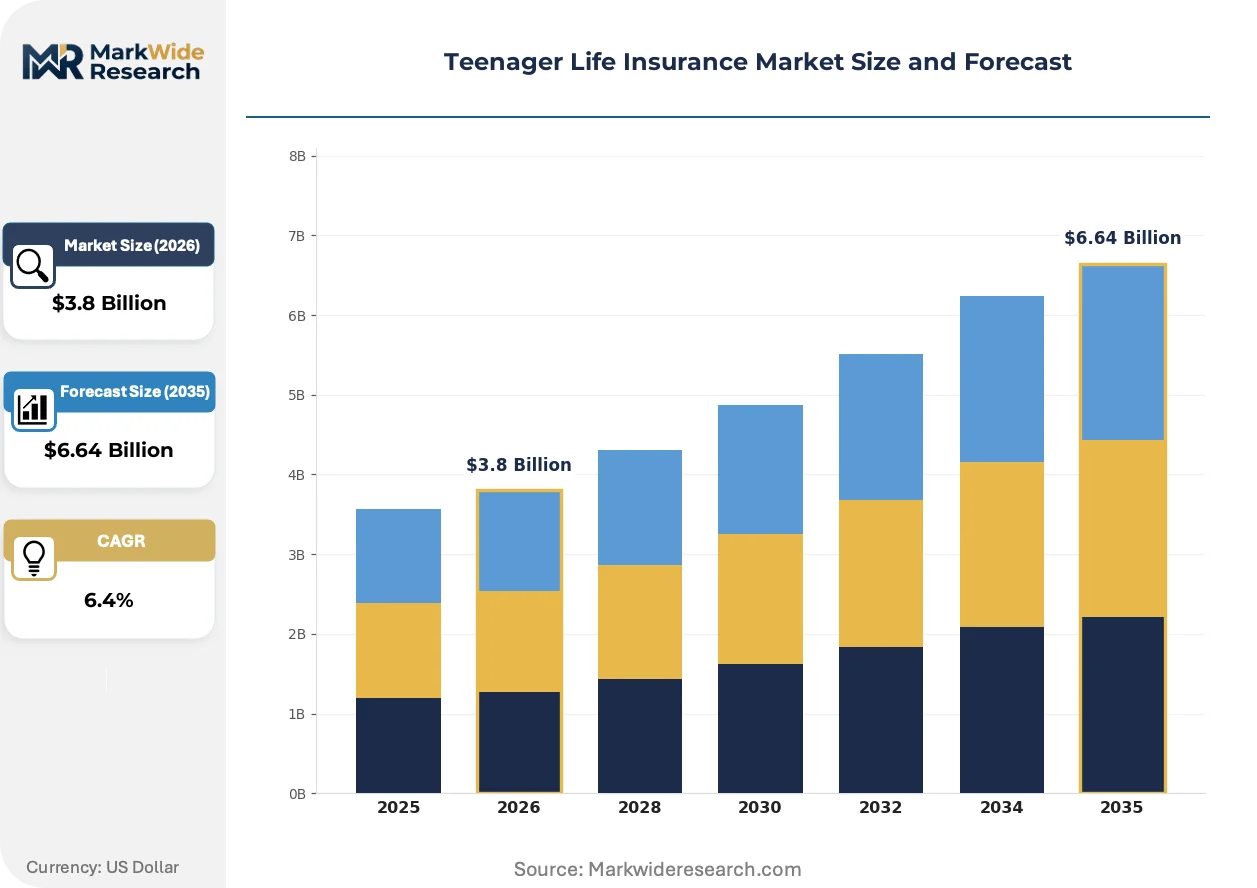
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Term Life, Whole Life, Universal Life, Variable Life, Indexed Universal Life Distribution Channel: Direct Sales, Brokers, Bancassurance, Online Platforms, Agent Networks Premium Payment Frequency: Monthly, Quarterly, Semi-Annual, Annual, Single Payment End User: Dependent Teens, Students, Young Athletes, Part-Time Workers, Early Working Professionals |
| Companies Covered | Allianz, Assicurazioni Generali, China Life Insurance, MetLife, PingAn, AXA, Sumitomo Life Insurance, Aegon, Dai-ichi Mutual Life Insurance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Teenager Life Insurance Market Trends and Innovations
Artificial intelligence and behavioral data analytics are reconfiguring risk selection protocols, while regulatory bodies across multiple jurisdictions impose algorithmic accountability requirements that constrain automated decision-making latitude.
Telematics-enabled health monitoring is digitizing the traditional paramedical examination. Wearable devices capture continuous biometric signals from adolescent policyholders, enabling dynamic risk scoring that adjusts premiums based on verified physical activity patterns. Insurtech platforms are integrating these data streams with electronic health record APIs, collapsing underwriting cycles from days to minutes while expanding the addressable market to parents who delay purchase due to perceived administrative burden.
China's NMPA and SAMR are tightening oversight of health data usage in underwriting algorithms, requiring explicit consent protocols and prohibiting certain predictive variables from automated scoring models. Insurers operating in this jurisdiction must now maintain dual underwriting tracks—algorithmic for compliant data subsets and manual review for restricted categories. This bifurcation increases operational complexity but creates competitive moats for carriers with established compliance infrastructure.
Millennial and Generation Z parents are abandoning traditional agent-mediated purchase pathways in favor of direct-to-consumer digital platforms with transparent pricing and self-service policy management. This channel migration compresses distribution margins and eliminates the relationship-based selling that historically explained policy persistency. The shift is most pronounced in coastal metropolitan markets where smartphone penetration and financial app usage exceed national baselines by substantial margins.
Teenager Life Insurance Market Segmentation
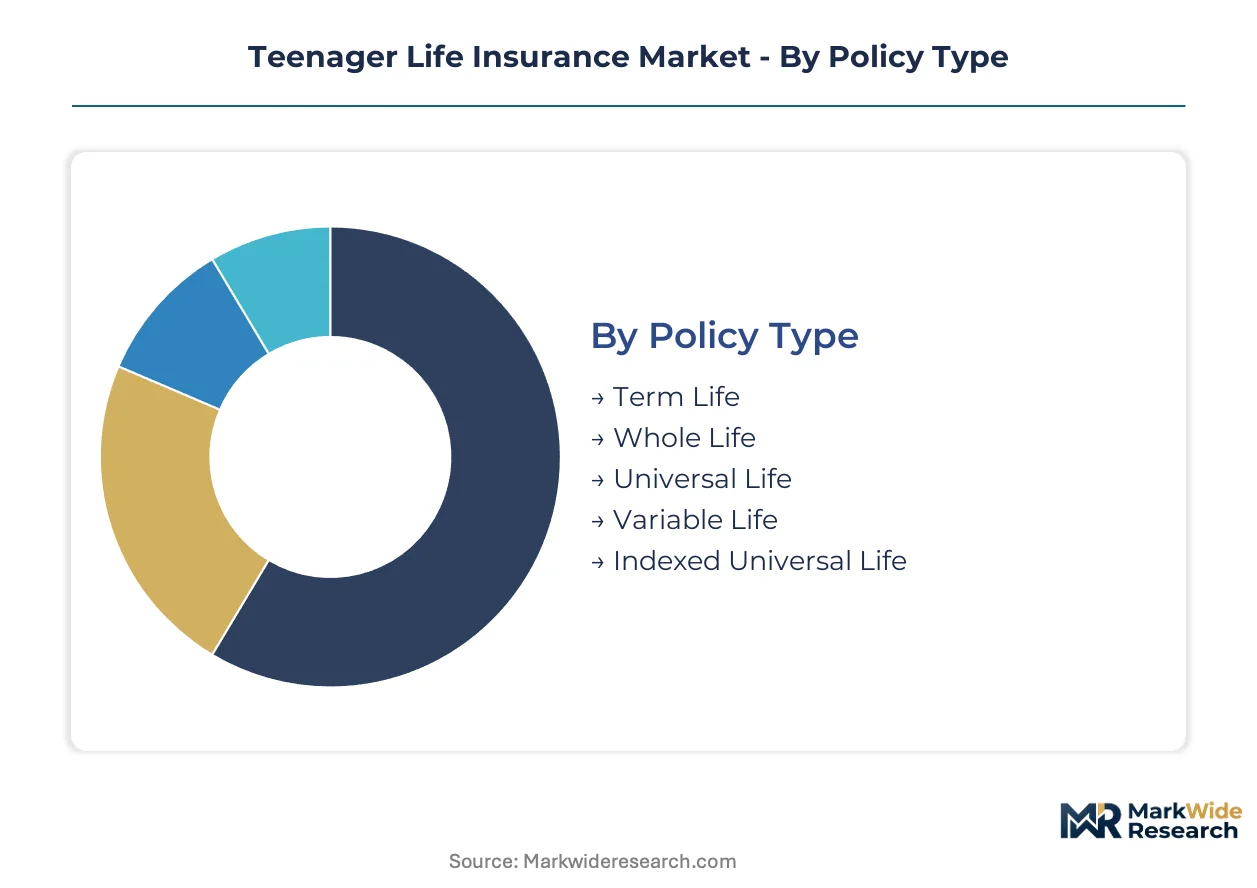
Segmentation in teenager life insurance reveals how product architecture, distribution economics, and buyer circumstances intersect. Policy structures vary dramatically in cash-value mechanics and premium flexibility. Distribution channels are fragmenting as digital-native parents abandon traditional agent relationships.
Policy Type:
Cost tier differentiation separates products designed for pure protection from those bundling savings components with mortality coverage.
- Whole Life:Permanent coverage with guaranteed death benefit and fixed premiums builds cash value through insurer-held reserves. Parental preference concentrates in suburban United States households seeking predictable outcomes for college funding bridges.
- Term Life:Temporary coverage spanning 10-30 years delivers maximum death benefit per premium dollar. Budget-conscious buyers in India and China favor this structure for funeral expense protection without savings overhead.
- Universal Life:Flexible premium schedules and adjustable death benefits accommodate income volatility among gig-economy families.
- Variable Life:Cash value tied to separate investment accounts exposes policyholders to market fluctuation.
- Indexed Universal Life:Crediting rates linked to equity index performance with downside floors appeals to risk-moderate parents.
Whole Life commands the established base. The steepest expansion runs through Indexed Universal Life.
Distribution Channel:
Application context determines channel selection—employer enrollment periods, banking relationships, or independent research moments.
- Online Platforms:Direct-to-consumer quoting engines with algorithmic underwriting compress purchase cycles from weeks to minutes. Millennial parents in coastal United States metros and Tier-1 Chinese cities gravitate toward self-service policy management without agent intermediation.
- Agent Networks:Licensed producers provide trust-based guidance for complex rider selections and conversion timing decisions. Rural ZIP codes in India and suburban United States counties retain dependence on face-to-face consultation.
- Bancassurance:Retail banking partnerships embed product offers within checking account workflows and mortgage closing packages.
- Brokers:Independent intermediaries compare carrier offerings across multiple insurers for price-sensitive buyers.
- Direct Sales:Carrier-owned sales forces target employer-sponsored juvenile programs and affinity group contracts.
Agent Networks retain the largest policy count. Online Platforms are climbing the fastest.
Premium Payment Frequency:
Volume concentration varies by household cash flow predictability and administrative cost tolerance.
- Monthly:Automated bank drafts align with salary cycles for working parents managing tight budgets. This frequency dominates among part-time worker households in United States urban corridors.
- Annual:Single lump-sum payments eliminate processing fees and reduce lapse risk through precommitment. Affluent families in China and India prefer this structure for whole life policies.
- Quarterly:Intermediate frequency balances administrative burden with cash flow smoothing.
- Semi-Annual:Twice-yearly payments reduce transaction costs for policyholders with seasonal income patterns.
- Single Payment:Fully prepaid policies eliminate future premium obligations and maximize cash value accumulation.
Annual payment structures anchor the mature book. Monthly billing is gaining share fastest.
End User:
Customer type segmentation isolates mortality risk profiles and coverage motivation differences across adolescent life stages.
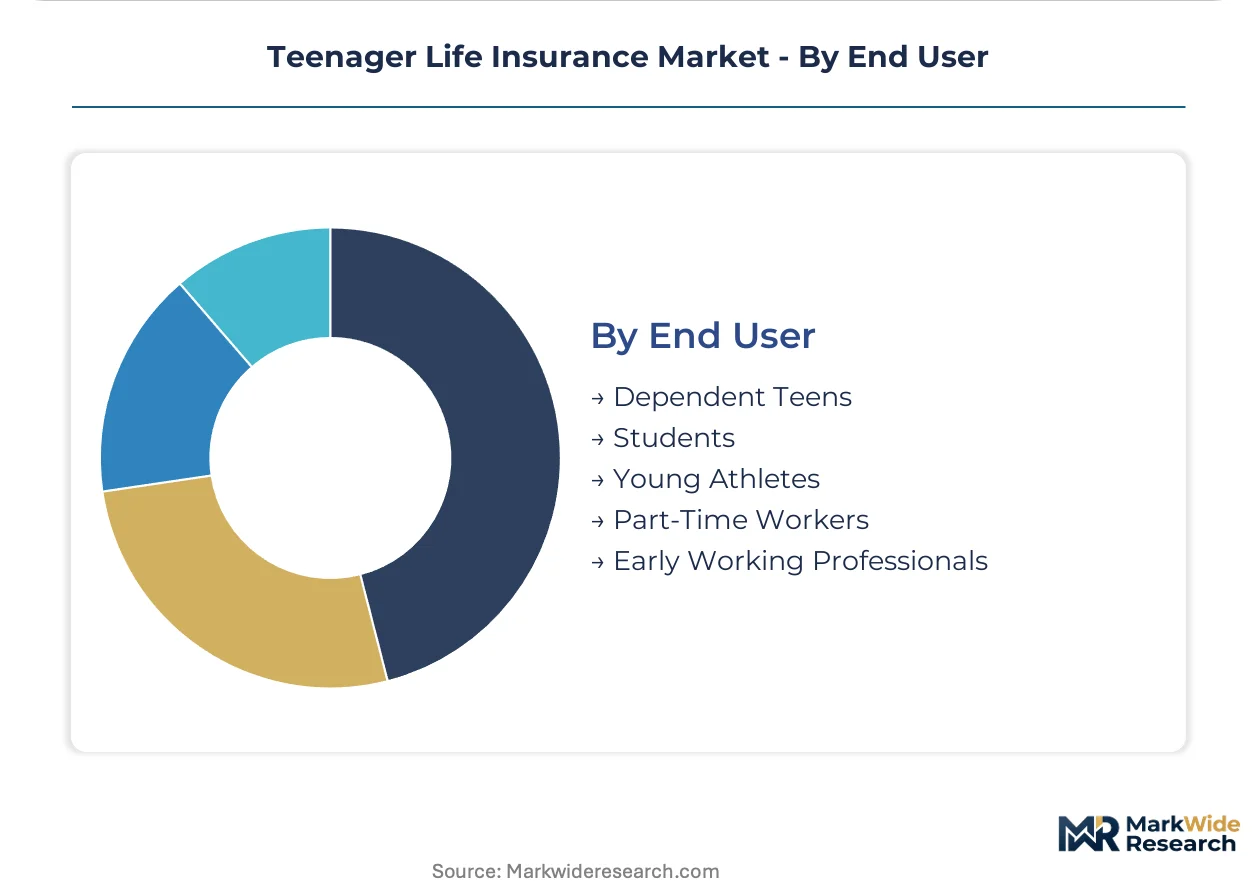
- Dependent Teens:Non-working minors covered under parental policies represent the core market volume. Parents purchasing for this segment in the United States, China, and India drive premium flow through guaranteed insurability riders.
- Young Athletes:Organized sports participants carry elevated accidental death exposure that specialized riders address. Youth leagues in the United States and school athletic programs in India generate concentrated demand.
- Students:College-bound adolescents with education loans prompt creditor-protection motivated purchases.
- Part-Time Workers:Employed teenagers with independent income streams qualify for simplified issue products.
- Early Working Professionals:Young adults transitioning from dependent status seek convertible coverage without medical requalification.
Dependent Teens holds the policy base. Young Athletes shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level premium tax incentives and federal estate tax portability rules in the United States have accelerated parental purchases of juvenile whole life policies. China's dual carbon goals indirectly pressure insurers to digitize underwriting infrastructure, reducing paper-based policy issuance timelines. India's IRDAI juvenile disclosure mandates create transparency arbitrage for carriers with superior lapse-rate histories.
United States
Employer-sponsored juvenile coverage programs at Fortune 500 firms drive automated enrollment during open enrollment periods. HIPAA privacy frameworks enable accelerated underwriting through pediatric medical record access with parental consent. Suburban counties in Texas and Florida concentrate agent network activity for guaranteed insurability rider sales.
China
NMPA and SAMR oversight of health data usage in underwriting algorithms bifurcates carrier operations into algorithmic and manual review tracks. Tier-1 cities including Shanghai and Beijing show highest digital platform adoption among millennial parents seeking direct-to-consumer purchase pathways. Bancassurance partnerships with state-owned banks sustain premium flow in lower-tier cities.
India
IRDAI-mandated solvency reserves and juvenile policy disclosure standards differentiate carriers on guaranteed crediting rate transparency. Maharashtra and Gujarat host concentrated agent network penetration for funeral expense-focused term products. Digital underwriting platforms in Bangalore and Hyderabad reduce policy issuance friction for tech-sector parents.
Germany
Allianz leverages bancassurance distribution through Sparkasse and Volksbanken retail channels for family-oriented product placement. BaFin supervision of insurance intermediaries ensures standardized advice protocols for juvenile policy sales. Munich and Frankfurt anchor product development for convertible term structures with guaranteed insurability features.
Japan
Sumitomo Life Insurance and Dai-ichi Mutual Life Insurance compete through agency channel dominance in prefectures with aging demographic profiles. FSA guidelines on suitability standards govern sales practices for policies covering adolescent dependents. Tokyo and Osaka metropolitan areas concentrate demand for whole life products with education-funding cash value accumulation.
Teenager Life Insurance Market Competitive Landscape
On the supply side, the industry is tiered between multinational composite carriers with bancassurance scale, mutual life insurers with agency channel depth, and emerging insurtech platforms with algorithmic underwriting capabilities. Strategic archetypes include: integrated financial conglomerates leveraging banking relationships, mutual insurers with policyholder-owned capital structures, and venture-backed digital distributors with API-first architectures. Competitive moves concentrate on embedded distribution partnerships with pediatric care networks and wearable-enabled dynamic risk scoring capabilities.
Within the multinational composite tier, Allianz and AXA exemplify bancassurance-driven distribution models spanning European and Asian retail banking channels. MetLife anchors the employer-sponsored juvenile coverage segment through group benefit extensions to dependent populations. China Life Insurance and PingAn occupy positions at the state-backed scale end, leveraging domestic bank distribution and regulatory alignment with NMPA data governance frameworks.
| Leading Market Players |
|---|
| Allianz |
| Assicurazioni Generali |
| China Life Insurance |
| MetLife |
| PingAn |
| AXA |
| Sumitomo Life Insurance |
| Aegon |
| Dai-ichi Mutual Life Insurance |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in algorithmic underwriting talent across India and China compresses policy issuance timelines while elevating pricing power for carriers with established digital infrastructure. This utilization squeeze forces insurers to prioritize premium-mid-economy pricing differentiation over pure rate competition.
Pricing Analysis
Volume-discount tiering structures separate annual premium commitments from monthly billing cycles, with lump-sum payments eliminating processing overhead for affluent parents in China and India. Price differentiation hinges on guaranteed insurability rider bundling and cash-value accumulation guarantees. Cost compression in term life products is intensifying because digital platforms collapse distribution margins. Budget-conscious buyers in Indian urban corridors exhibit highest price sensitivity, while suburban United States households purchasing whole life show lowest elasticity.
Supply Chain Analysis
Tariff exposure between United States and China on cloud computing infrastructure complicates cross-border data hosting for underwriting platforms. Supply concentrates in the United States, China, and India for actuarial modeling services and pediatric mortality data. Raw material dependencies include electronic health record APIs, wearable biometric sensors, and algorithmic scoring engines. Single-source vulnerability in legacy policy administration systems constrains product innovation. Distribution runs through bancassurance partnerships, employer-sponsored enrollment pathways, and direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity abounds as millennial and Generation Z parents abandon agent-mediated purchase pathways, creating white-space niches for digitally native carriers with transparent pricing architectures.
For Market Incumbents: Entrench algorithmic underwriting capabilities through backward integration into wearable data partnerships and electronic health record API access. Defend against insurtech entrants by locking in exclusive bancassurance distribution with European retail banking networks. Prioritize capacity addition in Tier-1 Chinese cities where digital platform adoption outpaces legacy agent coverage. For New Entrants and Emerging Players: Establish a beachhead in employer-sponsored juvenile coverage programs, the most penetrable segment given automated enrollment pathways during open enrollment periods. Target underbanked urban corridors in India where digital literacy exceeds insurance access. Deploy API-first architectures enabling self-service policy management without agent intermediation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among carriers with guaranteed insurability rider attachment rates exceeding industry baselines. Long-term viability favors mutual insurers with policyholder-owned capital structures and superior lapse-rate histories. The signal to watch is regulatory scrutiny of generative AI in age-based risk classification, which could bifurcate carrier operations into compliant and non-compliant tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Care Network Partnership | Embedded distribution at children's hospitals captures parents during well-child visits with heightened mortality awareness. |
| Wearable-Enabled Dynamic Underwriting | Integration of adolescent fitness trackers with accelerated algorithms enables preferred risk classification without invasive exams. |
| Guaranteed Insurability Rider Expansion | Convertible term structures lock in lifelong coverage for families with hereditary health conditions, removing underwriting friction. |
| Legacy System Modernization | Core platform upgrades accommodate minor beneficiary designations and age-triggered conversion features. |
| IRDAI Compliance Infrastructure | Mandated juvenile disclosure standards create transparency arbitrage for carriers with superior lapse-rate histories. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with product development executives, actuarial modeling directors, bancassurance partnership leads, and pediatric care network administrators; and secondary validation through IRDAI solvency filings, HIPAA privacy framework documentation, NMPA algorithmic oversight guidelines, and SEC insurance holding company disclosures. Bottom-up policy issuance volume estimates triangulated against top-down premium flow projections.
Forecast inputs considered policy type segmentation, distribution channel migration patterns, premium payment frequency shifts, and end-user mortality risk profiles across the projection horizon. CAGRs were derived from fitted growth curves accounting for digital platform penetration rates and guaranteed insurability rider attachment trends. Juvenile mortality table improvements and investment yield fluctuations anchored sensitivity analyses.
Stress conditions across funeral cost inflation volatility, agent network concentration in rural ZIP codes, and regulatory bifurcation of algorithmic underwriting tracks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on parental purchase motivation and digital adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Finland Life and Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
USA Life and Non-Life Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
Children Life Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Life Reinsurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Russia Life and Non-Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
Germany Life and Non-Life Insurance Market
Life and Non Life Insurance
Brazil Life and Non-Life Insurance Market
Life and Non Life Insurance
France Life and Non-Life Insurance Market