
 Czech Republic Life & Non-Life Insurance Market | 2026-2036
Czech Republic Life & Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Czech Republic Life & Non-Life Insurance Market Insights
Unit-linked and index-linked product financing is reshaping how Czech insurers compete for long-term savings flows. Generali Česká pojišťovna leverages its bancassurance network to dominate retail distribution. Kooperativa pojišťovna anchors commercial lines through its entrenched SME relationships. ČSOB Pojišťovna positions its digital platform to capture younger policyholders shifting away from traditional agent channels.
Czech Republic Life & Non-Life Insurance encompasses risk transfer contracts where life segments provide mortality and savings-linked benefits through term, whole, universal, and endowment structures, while non-life segments indemnify against property damage, liability, health, and travel contingencies. The product mix spans guaranteed-return traditional policies and variable-return unit-linked contracts tied to capital market performance. Term life and endowment products lead premium volume among life offerings, while health and property coverage command the largest non-life premium pools. Online platforms represent the fastest-growing distribution vector as direct-to-consumer digital onboarding reduces acquisition costs.
The Czech National Bank enforces Solvency II-derived capital adequacy rules that mandate risk-based reserving and granular disclosure, compressing margins for thinly capitalized underwriters. Česká podnikatelská pojišťovna navigates these requirements through selective risk ceding to reinsurance panels. EU-wide Insurance Distribution Directive standards govern product suitability and cross-border selling permissions. Stakeholders must monitor how forthcoming sustainability disclosure obligations under the EU Green Deal will force integration of climate risk into Czech property and casualty pricing models.
Market Dynamics
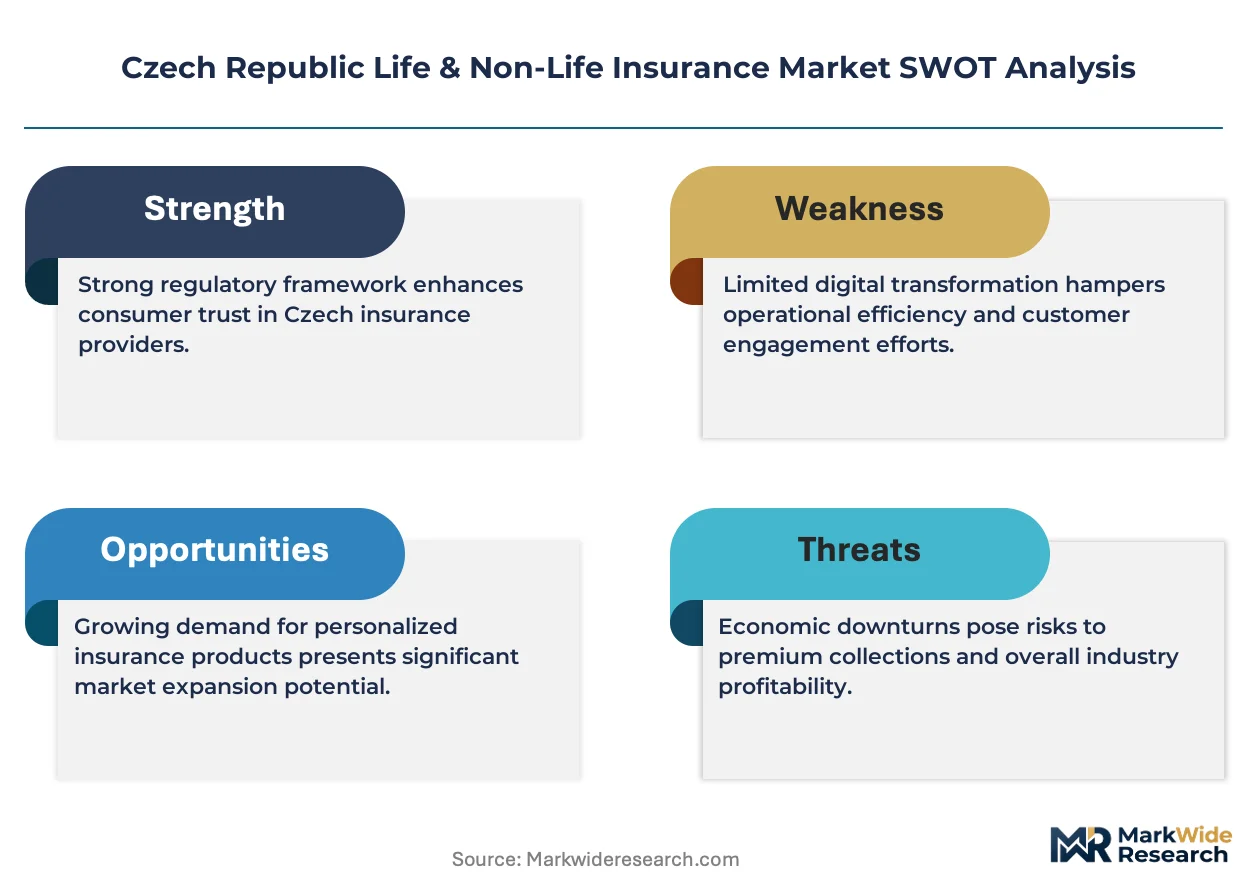
Solvency II-aligned capital requirements from the Czech National Bank are compressing margins for thinly capitalized domestic underwriters while accelerating consolidation among mid-tier insurers.
Growth Catalysts
- Bancassurance expansion:Strategic partnerships between insurers and Czech banking networks unlock captive retail distribution channels for unit-linked savings products.
- SME commercial coverage growth:Manufacturing clusters in South Moravia and Plzeň generate escalating demand for property and liability protection as export volumes rise.
- EU Green Deal integration:Sustainability disclosure mandates are forcing climate risk modeling into property and casualty pricing, creating new advisory revenue streams.
Market Restraints
- Low interest rate environment:Persistently suppressed yields on government bonds constrain guaranteed-return product profitability and force reserve strengthening.
- Reinsurance capacity concentration:Heavy reliance on Munich and London-based reinsurance panels exposes Czech underwriters to hardening global treaty terms.
- Demographic headwinds:Aging population dynamics shrink the addressable market for traditional term life products while lengthening annuity liabilities.
Strategic Opportunities
- Digital platform penetration:Direct-to-consumer onboarding via mobile applications captures younger policyholders abandoning traditional agent relationships.
- Embedded insurance partnerships:Integration with automotive and real estate transaction platforms creates frictionless distribution at point of sale.
- Preventive health services:Wearable data partnerships enable dynamic pricing models in health insurance, aligning premiums with behavioral outcomes.
Industry Challenges
- Legacy system modernization:Core policy administration platforms require substantial capital replacement to support real-time digital service delivery.
- Actuarial talent scarcity:Competition with fintech and banking sectors limits recruitment of quantitative risk professionals in Prague and Brno.
- Interoperability friction:Integration between proprietary insurer databases and national healthcare registries delays claims automation initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Czech Republic Life & Non-Life Insurance Market |
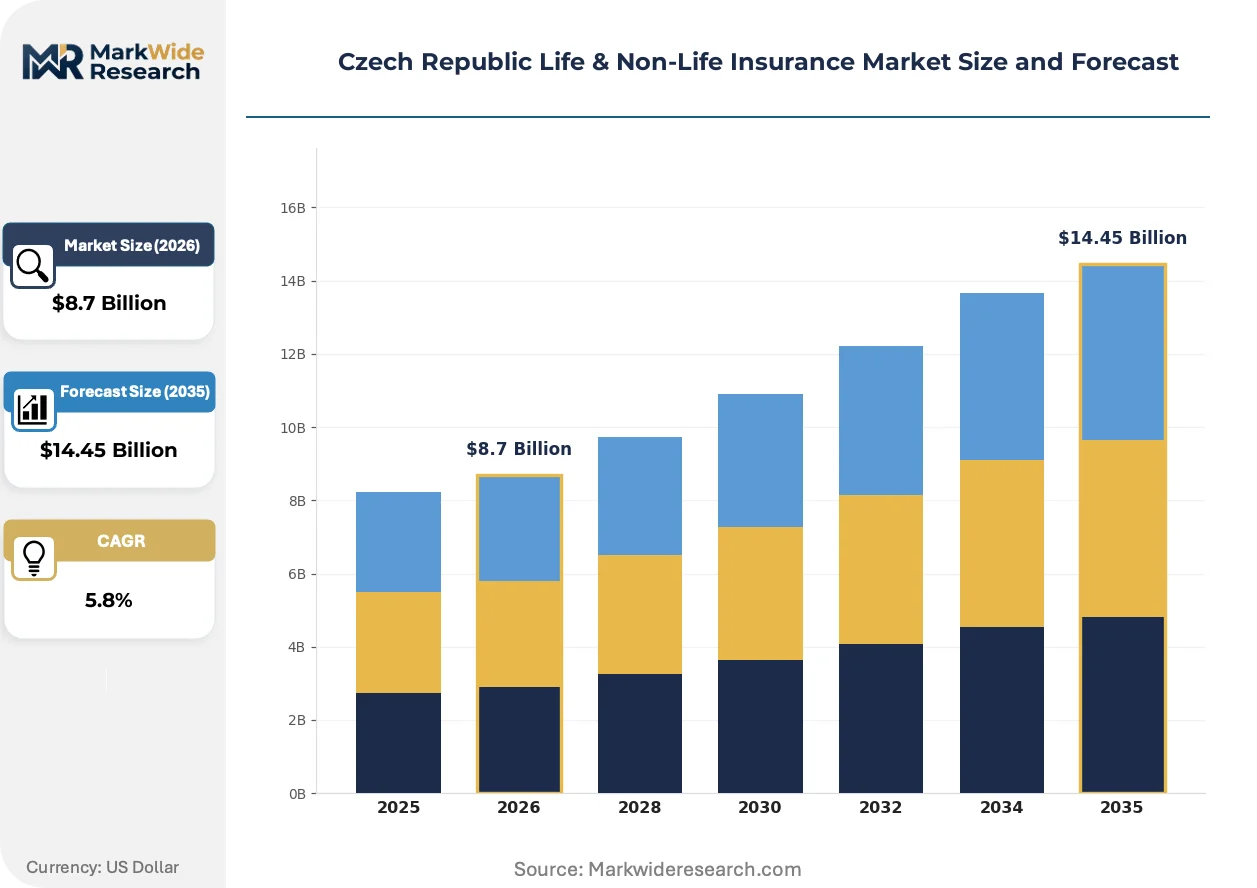
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Term Life, Whole Life, Universal Life, Endowment Coverage Type: Health Insurance, Property Insurance, Liability Insurance, Travel Insurance Distribution Channel: Direct Sales, Brokers, Banks, Online Platforms Customer Type: Individual Clients, Families, Corporates, SMEs |
| Companies Covered | Kooperativa pojišťovna, Česká podnikatelská pojišťovna, Generali Česká pojišťovna, Allianz pojišťovna, Česká pojišťovna, UNIQA pojišťovna, ČSOB Pojišťovna, ERGO pojišťovna, AXA pojišťovna, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Czech Republic Life & Non-Life Insurance Market Trends and Innovations
Unit-linked product architecture and digital distribution infrastructure are converging to reshape competitive positioning across Czech retail and commercial lines.
Artificial intelligence-driven underwriting engines are hybridizing traditional risk assessment with real-time behavioral data streams. Mid-sized Czech insurers are deploying these tools to compress quote-to-bind timelines from days to minutes. The technology is hybridizing price discovery mechanisms, enabling dynamic tariff adjustments that erode static pricing advantages held by incumbent players with legacy actuarial workflows.
The Czech National Bank's implementation of Solvency II-derived reporting standards mandates granular asset-liability matching disclosures. This regulatory architecture forces smaller domestic underwriters to either consolidate or cede disproportionate premium volumes to reinsurance panels. Commercial property lines face the steepest compliance cost escalation as climate stress testing becomes mandatory for regulatory approval.
Younger policyholders are migrating toward self-service digital channels for routine policy management and claims initiation. Traditional agent networks in Prague and regional cities are losing share to insurer-owned mobile applications and comparison aggregators. This behavioral pivot is most pronounced among consumers under 35 purchasing motor and travel coverage, where price transparency tools have collapsed information asymmetries.
Czech Republic Life & Non-Life Insurance Market Segmentation
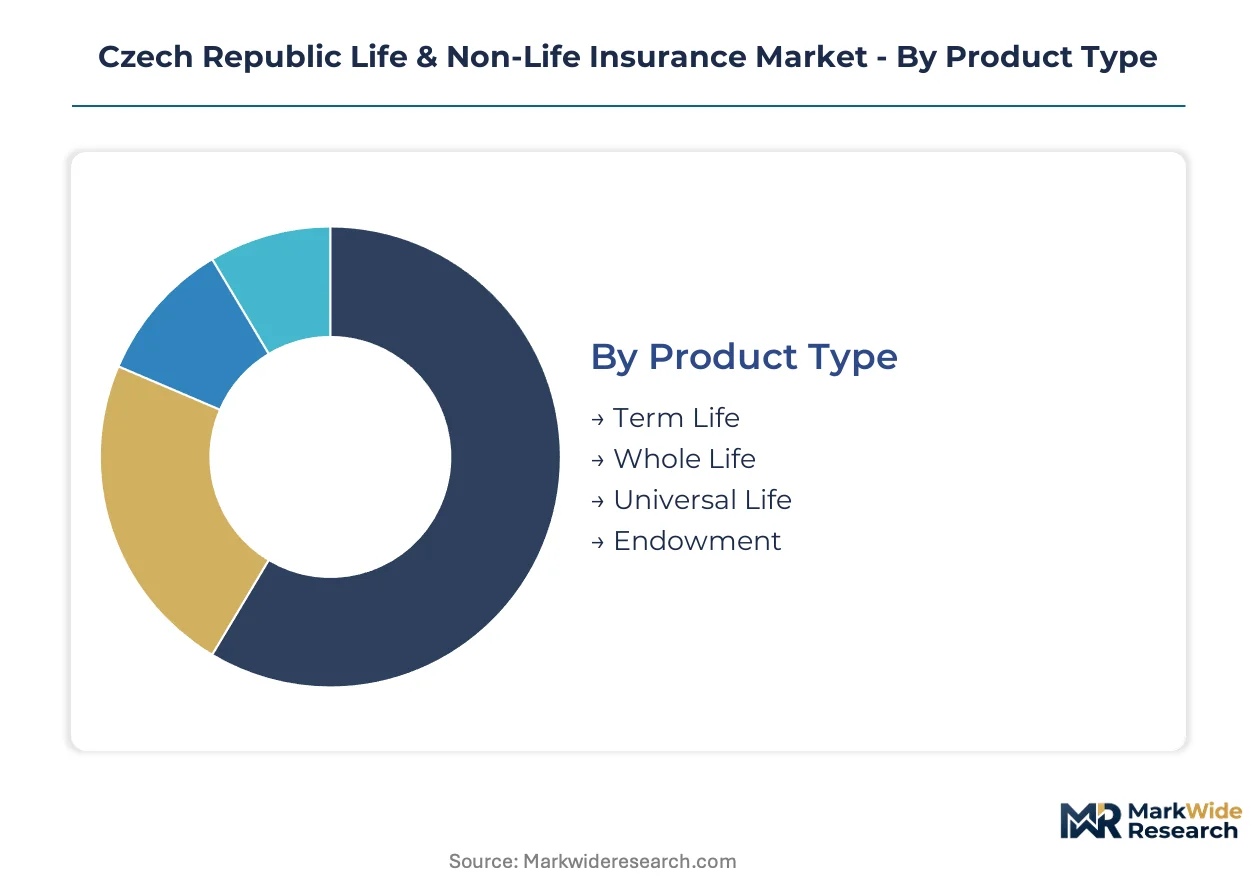
Czech insurers structure product portfolios around distinct risk profiles and servicing intensities. Segment boundaries determine capital allocation, distribution partnerships, and regulatory reserve requirements across life and non-life lines.
Product Type:
After-sales servicing demands vary sharply across life product architectures, with surrender penalties and fund switching creating divergent administrative burdens.
- Term Life:Pure mortality protection with fixed premiums over defined periods. Demand concentrates among Prague's young professionals securing mortgage collateral coverage as housing origination volumes climb.
- Whole Life:Permanent coverage with guaranteed cash value accumulation and level premiums. Rural households in Moravia favor these contracts for estate liquidity, though low sovereign yields compress participating dividend scales.
- Universal Life:Flexible premium structures with adjustable death benefits. Czech banks bundle these with wealth management mandates for affluent depositors.
- Endowment:Savings-linked contracts maturing at predetermined dates. South Bohemian agricultural cooperatives deploy these for succession planning.
Endowment holds the largest share; momentum sits with Term Life.
Coverage Type:
Non-life lines stratify by claims frequency and loss adjustment expense ratios, with health and property commanding divergent technical capabilities.
- Health Insurance:Voluntary medical expense reimbursement supplementing statutory coverage. Prague-based technology firms purchase group policies to attract software engineering talent amid labor shortages.
- Property Insurance:Physical asset protection against fire, flood, and industrial damage. Manufacturing clusters in Plzeň and Ostrava drive commercial lines demand as export-oriented capacity expands.
- Liability Insurance:Third-party obligation coverage for professional and operational risks. Czech construction contractors face mandatory carry requirements under public procurement rules.
- Travel Insurance:Short-term medical and cancellation protection. Online aggregators capture Brno's student population booking Erasmus mobility.
Property Insurance holds the largest share; Health Insurance is climbing the fastest.
Distribution Channel:
Channel economics diverge by customer acquisition cost and persistency rates, with digital onboarding disrupting traditional agent economics.
- Direct Sales:Insurer-employed agents selling proprietary products. Kooperativa maintains captive networks in regional cities where relationship depth offsets higher fixed costs.
- Brokers:Independent intermediaries comparing multi-carrier offerings. Large Czech industrial risks route through Prague-based brokerage houses for capacity placement.
- Banks:Bancassurance partnerships leveraging branch foot traffic. Generali Česká pojišťovna dominates this channel through exclusive distribution agreements.
- Online Platforms:Direct-to-consumer digital onboarding with automated underwriting. ČSOB Pojišťovna targets under-35 motor and travel purchasers through mobile-first interfaces.
Banks hold the largest share; Online Platforms are gaining share fastest.
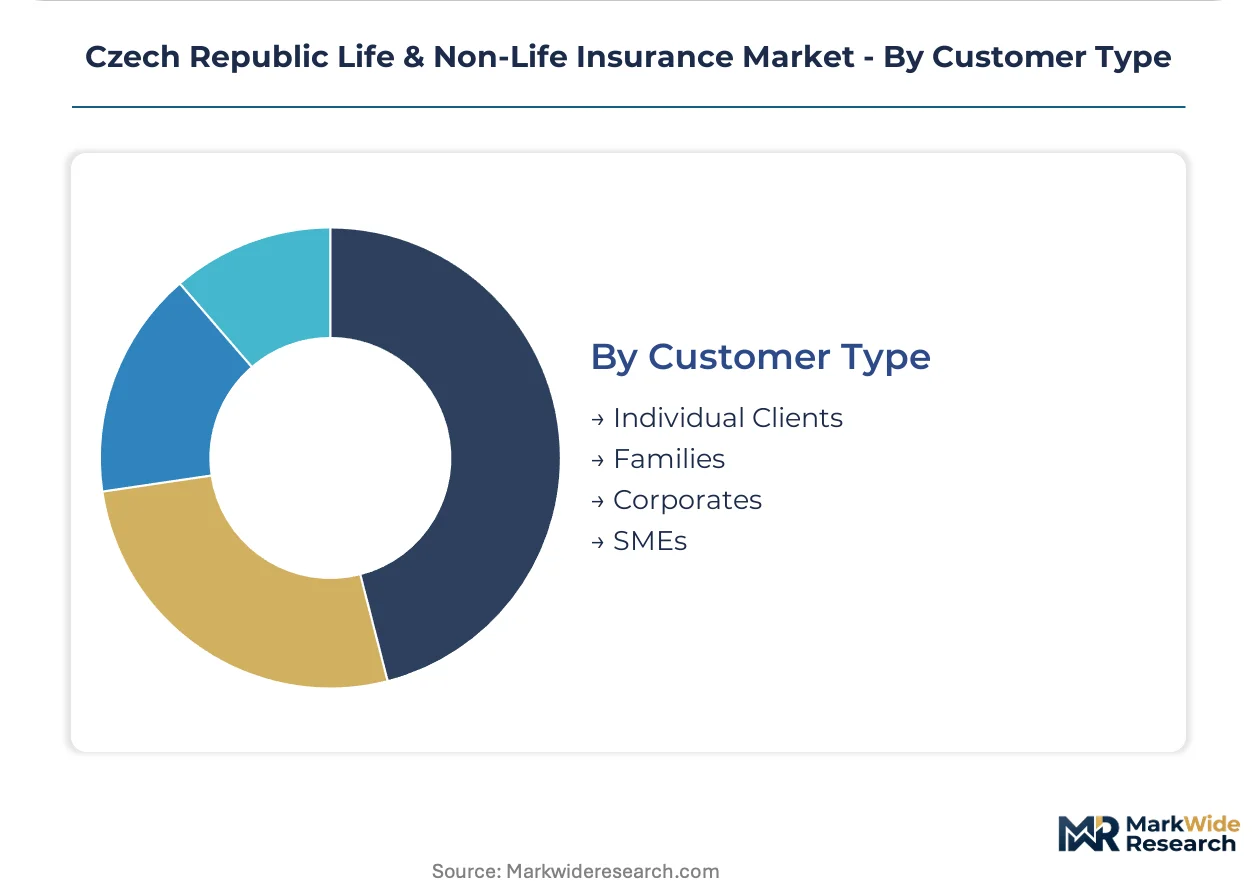
Customer Type:
Risk selection and servicing protocols vary by policyholder scale, with corporates demanding bespoke coverage structures unavailable to retail segments.
- Individual Clients:Single-policy purchasers seeking mortality and health protection. Digital comparison tools have collapsed information asymmetries for this segment.
- Families:Multi-life household coverage with dependent riders. Czech National Bank disclosure rules mandate enhanced suitability documentation for bundled sales.
- Corporates:Large domestic and multinational employers procuring group life and health. Prague's financial services sector generates concentrated demand for executive benefit programs.
- SMEs:Mid-sized enterprises with fragmented risk management functions. South Moravian manufacturing SMEs are expanding commercial portfolios as export credit requirements tighten.
SMEs hold the largest share; momentum sits with Individual Clients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Czech insurers export capacity through cross-border reinsurance treaties while importing Munich and London reinsurance backing. This trade pattern concentrates risk selection domestically and capital protection externally.
Prague
Corporate group life and executive benefit programs dominate premium flows as financial services employers compete for talent. Czech National Bank solvency disclosures mandate granular asset-liability matching for underwriters headquartered here. The city's fintech corridor incubates digital distribution startups targeting mobile-first policyholders.
Brno
South Moravian manufacturing clusters generate concentrated demand for commercial property and export credit coverage. EU Green Deal climate stress testing requirements apply to industrial risk pricing across the region. Automotive suppliers in the surrounding districts are expanding liability portfolios as just-in-time contract terms tighten.
Plzeň
Export-oriented machinery manufacturers drive demand for machinery breakdown and business interruption protection. The country's central bank enforces risk-based capital reserves that elevate pricing for heavy industrial exposures. Regional broker networks specialize in placing large commercial risks through Prague-based wholesale channels.
Ostrava
Legacy industrial infrastructure creates persistent demand for environmental liability and legacy pollution coverage. Solvency II-aligned reporting standards force granular disclosure of long-tail reserve adequacy for underwriters active here. Mining and metallurgical operations in the surrounding area anchor commercial lines premium pools.
Liberec
Textile and automotive component manufacturers generate SME-focused commercial coverage demand. EU Insurance Distribution Directive suitability rules govern cross-border selling permissions for underwriters operating near the Polish and German borders. The region's industrial parks attract foreign direct investment requiring tailored risk transfer structures.
Czech Republic Life & Non-Life Insurance Market Competitive Landscape
On the supply side, the industry is consolidating around bancassurance alliances and digital platform investments. Tier-one underwriters leverage captive banking distribution for unit-linked savings products. Mid-tier carriers rely on selective reinsurance ceding to meet capital requirements. Strategic moves center on acquiring digital onboarding capabilities and embedding insurance into automotive and real estate transaction platforms.
Within the domestic tier, Kooperativa pojišťovna, Generali Česká pojišťovna, and ČSOB Pojišťovna occupy distinct positioning vectors. Kooperativa exemplifies the SME-commercial specialist archetype through entrenched regional relationships. Generali Česká pojišťovna represents the bancassurance-anchored model with exclusive banking network access. ČSOB Pojišťovna sits within the digital-native tier targeting younger policyholders through mobile-first interfaces. These three patterns illustrate how capital requirements and distribution economics are segmenting competitive space.
| Leading Market Players |
|---|
| Kooperativa pojišťovna |
| Česká podnikatelská pojišťovna |
| Generali Česká pojišťovna |
| Allianz pojišťovna |
| Česká pojišťovna |
| UNIQA pojišťovna |
| ČSOB Pojišťovna |
| ERGO pojišťovna |
| AXA pojišťovna |
| Others |
Pricing and Supply Chain Analysis
Reinsurance capacity concentration in Munich and London panels determines both premium tier spreads and supply chain configuration for Czech domestic underwriters. Solvency II-aligned capital requirements from the Czech National Bank force risk ceding decisions that reshape cost structures across retail and commercial lines.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term pricing structure where guaranteed-return traditional policies command premium positioning over unit-linked alternatives. Price differentiation centers on Solvency II capital adequacy tiers and bancassurance exclusivity arrangements, with digital-native carriers compressing acquisition costs in the standard tier. Pricing pressure stems from persistently suppressed sovereign bond yields forcing reserve strengthening. SMEs exhibit highest price sensitivity; corporate group purchasers show lowest elasticity due to bundled executive benefit mandates.
Supply Chain Analysis
Extended payment terms from Munich and London reinsurance panels finance capacity backing for Czech domestic underwriters. Geographic supply concentration rests on Germany, the United Kingdom, and Switzerland for treaty capacity. Raw material dependencies include mortality tables, climate risk models, and healthcare cost indices. Single-source vulnerability sits with concentrated reinsurance panel access. Distribution runs through captive agent networks, bancassurance partnerships, and direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Czech insurance market functions as a service-attach opportunity where preventive health advisory and dynamic pricing layers expand faster than traditional policy underwriting. Recurring revenue from wearable data partnerships and embedded distribution commissions now outpaces pure risk-transfer growth.
For Market Incumbents: Entrench bancassurance exclusivity through deeper integration with Česká spořitelna and Komerční banka branch networks. Consolidate SME relationships in South Moravian manufacturing clusters before digital-native competitors capture share. Solvency II capital requirements favor scale; selective acquisition of thinly capitalized regional underwriters preserves distribution access.
For New Entrants and Emerging Players: Pursue embedded insurance partnerships with automotive leasing platforms and real estate transaction portals where incumbent agent networks hold weak positions. The under-35 individual motor and travel segment offers lowest penetration barriers. A mobile-first direct-to-consumer interface with automated underwriting captures price-sensitive policyholders abandoning traditional channels.
For Investors and Strategic Acquirers: EU Green Deal climate disclosure mandates reshape the acquisition landscape by elevating actuarial capabilities in climate risk modeling. Long-term viability favors underwriters with proprietary data assets and reinsurance panel relationships. The signal to watch is Czech National Bank enforcement intensity on Solvency II reserve adequacy, which accelerates consolidation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | ČSOB Pojišťovna's mobile-first interface captures under-35 policyholders migrating from agent channels. |
| Bancassurance Partnership Expansion | Generali Česká pojišťovna leverages exclusive Česká spořitelna distribution for unit-linked savings products. |
| Climate Risk Modeling Investment | EU Green Deal mandates force integration of flood and industrial exposure data into property pricing. |
| Preventive Health Service Launch | Wearable data partnerships enable Kooperativa to align health premiums with behavioral outcomes. |
| SME Commercial Portfolio Buildout | South Moravian manufacturing clusters generate escalating export credit and liability coverage demand. |
Research Methodology
Initial hypotheses were tested against primary input from chief actuaries, distribution channel heads, and Czech National Bank supervisory staff and refined through secondary validation. Chief underwriting officers at tier-one carriers, reinsurance treaty brokers in Prague, and SME risk managers in Brno manufacturing clusters provided operational perspective. Secondary sources included Czech National Bank solvency disclosure filings, EU Insurance Distribution Directive implementation guidelines, and Czech Insurance Association statistical bulletins. Bottom-up premium volume estimates triangulated against top-down macroeconomic allocation models.
Demand-supply balance across the analysis window reflects segmented modeling of life product architectures, non-life coverage types, distribution channel economics, and customer scale tiers. The projection framework incorporates mortality improvement assumptions, sovereign yield curve trajectories, and SME export credit demand patterns. CAGRs derive from recursive baseline adjustments against regulatory capital requirement phase-ins.
Macroeconomic conditions sit as an overlay; deviation in Czech sovereign bond yields, eurozone reinsurance capacity pricing, or EU sustainability disclosure timelines would shift the trajectory. Forecasts embed assumptions about Solvency II implementation consistency and cross-border treaty availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Sri Lanka Life and Non-Life Insurance Market
Life and Non Life Insurance
Argentina Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia Pacific Life & Non-Life Insurance Market
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Australia Life and Non-Life Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
Colombia Life and Non-Life Insurance Market
Life and Non Life Insurance
Children Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
North America Business Income Insurance Market
Life and Non Life Insurance
South Korea Life & Non-Life Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market