
 South Korea Life & Non-Life Insurance Market | 2026-2036
South Korea Life & Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Life & Non-Life Insurance Market Insights
Corporate risk managers is rotating demand toward comprehensive casualty and property bundles as Korean manufacturers globalize supply chains. Samsung Life Insurance leverages its bancassurance network to sustain premium flow from salaried households. Hanwha Life Insurance anchors its position through variable annuity specialization. Hyundai Marine & Fire Insurance competes aggressively in SME commercial lines through digital underwriting platforms.
Life and non-life insurance in South Korea constitutes a dual-pillar financial system where life carriers manage long-duration mortality and savings-linked liabilities while non-life underwriters price property, casualty, and health risks through statistical loss models and reinsurance treaties. The primary purpose is capital protection and income replacement for households and enterprises. Life insurance and annuities dominate premium pools due to Korea's aging demographic structure, while online platforms represent the fastest-growing distribution channel as MFDS-aligned insurtech entrants reduce acquisition costs. Property insurance maintains mature margins in industrial fire and marine segments tied to Korea's export manufacturing base.
Financial Supervisory Service capital adequacy rules and IFRS 17 accounting standards reshape product design and reserving practices across Korean carriers. The Personal Information Protection Act constrains data-driven pricing innovation while K-ISMS certification requirements elevate cybersecurity spending for digital distribution platforms. Stakeholders must monitor how the Financial Services Commission's sandbox approvals for AI-powered underwriting will alter competitive barriers between established insurers and technology-backed entrants.
Market Dynamics
IFRS 17 accounting standards are forcing Korean carriers to rebuild actuarial systems and reserve methodologies, compressing product development cycles while elevating compliance costs across the life insurance segment.
Growth Catalysts
- Financial Services Commission sandbox approvals:AI-powered underwriting tools receive accelerated regulatory clearance, lowering barriers for insurtech entrants targeting SME commercial lines.
- Seoul metropolitan financial district concentration:Salaried households in Gangnam and Yeouido clusters sustain demand for savings-linked life products through bancassurance networks.
- K-ISMS certification requirements:Mandatory cybersecurity frameworks for digital distribution platforms are driving infrastructure investment that reduces policy acquisition costs.
Market Restraints
- Personal Information Protection Act constraints:Strict data usage limits prevent granular risk pricing for health-linked policies, compressing margins on personalized products.
- Long-duration liability duration mismatch:Korean life insurers face structural asset-liability gaps as low-yield environments persist, pressuring investment returns on guaranteed products.
- Reinsurance capacity concentration:Korean non-life carriers remain dependent on limited international reinsurer panels for catastrophe coverage, elevating cost volatility.
Strategic Opportunities
- Gyeonggi province SME expansion:Manufacturing clusters around Suwon and Incheon present underpenetrated commercial lines demand as export-oriented firms globalize supply chains.
- Variable annuity product innovation:Regulatory tailwinds from Financial Supervisory Service capital rules favor unit-linked savings products with transparent fee structures.
- Telematics-auto convergence:Usage-based motor insurance combining IoT sensors with mobile distribution channels opens new pricing models for younger driver segments.
Industry Challenges
- Actuarial talent scarcity:IFRS 17 implementation demands specialists in stochastic modeling and data science that Korean carriers struggle to recruit at scale.
- Legacy system integration friction:Core policy administration platforms from the 1990s resist API connectivity with modern digital distribution stacks, delaying channel modernization.
- Reinsurance treaty renegotiation timelines:Compressed renewal cycles for international catastrophe coverage create liquidity planning complexity ahead of typhoon seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Life & Non-Life Insurance Market |
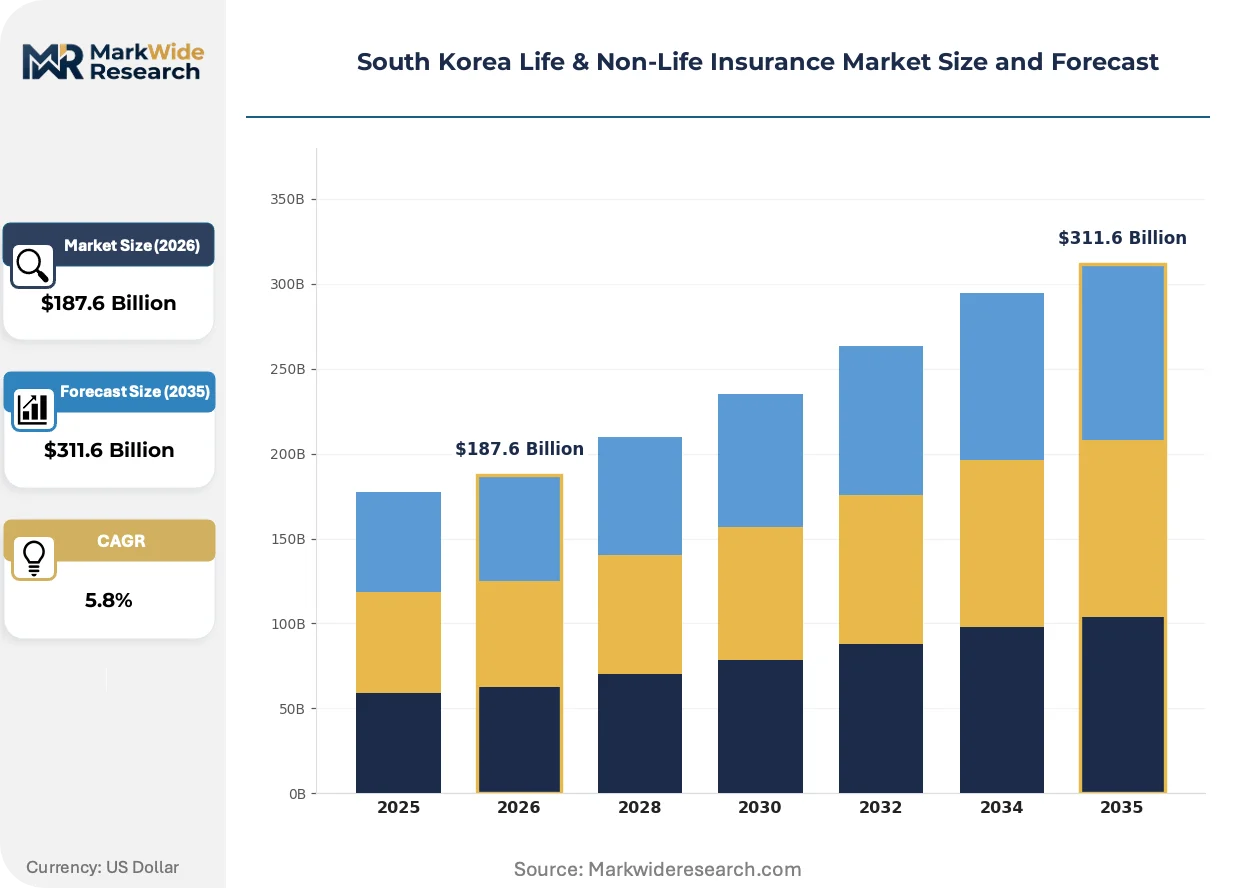
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $311.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Life Insurance, Health Insurance, Property Insurance, Casualty Insurance Distribution Channel: Online Platforms, Direct Sales, Agents, Banks Customer Type: Individuals, Corporates, SMEs, Government Policy Term: Short-term, Long-term, Single Premium, Annuities |
| Companies Covered | Samsung Life Insurance, Hanwha Life Insurance, Kyobo Life Insurance, Samsung Fire & Marine Insurance, DB Insurance, Hyundai Marine & Fire Insurance, KB Insurance, Meritz Fire & Marine Insurance, Mirae Asset Life Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Life & Non-Life Insurance Market Trends and Innovations
Digital-first distribution platforms are fragmenting traditional agency networks while embedded insurance partnerships penetrate e-commerce and mobility ecosystems across Korean metropolitan areas.
Blockchain-based smart contracts are decomposing traditional claims processing workflows in marine and fire insurance segments. Hyundai Heavy Industries and major port operators pilot automated cargo loss settlements through distributed ledger verification. This technology is decomposing the adjuster intermediary role, compressing settlement timelines from weeks to hours while reducing fraud exposure in Busan and Incheon shipping corridors.
Financial Supervisory Service capital adequacy rules are tightening risk-based capital requirements for interest rate sensitive products. Korean life insurers respond by shifting liability structures toward market-linked annuities and reducing guaranteed return commitments. Variable universal life products face the steepest reserve increases, prompting product line consolidation at mid-tier carriers.
Subscription-based microinsurance models are disrupting traditional annual policy structures among younger demographics in Seoul. KakaoPay and Toss platforms bundle bite-sized coverage for gig economy workers and renters, displacing conventional agent-sold term products. This pattern concentrates in the 25-35 age cohort, where mobile-first financial behavior dominates protection purchasing decisions.
South Korea Life & Non-Life Insurance Market Segmentation
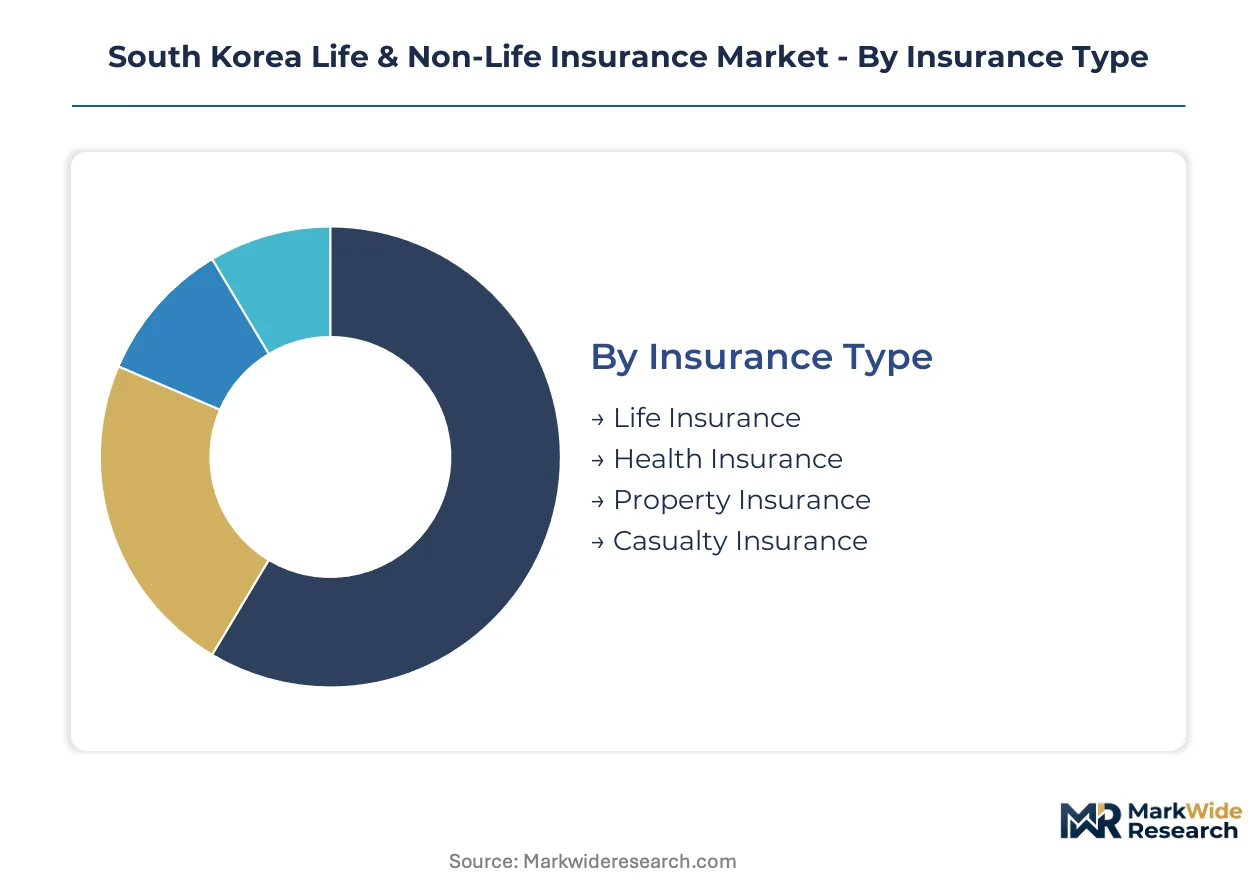
Segmentation in South Korea's insurance market reveals how carrier strategies diverge across liability duration, distribution economics, and customer sophistication. Each dimension carries distinct capital requirements and regulatory treatment under Financial Supervisory Service frameworks.
Insurance Type:
Substitution pressure from savings-linked investment products and corporate self-insurance pools reshapes competitive boundaries across traditional coverage categories.
- Life Insurance:Long-duration mortality and savings-linked contracts dominate premium pools through bancassurance networks. Demand concentrates in Seoul's Gangnam and Yeouido financial districts where salaried households seek tax-advantaged wealth accumulation vehicles amid persistent low-yield environments.
- Health Insurance:Supplementary medical expense coverage fills gaps in National Health Insurance Service reimbursement structures. SME employee benefit plans in Gyeonggi province manufacturing clusters drive commercial segment expansion as firms compete for talent.
- Property Insurance:Industrial fire and marine segments anchor commercial lines through Korea's export manufacturing base. Hyundai Heavy Industries and port operators in Busan and Incheon shipping corridors sustain demand for cargo and hull coverage.
- Casualty Insurance:Liability and commercial auto products face pricing pressure from telematics-enabled usage-based alternatives. Digital underwriting platforms reduce acquisition costs for SME commercial lines in Suwon and Incheon manufacturing zones.
Life Insurance anchors the volume base while Health Insurance gains share at the steepest rate.
Distribution Channel:
Cost tier differentiation separates high-touch advisory models from automated acquisition platforms with divergent expense ratio structures.
- Online Platforms:Mobile-first distribution through KakaoPay and Toss reduces policy acquisition costs by eliminating agent commissions. Subscription-based microinsurance models target 25-35 age cohorts in Seoul metropolitan areas with bite-sized coverage for gig economy workers.
- Direct Sales:Carrier-owned digital channels and call center operations serve price-sensitive term life segments. K-ISMS certification requirements elevate cybersecurity infrastructure spending but compress marginal distribution costs over scaled policy volumes.
- Agents:Tied and independent producer networks maintain dominance in complex whole life and variable annuity sales. Face-to-face advisory relationships sustain premium flow from older demographics in provincial cities beyond Seoul metropolitan concentration.
- Banks:Bancassurance partnerships leverage branch networks for savings-linked product distribution. Samsung Life Insurance and other major carriers embed products within retail banking relationships to access salaried household deposit bases.
Online Platforms command the steepest expansion trajectory while Banks retain the largest premium volume concentration.
Customer Type:
Application complexity separates standardized retail products from bespoke commercial programs with customized risk engineering requirements.
- Individuals:Retail policyholders purchase mortality protection and savings vehicles through agent and bancassurance channels. Aging demographic structure elevates demand for retirement income replacement products with guaranteed benefit features.
- Corporates:Large enterprise risk managers procure comprehensive casualty and property bundles as Korean manufacturers globalize supply chains. International operations exposure drives demand for multinational program structures with centralized policy administration.
- SMEs:Small and medium enterprises in Gyeonggi province manufacturing clusters present underpenetrated commercial lines opportunity. Digital underwriting platforms enable automated risk selection at premium volumes below traditional agent economic thresholds.
- Government:Public sector procurement of social insurance administration and catastrophe risk pools operates through specialized tender processes. Financial Services Commission sandbox approvals facilitate pilot programs for AI-powered public health coverage administration.
Individuals generate the largest absolute premium base while SMEs offer the most rapid volume expansion potential.
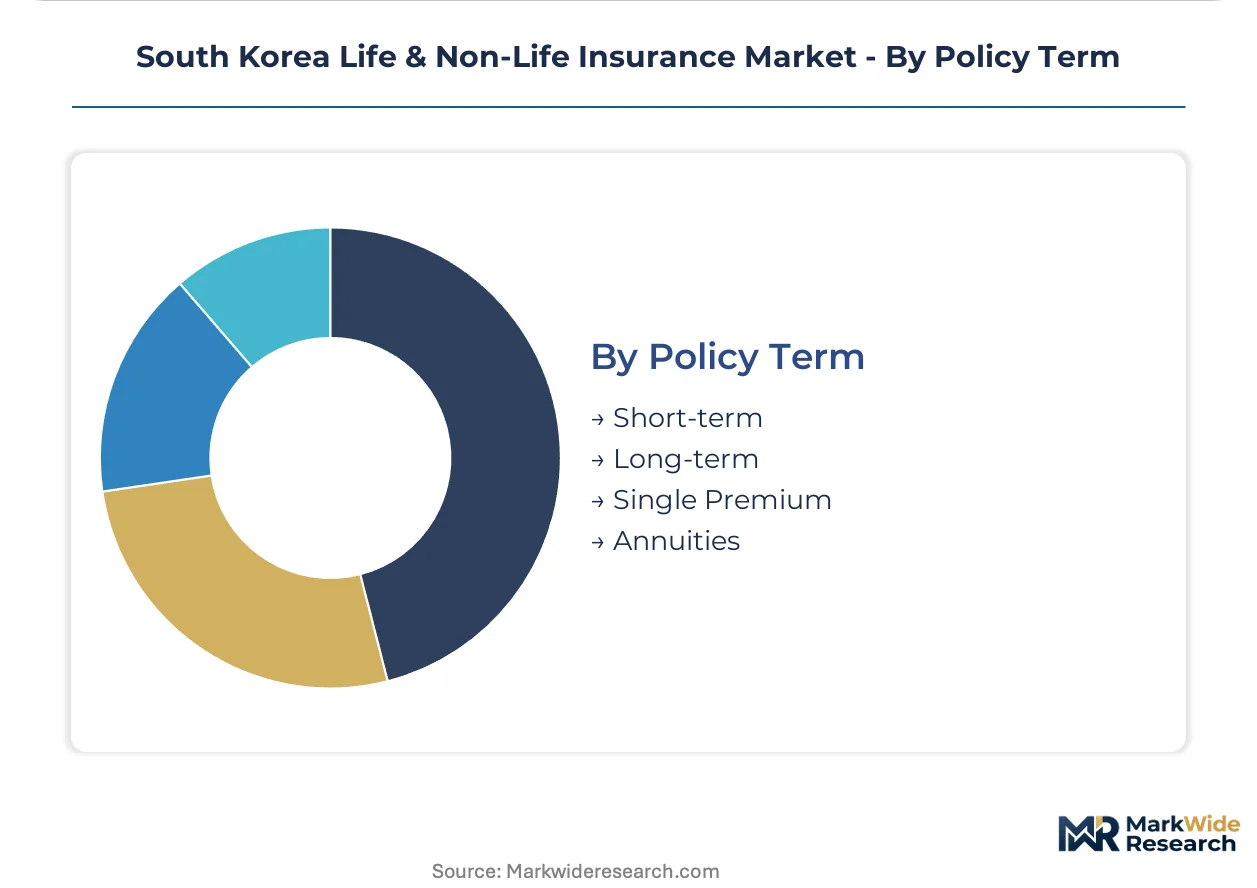
Policy Term:
Margin structure varies dramatically across duration profiles with long-term guaranteed products carrying the heaviest capital charges under risk-based frameworks.
- Short-term:Annual renewable contracts in property and casualty segments minimize reserve duration risk. Typhoon exposure in Korean peninsula coastal regions creates reinsurance treaty renegotiation complexity ahead of seasonal renewal cycles.
- Long-term:Multi-year life and health contracts lock in premium rates while exposing carriers to interest rate and mortality assumption drift. IFRS 17 accounting standards force rebuilds of actuarial systems and reserve methodologies for these duration-heavy liabilities.
- Single Premium:Lump-sum immediate annuity and endowment products concentrate investment risk with policyholders. Financial Supervisory Service capital adequacy rules impose steepest reserve increases on guaranteed return commitments in this category.
- Annuities:Retirement income products shift liability structures toward market-linked unit-linked structures. Variable annuity specialization at Hanwha Life Insurance and competitors responds to regulatory tailwinds favoring transparent fee structures.
Long-term policies dominate premium volume while Annuities climb the fastest among emerging product architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Korean life insurers export savings-linked products to Vietnamese and Indonesian middle-class households through bancassurance partnerships. Non-life carriers extend marine and cargo coverage across Busan-Incheon shipping corridors into Chinese and Japanese port networks.
Seoul Capital Area
Gangnam and Yeouido financial districts concentrate demand for variable annuities and retirement income products. Financial Supervisory Service capital adequacy rules tighten reserve requirements for guaranteed-return policies. Samsung Life Insurance and Hanwha Life Insurance anchor premium flow through retail banking branch networks.
Busan-Ulsan
Hyundai Heavy Industries and port operators sustain demand for marine hull and cargo insurance. Blockchain-based smart contracts pilot automated claims settlements through distributed ledger verification. Shipping corridors connecting Busan to Shanghai and Osaka elevate reinsurance treaty complexity.
Gyeonggi Province
Suwon and Incheon manufacturing clusters generate commercial lines demand from export-oriented SMEs. Digital underwriting platforms reduce acquisition costs for property and casualty coverage. Corporate risk managers procure comprehensive bundles as supply chains globalize.
Daegu-Gyeongbuk
Textile and electronics manufacturers drive group health insurance adoption for employee retention. National Health Insurance Service reimbursement gaps create supplementary coverage opportunities. Mid-sized enterprises shift from traditional agency channels to direct digital procurement.
Daejeon-Sejong
Government complex concentration stimulates demand for public sector risk pools and social insurance administration. Financial Services Commission sandbox approvals facilitate AI-powered underwriting pilots. Administrative city development projects elevate construction and surety bond requirements.
South Korea Life & Non-Life Insurance Market Competitive Landscape
Listed leaders compete with private specialists across distribution channel dominance. The market structures around three tiers: conglomerate-affiliated carriers with captive bancassurance networks, independent life specialists with variable annuity focus, and non-life underwriters with marine and fire expertise. Strategic moves concentrate on digital platform integration and embedded insurance partnerships with e-commerce and mobility ecosystems.
Within the conglomerate-affiliated tier, Samsung Life Insurance and Samsung Fire & Marine Insurance exemplify integrated financial services models. Hanwha Life Insurance occupies a position among variable annuity specialists. Hyundai Marine & Fire Insurance anchors the non-life segment with digital underwriting capabilities. These entities represent archetypal competitive positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Samsung Life Insurance |
| Hanwha Life Insurance |
| Kyobo Life Insurance |
| Samsung Fire & Marine Insurance |
| DB Insurance |
| Hyundai Marine & Fire Insurance |
| KB Insurance |
| Meritz Fire & Marine Insurance |
| Mirae Asset Life Insurance |
| Others |
Pricing and Supply Chain Analysis
Scale economies in actuarial data processing and digital distribution infrastructure concentrate pricing power among carriers with legacy bancassurance networks and modern API-ready platforms. This bifurcation creates divergent cost floors: established insurers leverage existing branch density to amortize fixed costs, while insurtech entrants compress acquisition expenses through mobile-first stacks.
Pricing Analysis
Current-generation AI-powered underwriting platforms command premium pricing against prior-generation manual risk assessment and emerging next-generation blockchain-verified parametric products. Three-tier pricing structure across premium, standard, and economy levels separates bundled bancassurance offerings from direct digital term products and bite-sized microinsurance subscriptions. Cost compression in standard-tier direct sales channels is intensifying because KakaoPay and Toss eliminate agent commissions. SME commercial lines exhibit highest price sensitivity due to thin operating margins, while high-net-worth variable annuity buyers demonstrate lowest elasticity.
Supply Chain Analysis
Port congestion along Busan-Shanghai and Incheon-Osaka trade lanes elevates inbound logistics costs for marine cargo underwriting data and reinsurance treaty documentation flows. Geographic supply concentration rests on Bermuda, London, and Singapore for international catastrophe reinsurance capacity. Raw material dependencies center on actuarial talent pools, cloud computing infrastructure, and K-ISMS-certified cybersecurity frameworks. Single-source vulnerability permeates the limited international reinsurer panel structure. Distribution runs through carrier-owned digital channels, embedded insurance partnerships, and traditional agency networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's insurance market sits in early-cycle expansion as AI-powered underwriting tools receive Financial Services Commission sandbox approvals, accelerating adoption curves among previously underserved SME segments.
For Market Incumbents: Fortify bancassurance network exclusivity through deeper Samsung Life Insurance-style retail banking integration while rebuilding core policy administration systems for API connectivity. Legacy platform fragility threatens channel modernization timelines against insurtech entrants. Prioritize actuarial data science recruitment to address IFRS 17 implementation talent scarcity. For New Entrants and Emerging Players: Anchor in Gyeonggi province SME commercial lines where digital underwriting platforms enable automated risk selection below traditional agent economic thresholds. Telematics-enabled usage-based motor insurance for younger driver segments offers the most penetrable white space. Pursue embedded insurance partnerships with e-commerce and mobility ecosystems as primary go-to-market angle. For Investors and Strategic Acquirers: Variable annuity specialists with transparent fee structures and unit-linked product expertise represent the most attractive acquisition target archetype in a regulatory environment favoring market-linked liabilities over guaranteed returns. Long-term viability hinges on carriers' ability to shift liability structures away from interest rate sensitive products. Monitor Financial Supervisory Service capital adequacy rule amendments as the critical inflection signal for reserve requirement trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Underwriting Platform Deployment | Financial Services Commission sandbox approvals lower barriers for SME commercial line penetration. |
| Blockchain Smart Contract Integration | Hyundai Heavy Industries pilots automated cargo loss settlements through distributed ledger verification in Busan. |
| Bancassurance Network Deepening | Samsung Life Insurance-style retail banking embedding sustains premium flow from salaried Gangnam households. |
| Telematics-Auto Convergence | Usage-based motor insurance opens new pricing models for 25-35 age cohorts in Seoul metropolitan areas. |
| Variable Annuity Product Innovation | Hanwha Life Insurance specialization responds to regulatory tailwinds favoring transparent fee structures. |
Research Methodology
The analysis maps life insurance, non-life insurance, health coverage, and annuity sub-sectors, each validated through chief risk officers, actuarial directors, digital distribution heads, and reinsurance treaty negotiators. Primary interviews with these stakeholders combined with secondary validation from Financial Supervisory Service regulatory filings, Financial Services Commission sandbox approval records, and carrier financial disclosures. Bottom-up policy volume modeling and top-down premium pool estimation enable cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include insurance type, distribution channel, customer archetype, and policy term duration. CAGRs were derived from trend extrapolation anchored in historical premium growth patterns and demographic trajectory assumptions. Forecast inputs incorporate IFRS 17 implementation timelines and K-ISMS certification penetration curves.
Material uncertainties — regulatory amendments to capital adequacy rules, reinsurance treaty renewal disruptions, and AI underwriting liability frameworks — sit outside the modeled envelope. Forecasts reflect assumptions about persistent low-yield environments and stable catastrophe loss frequencies. Practitioners should keep alternative scenarios live as Financial Supervisory Service reserve requirement adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Group Life Insurance Market
Life and Non Life Insurance
Life Reinsurance Market
Life and Non Life Insurance
Asia Pacific Life & Non-Life Insurance Market
Life and Non Life Insurance
Denmark Life and Non-Life Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
Finland Life and Non-Life Insurance Market
Life and Non Life Insurance
Life Insurance Policy Administration System Market
Life and Non Life Insurance
Israel Life and Non-Life Insurance Market
Life and Non Life Insurance
Peru Life and Non-Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
Sri Lanka Life and Non-Life Insurance Market
Life and Non Life Insurance
North America Business Income Insurance Market
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
Russia Life and Non-Life Insurance Market
Life and Non Life Insurance
Czech Republic Life & Non-Life Insurance Market