
 Aircraft Component MRO Market | 2026-2036
Aircraft Component MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Component MRO Market Analysis
Digital predictive maintenance is narrowing the gap between scheduled overhauls and condition-based interventions across the aviation aftermarket. Lufthansa Technik leverages its Hamburg-based MRO campus to sustain integrated engine-to-avionics service bundles for wide-body operators. ST Engineering anchors its growth on Singapore's Changi aerospace cluster, where humid tropical conditions accelerate corrosion monitoring demand. Rolls-Royce Holdings plc differentiates through TotalCare power-by-the-hour contracts that embed component MRO within engine lifecycle management.
Aircraft component MRO encompasses the repair, overhaul, and inspection of airworthy parts including turbine blades, flight control surfaces, hydraulic actuators, and avionics modules, typically requiring FAA/EASA-certified repair station authorization and traceable material pedigree documentation. The primary purpose is restoring components to manufacturer-specified performance tolerances while extending operational life cycles beyond original design limits. Engine overhaul commands the largest value pool within component type segmentation due to thermal fatigue accumulation in high-pressure turbine sections. Avionics repair gains momentum from software-intensive flight management system upgrades that outpace hardware replacement cycles. IoT Monitoring within technology segmentation captures expanding interest as real-time vibration and oil debris sensors enable shift-from-scheduled maintenance models.
The FAA's Airworthiness Directives and EASA's Part-145 repair station standards govern component certification, mandating documented traceability for life-limited parts and driving MRO providers toward digitized shop floor records. The EU Green Deal's sustainable aviation fuel benchmarks and emerging carbon border adjustments pressure operators to demonstrate emissions-reduced maintenance logistics, including optimized part routing and reduced test-cell fuel burn. Military end users under NATO supply chain protocols impose additional security-cleared handling requirements for dual-use component repairs. Stakeholders must weigh OEM-authorized network exclusivity against independent repair station cost advantages as additive manufacturing qualification standards mature for flight-critical hardware restoration.
Market Dynamics
The aircraft component MRO sector is undergoing structural recalibration as power-by-the-hour contracts and predictive analytics compress traditional overhaul cycles, forcing repair stations to reconfigure capacity planning around data-driven intervention triggers rather than fixed flight-hour intervals.
Growth Catalysts
- FAA Airworthiness Directives:Stricter traceability mandates for life-limited parts are compelling operators to outsource component overhaul to certified repair stations with digitized pedigree documentation systems.
- Tropical Climate Corrosion:Humid conditions in Southeast Asian maintenance hubs accelerate inspection frequency for flight control surfaces and hydraulic actuators, expanding regional MRO throughput requirements.
- Additive Manufacturing Qualification:Emerging FAA guidance on powder-bed fusion restoration for turbine blades is opening new repair pathways for previously scrap-limited components.
Market Restraints
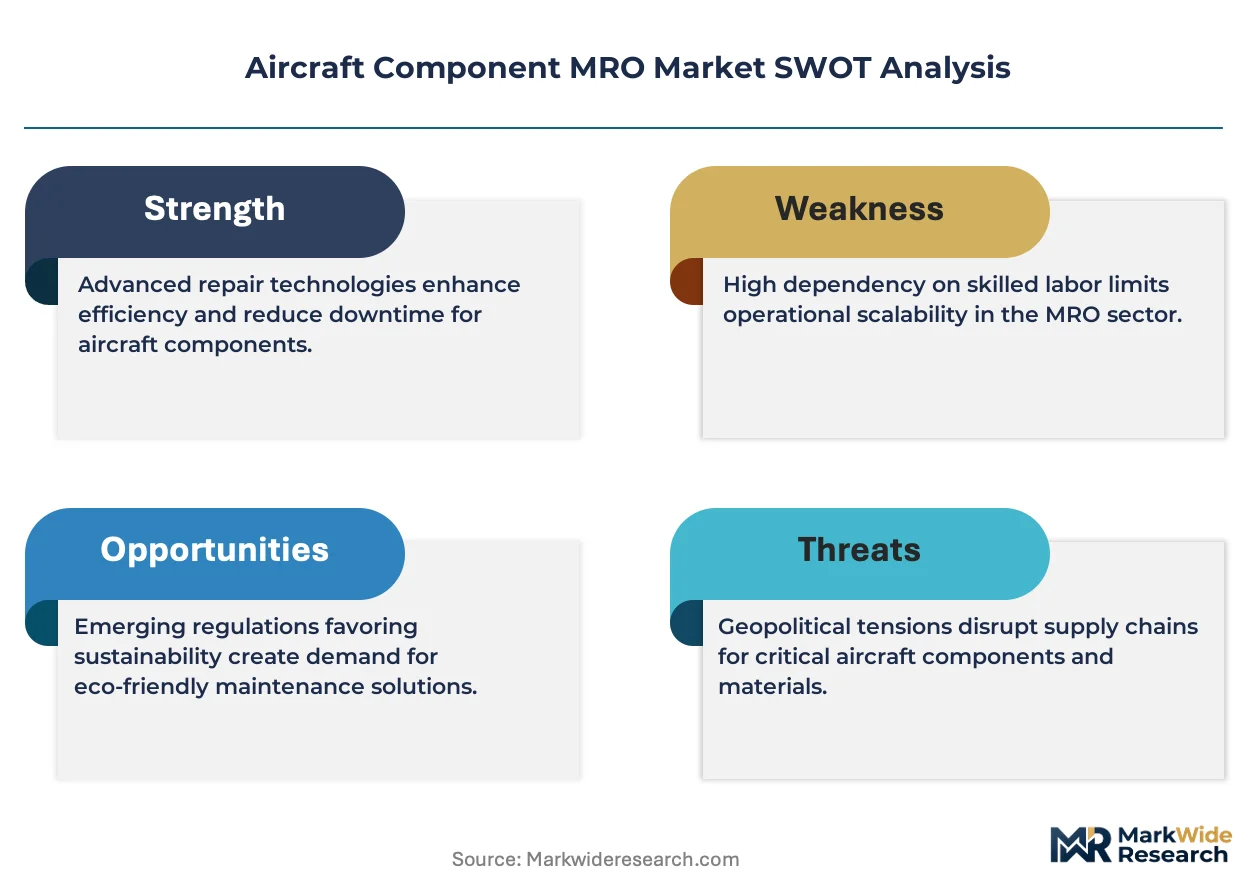
- OEM Network Exclusivity:Rolls-Royce and Pratt & Whitney restrict component repair intellectual property to authorized service networks, limiting independent station access to proprietary tooling.
- Titanium Alloy Supply Concentration:Russian VSMPO-AVISMA's dominance in aerospace-grade titanium creates input cost volatility and sanctions-driven sourcing disruptions for blade restoration.
- Dual-Use Component Handling:NATO supply chain protocols impose security-cleared facility requirements that fragment repair capacity for military-commercial crossover parts.
Strategic Opportunities
- Indonesia Fleet Expansion:Garuda Indonesia and Lion Air's narrow-body growth outpaces domestic MRO infrastructure, creating demand for component repair joint ventures in Batam and Jakarta.
- Sustainable Aviation Fuel Logistics:EU Green Deal emissions benchmarks incentivize optimized part routing algorithms that reduce test-cell fuel burn and AOG transport emissions.
- IoT-AI Convergence:Real-time vibration sensors combined with machine learning debris analysis enable just-in-time component replacement before secondary damage propagates.
Industry Challenges
- NDT Technician Shortage:Eddy current and ultrasonic inspection certification backlogs constrain shop floor throughput for turbine disk crack detection.
- Legacy Avionics Obsolescence:Flight management system software upgrades outpace hardware replacement cycles, creating configuration management complexity for mixed-fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Component MRO Market |
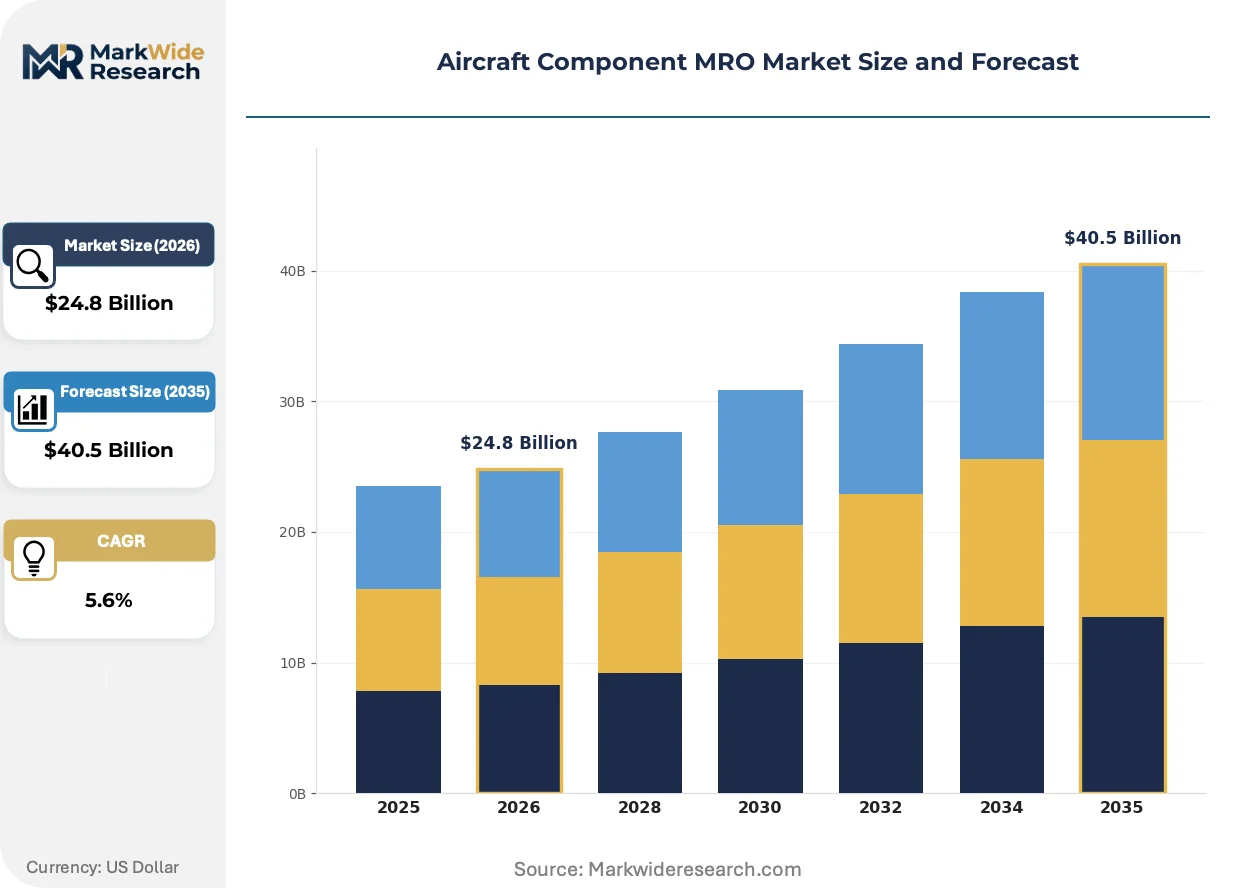
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.5 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Repair, Overhaul, Maintenance, Inspection Component Type: Engines, Avionics, Landing Gear, Airframes End User: Airlines, Private Operators, Military, Service Providers Technology: 3D Printing, Augmented Reality, IoT Monitoring, Robotics |
| Companies Covered | SIA Engineering Company, RTX Corporation, Lufthansa Technik, Rolls-Royce Holdings plc, Safran SA, General Electric Company, AAR, Turkish Technic, ST Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Component MRO Market Emerging Trajectories
Digital thread architectures are collapsing the latency between in-service component monitoring and shop floor repair planning, enabling MRO providers to reposition inventory and labor before failures trigger AOG events.
Blockchain-enabled material pedigree systems are digitizing component traceability from raw material melt through final assembly. Tier-one airlines and lessors are mandating distributed-ledger documentation for life-limited parts to satisfy EASA Part-145 audit requirements. This is compressing dispute resolution timelines and reducing paperwork-related airworthiness delays.
EASA's expanding scope of carbon border adjustments and sustainable aviation fuel verification requirements is reshaping maintenance logistics. Repair stations must now document emissions per component movement, with EU-registered operators facing compliance deadlines that accelerate adoption of electric ground support equipment and regionalized test-cell operations.
Airline procurement teams are unbundling engine overhaul contracts to extract component-level MRO pricing transparency. Low-cost carriers in Southeast Asia are leading this shift, negotiating direct repair station relationships for hydraulic actuators and avionics modules that were previously bundled under power-by-the-hour arrangements. This fragmentation is most visible in Singapore's Changi aerospace cluster, where independent specialists capture share from OEM-affiliated networks.
Aircraft Component MRO Market Segmentation

Aircraft component MRO segmentation reveals divergent margin structures across service modalities and technology maturity levels. Component-level economics vary sharply between life-limited rotating assemblies and software-intensive avionics modules.
Service Type:
Mature overhaul protocols dominate revenue capture while emerging predictive models reshape intervention timing.
- Repair:Component-level restoration addresses localized damage to turbine blades, flight control surfaces, and hydraulic actuators without full disassembly. Demand concentrates in Southeast Asian hubs—Singapore and Thailand—where tropical corrosion accelerates surface degradation on flight-critical hardware.
- Overhaul:Complete disassembly, inspection, and reassembly of engines, landing gear, and auxiliary power units restores manufacturer-specified performance tolerances. European operators under EASA Part-145 mandates drive outsourcing volume as digitized pedigree documentation requirements exceed in-house capability.
- Maintenance:Scheduled preventive interventions include lubrication, filter replacement, and wear-component substitution at prescribed flight-hour intervals.
- Inspection:Non-destructive testing via eddy current, ultrasonic, and borescope methods detects subsurface cracking and material fatigue before catastrophic failure.
Overhaul retains volume leadership; inspection holds the steepest expansion curve as condition-based monitoring compresses scheduled intervention cycles.
Component Type:
Cost tier stratification separates capital-intensive engine work from high-velocity avionics turnaround.
- Engines:High-pressure turbine sections accumulate thermal fatigue and creep deformation requiring blade replacement, casing weld restoration, and combustion liner refurbishment. FAA Airworthiness Directives on life-limited parts mandate documented traceability that drives repair station consolidation.
- Avionics:Flight management systems, navigation processors, and communication radios require software upgrades that outpace hardware obsolescence cycles. Low-cost carriers in Indonesia and the Philippines unbundle these services from power-by-the-hour contracts to capture direct pricing transparency.
- Landing Gear:Shock strut sealing, brake assembly overhaul, and structural crack repair address cyclic loading damage from high-cycle operations.
- Airframes:Fuselage skin panel replacement, corrosion treatment, and structural reinforcement extend operational life beyond original design limits.
Engines command premium pricing tiers; avionics demonstrates the fastest margin expansion as software-defined functionality displaces hardware replacement.
End User:
Customer type determines certification burden and contract structure across the service portfolio.
- Airlines:Scheduled network operators balance fleet availability against maintenance cost, driving long-term service agreements with OEM-affiliated networks and independent specialists.
- Private Operators:Business aviation and charter services prioritize rapid turnaround over unit cost, accepting premium pricing for minimized aircraft-on-ground exposure.
- Military:NATO supply chain protocols impose security-cleared facility requirements and dual-use component handling restrictions that fragment repair capacity.
- Service Providers:Third-party MRO stations and leasing company technical teams intermediate between operators and certified repair stations.
Airlines generate the largest contract value; private operators deliver the highest per-component margin realization.
Technology:
Application maturity separates production-proven monitoring systems from pilot-phase augmentation tools.
- 3D Printing:Powder-bed fusion restoration of turbine blades and structural brackets enables repair geometries previously achievable only through replacement. Emerging FAA guidance on additive manufacturing qualification opens pathways for previously scrap-limited components.
- Augmented Reality:Technician guidance overlays and remote expert collaboration tools reduce training time for complex assembly procedures. Adoption concentrates in German and Singaporean facilities where labor cost justifies capital deployment.
- IoT Monitoring:Real-time vibration, temperature, and oil debris sensors enable predictive intervention before secondary damage propagates.
- Robotics:Automated drilling, sealing, and inspection systems improve repeatability in high-volume component processing.
IoT Monitoring scales fastest across installed fleets; 3D Printing holds the steepest capability expansion trajectory as regulatory frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore exports component overhaul services to European and North American flag carriers under long-term power-by-the-hour arrangements, while Southeast Asian demand concentrates in humid-climate corrosion monitoring for flight control surfaces.
United States
FAA Airworthiness Directives on life-limited parts drive outsourcing to certified repair stations with digitized pedigree documentation. The FAA mandates stricter traceability standards under evolving airworthiness directives. Dallas-Fort Worth anchors domestic engine overhaul capacity where GE Aviation and independent specialists co-locate test-cell operations.
Germany
EASA Part-145 repair station standards compel operators to demonstrate emissions-reduced maintenance logistics under EU Green Deal benchmarks. EASA's carbon border adjustments pressure documentation of emissions per component movement. Hamburg's MRO campus sustains integrated engine-to-avionics service bundles for wide-body operators.
Singapore
Humid tropical conditions accelerate corrosion monitoring demand for flight control surfaces and hydraulic actuators. The country's national aviation regulator enforces alignment with EASA Part-145 audit requirements for blockchain-enabled material pedigree systems. Changi aerospace cluster deepens OEM-affiliated service network capacity for regional low-cost carrier expansion.
Thailand
Maintenance hub expansion captures narrow-body fleet growth from Indonesian and Philippine operators seeking cost-competitive overhaul alternatives. The country's civil aviation authority implements FAA-equivalent repair station certification to attract foreign operator contracts. U-Tapao aerospace precinct develops component repair joint ventures with Singaporean technical partners.
Indonesia
Garuda Indonesia and Lion Air's narrow-body growth outpaces domestic MRO infrastructure, creating demand for component repair capability. The national aviation regulator coordinates with ASEAN maintenance protocols to harmonize cross-border certification. Batam and Jakarta emerge as priority locations for foreign joint ventures targeting unmet engine and avionics overhaul demand.
Aircraft Component MRO Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered service hierarchies. OEM-affiliated networks restrict component repair intellectual property to authorized stations, while independent specialists capture share through direct pricing transparency. Three archetypes dominate: engine OEMs bundling MRO within lifecycle contracts, airline-captive technical divisions, and independent repair stations pursuing additive manufacturing qualifications. Competitive moves concentrate on geographic joint ventures in Southeast Asian growth markets and digitized shop floor records for EASA audit compliance.
Within the OEM-integrated tier, Rolls-Royce Holdings plc and General Electric Company exemplify power-by-the-hour contract structures that embed component MRO within engine lifecycle management. Among independent specialists, AAR occupies a position representing direct airline procurement relationships unbundled from bundled service arrangements. ST Engineering anchors the Asia-Pacific specialist segment, exemplifying humid-climate corrosion monitoring capabilities developed at Singapore's Changi aerospace cluster.
| Leading Market Players |
|---|
| SIA Engineering Company |
| RTX Corporation |
| Lufthansa Technik |
| Rolls-Royce Holdings plc |
| Safran SA |
| General Electric Company |
| AAR |
| Turkish Technic |
| ST Engineering |
| Others |
Supply Flow & Price Mechanics
Titanium alloy supply concentration in Russian VSMPO-AVISMA's production network determines both tiered pricing spreads across OEM-authorized versus independent repair stations and the geographic shape of component sourcing. This single-source dependency forces MRO providers to absorb input cost volatility while restructuring procurement toward alternative aerospace-grade titanium suppliers in Japan and the United States.
Pricing Analysis
Technology-generation pricing gaps separate next-generation powder-bed fusion restoration from conventional weld repair and legacy replacement sourcing. Three-tier pricing structure across OEM-authorized premium, EASA-certified standard, and uncertified economy levels reflects certification burden and traceability documentation depth. Pricing pressure stems from low-cost carrier procurement teams unbundling power-by-the-hour contracts to extract component-level transparency. Regional low-cost operators in Southeast Asia demonstrate highest price sensitivity, while business aviation private operators accept premium positioning for minimized AOG exposure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates raw material routing decisions for avionics module sourcing and test-cell equipment procurement. Supply concentrates in the United States for FAA-certified repair station tooling, Germany for precision measurement systems, and Singapore for regional distribution hubs serving Southeast Asian fleet operators. The chain draws from aerospace-grade titanium alloys, nickel-based superalloys, and specialized avionics semiconductors as critical inputs. Single-source vulnerability in Russian titanium creates sanction-driven disruption risk. Distribution runs through OEM-authorized service networks, independent repair station direct contracts, and leasing company technical intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Additive manufacturing qualification for flight-critical hardware restoration presents a credible substitute threat to conventional replacement sourcing, forcing incumbents to defend repair station authorization value against independent specialists capturing share through direct pricing transparency.
For Market Incumbents: Pre-empt independent repair station encroachment by accelerating FAA additive manufacturing certification for turbine blade restoration and deepening captive supply of aerospace-grade titanium through backward integration into Japanese and US alternative sourcing. Channel control through OEM-authorized network exclusivity remains defensible only with simultaneous digitization of shop floor records for EASA Part-145 audit compliance. For New Entrants and Emerging Players: Pursue white-space capture in Indonesia's unmet narrow-body engine and avionics overhaul demand, where Garuda Indonesia and Lion Air fleet growth outpaces domestic MRO infrastructure. Batam and Jakarta joint ventures with Singaporean technical partners offer the most penetrable entry pathway. Lead with humid-climate corrosion monitoring specialization differentiated from generic overhaul capabilities. For Investors and Strategic Acquirers: EASA's expanding carbon border adjustment implementation reshapes the acquisition landscape toward repair stations with documented emissions-per-component-movement capabilities and electric ground support equipment deployment. Long-term viability favors targets with dual-use military-commercial handling clearance under NATO supply chain protocols. The signal to watch is FAA guidance finalization on powder-bed fusion qualification standards, which would unlock valuation premia for additive manufacturing-capable assets.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Qualification | FAA powder-bed fusion guidance unlocks repair pathways for previously scrap-limited turbine blades. |
| Blockchain Pedigree Implementation | Distributed-ledger documentation satisfies EASA Part-145 audit requirements for life-limited parts traceability. |
| Indonesia Joint Venture Formation | Batam and Jakarta partnerships address unmet engine overhaul demand from Lion Air and Garuda Indonesia fleet expansion. |
| Corrosion Monitoring Specialization | Humid-climate flight control surface expertise captures Southeast Asian low-cost carrier procurement unbundling. |
| Alternative Titanium Sourcing | Japanese and US aerospace-grade suppliers reduce VSMPO-AVISMA sanction exposure for blade restoration inputs. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline fleet managers, MRO station directors, OEM aftermarket executives, and EASA Part-145 audit specialists. Secondary validation drew from FAA Airworthiness Directive filings, EASA repair station certification databases, ICAO safety management system reports, and aerospace trade customs records. Bottom-up triangulation across component-level service transaction data converged with top-down market sizing from fleet forecast databases and maintenance interval modeling.
Calibration across the analysis window employed scenario-weighted projections for fleet renewal timing, regulatory adoption curves for additive manufacturing qualification, and regional MRO capacity expansion schedules. Segmentation dimensions modeled encompassed service type modality, component category economics, end-user contract structure, and technology maturity tier. CAGRs were derived from fitted growth curves against historical maintenance spend patterns and projected flight-hour accumulation. Industry-specific inputs included power-by-the-hour contract penetration rates and tropical climate corrosion inspection frequency differentials.
Sensitivities concentrate around FAA additive manufacturing guidance timing, EASA carbon border adjustment enforcement deadlines, and VSMPO-AVISMA supply continuity under sanctions regimes. Forecasts reflect documented assumptions regarding fleet renewal program acceleration and low-cost carrier procurement unbundling momentum. Material shifts in regulatory qualification pathways or titanium supply geopolitics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Aerospace and Defense MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Cloud MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aviation Engine MRO Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Military Aviation Maintenance, Repair, and Overhaul Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market