
 US Military Aviation Market | 2026-2036
US Military Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
US Military Aviation Market Analytics
Premium manned fighter platforms and commodity unmanned systems is decoupling as acquisition budgets bifurcate toward high-end survivable assets and attritable drones. Lockheed Martin leverages its F-35 production scale to dominate advanced stealth fighter deliveries. Boeing anchors military rotorcraft output through its Apache and Chinook lines in Mesa, Arizona. Northrop Grumman specializes in high-altitude long-endurance unmanned systems, competing for next-generation airborne early warning contracts.
US military aviation encompasses the design, development, production, and sustainment of crewed and uncrewed aerial vehicles operating under Department of Defense mission parameters, with turbine engines generating thrust exceeding 5,000 pounds-force and airframes engineered to withstand nine-g maneuver loads. Fighter jets absorb the largest share of procurement value as the Air Force pursues sixth-generation platforms, while drones represent the fastest-expanding segment driven by attritable warfare concepts. Sensor technologies command outsized margins relative to hardware volumes, with infrared search-and-track and synthetic aperture radar systems integrating across multiple airframes.
The Federal Aviation Administration coordinates military-civilian airspace integration under Title 14 CFR, while the Defense Contract Management Agency enforces cost accounting standards on prime contractors. The Pentagon's Cybersecurity Maturity Model Certification framework now gates supplier eligibility, reshaping subcontractor access. Stakeholders must monitor how the Navy's unmanned carrier aviation program and the Air Force's Collaborative Combat Aircraft initiative redistribute platform demand between traditional primes and emerging entrants.
Market Dynamics
The Pentagon's Joint All-Domain Command and Control initiative is compressing avionics development cycles and forcing prime contractors to re-architect platform electronics for seamless interoperability across air, space, and cyber domains.
Growth Catalysts
- Army Rotary-Wing Modernization:The service branch's accelerated procurement timelines for next-generation helicopter platforms is pulling forward production slots at final assembly facilities in Texas and Arizona.
- Cybersecurity Maturity Model Certification:The DoD's CMMC framework is filtering subcontractor eligibility and consolidating supplier bases toward accredited defense industrial base participants.
- Southwest Defense Corridor Clustering:Concentrated flight test infrastructure and turbine engine manufacturing in Mesa, Arizona and surrounding counties is reducing logistics friction for integrated platform delivery.
Market Restraints
- Turbine Engine Supply Concentration:Domestic production of high-thrust powerplants above 5,000 pounds-force depends on a limited qualified supplier base concentrated in three states.
- Cost Accounting Standard Compliance:Defense Contract Management Agency enforcement of CAS 401-420 creates audit friction for mid-tier subcontractors seeking prime contractor relationships.
- Airspace Integration Friction:Title 14 CFR coordination requirements between FAA and military operators delay unmanned system test expansion in congested corridors.
Strategic Opportunities
- Collaborative Combat Aircraft Programs:The Air Force's CCA initiative opens white space for attritable drone platforms operating alongside crewed fighters in contested airspace.
- Sensor Technology Convergence:Infrared search-and-track systems are converging with synthetic aperture radar architectures, enabling multi-spectral fusion without platform-specific redesign.
- Texas-Arizona Test Range Expansion:Underutilized military operating areas in the Southwest corridor offer capacity for next-generation unmanned carrier aviation development.
Industry Challenges
- Legacy System Integration Complexity:Fourth-generation fighter sustainment requirements compete with sixth-generation development for engineering talent and simulation infrastructure.
- Software-Defined Avionics Talent Gap:Shortages in embedded systems security engineers and model-based systems architects delay JADC2-compliant platform deliveries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Military Aviation Market |
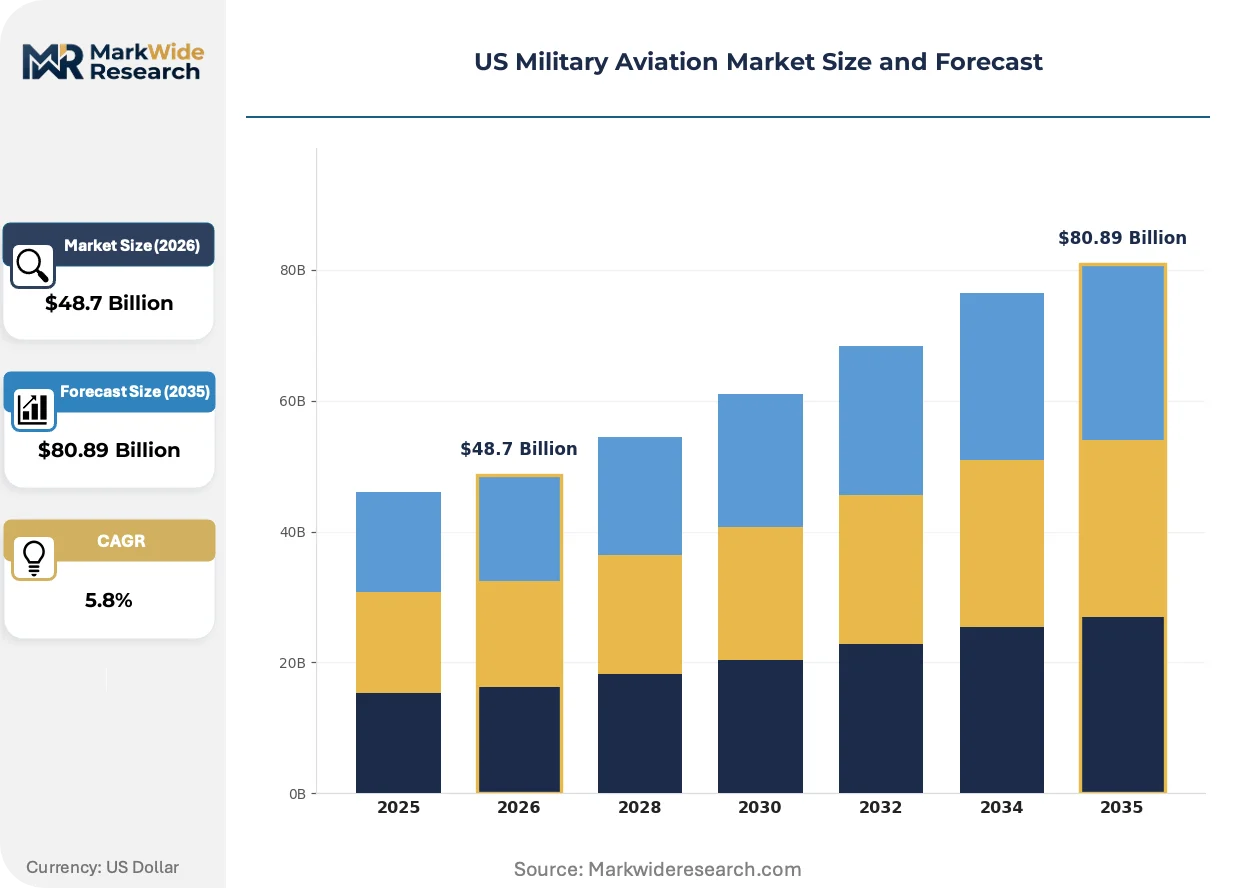
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helicopters, Fighter Jets, Transport Aircraft, Drones Technology: Avionics, Propulsion Systems, Sensor Technologies, Navigation Systems Application: Surveillance, Transport, Combat, Logistics End User: Army, Navy, Air Force, Special Operations |
| Companies Covered | Lockheed Martin Corporation, The Boeing Company, Northrop Grumman Corporation, Raytheon Technologies Corporation, General Dynamics Corporation, Textron Inc., Airbus SE, BAE Systems plc, Leonardo S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Military Aviation Market Evolving Landscape
Artificial intelligence-enabled mission systems are compressing the sensor-to-shooter timeline and redefining human-machine teaming protocols across crewed and uncrewed platforms.
Digital engineering toolchains are converging with physics-based modeling environments to enable virtual qualification of flight-critical components before physical prototype build. The Navy's unmanned carrier aviation program and Air Force CCA efforts are adopting these methods at scale, collapsing traditional development timelines by eliminating hardware-in-the-loop iteration cycles for non-safety-critical subsystems.
The Defense Contract Management Agency is tightening enforcement of Cybersecurity Maturity Model Certification Level 2 requirements across the defense industrial base supplier tier. Prime contractors are now flowing down attestation requirements to subcontractors handling controlled unclassified information, forcing smaller precision machining and composite fabrication shops to invest in security infrastructure before contract award eligibility.
Service branches are unbundling sustainment contracts from original platform procurement, creating discrete competition events for depot maintenance and operational support. The Air Force's F-35 sustainment recompete and Army Apache fleet management restructuring exemplify this pattern, shifting contractor relationships from lifecycle monopolies toward performance-based logistics competitions with shorter award periods and stricter availability metrics.
US Military Aviation Market Segmentation
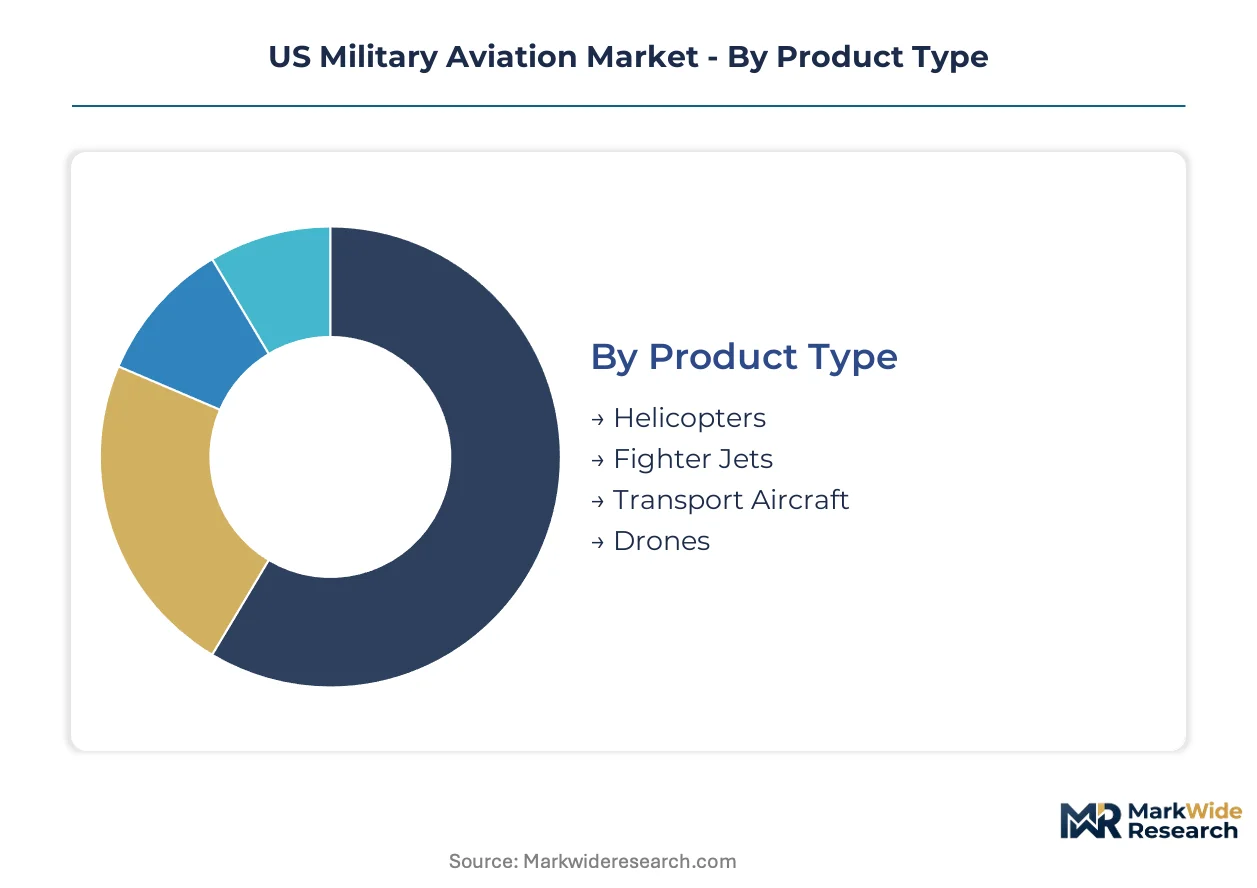
Segmentation in US military aviation exposes how procurement budgets bifurcate between survivable crewed platforms and attritable unmanned systems. Each dimension reveals distinct supply chain configurations, certification requirements, and prime contractor specialization patterns that shape competitive positioning.
Product Type:
Standalone platforms operate as complete weapon systems requiring full airworthiness certification, while embedded subsystems integrate into existing airframes under supplemental type certificate pathways.
- Fighter Jets:Crewed tactical aircraft with turbine thrust exceeding 5,000 pounds-force and nine-g structural load ratings. The Air Force's sixth-generation platform pursuit and F-35 sustainment recompete concentrate demand in Texas and Arizona final assembly corridors, though turbine engine supply concentration in three states constrains production elasticity.
- Drones:Uncrewed aerial vehicles spanning attritable tactical systems to high-altitude long-endurance platforms. The Air Force's Collaborative Combat Aircraft initiative and Navy unmanned carrier aviation program are accelerating procurement timelines for attritable platforms operating alongside crewed fighters in contested airspace.
- Helicopters:Rotary-wing platforms with vertical lift capability and turbine powerplants optimized for low-altitude maneuverability. Army modernization programs are pulling forward production slots at Mesa, Arizona facilities for next-generation helicopter deliveries.
- Transport Aircraft:Fixed-wing cargo and personnel carriers with extended range and heavy payload configurations. Strategic airlift requirements sustain demand for wide-body military derivatives and tactical intra-theater platforms.
Volume placements concentrate in Fighter Jets; the faster expansion belongs to Drones.
Technology:
Cost tiers separate flight-critical hardware from mission systems that iterate on faster commercial technology cycles.
- Sensor Technologies:Multi-spectral detection systems including infrared search-and-track and synthetic aperture radar architectures. These systems command outsized margins relative to hardware volumes and are converging toward multi-spectral fusion without platform-specific redesign, with demand concentrating across multiple airframe programs.
- Avionics:Electronic flight control, communication, and mission computing systems. The Pentagon's Joint All-Domain Command and Control initiative is compressing development cycles and forcing re-architecture for seamless interoperability across air, space, and cyber domains.
- Propulsion Systems:Turbine engines and power transmission components generating thrust above 5,000 pounds-force. Domestic production depends on a limited qualified supplier base concentrated in three states, creating supply concentration risk for high-thrust applications.
- Navigation Systems:Positioning, guidance, and landing aid electronics including GPS-denied alternatives. Anti-jam and alternative positioning requirements are driving refresh cycles independent of platform generation updates.
Revenue concentration sits with Sensor Technologies; avionics claims the steepest expansion trajectory as JADC2 compliance mandates cascade through platform programs.
Application:
Application segments map to distinct contracting vehicles and operational support requirements that shape supplier relationships.
- Combat:Kinetic strike, air-to-air engagement, and close air support missions requiring hardened platforms and weapons integration. The Air Force and Navy dominate procurement through program offices with extended development horizons and strict airworthiness protocols.
- Surveillance:Intelligence collection, target acquisition, and battlespace awareness missions. Special Operations and Air Force requirements are converging on multi-intelligence platforms with rapid sensor reconfiguration capability.
- Transport:Personnel and cargo movement across strategic and tactical distances. Army and Air Force sustainment contracts are unbundling from original procurement, creating discrete competition events for depot maintenance.
- Logistics:Supply delivery, aeromedical evacuation, and utility support missions. Demand concentrates in Army rotary-wing and Air Force fixed-wing platforms with performance-based logistics contracting.
Budget share tilts toward Combat applications; Logistics is climbing the fastest as sustainment contracts separate from platform awards.
End User:
Service branch procurement patterns reflect distinct mission profiles and basing strategies that dictate platform specifications.
- Air Force:Fixed-wing crewed and uncrewed platforms for air superiority, global strike, and intelligence missions. The service's Collaborative Combat Aircraft initiative and sixth-generation fighter pursuit are redistributing demand between traditional primes and emerging entrants.
- Army:Rotary-wing platforms for maneuver support, attack, and utility missions. Accelerated modernization timelines for next-generation helicopters are pulling forward production at Southwest corridor facilities.
- Navy:Carrier-compatible crewed fighters and uncrewed systems for maritime strike and surveillance. The unmanned carrier aviation program is adopting digital engineering methods to collapse traditional development timelines.
- Special Operations:Modified platforms for irregular warfare, infiltration, and precision strike. Requirements favor rapid fielding cycles and contractor logistics support arrangements distinct from conventional service acquisition.
Procurement volume centers on Air Force programs; Special Operations is gaining share fastest through rapid acquisition pathways and modified commercial derivatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mesa, Arizona anchors the Southwest defense corridor where Boeing's rotary-wing final assembly and Lockheed Martin's F-35 production concentrate turbine engine integration and flight test infrastructure. This clustering reduces logistics friction for integrated platform delivery across Army and Air Force programs.
Texas
Army helicopter modernization programs pull forward production slots at final assembly facilities in the Dallas-Fort Worth metroplex and Red River Army Depot corridors. The Defense Contract Management Agency enforces Cost Accounting Standards on prime contractors operating in the state. Bell Textron's Amarillo assembly plant and Lockheed Martin's Fort Worth operations anchor rotorcraft and fighter platform output for domestic and foreign military sales.
Arizona
Accelerated procurement timelines for next-generation helicopter platforms concentrate demand at Boeing's Mesa production complex and surrounding supplier networks. The Federal Aviation Administration coordinates military-civilian airspace integration under Title 14 CFR for test ranges spanning Yuma Proving Ground and Barry M. Goldwater Range. Raytheon Technologies' Tucson missile systems division and Northrop Grumman's unmanned systems development in the state support platform-agnostic sensor integration.
California
High-altitude long-endurance unmanned systems development and space-domain integration for Joint All-Domain Command and Control architectures concentrate engineering talent in Palmdale and San Diego corridors. The Pentagon's Cybersecurity Maturity Model Certification framework gates supplier eligibility for subcontractors in the state's aerospace clusters. Northrop Grumman's Palmdale facilities and General Atomics' San Diego operations anchor unmanned platform design for Navy and Air Force programs.
Washington
Strategic airlift and tanker platform sustainment requirements sustain demand for wide-body military derivatives at Boeing's Everett and Renton facilities. The state's concentrated flight test infrastructure supports certification activities for next-generation airborne early warning and transport aircraft. Supplier accreditation under CMMC Level 2 requirements is filtering subcontractor eligibility toward accredited defense industrial base participants in the Puget Sound aerospace cluster.
Florida
Special Operations rapid acquisition pathways and modified commercial derivatives for irregular warfare missions concentrate contractor logistics support arrangements in the panhandle and central Florida corridors. The state's underutilized military operating areas offer capacity for unmanned system test expansion beyond congested Southwest corridors. Eglin Air Force Base and Hurlburt Field anchor precision strike and infiltration platform requirements distinct from conventional service acquisition timelines.
US Military Aviation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the sensor-technology and propulsion-system tiers, with avionics integration commanding outsized returns relative to hardware volumes. The vendor base organizes around three strategic archetypes: full-system integrators with captive airframe production, subsystem specialists extracting value from multi-platform sensor convergence, and emerging entrants targeting attritable drone white space. Consolidation pressure is accelerating through sustainment contract unbundling and CMMC-driven supplier base filtering, while strategic partnerships around digital engineering toolchains reshape development cycle economics.
Within the full-system integrator tier, Lockheed Martin Corporation and The Boeing Company exemplify scale-driven platform dominance across crewed fighter and rotary-wing segments. Northrop Grumman Corporation occupies a specialist position in high-altitude unmanned systems and airborne early warning architectures. These three entities anchor the competitive structure through final assembly concentration in the Southwest defense corridor and turbine engine supply relationships spanning the three-state qualified supplier base.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| The Boeing Company |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| General Dynamics Corporation |
| Textron Inc. |
| Airbus SE |
| BAE Systems plc |
| Leonardo S.p.A. |
| Others |
Value Network & Pricing Analysis
Defense-industrial-base consolidation through private-equity-rolled-up precision machining specialists has tightened both turbine engine component availability and cost-accounting-standard compliance costs, forcing prime contractors to absorb audit friction or push price adjustments through sustainment recompetes.
Pricing Analysis
Value-based pricing anchored to mission-availability metrics dominates fighter and helicopter sustainment contracts, with the Air Force's F-35 recompete and Army Apache fleet management restructuring shifting from fixed-price platform awards to performance-based logistics with strict availability guarantees. Price differentiation separates CMMC Level 2-accredited suppliers commanding audit-premium positions from non-accredited shops frozen out of controlled-unclassified-information work. Pricing pressure stems from unbundled sustainment competitions compressing margin pools across depot maintenance and operational support tiers. Mid-tier subcontractors handling composite fabrication and precision machining exhibit highest price sensitivity due to CMMC infrastructure investments, while sensor technology specialists with multi-platform fusion architectures maintain lowest sensitivity through irreplaceable engineering talent.
Supply Chain Analysis
Single-source vulnerability sits with high-thrust turbine engine production concentrated across Ohio, Connecticut, and Indiana, where three qualified suppliers anchor domestic powerplant output above 5,000 pounds-force. Raw material dependencies include nickel-based superalloys for turbine blades, titanium forgings for airframe structures, and gallium arsenide substrates for infrared search-and-track sensors. Supply chain risk centers on tariff exposure for rare-earth elements feeding permanent-magnet motor production in drone propulsion systems. Distribution runs through prime contractor final assembly corridors in Mesa, Arizona and Fort Worth, Texas, with Defense Contract Management Agency oversight enforcing cost accounting standards at each tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over sensor-technology development and turbine engine supply relationships determines who captures premium-margin positions versus commodity-tier sustainment work.
For Market Incumbents: Acquire embedded systems security engineering teams and model-based systems architecture capabilities before JADC2-compliant platform delivery deadlines harden qualification requirements. Consolidate supplier accreditation support infrastructure to filter subcontractor eligibility toward CMMC-compliant participants, defending against emerging entrants exploiting attritable drone white space through rapid digital engineering adoption. For New Entrants and Emerging Players: Digital-channel routes through Defense Innovation Unit and AFWERX rapid acquisition pathways bypass traditional program office timelines, opening access to Special Operations and Air Force CCA development contracts. Target underpenetrated attritable drone segments where software-defined avionics talent gaps delay incumbent deliveries, penetrating through agile hardware-in-the-loop elimination methods and virtual qualification toolchains. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier precision machining and composite fabrication shops in Texas and Arizona facing CMMC compliance cost burdens but holding irreplaceable platform-specific tooling relationships. Long-term viability hinges on five-to-ten-year sustainment contract unbundling patterns shifting contractor relationships from lifecycle monopolies toward competitive recompete structures. Watch Air Force and Navy unmanned carrier aviation program award timelines as inflection indicators for platform demand redistribution between traditional primes and software-native entrants.| Strategic Initiative | Industry Significance |
|---|---|
| CMMC Accreditation Investment | Defense Contract Management Agency enforcement gates subcontractor eligibility for controlled-unclassified-information handling. |
| Digital Engineering Toolchain Adoption | Virtual qualification methods collapse hardware-in-the-loop iteration cycles for Navy and Air Force unmanned programs. |
| Sensor Technology Convergence | Infrared search-and-track and synthetic aperture radar fusion enables multi-spectral integration without platform redesign. |
| Sustainment Contract Unbundling | Discrete competition events for depot maintenance shift relationships from lifecycle monopolies toward performance-based logistics. |
| Southwest Defense Corridor Expansion | Mesa, Arizona and Texas final assembly clustering reduces logistics friction for integrated platform delivery. |
Research Methodology
Department of Defense budget justification documents, Federal Procurement Data System contract awards, and Defense Contract Management Agency audit filings formed the secondary backbone, cross-referenced with primary interviews involving platform program office directors, turbine engine procurement leads, CMMC accreditation consultants, and Southwest defense corridor supplier network managers. Bottom-up triangulation across individual program line items and top-down validation against service branch total obligation authority ensured segmentation coherence across fighter, drone, helicopter, and transport categories.
Historical trendline analysis of procurement obligation patterns and production slot allocations informed the projection framework across the analysis window, with segmentation modeling spanning platform type, technology tier, mission application, and service branch end user. CAGRs derived from weighted average of program office acceleration timelines and supplier capacity expansion announcements incorporated Joint All-Domain Command and Control compliance mandates and Army rotary-wing modernization pull-forward effects as demand-side inputs.
The model holds under sustained Defense Department budget authority and CMMC implementation timelines; deviation in congressional appropriation delays or turbine engine supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Europe Helicopters Market
Aircraft
Military Aircraft Market
Aircraft
North America Aviation Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
Aviation Market
Aircraft
Global Aircraft Tugs Market
Aircraft
Light and Very Light Jets Market
Aircraft
Zero-Emission Aircraft Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Aircraft Radome Market
Aircraft
Global Aircraft Design and Engineering Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Civil Helicopter Market