
 Crane Pumps Market | 2026-2036
Crane Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Crane Pumps Market Analytics
Aftermarket service contracts and predictive maintenance software is recalibrating how crane pump vendors capture lifetime value from municipal and industrial buyers. Crane Pumps & Systems leverages its integrated service network to extend equipment uptime guarantees across North American water utilities. Gorman-Rupp anchors its competitive position through specialized cast iron construction and extensive distributor channel control. Goulds Pumps sustains technology leadership in submersible wastewater applications through continuous R&D investment in corrosion-resistant metallurgy.
Crane pumps are fluid-handling machines engineered to move water, slurry, or process liquids through centrifugal force, positive displacement, or diaphragm action, typically constructed from cast iron, stainless steel, or engineered polymers to withstand pressures ranging from 50 to 500 PSI and temperatures exceeding 200°F in industrial service. Their primary purpose spans municipal water distribution, wastewater treatment, fire suppression systems, and agricultural irrigation infrastructure. Centrifugal pumps occupy the largest installed base due to their simplicity and broad flow-rate adaptability across water supply and wastewater treatment applications. Submersible pumps represent the fastest-expanding category as underground and flood-prone installation environments multiply in coastal and low-lying municipalities. Positive displacement systems command premium positioning in high-viscosity industrial process streams where precise flow control protects downstream equipment.
The EPA enforces Clean Water Act discharge limits that mandate continuous pump reliability at municipal treatment plants, while ISO 5199 and API 610 standards govern centrifugal pump construction tolerances and testing protocols for industrial service. OSHA lockout/tagout requirements and NFPA 20 fire pump installation codes further shape product design, inspection cycles, and aftermarket service obligations across commercial and institutional buildings. Stakeholders must monitor evolving PFAS remediation mandates and building electrification codes that will redefine pump material specifications and drive motor technology transitions across the installed base.
Market Dynamics
Municipal utilities across Germany, the United States, and Japan are accelerating replacement cycles for aging wastewater infrastructure while EPA and EU discharge mandates tighten reliability requirements for continuous-duty pump systems.
Growth Catalysts
- EU Water Framework Directive compliance deadlines:German and Dutch municipalities are procuring submersible systems to meet 2027 nutrient removal targets, driving specification upgrades across municipal tender pipelines.
- Industrial cast iron replacement cycles:North American chemical processors are retiring 1980s-era centrifugal installations, creating pull for corrosion-resistant metallurgy in high-temperature process streams.
- Coastal floodplain urbanization:Underground station designs in low-lying Japanese and US municipalities are multiplying submersible pump deployment in flood-prone districts.
Market Restraints
- Specialized alloy input volatility:Duplex stainless steel and nickel-based superalloy prices fluctuate with mining output from South African and Indonesian concentrate suppliers, compressing margin predictability for corrosion-resistant product lines.
- Foundry capacity concentration:Heavy cast iron pump casing production clusters in China's Hebei province and India's Tamil Nadu belt, exposing supply chains to regional energy rationing and logistics disruptions.
- Positive displacement technical ceiling:Viscous slurry handling above 10,000 centipoise remains mechanically constrained, limiting addressable market in oil sands and mining tailings applications.
Strategic Opportunities
- PFAS remediation infrastructure:US EPA drinking water mandates are creating greenfield demand for specialized extraction pump skids at municipal wellheads in contaminated groundwater zones.
- Predictive maintenance software convergence:Vibration monitoring and motor current signature analysis integration is opening recurring revenue streams beyond hardware sale economics.
- India's AMRUT 2.0 sanitation expansion:Central government funding for urban sewer network buildout is accelerating tender activity for medium-capacity submersible wastewater packages in tier-2 municipalities.
Industry Challenges
- Cross-disciplinary field engineering scarcity:Technicians combining mechanical seal expertise with PLC troubleshooting capabilities are in short supply across North American service networks, extending commissioning timelines.
- API 610 and ISO 5199 testing protocol complexity:Multi-stage centrifugal certification for refinery service requires 12-18 month validation cycles, delaying product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crane Pumps Market |
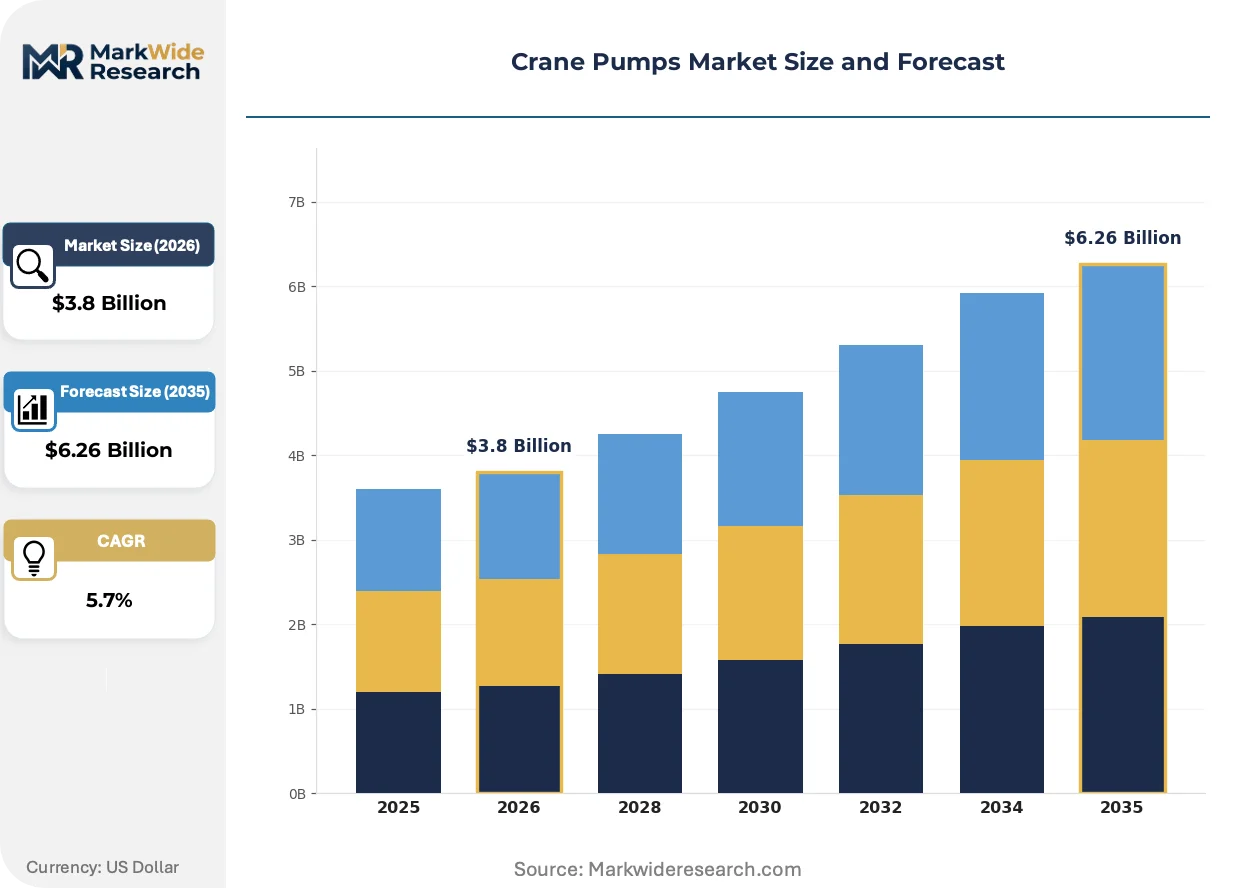
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Positive Displacement Pumps, Centrifugal Pumps, Diaphragm Pumps End User: Municipal, Industrial, Agriculture, Construction Technology: Electric, Hydraulic, Pneumatic, Mechanical Application: Water Supply, Wastewater Treatment, Fire Protection, Irrigation |
| Companies Covered | Crane Pumps & Systems, Goulds Pumps, Viking Pump, Fristam Pump, Gorman-Rupp, Barnes Pumps, Burks Pumps, Crown Pumps, Deming Pumps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crane Pumps Market Evolving Landscape
Digital instrumentation and advanced metallurgy are compressing maintenance intervals while regulatory chemistry mandates are expanding addressable applications for specialized fluid-handling architectures.
Permanent magnet synchronous motor (PMSM) technology paired with variable frequency drives is modularizing how crane pump OEMs configure powertrain packages across municipal and industrial specifications. German and Japanese water utilities are specifying integrated PMSM-VFD skids for 50-200 HP duty points, reducing energy consumption by 15-25% against conventional induction motor setups. This convergence is modularizing supplier ecosystems, enabling motor specialists and pump manufacturers to collaborate on platform designs rather than maintaining captive vertical integration.
REACH restrictions on hexavalent chromium surface treatments are forcing European foundries to convert to trivalent passivation and ceramic coating alternatives for cast iron corrosion protection. The industrial consequence is a 12-18 month qualification window for revised surface specifications across German and French pump OEMs. Submersible wastewater product lines serving North Sea offshore platforms and Baltic municipal systems are most affected, with buyers accepting premium pricing for certified low-toxicity surface finishes.
Performance-based service contracting is displacing traditional break-fix maintenance relationships across North American municipal water utilities. Chicago, Houston, and Phoenix water departments are tendering 10-15 year availability guarantees that transfer operational risk to OEM service networks. California's SB 414 water loss audit requirements are amplifying this shift, as utilities seek guaranteed uptime to avoid regulatory penalties for service interruptions.
Crane Pumps Market Segmentation
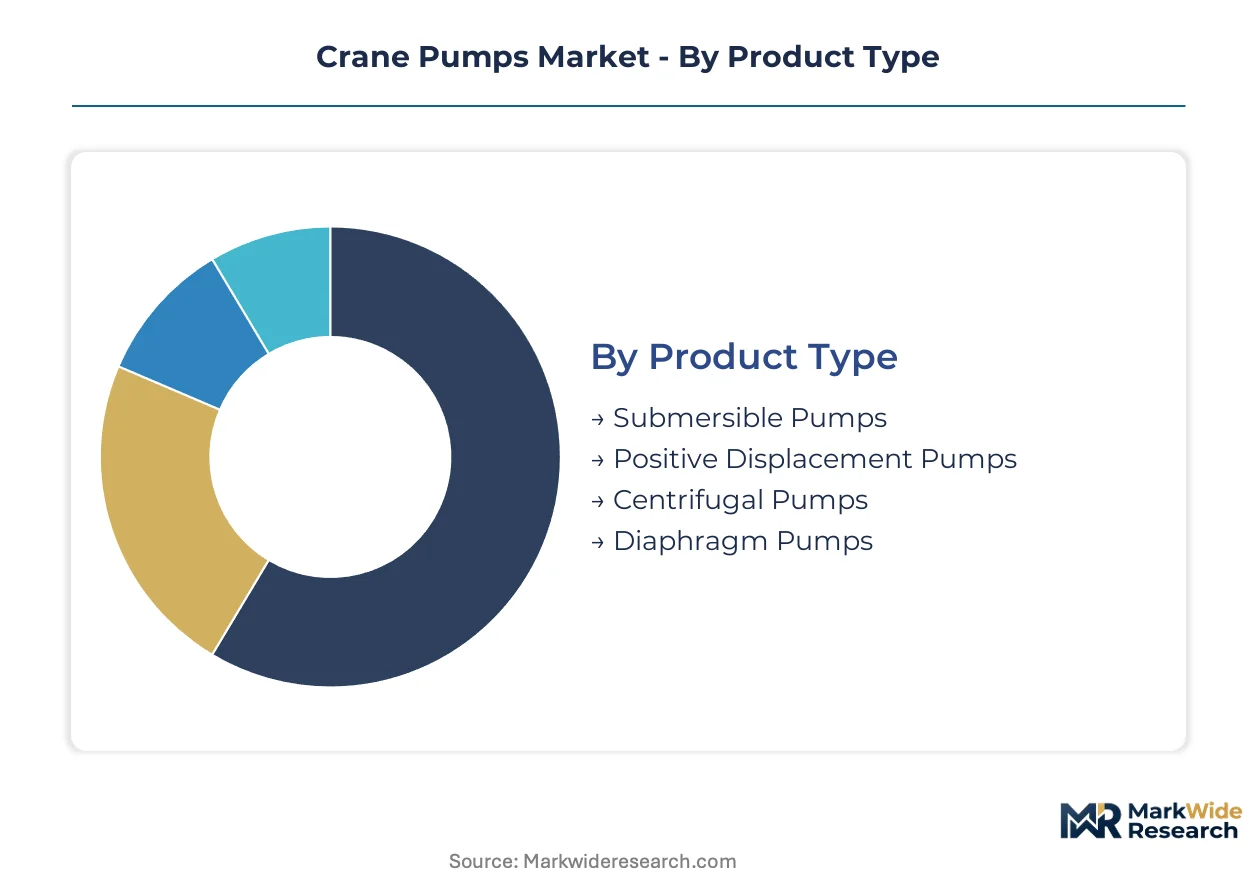
Crane pump procurement decisions hinge on installation environment, duty cycle intensity, and regulatory compliance obligations. Specification engineers balance capital cost against lifecycle energy consumption and maintenance accessibility.
Product Type:
Technical architecture determines pressure capability, efficiency curve, and seal complexity across installation scenarios.
- Centrifugal Pumps:Impeller-driven designs dominate municipal water distribution networks due to broad flow-rate adaptability and minimal moving parts. German utilities specify these for primary distribution loops where continuous duty cycles exceed 8,000 hours annually.
- Submersible Pumps:Hermetically sealed motor-pump units install below liquid level, eliminating suction lift limitations and pump house construction costs. Japanese coastal municipalities deploy these in underground flood-prone stations where space constraints and inundation risk converge.
- Positive Displacement Pumps:Reciprocating or rotary mechanisms deliver precise volumetric flow for high-viscosity industrial process streams.
- Diaphragm Pumps:Air-operated or electric elastomer diaphragm designs handle abrasive slurries and chemical transfer with zero seal leakage.
Centrifugal pumps lead on scale; submersible pumps lead on momentum.
End User:
Procurement sophistication and contract structure diverge sharply across buyer categories.
- Municipal:Public water utilities issue multi-year framework agreements with availability guarantees and predictive maintenance clauses. EPA discharge mandates and EU Water Framework Directive compliance timelines drive specification upgrades at treatment plants.
- Industrial:Chemical processors and refineries prioritize API 610 certification and corrosion-resistant metallurgy for high-temperature process streams. North American replacement cycles for 1980s-era cast iron installations are accelerating.
- Agriculture:Irrigation districts and farm cooperatives select cost-optimized centrifugal units with diesel or grid-electric powertrains.
- Construction:Dewatering contractors rent portable submersible packages for temporary site drainage and foundation work.
Municipal buyers concentrate procurement volume; industrial buyers concentrate specification premium.
Technology:
Powertrain selection shapes energy efficiency, control precision, and operational autonomy.
- Electric:Grid-connected induction and permanent magnet synchronous motors dominate stationary installations. German and Japanese utilities specify integrated PMSM-VFD skids for 50-200 HP duty points, cutting energy consumption substantially against conventional setups.
- Hydraulic:Fluid power drives deliver high torque density for mobile construction equipment and explosion-risk environments.
- Pneumatic:Compressed air operation suits hazardous area classifications where electrical ignition sources are prohibited.
- Mechanical:Direct engine or turbine coupling persists in remote agricultural and emergency fire pump applications.
Electric systems command installed base dominance; permanent magnet configurations gain share fastest.
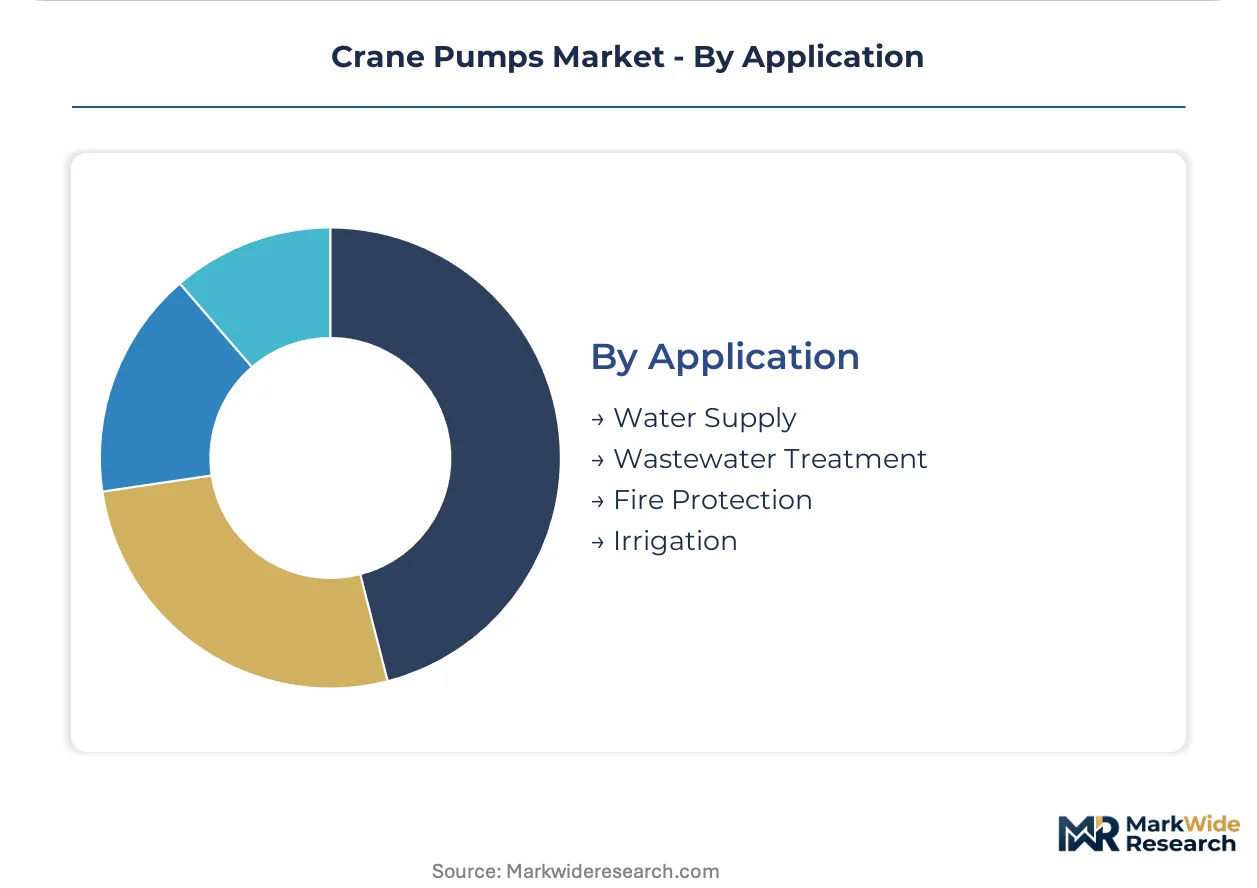
Application:
Fluid characteristics and reliability requirements dictate material selection and redundancy architecture.
- Wastewater Treatment:Abrasive solids handling and continuous duty cycles demand hardened impellers and mechanical seal monitoring. Dutch and German municipalities tender submersible systems to meet nutrient removal targets.
- Water Supply:Potable water transmission requires NSF/ANSI 61 certified materials and pressure-boosting station redundancy. Distribution networks across the United States and Japan specify cast iron or stainless steel construction.
- Fire Protection:NFPA 20 compliance mandates dedicated power supplies, automatic start sequences, and weekly test cycles.
- Irrigation:Seasonal duty patterns and abrasive groundwater favor robust, field-serviceable designs with minimal electronic complexity.
Water supply anchors volume; wastewater treatment drives technology upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of heavy cast iron pump casings clusters in China's Hebei province and India's Tamil Nadu belt, where energy rationing and logistics disruptions create compliance-cost arbitrage against European REACH-regulated foundries. This geographic split shapes competitive positioning across corrosion-resistant and standard-duty product lines.
United States
Municipal utilities in Chicago, Houston, and Phoenix are tendering 10-15 year availability guarantees that transfer operational risk to OEM service networks. EPA Clean Water Act discharge limits mandate continuous pump reliability at treatment plants. California's SB 414 water loss audit requirements amplify this shift toward performance-based contracting.
Germany
Industrial pump replacement cycles and greenfield infrastructure investments are accelerating procurement of submersible and centrifugal systems. EU Water Framework Directive compliance deadlines for 2027 nutrient removal targets drive specification upgrades. The Ruhr industrial cluster and Bavarian chemical corridor concentrate demand for API 610-certified refinery service pumps.
China
Foundry capacity concentration in Hebei province exposes supply chains to regional energy rationing and environmental compliance inspections. The country's national environmental regulator enforces dual carbon goals that reshape casting energy intensity requirements. Yangtze River Delta municipalities deploy submersible systems in underground flood-prone station designs.
Japan
Coastal municipalities deploy hermetically sealed motor-pump units in underground flood-prone stations where space constraints and inundation risk converge. METI industrial standards govern efficiency requirements for permanent magnet synchronous motor integration. The Kanto region around Tokyo anchors municipal specification leadership for 50-200 HP integrated PMSM-VFD skids.
India
Central government funding through AMRUT 2.0 for urban sewer network buildout accelerates tender activity for medium-capacity submersible wastewater packages. The Central Electricity Authority regulates motor efficiency standards for grid-connected installations. Tamil Nadu's industrial belt and Maharashtra's tier-2 municipalities concentrate procurement volume for cost-optimized centrifugal units.
Crane Pumps Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with municipal framework agreements favoring integrated service networks while industrial procurement rewards metallurgical certification depth. The vendor base organizes around three tiers: full-service OEMs with captive foundry and service infrastructure; technology licensors partnering with regional fabricators; and pure-play aftermarket service providers capturing recurring revenue from installed base maintenance. Consolidation pressure concentrates among mid-scale foundry operators facing REACH compliance cost escalation and energy intensity mandates.
Within the full-service OEM tier, Crane Pumps & Systems and Gorman-Rupp exemplify the integrated model combining captive casting capacity with North American service network density. Goulds Pumps occupies a position emphasizing submersible wastewater technology leadership through continuous investment in corrosion-resistant metallurgy. These three anchors represent distinct strategic postures: service-network scale, distributor channel control, and R&D-intensive product specialization respectively.
| Leading Market Players |
|---|
| Crane Pumps & Systems |
| Goulds Pumps |
| Viking Pump |
| Fristam Pump |
| Gorman-Rupp |
| Barnes Pumps |
| Burks Pumps |
| Crown Pumps |
| Deming Pumps |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up aftermarket service specialists are consolidating regional pump repair networks across the United States and Germany, tightening pricing discipline on multi-year availability contracts while compressing margins for independent foundry operators lacking captive service infrastructure.
Pricing Analysis
Capacity additions in India's Tamil Nadu foundry belt are reshaping price floors for standard-duty cast iron casings, forcing European REACH-regulated producers to retreat toward premium corrosion-resistant tiers. Three-tier pricing structure across premium, standard, and economy levels separates API 610-certified refinery pumps from municipal NSF/ANSI 61 units and bare-bones irrigation equipment. Cost compression in economy centrifugal segments is intensifying because Hebei province energy rationing sporadically disrupts Chinese export supply. Agricultural cooperatives exhibit highest price sensitivity; German chemical processors accept substantial premiums for documented duplex stainless steel metallurgy.
Supply Chain Analysis
Single-source vulnerability sits with South African and Indonesian concentrate suppliers of nickel and chromium for superalloy pump components. Heavy cast iron production clusters in China's Hebei province, India's Tamil Nadu belt, and Germany's North Rhine-Westphalia region. Raw material dependencies encompass duplex stainless steel, nickel-based superalloys, and engineered polymer seal faces. Tariff exposure on Chinese foundry output feeds into North American municipal procurement timelines. Distribution runs through authorized distributor networks for municipal and industrial specifications, with direct OEM contracting for large framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
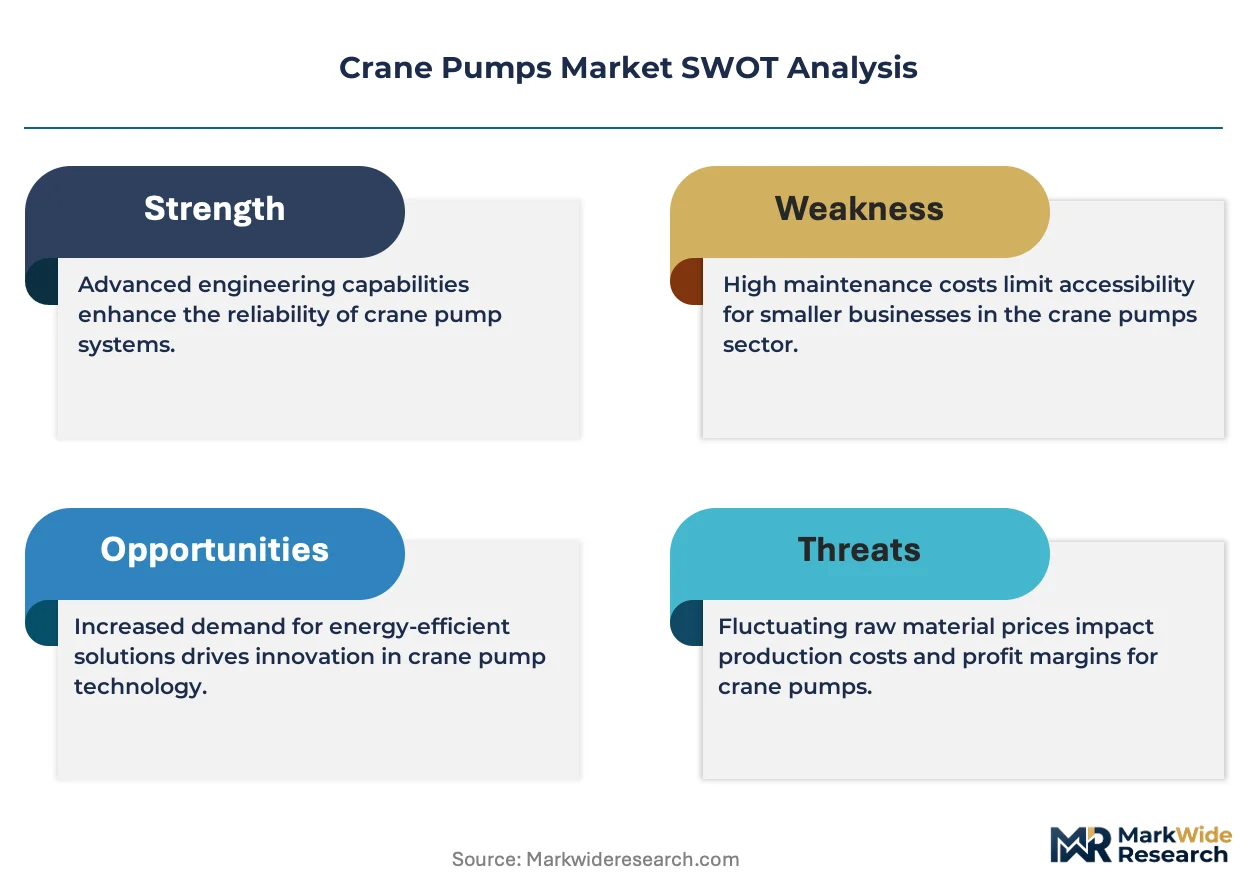
This market offers margin expansion through permanent magnet synchronous motor integration, where efficiency premiums justify 15-25% price uplifts against conventional induction configurations.
For Market Incumbents: To counter foundry cost escalation from REACH compliance and energy intensity mandates, deepen backward integration into captive casting capacity in India or consolidate regional service networks to capture recurring predictive maintenance revenue. Certification investment in API 610 and ISO 5199 testing protocols defends industrial premium positioning against mid-tier Asian competitors. For New Entrants and Emerging Players: Digital-channel routes through municipal procurement platforms and GSA schedule listings offer lower customer acquisition costs than traditional distributor relationships. White-space targets include PFAS remediation pump skids for US municipal wellheads and tier-2 Indian cities under AMRUT 2.0 sanitation expansion. Specialty corrosion-resistant metallurgy for North Sea offshore platforms represents the most penetrable premium segment. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European foundry operators facing dual carbon compliance deadlines without service network diversification. Long-term viability over the next decade hinges on aftermarket software integration and performance-based contracting capabilities. Watch for EPA PFAS enforcement acceleration as the inflection signal triggering greenfield infrastructure procurement spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive casting supply insulates margin from Hebei province energy rationing disruptions. |
| Predictive Maintenance Software Platform | Vibration monitoring integration locks in 10-15 year municipal availability contracts. |
| Permanent Magnet Motor-VFD Skid Launch | German and Japanese utility specifications reward 15-25% efficiency gains with premium positioning. |
| PFAS Remediation Pump Skid Development | EPA drinking water mandates create greenfield demand in contaminated groundwater zones. |
| REACH-Compliant Surface Treatment Conversion | Trivalent passivation certification preserves European municipal and offshore platform access. |
Research Methodology
Bottom-up municipal and industrial procurement modeling reconciled against top-down foundry capacity and trade flow tracking forms the analytical core. Primary interviews with maintenance directors at North American water utilities, OEM procurement teams at German chemical processors, aftermarket service heads, plant engineers at Indian tier-2 municipalities, and distributor channel partners informed demand-side assumptions. Secondary validation drew from EPA enforcement databases, EU Water Framework Directive implementation reports, SEC filings of listed pump manufacturers, German VDMA production statistics, and Indian Central Electricity Authority motor efficiency notifications.
Historical trendline analysis across equipment replacement cycles, regulatory compliance deadlines, and infrastructure investment programs established baseline growth parameters. Segmentation modeling incorporated product type, end-user procurement sophistication, powertrain technology, and application-specific material requirements. CAGRs were derived from installed base turnover rates and greenfield project pipelines. Forecast inputs included municipal budget authorization timelines, industrial capital expenditure survey data, and foundry energy cost trajectories.
The model assumes a particular technology adoption path; alternative pathways for permanent magnet synchronous motor penetration would alter the outlook. Forecasts reflect assumptions regarding EPA enforcement continuity, EU 2027 nutrient removal compliance adherence, and nickel alloy price stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Italy Metal Fabrication Equipment Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Static Crane Market
Construction Equipment
Construction Equipment Attachments Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Press Brakes Market
Construction Equipment
Commercial Laundry Machines Market