
 North America Welding Equipment Market | 2026-2036
North America Welding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Welding Equipment Market Insights
Automation integration across welding workflows is fragmenting traditional equipment procurement patterns as fabricators blend robotic cells with manual stations. Lincoln Electric Holdings Inc leverages its Cleveland-based R&D infrastructure to anchor premium arc welding system development. ESAB Corp competes through specialized plasma cutting and welding automation portfolios. Illinois Tool Works Inc sustains broad brand strength across Miller Electric's distribution network, dominating contractor-grade portable equipment channels.
North America welding equipment comprises power sources, torches, consumables, and auxiliary systems engineered to join metals through controlled thermal energy application, typically operating at 20–80 volts and 50–500 amperes depending on process and material thickness. The primary purpose centers on permanent metallurgical bonding for structural fabrication, repair, and manufacturing across carbon steel, stainless steel, and aluminum alloys. MIG welders lead volume shipments due to forgiving operational profiles in high-output automotive and construction environments. Laser welding represents the fastest-growing technology segment as aerospace manufacturers pursue precision joining of thin-gauge titanium and nickel superalloys. Portable equipment occupies the most contested margin pool, where rental channels and independent contractors resist premium pricing.
OSHA workplace safety standards and EPA air quality regulations shape equipment design requirements, particularly fume extraction integration and energy efficiency thresholds for fabrication facilities. NHTSA crashworthiness mandates indirectly drive welding protocol rigor across automotive OEM supply chains, elevating certification demands for resistance welding equipment. The FCC governs wireless connectivity modules in connected welding systems, creating compliance complexity for IoT-enabled fleet management. Stakeholders must monitor how CSA Group standards evolution and potential harmonization with EU machinery directives could reshape cross-border equipment certification burdens.
Market Dynamics
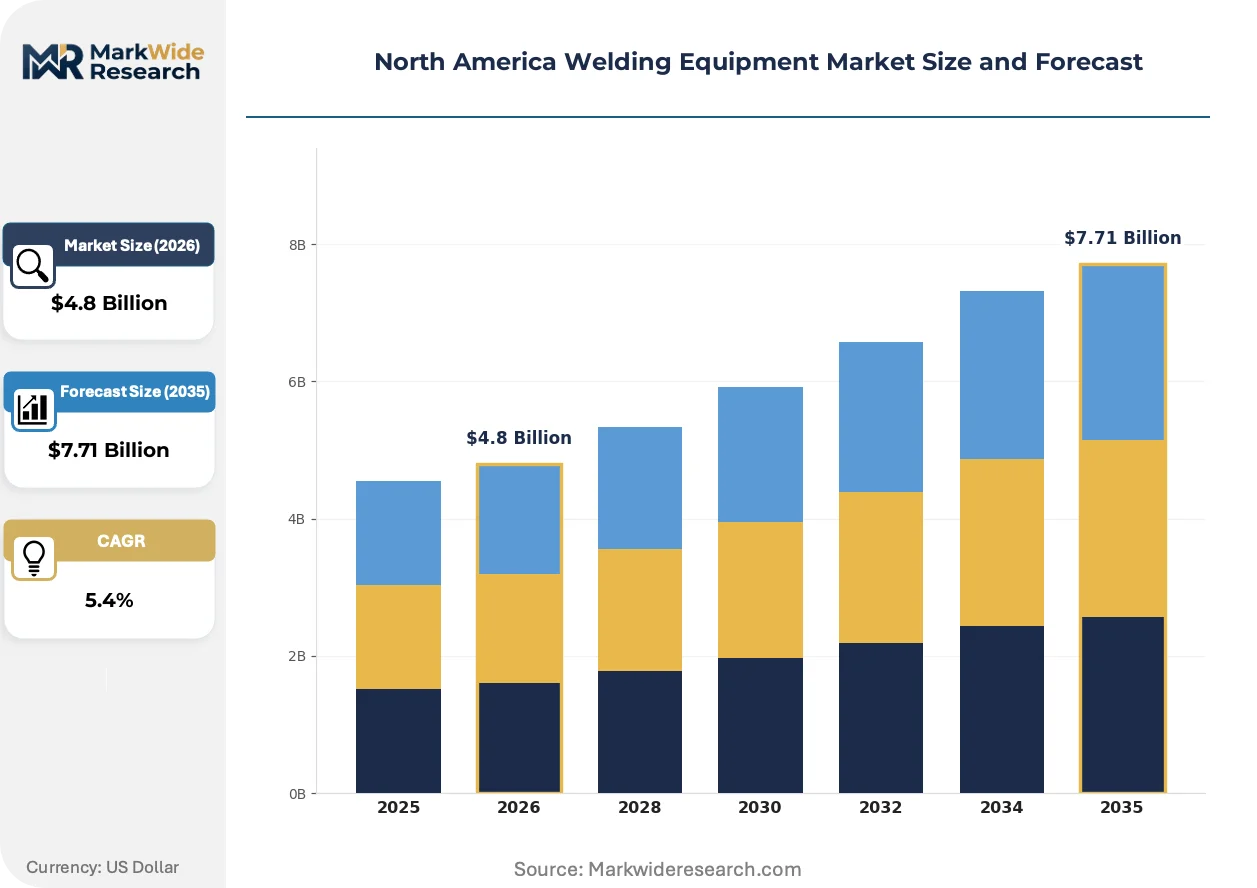
Automotive OEMs across Michigan and Ohio are accelerating automated welding cell deployment, compressing replacement cycles for legacy manual equipment and fragmenting procurement patterns between robotic and manual station blends.
Growth Catalysts
- EPA Emissions Standards:Tightened fabrication facility emissions rules under EPA jurisdiction accelerate demand for energy-efficient arc welding systems with integrated fume extraction.
- Automotive Production Clusters:Heavy machinery and automotive OEM assembly plants across the US Great Lakes industrial corridor drive concentrated equipment replacement demand.
- Laser Welding Technology:Aerospace manufacturers pursuing precision joining of thin-gauge titanium and nickel superalloys expand adoption of laser welding systems for specialized applications.
Market Restraints
- Copper and Aluminum Input Volatility:Power source manufacturing depends on copper windings and aluminum heat sinks, exposing margins to commodity price swings.
- Supply Concentration in East Asian Component Sources:Semiconductor modules and IGBT power electronics for inverter welders concentrate production in Taiwan and South Korea facilities.
- Manual Welder Skill Shortage:Aging certified welder demographics in US construction and repair sectors constrain output capacity regardless of equipment availability.
Strategic Opportunities
- Mexican Nearshoring Expansion:Automotive and appliance manufacturing relocation to Nuevo León and Chihuahua creates underpenetrated demand for automated welding infrastructure.
- OSHA Silica and Fume Mandates:Workplace safety enforcement creates regulatory tailwind for integrated extraction systems and low-fume consumable formulations.
- IoT-Enabled Fleet Management:FCC-governed wireless connectivity modules enable predictive maintenance service models and usage-based equipment financing.
Industry Challenges
- AWS Certification Timeline Compression:Accelerated welder qualification demands strain training infrastructure and extend deployment lead times for certified automation technicians.
- Legacy Equipment Integration Friction:Retrofitting robotic cells into existing manual welding bays requires custom fixture engineering and disrupts production continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Welding Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MIG Welders, TIG Welders, Stick Welders, Multi-Process Welders End User: Automotive OEMs, Construction Companies, Aerospace Manufacturers, Shipbuilding Firms Technology: Arc Welding, Resistance Welding, Laser Welding, Electron Beam Welding Size: Portable, Compact, Medium, Industrial |
| Companies Covered | Lincoln Electric Holdings Inc, ESAB Corp, Illinois Tool Works Inc, Miller Electric Mfg. LLC, Coherent Corp, Panasonic Industry, OTC DAIHEN, voestalpine AG, ACRO Automation Systems Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Welding Equipment Market Trends and Innovations
Welding equipment architecture is converging around sensor fusion, adaptive control algorithms, and cloud-connected fleet monitoring, compressing the gap between manual operator skill and automated output consistency.
Artificial vision and seam-tracking systems are digitizing weld pool geometry monitoring in real time. Automotive OEMs in Ohio and Michigan deploy these systems across resistance welding stations for body-in-white assembly. The technology is digitizing quality assurance workflows by replacing post-weld inspection with in-process defect detection.
OSHA workplace safety standards and EPA air quality regulations are tightening fume exposure thresholds for fabrication facilities. Equipment manufacturers must integrate extraction systems at the design stage rather than as aftermarket attachments. MIG and flux-cored welding operations in heavy machinery plants face the steepest compliance retrofit requirements.
Equipment-as-a-service financing models are displacing outright purchase in contractor segments. Independent welding contractors across Texas and Florida now favor rental channels with bundled maintenance over capital ownership. The shift concentrates procurement authority with national distributor networks and compresses manufacturer direct sales margins.
North America Welding Equipment Market Segmentation
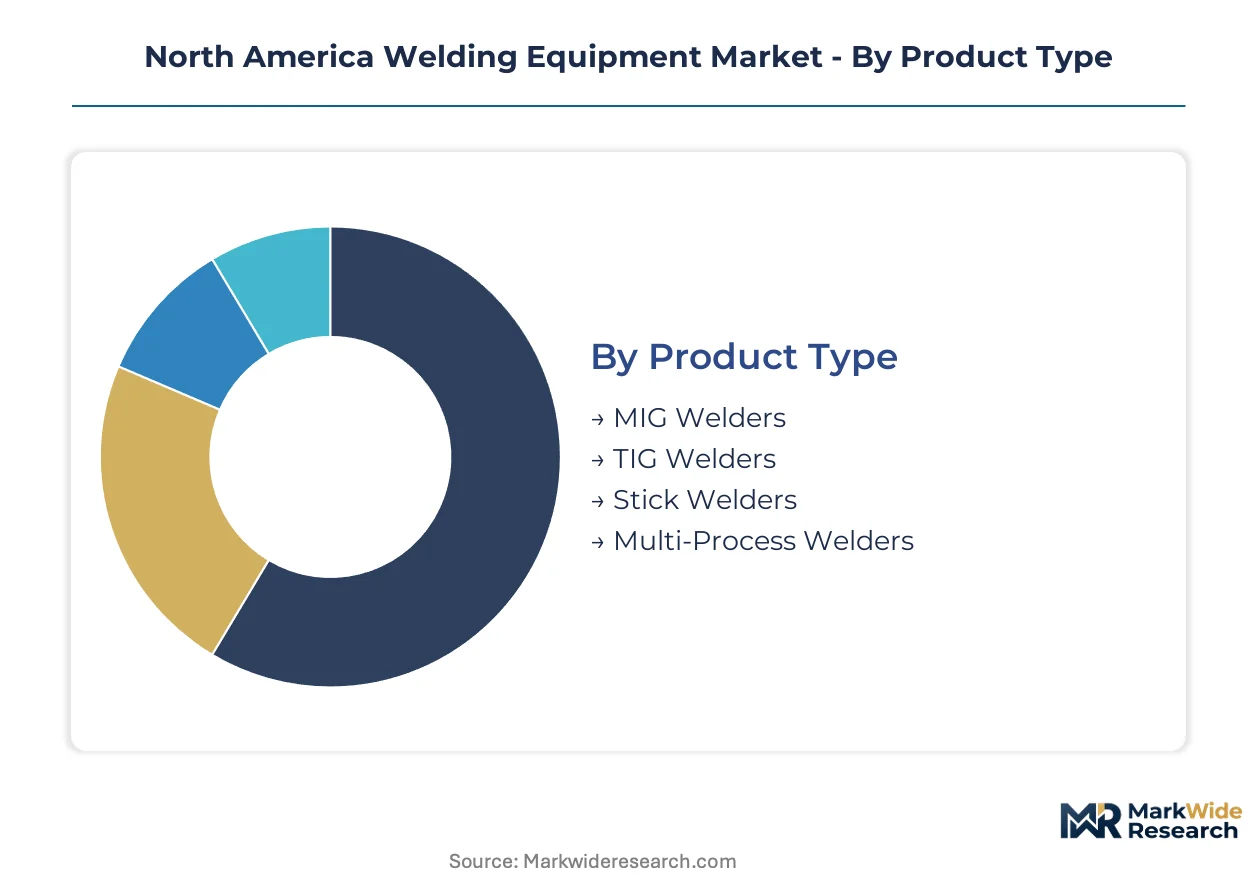
Welding equipment segmentation in North America reflects divergent maturity curves across process technologies and end-use applications. Procurement patterns fragment between high-volume automotive automation and dispersed contractor-grade portability requirements.
Product Type:
Mature arc processes dominate volume shipments while multi-process platforms emerge as the convergence play for capital-constrained fabricators.
- MIG Welders:Gas metal arc welding systems operate with continuous wire feed at 20-40 volts, delivering deposition rates exceeding 8 lbs/hour in carbon steel applications. Automotive OEMs across Michigan and Ohio specify MIG cells for body-in-white assembly, driven by forgiving operational profiles and high-duty cycle requirements. MIG welders retain volume leadership; multi-process welders hold the steepest expansion curve.
- TIG Welders:Tungsten inert gas systems provide precision control down to 5 amps for thin-gauge stainless and aluminum, requiring skilled operator intervention. Aerospace manufacturers in California and Washington specify TIG for titanium airframe joints where heat input control determines metallurgical integrity.
- Stick Welders:Shielded metal arc units remain the default for outdoor construction and repair, operating without external shielding gas. Independent contractors across Texas favor stick equipment for structural steel erection where wind disrupts gas-shielded processes.
- Multi-Process Welders:Inverter-based platforms switch between MIG, TIG, and stick modes through software configuration. Small fabrication shops in Pennsylvania and Illinois adopt these units to consolidate equipment footprints and reduce capital deployment.
MIG welders command the largest installed base; multi-process configurations are climbing the fastest as fabricators prioritize capital efficiency.
End User:
Customer concentration varies sharply, with automotive OEMs driving automated system demand while construction maintains fragmented procurement.
- Automotive OEMs:Original equipment manufacturers operate resistance welding cells at 10,000+ ampere outputs for unibody construction. Ford, General Motors, and Stellantis facilities across Detroit, Cleveland, and Chicago compress replacement cycles as EPA emissions standards mandate energy-efficient arc system upgrades. Automotive OEMs anchor equipment volume; aerospace manufacturers represent the fastest-climbing demand segment.
- Construction Companies:General contractors and steel erectors deploy portable equipment across dispersed job sites. OSHA silica enforcement in New York and California drives rental channel preference for integrated fume extraction units.
- Aerospace Manufacturers:Precision joining requirements for nickel superalloys and titanium alloys demand laser and electron beam systems with beam positioning accuracy below 0.1 mm. Boeing and Lockheed Martin operations in Washington and Texas specify automated seam tracking for thin-gauge applications.
- Shipbuilding Firms:Heavy plate fabrication in Virginia and Louisiana requires submerged arc and flux-cored systems for thick-section carbon steel. US Navy vessel programs sustain demand for certified welding protocols under NHTSA-influenced quality mandates.
Automotive OEMs concentrate procurement authority; aerospace manufacturers are expanding most quickly as defense and commercial aviation programs scale.
Technology:
Process selection maps directly to material thickness, joint geometry, and throughput requirements across the maturity spectrum.
- Arc Welding:Consumable electrode processes including MIG, TIG, and stick dominate structural fabrication. EPA tightened emissions standards for fabrication facilities accelerate inverter-based arc system replacement across Ohio and Indiana heavy machinery plants.
- Resistance Welding:Electric current and mechanical pressure join sheet metal without filler material. Automotive body-in-white assembly lines in Michigan deploy servo-electric spot welding guns with adaptive current control for aluminum-intensive vehicle architectures.
- Laser Welding:Concentrated coherent beam energy achieves penetration depths exceeding 10mm in titanium with heat-affected zones under 0.5mm. Aerospace manufacturers in California and Washington expand laser cell adoption for engine component joining where distortion control is critical.
- Electron Beam Welding:High-velocity electrons in vacuum chambers produce deep, narrow welds in refractory metals. Defense contractors in Connecticut and Arizona specify EB welding for nuclear and space applications requiring full penetration in thick sections.
Arc welding retains installed base dominance; laser welding posts the steepest technology trajectory as precision requirements intensify.
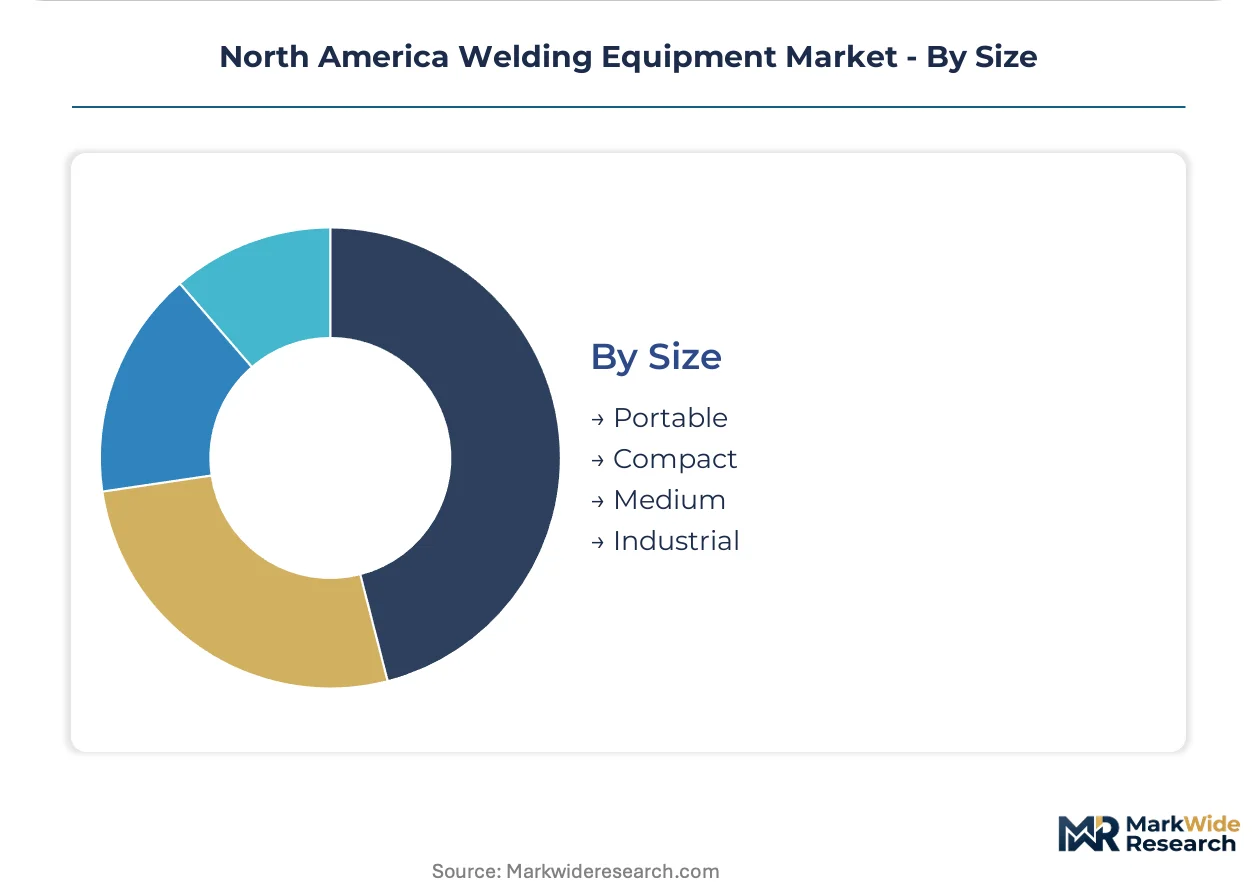
Size:
Equipment form factor determines channel strategy, with portability commanding rental penetration and industrial scale anchoring direct manufacturer relationships.
- Portable:Units under 50 lbs operate on 120V or 240V single-phase input for field repair and maintenance. Independent contractors across Florida and Texas favor rental channels with bundled maintenance over capital ownership, compressing manufacturer margins.
- Compact:Shop-grade systems under 200 lbs serve small fabrication operations with intermittent duty cycles. Machine shops in Wisconsin and Minnesota specify compact MIG units for job shop environments with limited floor space.
- Medium:Three-phase industrial equipment at 300-600 ampere output serves dedicated production cells. Heavy machinery manufacturers in Illinois deploy medium TIG systems for stainless steel component fabrication with precision requirements.
- Industrial:Automated cells with robotic integration and real-time seam tracking exceed 500,000 USD system cost. Automotive OEMs in Ohio and Michigan specify industrial-scale resistance welding lines with adaptive control algorithms for mixed-material vehicle programs.
Portable equipment commands the broadest channel penetration; industrial systems are gaining share fastest as automation integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican welding equipment exports flow primarily to automotive assembly plants across the US Great Lakes corridor, creating a tightly coupled regional supply chain that concentrates procurement authority in cross-border industrial zones.
United States
EPA tightened emissions standards for fabrication facilities accelerate inverter-based arc system replacement across Ohio and Indiana heavy machinery plants. OSHA silica enforcement drives integrated fume extraction mandates in construction and repair sectors. Detroit, Cleveland, and Chicago anchor automated welding cell deployment for Ford, General Motors, and Stellantis unibody construction programs.
Canada
Ontario and Quebec shipbuilding programs sustain demand for submerged arc systems under Transport Canada vessel certification requirements. Health Canada workplace safety guidelines align with OSHA thresholds for fume exposure in fabrication environments. Vancouver and Halifax maritime clusters deploy certified welding protocols for naval and commercial vessel construction.
Mexico
Nuevo León and Chihuahua automotive nearshoring expansion creates underpenetrated demand for automated welding infrastructure serving US supply chains. Mexican environmental regulators tighten industrial emissions protocols for maquiladora facilities. Monterrey and Ciudad Juárez assembly plants compress equipment replacement cycles as OEMs relocate capacity from Asia.
North America Welding Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement patterns that separate automotive OEM direct relationships from contractor rental networks. The vendor base clusters around three strategic archetypes: Cleveland-anchored premium system developers, diversified industrial conglomerates with welding portfolios, and specialized automation integrators. Dominant competitive moves include backward integration into consumables manufacturing and geographic expansion into Mexican nearshoring corridors.
Among diversified industrial conglomerates, Illinois Tool Works Inc and Lincoln Electric Holdings Inc exemplify scale-driven positioning across multiple welding technology tiers. ESAB Corp occupies a specialist position within plasma cutting and automation portfolios. These three entities represent contrasting strategic postures: conglomerate breadth versus focused specialization versus integrated premium system development.
| Leading Market Players |
|---|
| Lincoln Electric Holdings Inc |
| ESAB Corp |
| Illinois Tool Works Inc |
| Miller Electric Mfg. LLC |
| Coherent Corp |
| Panasonic Industry |
| OTC DAIHEN |
| voestalpine AG |
| ACRO Automation Systems Inc |
| Others |
Pricing and Supply Chain Analysis
Port of Long Beach container throughput volatility feeds directly into welding equipment landed costs, compressing margins for distributors serving Great Lakes automotive clusters while amplifying price spreads between inverter-based systems and legacy transformer welders. This freight corridor instability reinforces supplier concentration power in premium automation segments.
Pricing Analysis
Inverter-generation welders command 40-60% premiums over transformer-era equipment, with next-generation laser cells widening the gap further. Three-tier pricing structure across premium automation, standard industrial, and economy portable levels stratifies by duty cycle certification and IoT connectivity bundling. Cost compression in contractor-grade portable equipment intensifies as rental channels consolidate procurement authority. Independent welding contractors exhibit highest price sensitivity; aerospace OEMs accept premium positioning for precision beam systems.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for power electronics sourcing. IGBT modules and semiconductor controls concentrate production in Taiwan, South Korea, and China, with copper windings and aluminum heat sinks drawing from Chilean and Canadian smelters. Single-source vulnerability in advanced inverter components threatens equipment lead times. Distribution runs through national rental networks and OEM direct sales channels, with Mexican nearshoring corridors gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Welding equipment markets approach a platform-economics inflection as IoT-enabled fleet management and predictive maintenance interoperability reshape vendor-customer relationships. AWS certification digitization and cross-OEM data standards will determine ecosystem control points.
For Market Incumbents: Entrench position through captive consumables manufacturing and backward integration into wire electrode production. Lincoln Electric and Illinois Tool Works must defend against specialized automation integrators by locking in multi-year service contracts with Detroit-area automotive OEMs. Certification digitization investment represents the priority capability lever. For New Entrants and Emerging Players: Mexican nearshoring corridors in Nuevo León and Chihuahua present the most penetrable geographic whitespace. Automated welding cell demand from relocated appliance and automotive assembly plants outpaces established distributor coverage. Target mid-tier fabricators with equipment-as-a-service financing models bundled with maintenance. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming welding automation divisions. Long-term viability hinges on software-defined control architecture and data monetization potential. Monitor AWS certification timeline compression as the inflection signal for training infrastructure bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Consumables | Lincoln Electric's electrode manufacturing captive supply secures margin control against commodity volatility. |
| Mexican Manufacturing Footprint Expansion | ESAB's Monterrey facility positions for automotive nearshoring demand from Stellantis and GM suppliers. |
| IoT Platform Standardization | Miller Electric's wireless connectivity modules require FCC compliance for fleet management service models. |
| Laser Welding Technology Licensing | Coherent Corp's beam source partnerships penetrate aerospace titanium joining applications in Washington state. |
| Certification Digitization Investment | AWS qualification compression demands training infrastructure scaling across Ohio and Michigan technical colleges. |
Research Methodology
A spread of perspectives from plant engineers, OEM procurement teams, aftermarket service directors, and rental channel operators converged on the working assumptions driving this analysis. Primary fieldwork with maintenance directors at heavy machinery manufacturers and welding automation specialists at Tier 1 automotive suppliers combined with secondary validation from EPA emissions filings, OSHA enforcement databases, SEC 10-K equipment disclosures, and customs trade records. Bottom-up equipment shipment tallies triangulated against top-down fabrication facility capex surveys.
Demand-supply balance dynamics anchored the forecast framework across the analysis window, with segmentation modeled by process technology, end-use application, equipment size tier, and regional industrial cluster. CAGRs derived from replacement cycle analysis, automation penetration curves, and regulatory compliance deadlines. Specific inputs included EPA emissions standard implementation timelines and AWS certification throughput capacity at US technical training centers.
Practitioners should monitor copper and aluminum commodity volatility, semiconductor module availability from East Asian foundries, and Mexican environmental regulatory evolution for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
Vibratory Rammer Market
Construction Equipment
Construction Lasers Market
Construction Equipment
Bale Openers Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Excavator Augers Market
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Autonomous Heavy Equipment Market
Construction Equipment
Grout Bags Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
LAMEA Mini Excavators Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market