
 North America Construction Equipment Market | 2026-2036
North America Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Construction Equipment Market Analytics
Data center construction across the United States is expanding demand for heavy earthmoving fleets. Caterpillar Inc. leverages its integrated powertrain manufacturing to anchor supply agreements with tier-one contractors. Komatsu Ltd. competes through telematics-enabled fleet management systems that reduce idle time on large-scale sites. Deere & Company differentiates via precision grading technology tied to its SmartGrade platform.
North America construction equipment comprises self-propelled and towed machinery engineered for earthmoving, lifting, and material placement, with hydraulic systems operating at pressures exceeding 3,000 PSI to deliver breakout forces above 50,000 lbf for primary excavation tasks. The product category serves commercial building, mining extraction, and transportation infrastructure development across varied terrain and climatic conditions. Excavators and loaders command the largest installed base, while electric and hybrid technologies represent the fastest-expanding technology segment as contractors face emissions compliance deadlines. Hydraulic systems retain dominance in high-duty-cycle mining applications where power density requirements exceed current battery-electric capabilities.
The EPA Tier 4 Final standards and California Air Resources Board off-road regulations mandate diesel particulate filters and selective catalytic reduction across engines above 25 horsepower, elevating equipment costs and accelerating rental fleet turnover. The US Department of Transportation Buy America provisions and Infrastructure Investment and Jobs Act funding stipulations shape procurement eligibility for federally backed projects. OSHA excavation safety standards influence trenching equipment specifications and operator training investments. Stakeholders must weigh electrification capital requirements against regulatory compliance timelines and residual value risk in used equipment channels.
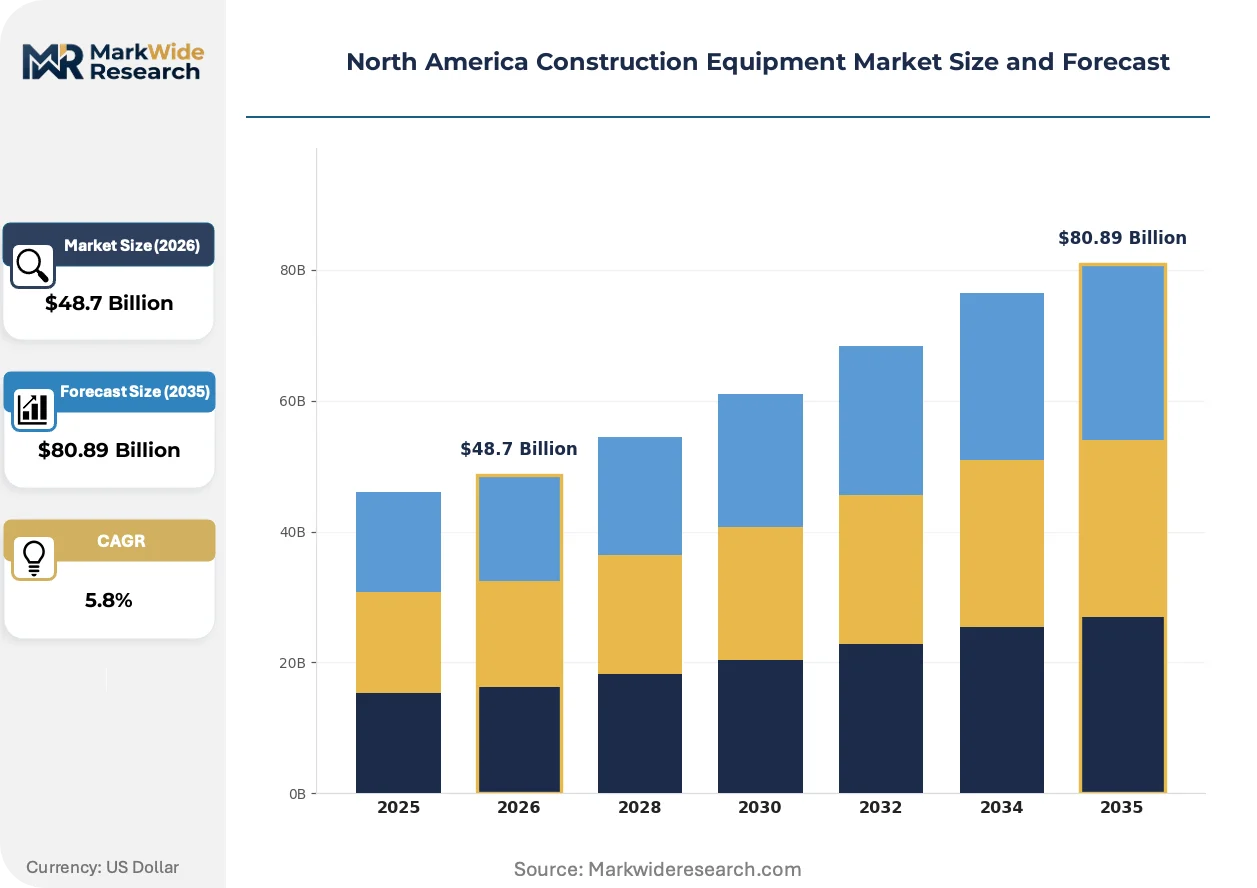
Market Dynamics
EPA Tier 4 Final compliance deadlines and electrification capital requirements are compressing fleet replacement cycles while reshaping procurement priorities across contractor tiers.
Growth Catalysts
- Infrastructure Investment and Jobs Act:Federal funding pipelines for transportation and broadband projects are accelerating equipment deployment timelines across Texas, California, and Ontario corridors.
- Data center construction:Hyperscale facility builds are expanding demand for hydraulic excavators and material handlers with extended reach specifications.
- Telematics integration:Fleet management platforms that reduce idle time are pulling replacement demand from cost-conscious rental operators.
Market Restraints
- After-treatment cost inflation:Diesel particulate filters and selective catalytic reduction systems mandated by EPA Tier 4 Final have elevated engine costs by double-digit percentages.
- Power density limitations:Battery-electric systems cannot yet match hydraulic breakout forces above 50,000 lbf in high-duty-cycle mining applications.
- Residual value uncertainty:Electrification transition timelines are compressing resale values for Tier 4 Final diesel assets in secondary markets.
Strategic Opportunities
- Precision grading automation:Integration of machine control systems with GPS and LiDAR is opening premium pricing tiers for earthmoving contractors.
- Rental fleet electrification:California Air Resources Board off-road regulations are creating first-mover advantages for zero-emission equipment lessors.
- Mexico infrastructure corridor:Nearshoring manufacturing expansion is generating greenfield construction demand for compact equipment categories.
Industry Challenges
- Technician certification gaps:High-voltage system servicing requires OSHA-compliant training programs that most dealer networks have not scaled.
- Software-hardware integration:Legacy hydraulic architectures resist seamless integration with telematics platforms without extensive retrofit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Construction Equipment Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Cranes, Graders End User: Mining, Infrastructure, Residential, Commercial Technology: Hydraulic, Electric, Autonomous, Hybrid Application: Earthmoving, Demolition, Material Handling, Road Construction |
| Companies Covered | Caterpillar Inc., Deere & Company, Komatsu Ltd., Volvo Construction Equipment, CNH Industrial, Hitachi Construction Machinery, Terex Corporation, Manitowoc Company, Inc., Doosan Bobcat, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Construction Equipment Market Evolving Landscape
Electrification architectures and autonomous control systems are converging to redefine equipment performance benchmarks and ownership economics across contractor segments.
Battery-electric powertrains with modular pack configurations are rewriting duty-cycle assumptions for urban construction sites. Municipal contractors in California and Ontario are piloting 20-ton-class electric excavators for noise-restricted zones. The technology is compressing total cost of ownership calculations by eliminating diesel logistics and after-treatment maintenance.
EPA Tier 4 Final and California Air Resources Board off-road regulations are mandating real-time emissions monitoring via onboard diagnostics. Engine manufacturers must now architect systems with permanent data logging capabilities. Mining operators in Nevada and Arizona are responding by accelerating fleet turnover to avoid compliance penalties on aging assets.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-tier earthmoving contractors. Rental companies are unbundling maintenance and telematics subscriptions into usage-based fee structures. Texas infrastructure contractors are driving this shift, prioritizing balance sheet flexibility over equipment ownership during stimulus-funded project ramps.
North America Construction Equipment Market Segmentation
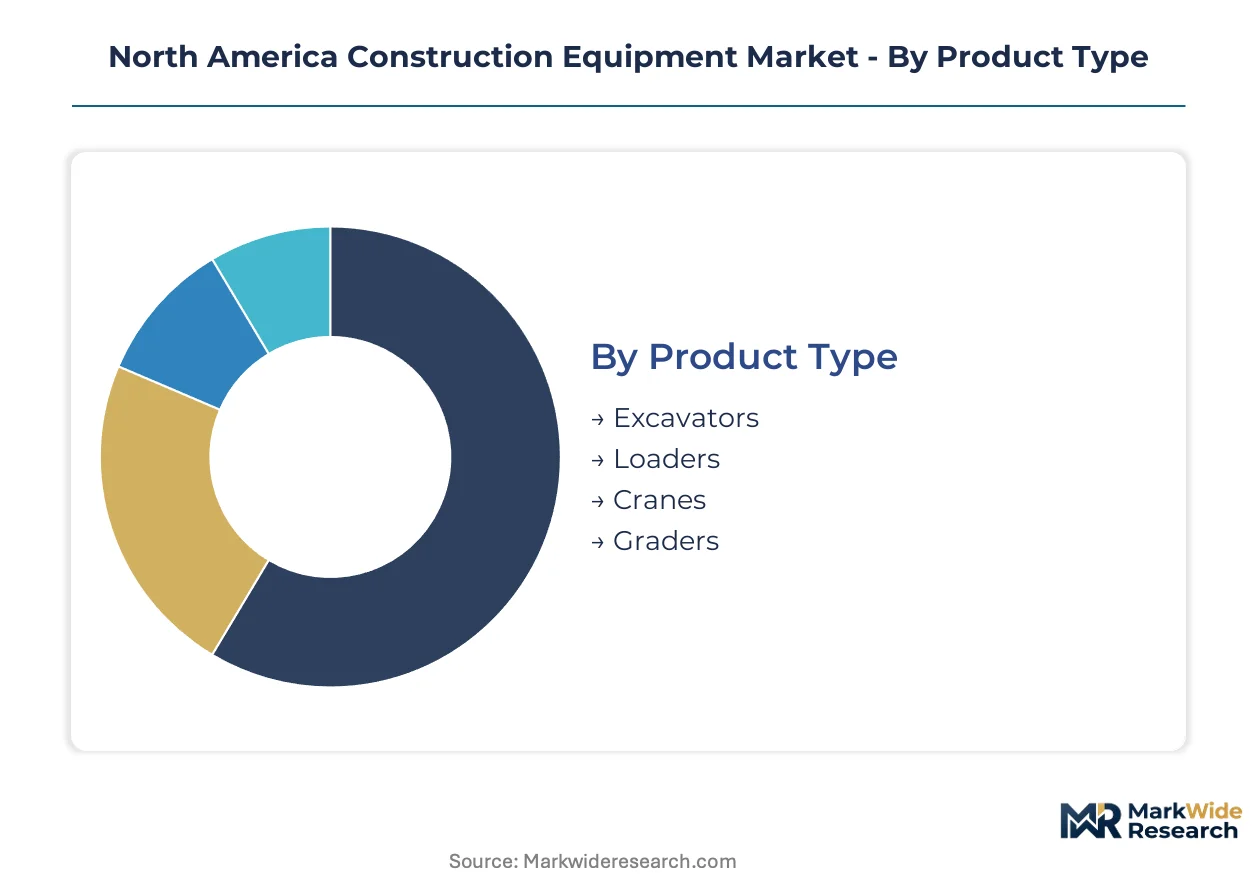
Segmentation in North American construction equipment reveals distinct capital requirements and technology adoption curves across contractor tiers. Mining operators prioritize power density while municipal fleets face accelerating electrification mandates.
Product Type:
Capital intensity varies dramatically across equipment categories, with mining-class excavators demanding the highest upfront investment.
- Excavators:Hydraulic systems operating above 3,000 PSI deliver breakout forces exceeding 50,000 lbf for primary excavation tasks. Mining operators in Nevada and Arizona concentrate orders for 20-ton-class units as EPA Tier 4 Final deadlines compress replacement cycles.
- Loaders:Wheel and track configurations dominate material placement with rated operating loads spanning 2,000 to 20,000 pounds. Texas infrastructure contractors are expanding fleet orders for extended-reach specifications to serve data center construction corridors.
- Cranes:Mobile and crawler configurations serve vertical lifting requirements across commercial building sites.
- Graders:Precision grading platforms integrate GPS and LiDAR for road construction applications.
Most installed capacity flows through excavators. Expansion is steepest in graders as precision automation commands premium pricing.
End User:
Customer type determines procurement patterns, with mining operators favoring ownership and infrastructure contractors shifting toward rental models.
- Mining:High-duty-cycle extraction operations in Nevada, Arizona, and Ontario require hydraulic powertrains where battery-electric systems cannot yet match density requirements. EPA Tier 4 Final compliance is accelerating fleet turnover to avoid penalties on aging assets.
- Infrastructure:Federal stimulus funding through the Infrastructure Investment and Jobs Act is expanding deployment timelines across Texas and California corridors. Contractors prioritize balance sheet flexibility through equipment-as-a-service contracting.
- Residential:Single-family and multi-family construction drives compact equipment demand.
- Commercial:Data center builds are expanding orders for material handlers with extended reach specifications.
Mining commands the highest equipment utilization rates. Infrastructure is gaining share fastest as stimulus funding flows accelerate.
Technology:
Powertrain architecture separates mature hydraulic platforms from emerging electric and autonomous systems with divergent cost structures.
- Hydraulic:Dominant architecture for mining applications where duty cycles exceed current battery capabilities. Systems retain installed base leadership despite after-treatment cost inflation from EPA Tier 4 Final mandates.
- Electric:Modular battery configurations are rewriting total cost of ownership for urban construction. California and Ontario municipal contractors pilot 20-ton-class electric excavators for noise-restricted zones.
- Autonomous:Machine control systems with GPS and LiDAR integration enable precision grading automation.
- Hybrid:Combines diesel range with electric efficiency for transitional duty cycles.
Hydraulic systems retain the largest installed base. Electric configurations are climbing the fastest as CARB off-road regulations tighten.
Application:
Functional specialization determines equipment specifications, with earthmoving commanding the broadest fleet requirements.
- Earthmoving:Excavators and loaders perform mass excavation, grading, and trenching across varied terrain. Texas data center construction is expanding demand for hydraulic excavators with extended reach specifications.
- Demolition:Specialized attachments and reinforced cabs serve structural takedown operations in urban environments.
- Material Handling:Telehandlers and forklifts manage logistics on large-scale commercial sites.
- Road Construction:Graders, pavers, and compactors serve transportation infrastructure development.
Earthmoving absorbs the majority of fleet investment. Road construction is expanding most quickly as Infrastructure Investment and Jobs Act funding deploys.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement patterns diverge sharply across North America as regulatory cost differentials reshape fleet deployment strategies. Contractors in jurisdictions with accelerated emissions deadlines face compressed replacement cycles, while operators in less stringent markets exploit arbitrage opportunities in secondary equipment channels.
United States
Data center construction corridors in Texas and Virginia are absorbing record volumes of hydraulic excavators with extended-reach specifications. EPA Tier 4 Final compliance deadlines are forcing Nevada and Arizona mining operators into accelerated fleet turnover to avoid penalties on aging diesel assets. Fleet concentration is densest in the Permian Basin where oilfield services contractors maintain parallel equipment pools for extraction and midstream infrastructure.
Canada
Ontario mining operations in the Sudbury Basin and Ring of Fire districts require high-duty-cycle hydraulic powertrains that battery-electric systems cannot yet match. Federal Infrastructure Canada funding pipelines are accelerating deployment timelines across the Quebec City-Windsor corridor. Alberta oil sands contractors are diversifying fleet composition toward material handlers as tailings pond remediation mandates expand.
Mexico
Nearshoring manufacturing expansion across Nuevo León and the Bajío Region is generating greenfield construction demand for compact equipment categories. Mexican federal environmental standards lag EPA Tier 4 Final implementation, creating cost-of-compliance arbitrage for used equipment imports from US rental fleets. Monterrey anchors the densest contractor equipment concentration as automotive and electronics manufacturing facilities multiply.
North America Construction Equipment Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment manufacturers seek technology licensing agreements to bridge electrification capability gaps. The vendor base stratifies across three tiers: integrated powertrain specialists, telematics platform providers, and regional fabrication houses serving niche duty-cycle requirements. Two strategic archetypes have emerged—full-line manufacturers leveraging captive component production, and technology licensors monetizing control-system IP. Competitive intensity concentrates on portfolio diversification into electric architectures and geographic expansion into Mexico's infrastructure corridor.
Among North American full-line manufacturers, Caterpillar Inc., Deere & Company, and Komatsu Ltd. exemplify the integrated powertrain archetype. Caterpillar anchors the mining and heavy infrastructure tier through captive manufacturing of engines and hydraulic systems. Deere occupies a position within precision agriculture-adjacent construction segments where SmartGrade automation commands premium positioning. Komatsu sits within the telematics-enabled fleet management tier, reducing operator idle time through machine-level data analytics. Each represents a distinct competitive vector—captive supply chain control, precision automation integration, and connected fleet optimization—rather than direct product overlap.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Deere & Company |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| CNH Industrial |
| Hitachi Construction Machinery |
| Terex Corporation |
| Manitowoc Company, Inc. |
| Doosan Bobcat |
| Others |
Value Network & Pricing Analysis
Data center contractors demanding extended-reach hydraulic excavators with telematics integration are forcing OEMs to reconfigure component sourcing and absorb after-treatment cost inflation into list pricing. Tier 4 Final compliance deadlines compress procurement timelines while elevating capital requirements for fleet operators.
Pricing Analysis
Distributor margins on hydraulic systems absorb the steepest compression as OEMs pass through Tier 4 Final after-treatment costs. Three-tier pricing structure across premium, standard, and economy levels separates telematics-enabled fleets from base configurations. Price differentiation hinges on EPA certification tier and bundled maintenance contracts. Pricing pressure stems from rental fleet operators demanding usage-based fee structures. Municipal contractors in California exhibit highest price sensitivity; mining operators in Nevada show least.
Supply Chain Analysis
Dual-sourcing requirements for diesel particulate filters and selective catalytic reduction systems are forcing OEMs to qualify secondary suppliers in Mexico and Canada. Engine architecture draws from US, Japan, and Germany. Critical inputs include high-pressure hydraulic pumps, steel forgings, and battery modules. Single-source vulnerability concentrates in semiconductor components for telematics platforms. Distribution runs through authorized dealer networks with captive service operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final and California Air Resources Board off-road regulations compound fleet replacement demand across contractor tiers. Compliance deadlines create predictable procurement windows for equipment manufacturers.
For Market Incumbents: Deepen captive engine manufacturing to anchor supply agreements against emerging electric entrants. Expand telematics platform integration to lock in rental fleet contracts. Tier 4 Final cost inflation threatens margin compression without vertical integration into after-treatment systems. For New Entrants and Emerging Players: Mid-tier infrastructure contractors in Texas represent an underserved buyer archetype seeking equipment-as-a-service flexibility without legacy fleet ownership. Mexico's nearshoring corridor offers white-space demand for compact electric equipment. California's zero-emission mandates create first-mover positioning for battery-electric lessors. For Investors and Strategic Acquirers: Asymmetric upside sits with telematics platform specialists holding machine-learning IP for idle-time reduction. Long-term viability centers on software-hardware integration capabilities across the electrification transition. Watch CARB regulatory acceleration as inflection signal for electric fleet adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into After-Treatment Systems | Captive SCR and DPF production insulates Caterpillar and Deere from Tier 4 Final cost volatility. |
| Telematics Platform Licensing | Komatsu's machine-level data analytics reduce operator idle time across Texas data center sites. |
| Electric Fleet-as-a-Service Launch | California contractors pilot 20-ton-class electric excavators through usage-based subscription models. |
| Mexico Distribution Expansion | Monterrey manufacturing growth drives compact equipment demand across Nuevo León infrastructure corridors. |
| Precision Grading Automation | Deere's SmartGrade GPS-LiDAR integration commands premium positioning in road construction segments. |
Research Methodology
Bottom-up contractor fleet modeling reconciled against top-down OEM production tracking forms the analytical core of this study. Primary interviews with equipment procurement managers, rental fleet directors, mining operations engineers, and dealer service heads combine with secondary validation from EPA certification databases, Infrastructure Investment and Jobs Act funding disclosures, and SEC equipment manufacturer filings. Triangulation across demand-side deployment data and supply-side production schedules ensures coverage integrity.
Historical trendline analysis of replacement cycle compression and electrification capital deployment patterns anchors the projection framework. Segmentation dimensions span product type, end-user industry, powertrain technology, and regional regulatory cluster. CAGRs derive from equipment shipment trajectories and fleet turnover velocity. Mining duty-cycle requirements and data center construction pipelines constitute industry-specific forecast inputs across the modeling period.
Underlying measurement precision varies by segment; electric and hybrid technology trajectories carry tighter precision than autonomous system adoption curves. Forecasts reflect assumptions around EPA enforcement consistency and Infrastructure Act funding continuity. Deviation in California Air Resources Board regulatory acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
CNC Router Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Wheeled Excavators Market
Construction Equipment
Global Scaffolding Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
US Rental Equipment Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Dozer Blade Market