
 Renal Cyst Treatment Market | 2026-2036
Renal Cyst Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Renal Cyst Treatment Market Analytics
Image-guided percutaneous ablation is reconfiguring how clinicians manage symptomatic renal cysts, shifting volume away from open surgical protocols toward outpatient interventions. Boston Scientific Corporation leverages its interventional urology portfolio to anchor positions in minimally invasive access devices across major hospital networks. Cook Medical sustains competitive differentiation through specialized drainage catheter lines designed for percutaneous renal applications. Siemens Healthineers dominates the imaging stack, supplying ultrasound and CT navigation systems that physicians require for precise cyst localization and procedural guidance.
Renal cyst treatment encompasses medical and interventional protocols for managing fluid-filled sacs arising from kidney parenchyma, typically employing sclerotherapy agents such as ethanol or povidone-iodine, laparoscopic decortication, or serial imaging surveillance for asymptomatic lesions. The primary purpose is preventing cyst-related complications including infection, hemorrhage, hypertension, or progressive renal function impairment in polycystic disease variants. Medications within the product-type dimension remain limited to symptom management and infection prophylaxis rather than curative therapy, while surgical intervention commands premium reimbursement due to operating room resource intensity and specialized surgical skill requirements. Minimally invasive treatment methods are expanding fastest in outpatient clinic settings where same-day discharge protocols reduce total cost of care and improve patient throughput.
FDA 510(k) premarket notification requirements govern interventional device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence and post-market surveillance obligations for renal access instruments sold in European member states. Japan's PMDA maintains distinct pharmaceutical and medical device approval tracks that manufacturers must navigate separately for sclerosing agents versus mechanical drainage systems. Stakeholders should monitor evolving reimbursement coding for percutaneous procedures as payers recalibrate coverage policies between hospital and ambulatory surgical center settings.
Market Dynamics
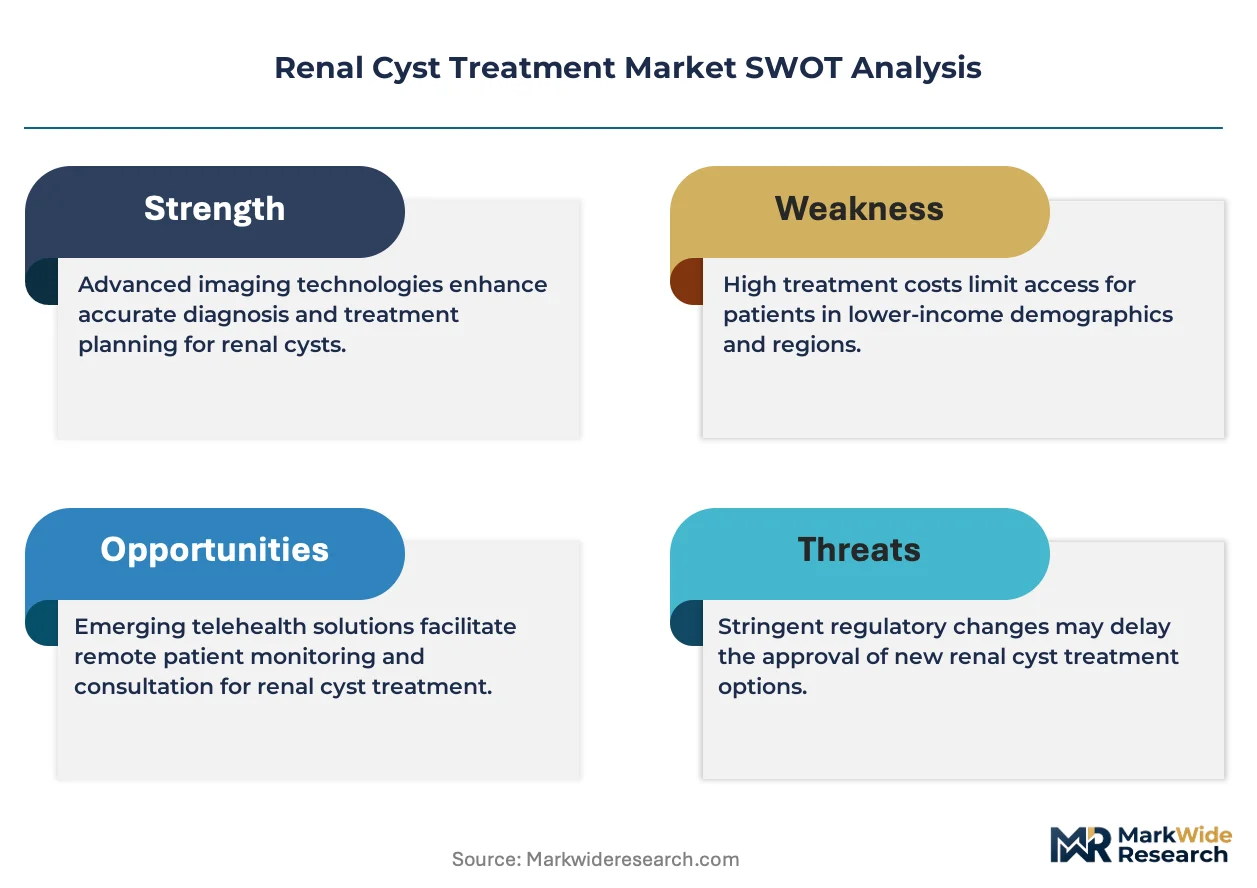
Image-guided percutaneous ablation is compressing the addressable surgical market for symptomatic renal cysts, shifting procedural economics toward outpatient settings and forcing recalibration of hospital reimbursement strategies.
Growth Catalysts
- EU Medical Device Regulation (MDR) harmonization:Streamlined CE marking pathways for renal access devices are accelerating cross-border commercialization across Germany, France, and Italy.
- CT-guided navigation systems:Sub-millimeter localization precision is expanding treatable patient populations to include complex cyst geometries previously deemed inoperable.
- Japan's aging demographic concentration:Elevated polycystic kidney disease prevalence in patients over 65 is sustaining procedural volume growth in Tokyo and Osaka metropolitan hospital networks.
Market Restraints
- Ethanol sclerotherapy supply concentration:Production of pharmaceutical-grade ethanol for percutaneous instillation concentrates in a limited supplier base, creating input cost volatility.
- FDA 510(k) evidentiary requirements:Tightened clinical data standards for interventional drainage catheters are extending premarket notification timelines and elevating regulatory compliance expenditures.
- Laparoscopic decortication persistence:Established surgical protocols for large Bosniak III/IV cysts retain physician preference in academic medical centers, limiting percutaneous penetration.
Strategic Opportunities
- Ambulatory surgical center (ASC) channel expansion:Same-day discharge protocols for sclerotherapy procedures are unlocking reimbursement arbitrage between hospital outpatient departments and freestanding ASCs.
- Artificial intelligence-integrated ultrasound:Real-time cyst margin detection algorithms are converging with portable imaging hardware to enable point-of-care diagnosis in primary care settings.
- Germany's Diagnosis-Related Group (DRG) reform:Recalibrated reimbursement weights for minimally invasive renal interventions are creating payment incentives favoring percutaneous over open surgical approaches.
Industry Challenges
- Interventional radiology workforce scarcity:Specialized training pathways for percutaneous renal procedures remain underdeveloped relative to procedural demand growth.
- Legacy electronic health record integration:PACS connectivity standards for image-guided navigation systems require costly customization within entrenched hospital IT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renal Cyst Treatment Market |
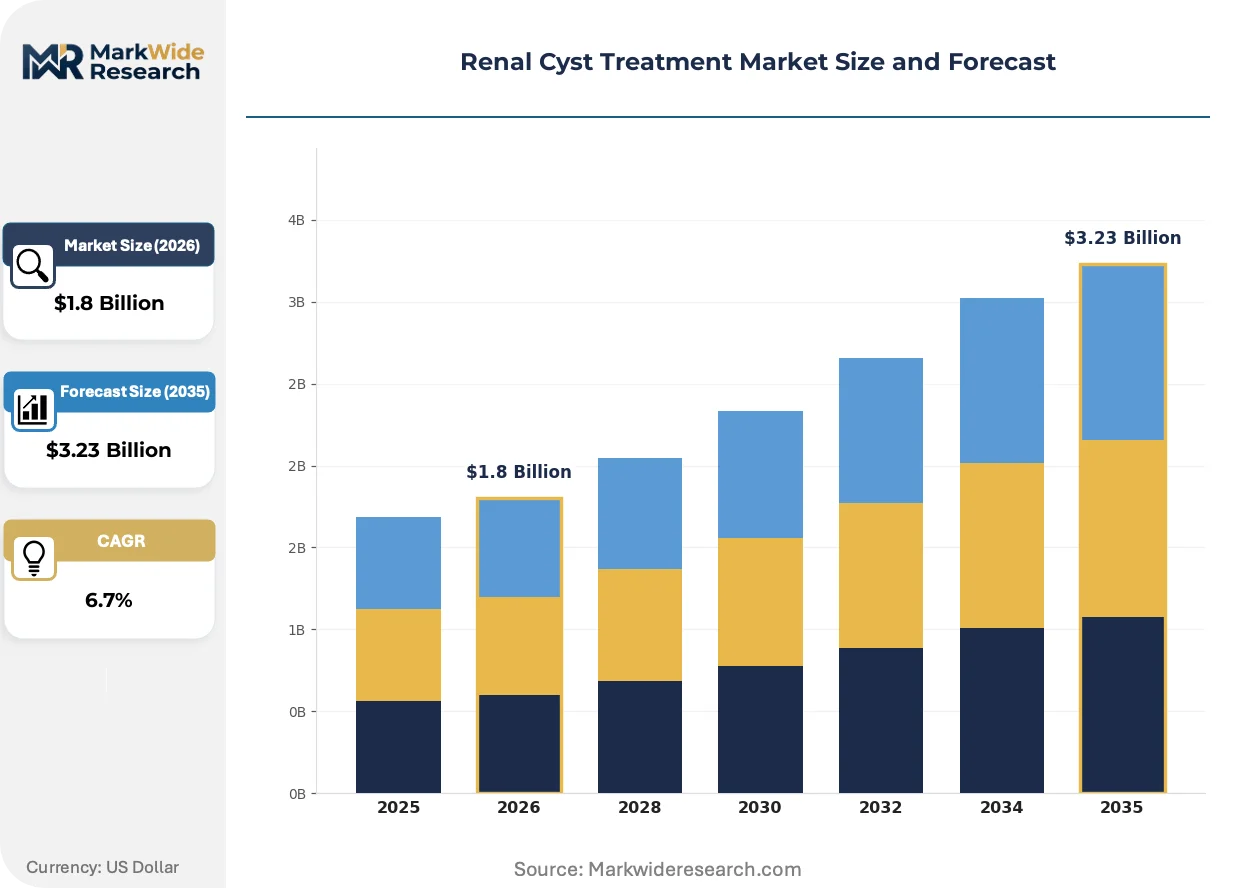
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Intervention, Observation, Drainage Treatment Method: Minimally Invasive, Laparoscopic Surgery, Open Surgery, Conservative Management Patient Demographics: Adults, Pediatric Patients, Elderly, Gender Specific Care Setting: Outpatient Clinics, Hospitals, Specialized Centers, Home Care |
| Companies Covered | Merck & Co., Inc., Boston Scientific Corporation, Cook Medical, Olympus Corporation, Siemens Healthineers, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Sanofi, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renal Cyst Treatment Market Evolving Landscape
Convergence of portable imaging hardware and artificial intelligence-assisted navigation is democratizing access to precision renal intervention, compressing the traditional hierarchy between academic medical centers and community-based practice settings.
Microwave ablation catheters with integrated temperature monitoring are rendering obsolete conventional ethanol sclerotherapy for recurrent simple renal cysts. Community hospitals in the United States are adopting these systems at accelerating pace as capital equipment costs decline. The technology is rendering obsolete the historical requirement for interventional radiology fellowship-trained operators, expanding treatable case volumes to general urologists.
FDA's evolving 510(k) premarket notification framework for ablation devices is imposing stricter thermal damage zone characterization requirements on manufacturers. Submissions now require histopathological correlation data from animal models that previously sufficed with computational modeling. Renal access catheter producers with established predicate device portfolios are responding by acquiring specialized histology contract research organizations.
Hospital procurement committees are unbundling imaging navigation systems from ablation device contracts, forcing equipment vendors to compete on standalone software performance metrics. This purchasing pattern shift is disrupting traditional bundled capital equipment sales models. The unbundling trend is most visible in German hospital networks, where centralized procurement cooperatives are mandating component-level competitive tendering.
Renal Cyst Treatment Market Segmentation
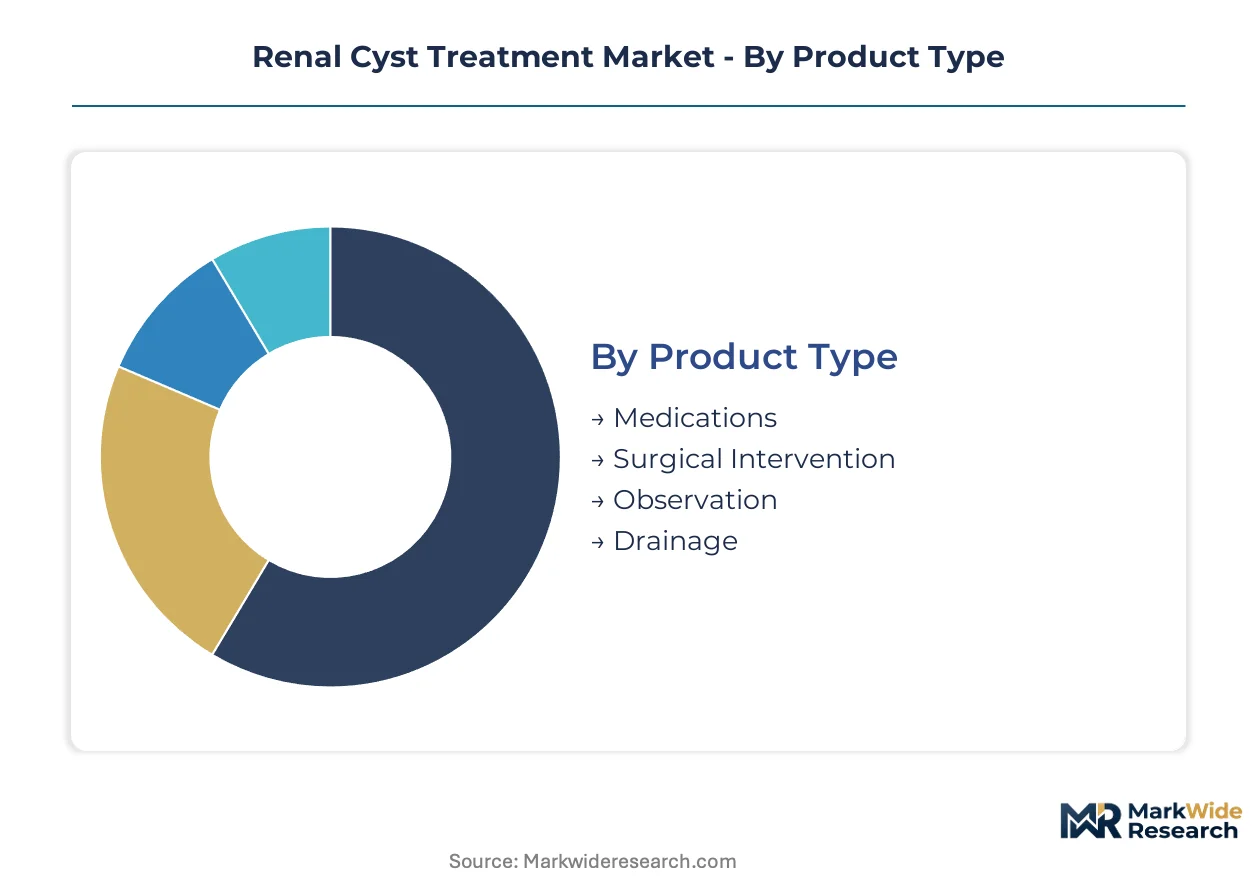
Renal cyst treatment segmentation reveals how procedural economics, patient acuity, and reimbursement frameworks reshape channel strategies across care delivery systems. Understanding these dimensions enables stakeholders to align product portfolios with where volume is actually concentrating versus where legacy assumptions place it.
Product Type:
Cost tier stratification separates commodity pharmaceutical inputs from capital-intensive surgical platforms and recurring consumable revenue streams.
- Medications:Pharmaceutical-grade ethanol and povidone-iodine formulations for percutaneous instillation dominate sclerotherapy protocols. Demand concentrates in ambulatory surgical centers across the United States where same-day reimbursement codes favor chemical ablation over mechanical alternatives.
- Surgical Intervention:Laparoscopic decortication and open cyst unroofing procedures command premium operating room reimbursement. Academic medical centers in Germany retain preference for these approaches in Bosniak III/IV complex cysts despite percutaneous alternatives.
- Observation:Serial imaging surveillance protocols for asymptomatic simple cysts consume radiology capacity without generating interventional revenue. This segment expands with incidental cyst detection from unrelated abdominal imaging studies.
- Drainage:Percutaneous catheter systems with integrated aspiration and irrigation functions enable outpatient fluid evacuation. Japanese hospital networks deploy these for infected cysts requiring prolonged drainage.
Surgical intervention commands the established base. The steepest expansion runs through drainage systems.
Treatment Method:
Application maturity determines whether technologies compete on clinical outcomes, total cost of care, or operator training requirements.
- Minimally Invasive:Image-guided percutaneous ablation using ultrasound or CT navigation eliminates general anesthesia requirements. Outpatient clinics in Tokyo and Osaka metropolitan areas report highest adoption velocity as interventional radiology capacity expands.
- Laparoscopic Surgery:Robot-assisted decortication systems sustain procedural volume in large cysts exceeding 10cm diameter. German DRG reimbursement weights still favor these approaches over percutaneous alternatives in hospital settings.
- Open Surgery:Retroperitoneal flank approaches for recurrent or hemorrhagic cysts retain indication in coagulopathic patients. Volume concentrates in tertiary referral centers managing polycystic kidney disease complications.
- Conservative Management:Watchful waiting with periodic imaging surveillance applies to asymptomatic Bosniak I/II lesions. Primary care networks in the United States drive volume through incidental detection protocols.
Laparoscopic surgery retains the revenue base. Minimally invasive methods are climbing the fastest as imaging navigation costs decline.
Patient Demographics:
Customer type heterogeneity shapes product design requirements from catheter sizing to sedation protocols and follow-up intensity.
- Adults:Working-age patients aged 18-64 prioritize rapid return to employment and minimal scarring. United States employer-sponsored insurance plans increasingly mandate ambulatory site-of-service for eligible procedures.
- Elderly:Patients over 65 present highest polycystic kidney disease prevalence and multiple comorbidities. Japanese metropolitan hospital networks concentrate specialized geriatric interventional capacity.
- Pediatric Patients:Congenital cystic kidney disease requires specialized anesthesia and smaller-gauge access instruments. German pediatric nephrology centers maintain dedicated interventional suites.
- Gender Specific:Pregnancy-associated symptomatic cysts and gender-differentiated polycystic disease phenotypes drive protocol customization. Research protocols in the United States explore hormonal modulation effects on cyst progression.
Adults generate the procedural volume base. Elderly patients are expanding most quickly as demographic aging accelerates across Japan and Germany.
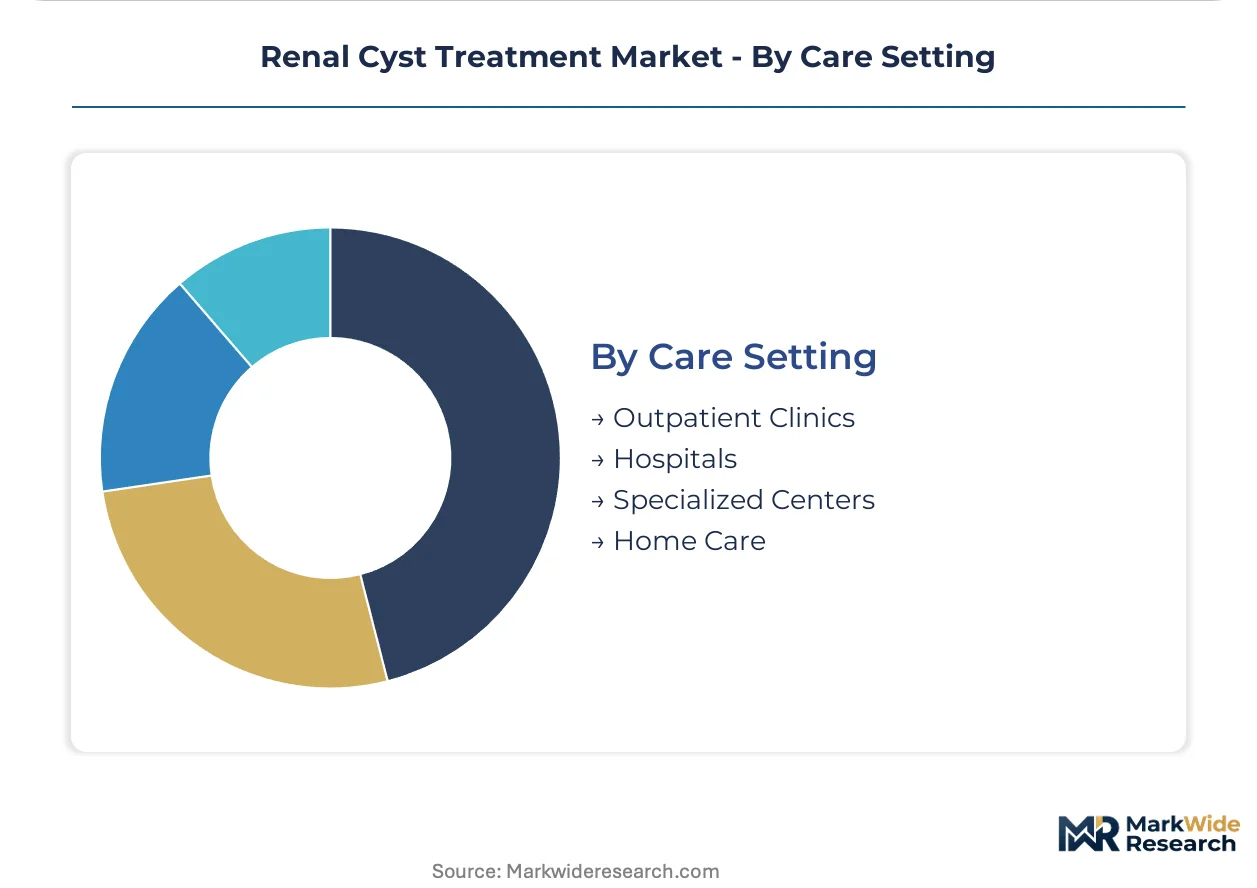
Care Setting:
Geography of service delivery—urban versus suburban, integrated system versus independent—determines procurement authority and technology refresh cycles.
- Hospitals:Inpatient departments manage complex cases requiring general anesthesia and overnight observation. German university hospitals maintain highest laparoscopic decortication volumes.
- Outpatient Clinics:Freestanding interventional radiology suites perform same-day sclerotherapy with local anesthesia. United States ambulatory surgical centers exploit reimbursement arbitrage against hospital outpatient departments.
- Specialized Centers:Dedicated polycystic kidney disease institutes combine nephrology, interventional radiology, and transplant services. Tokyo and Osaka host Asia's highest concentration of these facilities.
- Home Care:Indwelling drainage catheter maintenance and infection monitoring extend post-procedural care outside facilities. German statutory health insurance pilots reimburse home nursing for selected patients.
Hospitals retain the infrastructure base. Outpatient clinics are gaining share fastest as site-of-service policies tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German interventional device manufacturers export drainage catheter systems to Japanese hospital networks, establishing a trans-Eurasian trade corridor in minimally invasive renal access technology.
United States
Commercial insurers and Medicare Advantage plans tighten site-of-service policies, steering symptomatic cyst cases toward ambulatory surgical centers. FDA 510(k) premarket notification timelines for ablation devices extended eighteen months on average. Interventional radiology suites in Phoenix and Dallas metropolitan clusters report highest percutaneous sclerotherapy volumes.
Germany
University hospital networks in Bavaria and Baden-Württemberg sustain laparoscopic decortication preference for Bosniak III/IV complex cysts. EU Medical Device Regulation CE marking requirements for renal access instruments intensify post-market surveillance obligations. Berlin-Brandenburg procurement cooperatives unbundle imaging navigation from ablation device contracts.
Japan
PMDA maintains separate pharmaceutical and medical device approval tracks for sclerosing agents versus mechanical drainage systems. Metropolitan Tokyo and Osaka hospital networks concentrate specialized geriatric interventional capacity for polycystic kidney disease patients over 65. Government reimbursement recalibration favors same-day discharge protocols.
United Kingdom
NHS England integrated care systems consolidate renal interventional services into regional hub-and-spoke models. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment pathways for drainage catheter manufacturers. London and Manchester academic medical centers retain open surgical capacity for hemorrhagic cyst complications.
France
ANSM pharmacovigilance requirements for ethanol sclerotherapy agents intensify batch-level traceability mandates. HAS reimbursement guidance differentiates between hospital outpatient and ambulatory surgical center site-of-service payments. Lyon and Marseille metropolitan clusters develop interventional radiology fellowship training pipelines.
Renal Cyst Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: diversified medical technology conglomerates with interventional portfolios, specialized urological device manufacturers, and pharmaceutical suppliers of sclerotherapy agents. Strategic archetypes include imaging-navigation integrators, catheter-focused drainage specialists, and sclerosing agent formulators. Dominant competitive moves encompass vertical integration into histopathology contract research capabilities and geographic expansion through hospital procurement cooperative partnerships.
Among diversified medical technology conglomerates, Boston Scientific Corporation and Siemens Healthineers occupy positions spanning interventional access devices and imaging navigation systems respectively. Cook Medical exemplifies the specialized drainage catheter archetype with percutaneous renal application focus. These three entities represent distinct strategic postures: imaging-hardware bundling, interventional-urology portfolio breadth, and single-indication mechanical specialization.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Boston Scientific Corporation |
| Cook Medical |
| Olympus Corporation |
| Siemens Healthineers |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi |
| Medtronic plc |
| Others |
Value Network & Pricing Analysis
Undercapacity in pharmaceutical-grade ethanol production for sclerotherapy applications across European manufacturing facilities is compressing supplier margins while elevating spot-market pricing volatility for hospital procurement committees negotiating annual ablation device contracts.
Pricing Analysis
Next-generation microwave ablation catheters with integrated temperature monitoring command substantial premiums over conventional ethanol sclerotherapy protocols and first-generation drainage systems. Three-tier pricing structure across premium navigation-integrated systems, standard catheter platforms, and economy sclerosing agents reflects FDA certification tier and software bundling intensity. Pricing pressure stems from German procurement cooperative unbundling mandates that force standalone software competition. Academic medical centers exhibit lowest price sensitivity due to DRG reimbursement insulation, while United States ambulatory surgical centers negotiate aggressively on consumable bundles.
Supply Chain Analysis
Extended payment terms from Japanese hospital networks to German drainage catheter manufacturers are straining working capital requirements for specialized interventional device producers. Component manufacturing concentrates in Germany, Japan, and the United States for precision catheter extrusion and imaging navigation hardware. Raw material dependencies include medical-grade polymers, biocompatible coatings, and semiconductor chips for temperature sensors. Single-source vulnerability in pharmaceutical-grade ethanol purification creates supply risk. Distribution runs through hospital procurement cooperatives in Germany and GPO contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in renal cyst treatment are expanding faster than hardware sales, with recurring revenue from sclerotherapy agent replenishment, catheter maintenance protocols, and imaging software subscription tiers outpacing capital equipment growth.
For Market Incumbents: Entrench market position through backward integration into pharmaceutical-grade ethanol production and captive supply of biocompatible catheter coatings. Acquire specialized histology contract research organizations to accelerate FDA 510(k) thermal damage zone characterization submissions. Channel control through exclusive hospital system partnerships in Tokyo and Osaka metropolitan networks defends against emerging portable ultrasound entrants. For New Entrants and Emerging Players: Mid-market outpatient clinics in France and the United Kingdom represent the most penetrable entry point for AI-integrated portable ultrasound systems with real-time cyst margin detection. Target interventional radiology workforce scarcity in community hospital settings where general urologists seek simplified ablation protocols. Go-to-market angle emphasizes same-day discharge reimbursement arbitrage against hospital outpatient departments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among drainage catheter specialists with established sclerotherapy agent formularies in Japanese hospital networks. Long-term viability favors platforms combining hardware, consumables, and software subscriptions across the analysis window. Acquisition target archetype includes AI-ultrasound navigation developers with regulatory clearance pathways in multiple geographies. Monitor FDA 510(k) timeline compression for ablation devices as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR harmonization accelerates cross-border commercialization across German, French, and Italian hospital networks. |
| Hospital System Partnership | Exclusive procurement agreements with Tokyo and Osaka metropolitan networks lock in recurring sclerotherapy volume. |
| Software Companion Development | AI-integrated ultrasound navigation expands treatable case volumes to general urologists without fellowship training. |
| Reimbursement Strategy | Site-of-service policy navigation between hospital outpatient departments and ambulatory surgical centers optimizes payment capture. |
| FDA Submission | Histopathological correlation data from acquired contract research organizations satisfies tightened thermal damage zone requirements. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR CE marking registries, and Japanese PMDA approval filings preceded structured interviews with interventional radiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, CMS Medicare reimbursement coding updates, and German DRG weighting revisions. Bottom-up procedure volume estimates triangulated against top-down market sizing from capital equipment shipment data.
Forecast assumptions held fixed the current regulatory pathway timelines and reimbursement coding structures while varying procedural volume growth rates across care settings. Segmentation dimensions modeled include product type, treatment method, patient demographics, and care setting geography. CAGRs were derived from logistic adoption curves fitted to historical percutaneous procedure penetration patterns. Industry-specific inputs incorporated interventional radiology workforce expansion projections and imaging navigation cost decline trajectories.
Practitioners should monitor FDA evidentiary requirement tightening, EU MDR post-market surveillance obligation expansion, and Japanese reimbursement recalibration for same-day discharge protocols as early signals. Forecasts reflect these documented assumptions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Bladder Scanner Market
Urology
Urology Devices Market
Urology
Urinary Tract Infection (UTI) Treatment Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
Genitourinary Cancers Treatment Market
Urology
Ureterorenoscopes Market
Urology
Urinary Catheters Market
Urology
Urinary Tract Infection (UTI) Market
Urology
Uraemia Treatment Market
Urology
Asia-Pacific Bladder Disorders Market
Urology
North America Transrectal Ultrasound Market
Urology
Europe Bladder Disorders Market
Urology
Urinary Tract Infection Testing Market
Urology
Uropathy Treatment Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Chronic Pyelonephritis Treatment Market