
 Global Bone Densitometer Market | 2026-2036
Global Bone Densitometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bone Densitometer Market Foresight
Preventive maintenance contracts and remote calibration subscriptions is rebalancing how bone densitometer vendors monetize hardware placements. GE Healthcare leverages its installed base of Lunar systems to lock in multi-year service agreements across North American hospital networks. Hologic Inc. anchors its competitive stance through dense field engineering coverage that minimizes device downtime in high-throughput diagnostic centers. OsteoSys Corp. differentiates by specializing in compact ultrasound-based units that reduce per-scan operational overhead for orthopedic clinics.
A bone densitometer is a medical imaging device that quantifies bone mineral density using ionizing radiation or acoustic pulse-echo methods, typically resolving differences of one to two percent in mineral content to assess skeletal integrity. Its primary commercial purpose is enabling early detection of osteoporosis and fracture risk stratification before symptomatic bone failure occurs. DXA systems occupy the dominant margin pool due to reimbursement familiarity and established clinical guidelines, while ultrasound technology is gaining fastest in point-of-care settings where portability overrides absolute precision requirements. Quantitative CT holds a narrower position in research laboratories where three-dimensional trabecular analysis justifies higher capital outlays and specialized operator training.
FDA 510(k) clearances and CE marking under the EU MDR shape product development timelines and geographic launch sequencing for device manufacturers. Japan's PMDA enforces distinct software validation standards for AI-assisted fracture risk scoring that adds compliance layers for vendors targeting that market. China's NMPA requires in-country clinical trials for dual-energy X-ray systems, creating a staggered approval pathway that favors early regulatory investment. Stakeholders must monitor how reimbursement code consolidation in major markets alters the economic viability of premium feature sets versus baseline diagnostic configurations.
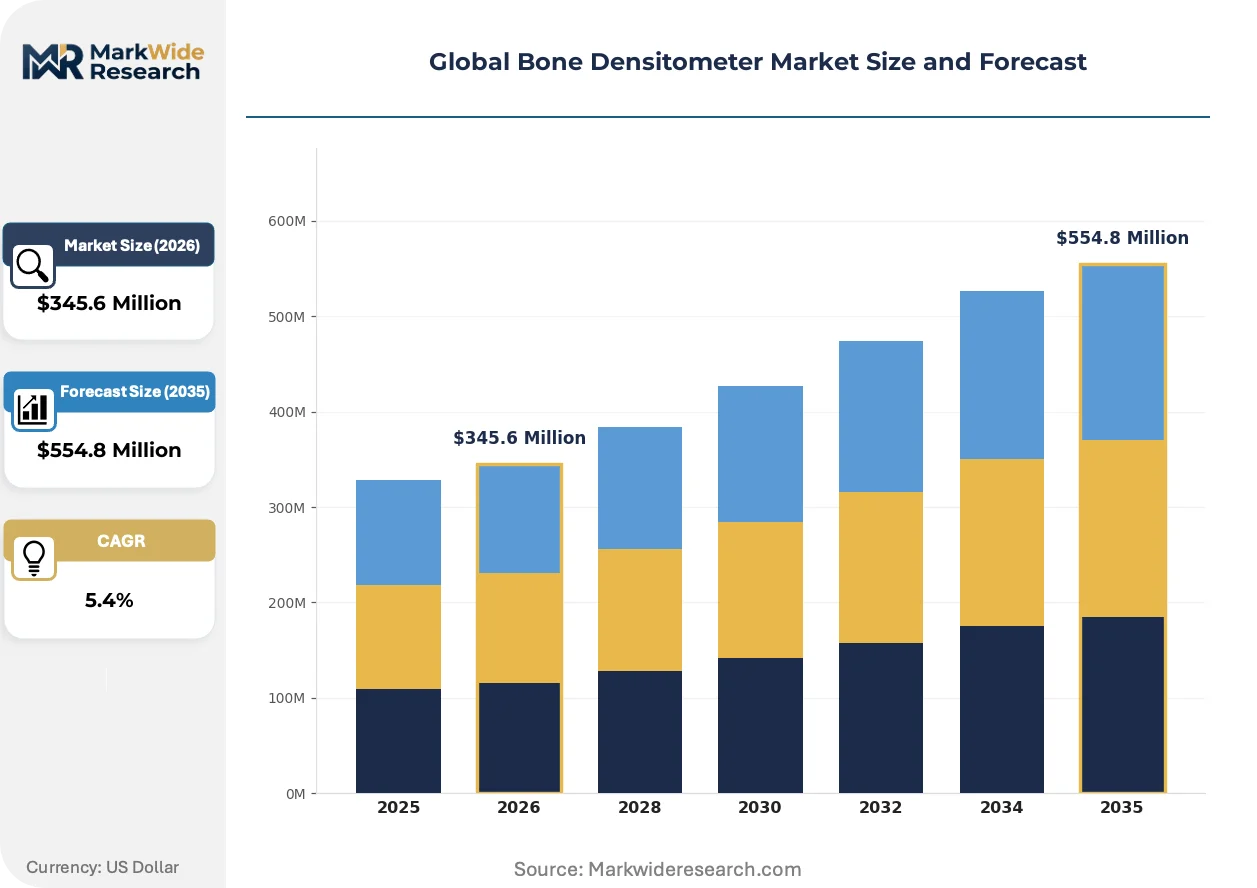
Market Dynamics
Preventive maintenance contracts and remote calibration subscriptions are rebalancing how bone densitometer vendors monetize hardware placements, shifting revenue streams from capital sales toward recurring service architectures that lock in multi-year customer relationships.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:The FDA's streamlined premarket notification process for dual-energy X-ray devices is compressing product clearance timelines and enabling faster geographic expansion for manufacturers with established predicate devices.
- Japan METI Preventive Screening Mandates:METI guidelines promoting bone health screening in aging municipalities are creating institutional procurement pull for compact diagnostic systems in community health centers.
- AI-Assisted Fracture Risk Scoring:Machine learning algorithms integrated into DXA software are expanding reimbursable diagnostic outputs and justifying premium system configurations in high-throughput hospital networks.
Market Restraints
- Ionizing Radiation Exposure Limits:Stringent ALARA protocols in pediatric and frequent-monitoring applications restrict repeat scan frequency and cap addressable patient volume in osteoporosis management programs.
- CE Marking Under EU MDR:The European Union's Medical Device Regulation imposes enhanced clinical evidence requirements and notified body capacity constraints that elongate market entry timelines for new system launches.
- Ultrasound Substitution in Primary Care:Radiation-free quantitative ultrasound systems are capturing point-of-care screening volume where absolute BMD precision is secondary to accessibility and operational simplicity.
Strategic Opportunities
- Rural China Penetration:County-level hospital upgrades under China's Healthy China 2030 initiative are creating first-time installation demand for compact, trailer-mounted DXA systems in underserved interior provinces.
- Quantitative CT Research Adoption:Three-dimensional trabecular analysis capabilities are opening high-margin niches in academic medical centers studying bone microarchitecture and pharmaceutical treatment response.
- Remote Calibration-as-a-Service:Cloud-connected phantom-based quality assurance is enabling vendors to unbundle technical service contracts and capture recurring revenue from distributed clinic networks without field engineer dispatch.
Industry Challenges
- DXA Technologist Certification Bottlenecks:ISCD credentialing requirements and limited training program capacity constrain workforce expansion needed to operate installed base growth in screening-dense markets.
- Legacy PACS Integration Complexity:DICOM conformance variations across hospital IT architectures demand customized interface engineering that extends deployment timelines and inflates professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bone Densitometer Market |
| Market Size in 2026 | $345.6 Million |
| Market Size in 2035 | $554.8 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DXA, Ultrasound, Quantitative CT, Radiographic Absorptiometry Technology: Dual-Energy X-ray, Single-Energy X-ray, Pulse-Echo Ultrasound, Micro-CT Application: Osteoporosis Diagnosis, Fracture Risk Assessment, Bone Health Monitoring, Metabolic Bone Disease Analysis End User: Hospitals, Diagnostic Centers, Orthopedic Clinics, Research Laboratories |
| Companies Covered | GE Healthcare, Hologic Inc., OsteoSys Corp., BeamMed Ltd., FURUNO Electric Co., Ltd., DMS Group, Swissray, Echolight S.p.A., Trivitron Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bone Densitometer Market Shifts & Advancements
Digital workflow architectures and artificial intelligence augmentation are compressing scan-to-report timelines while expanding the clinical utility of bone mineral density data beyond binary osteoporosis classification toward integrated fracture risk management.
Photon-counting detector technology is integrating into next-generation DXA platforms to deliver spectral separation capabilities that enable simultaneous bone and body composition analysis. Academic medical centers in Germany and the Netherlands are piloting these systems for research protocols requiring adipose tissue quantification. The structural consequence is that manufacturers are integrating advanced detector physics into premium tier offerings to defend margin pools against commoditized base configurations.
The EU MDR's enhanced post-market surveillance requirements are mandating systematic clinical follow-up data collection for CE-marked bone densitometers. Device manufacturers must now maintain active registries tracking long-term measurement stability and patient outcomes. High-volume system operators in France and Italy are responding by negotiating data-sharing agreements that offset compliance costs through preferential service pricing.
Hospital procurement committees are consolidating imaging equipment purchasing through centralized capital committees that evaluate total cost of ownership across modality portfolios. Standalone bone densitometer vendors face displacement by multi-modality suppliers offering bundled maintenance contracts. This behavioral shift is most visible in United States integrated delivery networks where radiology service line directors prioritize vendor reduction over best-of-breed point solutions.
Global Bone Densitometer Market Segmentation
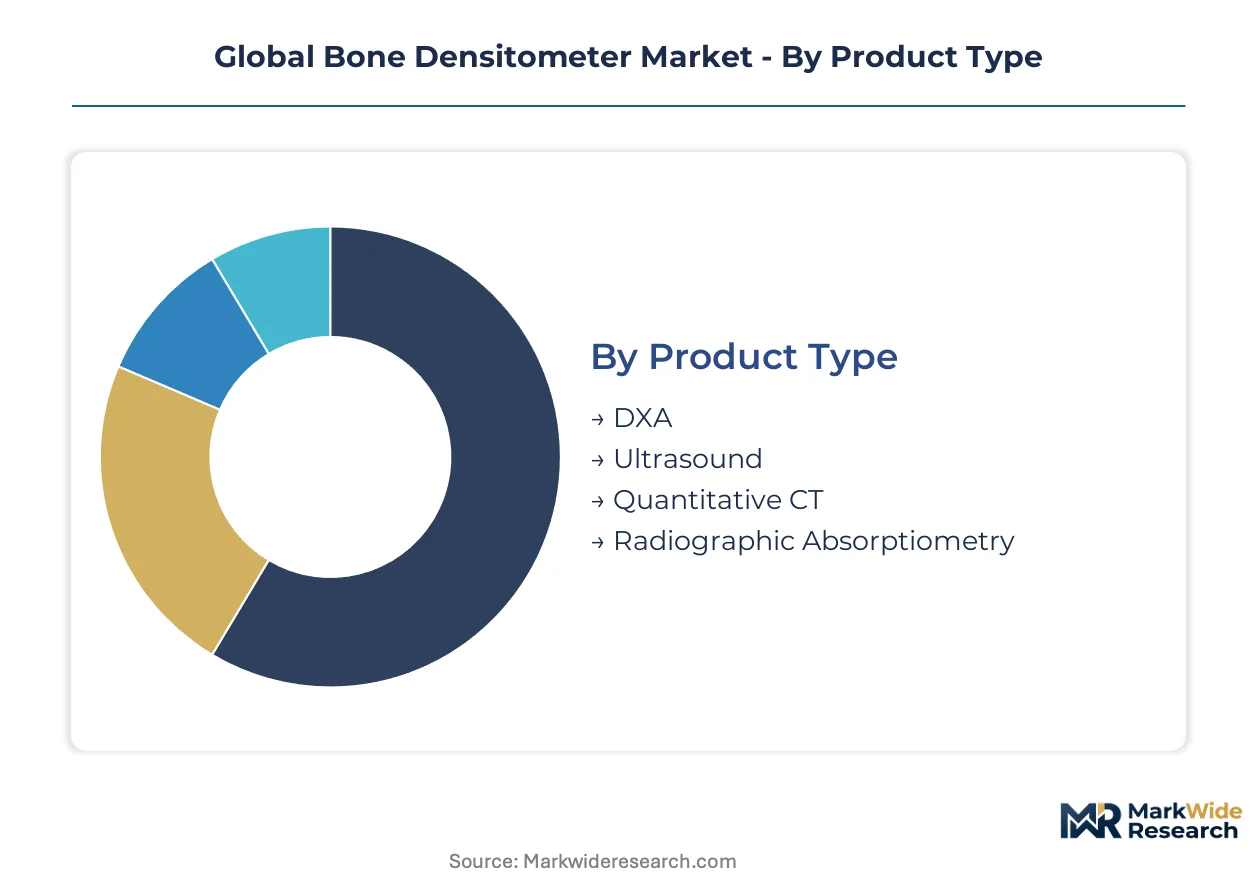
Bone densitometer market segmentation reveals divergent technology economics. Dual-energy X-ray systems command premium pricing through reimbursement codes, while ultrasound and portable alternatives carve volume through lower capital barriers and point-of-care accessibility.
Product Type:
DXA systems anchor the premium tier through established clinical guidelines and third-party payment structures. Ultrasound and alternative modalities compete on deployment flexibility and operational simplicity.
- DXA:Dual-energy X-ray absorptiometry systems deliver the clinical gold standard for bone mineral density quantification with precision to one percent. Hospital networks in Germany and Japan concentrate procurement for these systems under national osteoporosis screening mandates. Mature deployment sits with DXA. Newer deployment is concentrated in ultrasound.
- Ultrasound:Quantitative ultrasound devices eliminate ionizing radiation exposure while enabling portable screening in community health settings. Orthopedic clinics in aging Japanese municipalities favor these units for preventive bone health programs.
- Quantitative CT:Three-dimensional trabecular analysis capabilities serve academic medical centers studying pharmaceutical treatment response and bone microarchitecture.
- Radiographic Absorptiometry:Single-projection methods persist in resource-constrained settings where DXA infrastructure remains unavailable.
DXA systems retain reimbursement advantage. Ultrasound gains fastest in point-of-care expansion.
Technology:
Detector physics and energy separation methods differentiate performance tiers. Photon-counting architectures now penetrate the high-end, while legacy scintillation detectors defend installed base economics.
- Dual-Energy X-ray:Spectral separation at two distinct energy levels enables soft-tissue subtraction and precise bone mineral quantification. FDA 510(k) clearances for these systems are compressing under streamlined predicate pathways.
- Single-Energy X-ray:Simplified hardware architectures reduce per-unit manufacturing cost for screening-dense markets. China's county-level hospital upgrades under Healthy China 2030 are absorbing these systems for first-time bone health infrastructure.
- Pulse-Echo Ultrasound:Acoustic pulse-echo methods measure broadband ultrasound attenuation and speed of sound through calcaneus or phalanx. Compact form factors suit mobile screening units in rural India and Brazil.
- Micro-CT:High-resolution three-dimensional imaging at micron-scale resolution serves preclinical pharmaceutical research and ex vivo bone specimen analysis.
Dual-energy configurations dominate revenue. Pulse-echo ultrasound climbs fastest in volume terms.
Application:
Diagnostic purpose shapes system specification and reimbursement pathway. Binary osteoporosis classification demands less computational overhead than integrated fracture risk management with AI augmentation.
- Osteoporosis Diagnosis:Binary T-score classification against young-adult reference populations drives the majority of reimbursable scan volume. Hospital networks in France and Italy negotiate data-sharing agreements with manufacturers to offset EU MDR post-market surveillance costs.
- Fracture Risk Assessment:Machine learning algorithms now integrate clinical risk factors with BMD measurements to generate ten-year fracture probability scores. Japan's PMDA enforces distinct software validation standards for these AI-assisted outputs.
- Bone Health Monitoring:Serial measurement protocols track therapeutic response in patients receiving anti-resorptive or anabolic agents. ALARA protocols constrain repeat scan frequency in pediatric and frequent-monitoring populations.
- Metabolic Bone Disease Analysis:Specialized protocols for renal osteodystrophy, Paget's disease, and primary hyperparathyroidism require extended scan regions and customized reference databases.
Diagnostic applications concentrate installed base. Risk assessment applications are expanding most quickly through software premiumization.
End User:
Procurement authority and technical staffing levels segment customer economics. High-throughput hospital networks prioritize uptime guarantees, while distributed clinics value operational simplicity.
- Hospitals:Integrated delivery networks in the United States consolidate purchasing through centralized capital committees evaluating total cost of ownership across modality portfolios. ISCD technologist certification bottlenecks constrain workforce expansion for installed base growth.
- Diagnostic Centers:High-volume dedicated imaging facilities demand rapid scan-to-report workflows and dense field engineering coverage to minimize device downtime.
- Orthopedic Clinics:Specialty practices prioritize compact footprints and reduced per-scan operational overhead. OsteoSys Corp. targets this segment with ultrasound-based unit specialization.
- Research Laboratories:Academic medical centers in Germany and the Netherlands pilot photon-counting detector systems for simultaneous bone and body composition analysis protocols.
Hospital procurement dominates capital commitment. Orthopedic clinic deployment is gaining share fastest through portable system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for bone densitometer systems clusters in the United States, Germany, and Japan, while consumption demand spreads across aging populations in Europe and Asia-Pacific. Germany exports precision-engineered DXA platforms to hospital networks throughout the continent. China's domestic production scales to serve county-level hospital upgrades under national health infrastructure programs.
United States
Integrated delivery networks consolidate imaging equipment purchasing through centralized capital committees that evaluate total cost of ownership across modality portfolios. FDA 510(k) clearances for dual-energy X-ray devices compress under streamlined predicate pathways. Hospital networks in the Northeast and Midwest expand DXA screening programs for osteoporosis diagnosis.
Germany
Hospital networks expand DXA screening programs for osteoporosis diagnosis under national disease management guidelines. CE marking under the EU MDR imposes enhanced clinical evidence requirements that elongate market entry timelines for new system launches. Academic medical centers in Bavaria and Baden-Württemberg pilot photon-counting detector systems for simultaneous bone and body composition analysis.
Japan
METI guidelines promoting bone health screening in aging municipalities create institutional procurement pull for compact diagnostic systems. PMDA enforces distinct software validation standards for AI-assisted fracture risk scoring that adds compliance layers for vendors. Community health centers in Osaka and Nagoya absorb ultrasound-based units for preventive bone health programs.
China
NMPA requires in-country clinical trials for dual-energy X-ray systems, creating a staggered approval pathway that favors early regulatory investment. County-level hospital upgrades under the Healthy China 2030 initiative generate first-time installation demand for compact, trailer-mounted DXA systems. Interior provinces in Sichuan and Shaanxi deploy these units to underserved rural populations.
India
Orthopedic clinics in aging urban centers favor portable ultrasound units for point-of-care screening where absolute BMD precision is secondary to accessibility. CDSCO regulates medical device imports through a risk-based classification system that affects product launch sequencing. Diagnostic chains in Maharashtra and Karnataka expand bone health screening services to tier-two cities.
Global Bone Densitometer Market Competitive Landscape
Top-tier vendors anchor the premium DXA segment, while mid-tier specialists compete on portable ultrasound configurations and regional service density. The market structure stratifies across three tiers: multinational imaging conglomerates with installed base leverage, regional specialists with compact form factor expertise, and emerging entrants with AI-augmented software differentiation. Strategic archetypes include service-contract monetizers, hardware commoditizers, and software premiumizers. Dominant competitive moves encompass multi-year maintenance agreement lock-ins and cloud-connected calibration-as-a-service unbundling.
Among the established imaging conglomerates, GE Healthcare and Hologic Inc. occupy positions that exemplify the service-contract monetization archetype, leveraging dense field engineering networks to minimize device downtime. OsteoSys Corp. represents the compact-specialist tier, anchoring its competitive stance through ultrasound-based unit configurations that reduce per-scan operational overhead. These three companies collectively illustrate how vendor strategies diverge between premium-system defense and point-of-care accessibility expansion.
| Leading Market Players |
|---|
| GE Healthcare |
| Hologic Inc. |
| OsteoSys Corp. |
| BeamMed Ltd. |
| FURUNO Electric Co., Ltd. |
| DMS Group |
| Swissray |
| Echolight S.p.A. |
| Trivitron Healthcare |
| Others |
Supply & Pricing Matrix
Photon-counting detector migration from scintillation-based architectures is compressing manufacturing yields for legacy component suppliers while concentrating premium-tier production among German and Japanese precision-engineering clusters. This technology transition simultaneously elevates R&D amortization burdens on established vendors and creates sourcing bottlenecks for specialized semiconductor substrates used in next-generation DXA platforms.
Pricing Analysis
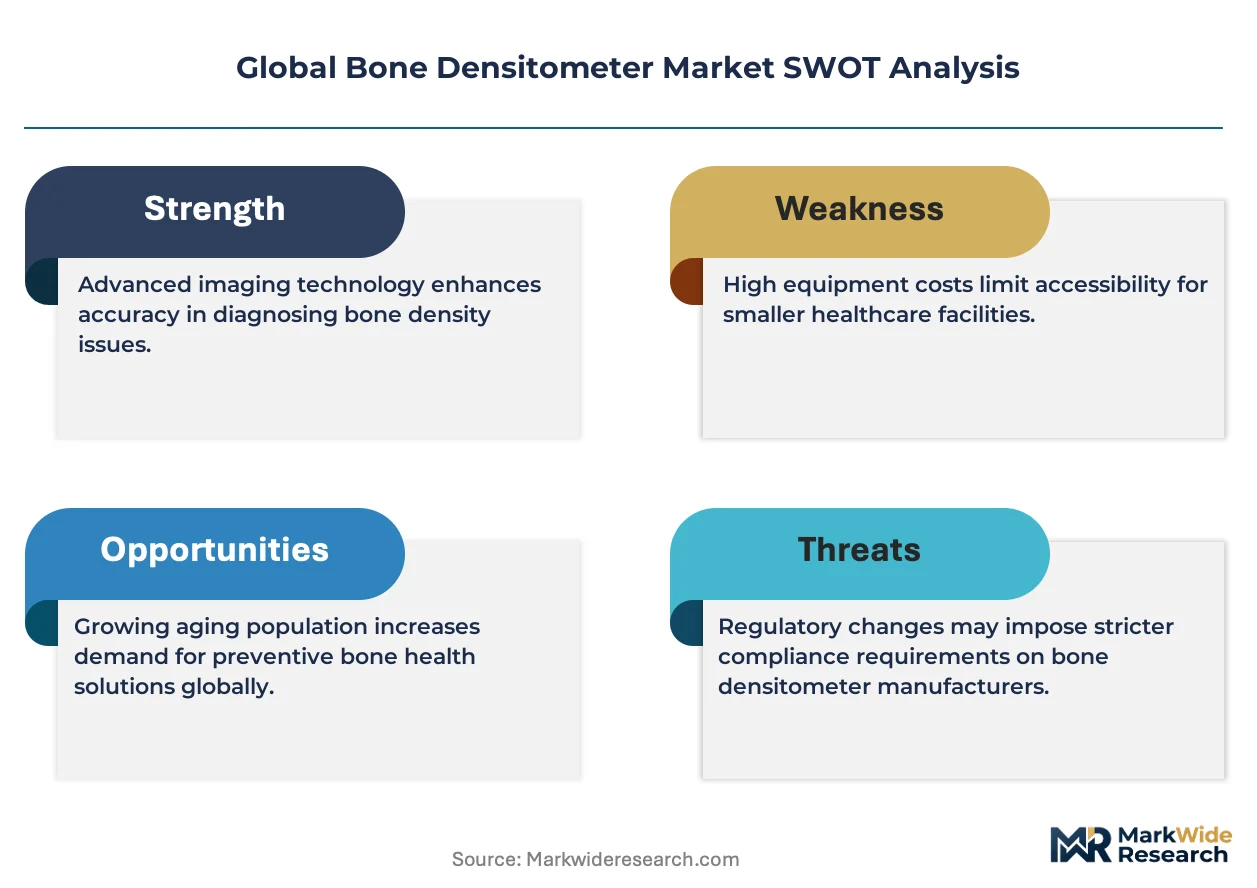
Margin tightening in mid-tier DXA configurations reflects volume concentration among integrated delivery networks negotiating enterprise-wide imaging contracts. Three-tier pricing structure across premium, standard, and economy levels separates photon-counting systems with body-composition capabilities from base DXA units and compact ultrasound alternatives. Certification grade under FDA 510(k) and CE marking pathways drives price differentiation, with AI-augmented fracture risk scoring commanding software premiumization. Orthopedic clinics and community health centers exhibit highest price sensitivity, while academic medical centers prioritize performance specifications over capital outlay.
Supply Chain Analysis
Freight cost volatility for precision-machined gantry components and detector assemblies is elevating landed costs for systems sourced from German and Japanese manufacturing hubs. Component supply draws from specialized semiconductor foundries in Taiwan, precision optics manufacturers in Germany, and rare-earth phosphor suppliers in China. Single-source vulnerability concentrates in photomultiplier tube and cadmium-zinc-telluride crystal supply. Distribution runs through regional imaging equipment distributors serving hospital procurement committees and direct OEM relationships with large integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bone densitometer market is consolidating around service-contract monetizers with dense field engineering networks, as EU MDR compliance costs and AI software validation requirements force sub-scale vendors toward exit or acquisition.
For Market Incumbents: To counter displacement by multi-modality suppliers bundling maintenance contracts across imaging portfolios, DXA specialists must deepen installed base lock-in through cloud-connected calibration-as-a-service unbundling and multi-year phantom-based quality assurance subscriptions. Vertical integration into detector manufacturing reduces exposure to Taiwan semiconductor foundry capacity constraints. For New Entrants and Emerging Players: Enter via compact ultrasound configurations targeting county-level hospital upgrades in China's interior provinces, where NMPA trial requirements favor later entrants with streamlined predicate pathways. Portable pulse-echo systems for rural India's orthopedic clinic networks offer the most penetrable white space, with mobile screening unit leasing as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by imaging conglomerates seeking bone health modality fill-in, with mid-tier DXA vendors holding ISCD-certified training program assets commanding strategic premium. Long-term viability hinges on software premiumization traction and recurring revenue mix. The signal to watch is PMDA approval velocity for AI-assisted fracture risk scoring algorithms, which indicates regulatory pathway clarity for premium-tier system configurations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Streamlined Pathway | Accelerates predicate-based clearances for dual-energy X-ray systems in US hospital networks. |
| CE Marking Under EU MDR | Mandates enhanced clinical evidence and post-market surveillance for European market entry. |
| Hospital System Partnership | Locks in multi-year service agreements through dense field engineering coverage commitments. |
| Software Companion Development | Expands reimbursable outputs via AI-assisted fracture risk scoring integrated into DXA platforms. |
| Reimbursement Strategy | Aligns premium feature sets with consolidated procedure codes in major payment markets. |
Research Methodology
Document review covered FDA 510(k) filings, PMDA approval summaries, EU MDR notified body guidance, and hospital procurement databases, complemented by interviews with biomedical engineers, radiology service line directors, GPO contracts managers, and DXA technologists. Secondary validation drew from CMS Medicare reimbursement data, ISCD certification program records, and METI preventive screening policy documents. Bottom-up installed base modeling and top-down epidemiological demand projection enabled cross-verification.
Cross-referencing historical DXA system shipment patterns against expert panel input on technology transition timing shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, detector technology, application purpose, and end-user procurement authority. CAGRs were derived from slope analysis of replacement cycle compression and expansion coefficients for first-time installation markets. Forecast inputs incorporated NMPA trial duration assumptions and county-level hospital upgrade cadence under China's Healthy China 2030 initiative.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR notified body capacity constraints and PMDA software validation standard revisions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
US ECG Equipment Market
Medical Equipment
Medical Air Sterilizer Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
Autopsy Saw Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Water Bath Market
Medical Equipment
US Radiotherapy Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
Cryochambers Market
Medical Equipment
PCR Plate Sealer Market