
 Composite Packaging Market | 2026-2036
Composite Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Packaging Market Analysis
Food and beverage demand is shifting toward extended-shelf-life formats that require oxygen and moisture barriers. Amcor plc leverages its global flexible film footprint to supply retort pouches and lidding solutions for protein brands. WestRock Company anchors North American corrugated composite demand through integrated paperboard and coating operations. Mondi plc differentiates in kraft-paper-based barrier packaging for fresh produce chains.
Composite packaging combines two or more distinct material layers—typically paper, plastic, metal foil, or glass—bonded through lamination, extrusion coating, or thermal fusion to achieve properties no single material delivers alone. These structures commonly achieve oxygen transmission rates below 1 cc/m²/day and are engineered primarily to protect sensitive contents from degradation, contamination, and physical damage during distribution. Flexible packaging leads volume due to its dominance in snack, confectionery, and pharmaceutical blister formats, while rigid and semi-rigid categories capture higher margin pools in premium personal care and medical device applications. Composite containers represent the smallest product type segment but show structural momentum in powdered nutrition and specialty coffee segments where shelf differentiation commands price premiums.
The EU Packaging and Packaging Waste Regulation and FDA food contact substance notifications shape material compliance pathways on both sides of the Atlantic, with REACH chemical restrictions further constraining adhesive and coating chemistries in European supply chains. ISO 18606 and ASTM D6400 compostability standards create divergent certification requirements that fragment export-ready product development. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border food and pharmaceutical channels.
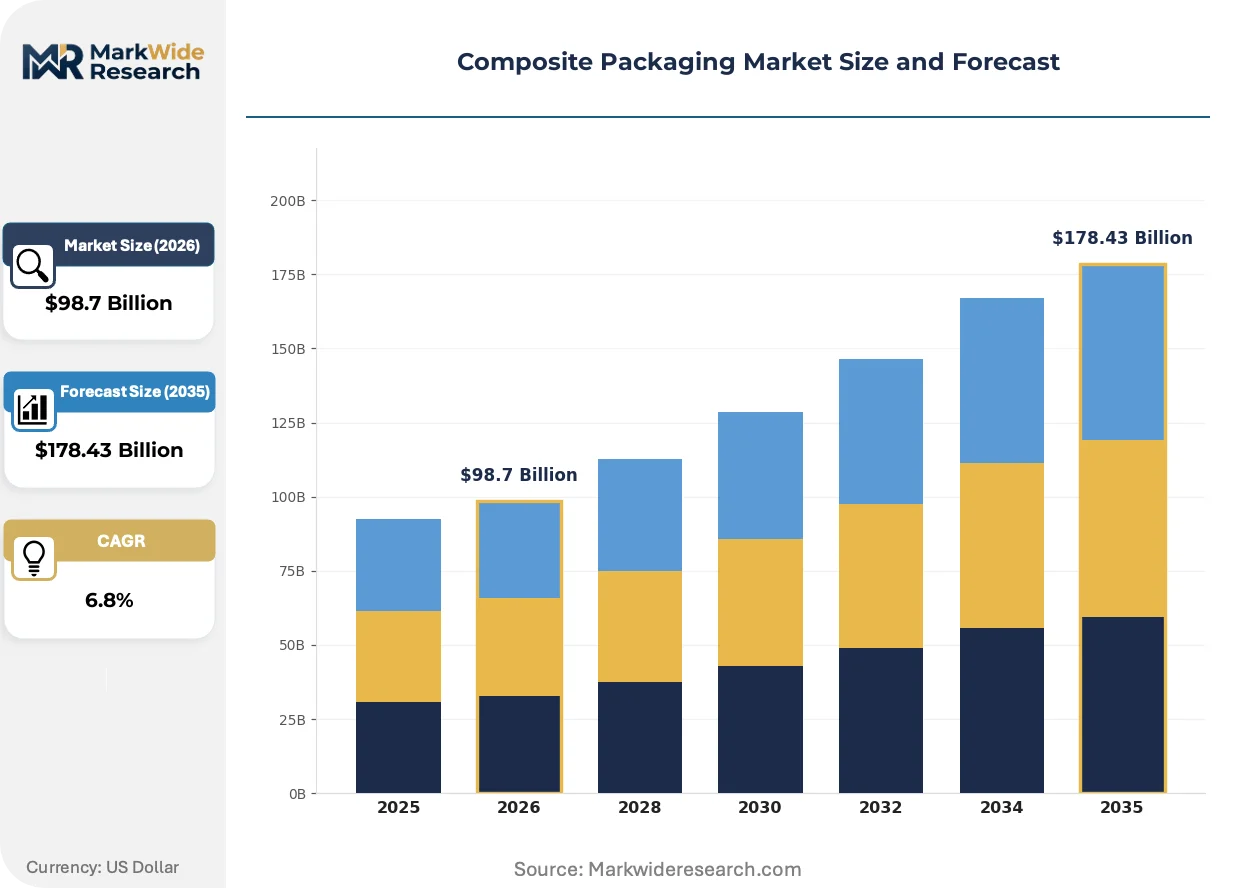
Market Dynamics
Multi-layer barrier formats are displacing single-material packaging across food and pharmaceutical supply chains as brands pursue extended shelf life without sacrificing recyclability targets mandated by the EU Packaging and Packaging Waste Regulation.
Growth Catalysts
- EU regulatory tightening:The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds and recyclability-by-design standards, forcing converters to invest in mono-material-compatible barrier coatings and paper-plastic hybrid lines.
- Pharmaceutical serialization:Track-and-trace mandates under the EU MDR and US DSCSA require tamper-evident composite blister formats with embedded authentication layers, pulling demand toward high-barrier aluminum-plastic laminates.
- Active packaging integration:Oxygen scavenger and moisture-absorbing films are embedding directly into retort pouch structures for ready-to-eat protein brands, eliminating secondary sachets and reducing packaging mass.
Market Restraints
- Aluminum foil supply concentration:European converter dependence on Chinese and Russian primary aluminum creates input cost volatility and forced substitution to metallized polymer films with inferior barrier performance.
- Adhesive chemistry constraints:REACH restrictions on isocyanate-based polyurethane laminating adhesives limit bonding options for high-performance structures, extending qualification timelines for food-contact applications.
- Mechanical recycling incompatibility:Multi-material laminates face rejection by European sorting facilities designed for mono-material streams, creating stranded volume risk as Extended Producer Responsibility fees scale with non-recyclable tonnage.
Strategic Opportunities
- India cold-chain expansion:FSSAI-mandated temperature integrity requirements for dairy and pharmaceutical distribution are creating first-mover advantage for vacuum-insulated composite shippers with phase-change material integration.
- Compostable barrier films:ASTM D6400 and EN 13432 certification pathways for polylactic acid-polyhydroxyalkanoate blends open premium positioning in food service and fresh produce channels where industrial composting infrastructure exists.
- Digital printing convergence:Electron beam-cured inks on flexible substrates enable lot-level customization without plate costs, compressing minimum order quantities for regional snack brands and private-label entrants.
Industry Challenges
- Multi-physics simulation talent:Barrier layer optimization requires coupled diffusion-mechanical modeling expertise that resides primarily in aerospace and semiconductor industries, creating recruitment friction for packaging converters.
- Legacy filling line retrofit:Transition from rigid cans to flexible retort pouches demands capital-intensive seaming and sterilization equipment replacement, slowing adoption at mid-cap food processors.
- Regulatory divergence management:Simultaneous compliance with FDA food contact notifications, EU 10/2011 plastic regulation, and China's GB standards fragments product development and strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Packaging Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Semi-Rigid Packaging, Composite Containers Material: Paper, Plastic, Metal, Glass End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Application: Food Preservation, Transit Packaging, Retail Display, Medical Storage |
| Companies Covered | Amcor plc, WestRock Company, International Paper Co, Smurfit Kappa, Sonoco Products Company, Mondi plc, TOPPAN Inc, Cosmo Films, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Packaging Market Emerging Trajectories
Material science breakthroughs and regulatory redesign are converging to redefine performance thresholds and compliance pathways across barrier packaging categories.
Water-based barrier coatings incorporating nanocellulose and bio-derived waxes are rewriting the technical-economic tradeoff between paper substrates and plastic films. Fresh produce distributors in Northern Europe are piloting these structures at scale for leafy greens and berries. The shift is compressing demand for conventional polyethylene extrusion coatings while creating new specification battles between coating suppliers.
REACH authorization requirements for per- and polyfluoroalkyl substances are eliminating oil-and-grease-resistant fluorochemical treatments from paperboard food packaging. Converters in Germany and the Netherlands are accelerating migration to silicone-based and clay-modified alternatives. The bakery and fast-casual segments face the steepest reformulation timelines as stockpiled legacy inventory depletes.
Direct-to-retailer contracting models are consolidating procurement authority previously dispersed among regional co-manufacturers. Protein and snack brands in the United States are centralizing specification control at headquarters level, squeezing converter margins through volume concentration while demanding faster turnaround on custom graphics. This concentration is most visible in the Southeast and Midwest manufacturing corridors where new regional distribution hubs are anchoring supplier consolidation.
Composite Packaging Market Segmentation
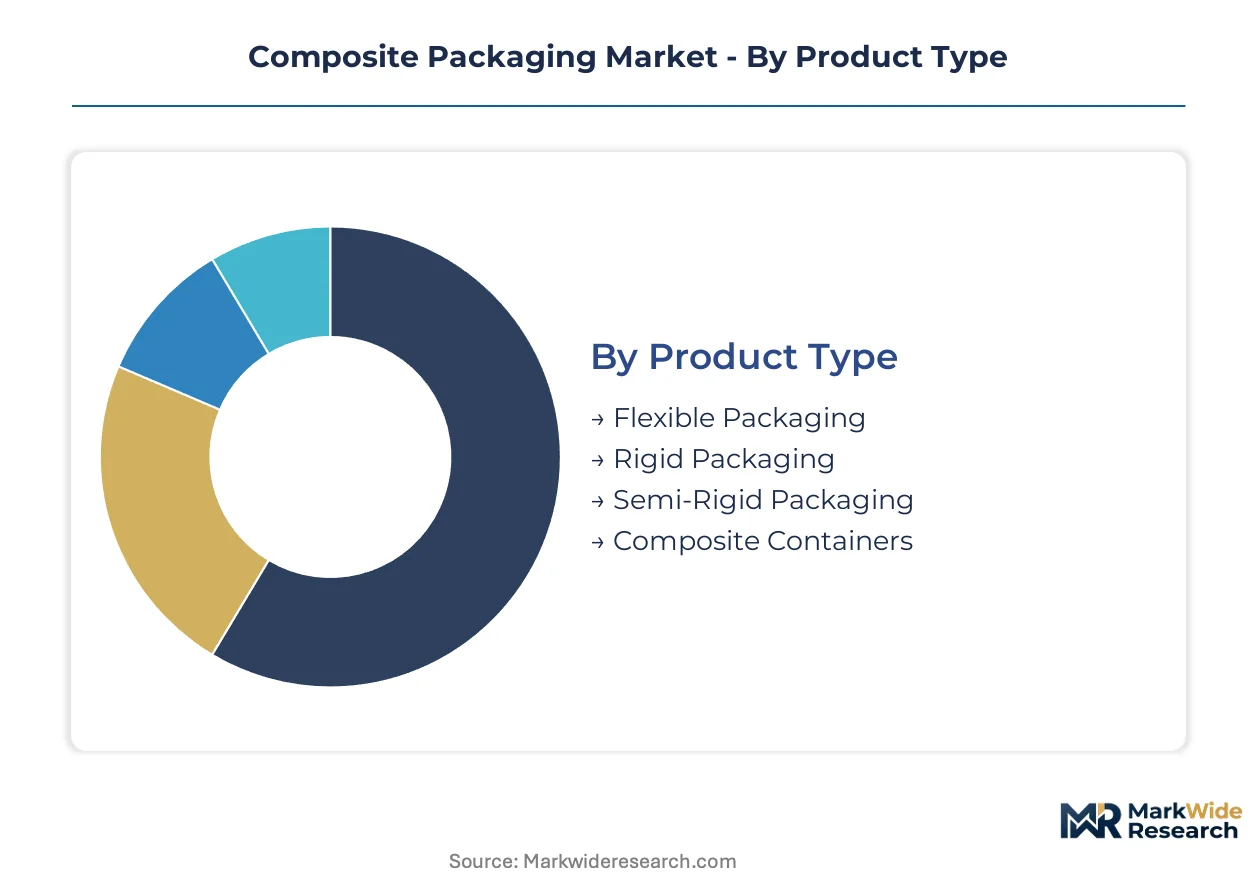
Composite packaging segments diverge sharply in regulatory burden and technical qualification. Material composition determines which FDA food contact notifications, EU 10/2011 plastic regulation, or REACH chemical restrictions apply.
Product Type:
Flexible packaging carries lighter mechanical testing obligations under ISO 18606 but faces intense scrutiny for adhesive chemistry compliance under REACH. Rigid and semi-rigid formats trigger more extensive migration testing protocols.
- Flexible Packaging:Multi-layer films laminated through extrusion coating or thermal fusion dominate snack, confectionery, and pharmaceutical blister applications. Demand concentrates in Germany where converter investments in paper-plastic hybrid lines have accelerated under EU Packaging and Packaging Waste Regulation recyclability mandates.
- Rigid Packaging:Structural formats combining paperboard with barrier coatings or aluminum layers serve premium personal care and medical device segments. North American corrugated composite demand anchors through integrated paperboard operations serving protein brands requiring retort sterilization compatibility.
- Semi-Rigid Packaging:Thermoformed trays and formed containers bridge protection and display functions for fresh produce chains.
- Composite Containers:Cylindrical formats for powdered nutrition and specialty coffee command shelf differentiation premiums in retail environments.
Leading the category by volume: Flexible Packaging. Growing fastest: Composite Containers.
Material:
Each substrate tier carries distinct certification pathways and supply concentration risks that shape converter sourcing strategies.
- Paper:Kraft-paper-based barrier structures with nanocellulose or bio-derived wax coatings are displacing polyethylene extrusion coatings in Northern European fresh produce distribution. Water-based barrier formulations face compressed qualification timelines as fluorochemical treatments phase out under REACH authorization requirements.
- Plastic:Polymer films and laminates provide oxygen transmission rates below 1 cc/m²/day for extended-shelf-life protein formats. Demand pulls toward mono-material-compatible barrier coatings as EU recyclability-by-design standards tighten across member states.
- Metal:Aluminum foil and metallized films create high-barrier layers for pharmaceutical blister and retort pouch applications. European converter dependence on Chinese and Russian primary aluminum creates input cost volatility and forced substitution to metallized polymer alternatives.
- Glass:Composite structures incorporating glass elements serve specialty pharmaceutical and high-value personal care segments requiring inert contact surfaces.
Paper and Plastic together anchor procurement volume. Metal faces the steepest substitution pressure from regulatory and supply-side forces.
End User:
End-use segments separate by serialization requirements, barrier performance thresholds, and channel compliance complexity.
- Food & Beverage:Oxygen and moisture barriers for ready-to-eat proteins and extended-shelf-life dairy drive retort pouch and lidding specification. Active packaging integration with embedded oxygen scavengers eliminates secondary sachets while reducing packaging mass.
- Pharmaceuticals:Tamper-evident composite blister formats with embedded authentication layers satisfy EU MDR and US DSCSA track-and-trace mandates. Aluminum-plastic laminates dominate high-barrier applications for moisture-sensitive dosage forms.
- Personal Care:Premium positioning demands rigid and semi-rigid composite structures with aesthetic finishing and dispensing functionality.
- Household Products:Concentrated and aggressive chemical formulations require corrosion-resistant barrier layers in spray and wipe packaging.
Food & Beverage generates the deepest volume base. Pharmaceuticals commands the highest margin and qualification barrier.
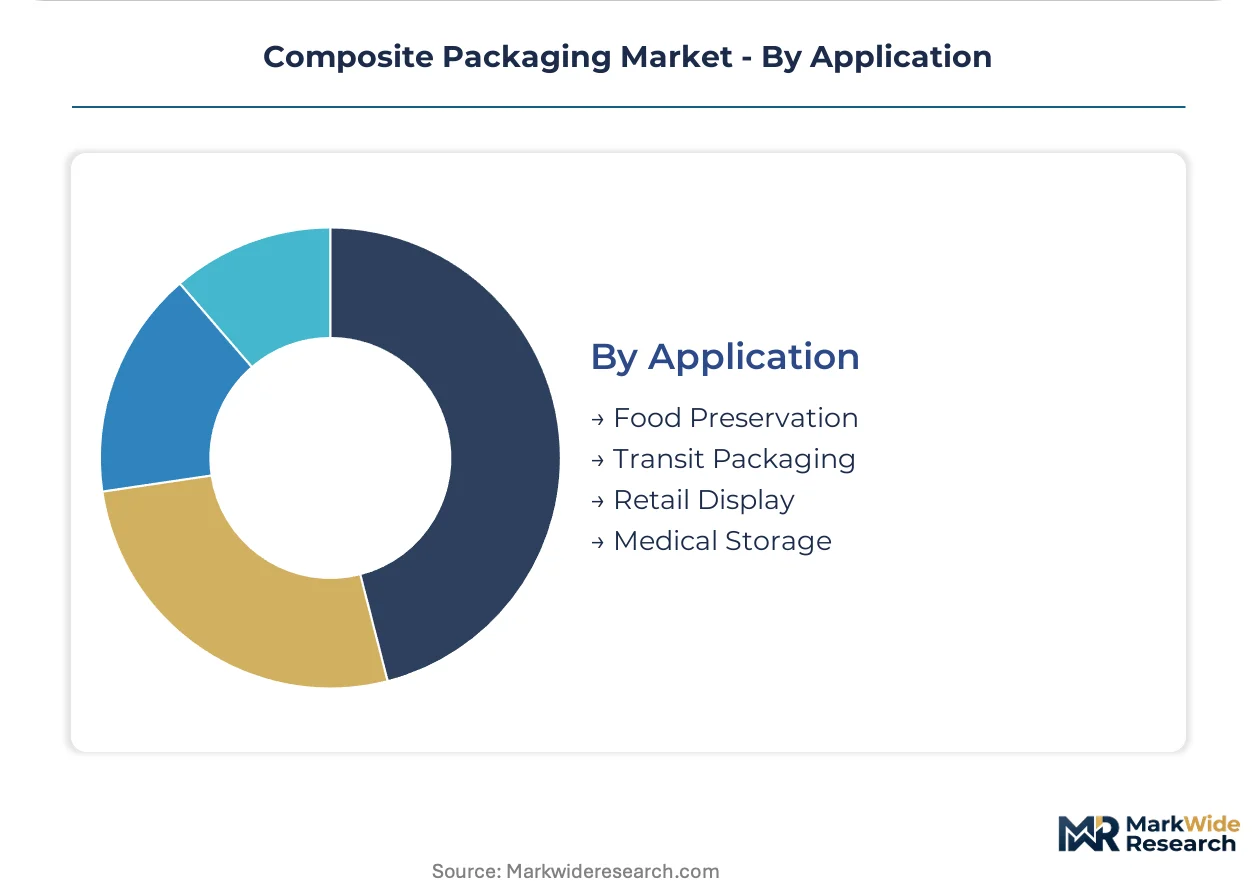
Application:
Application context determines sterilization compatibility, distribution stress requirements, and retail presentation specifications.
- Food Preservation:Retort sterilization compatibility and oxygen barrier performance define specification for shelf-stable protein and ready-meal segments. Phase-change material integration in vacuum-insulated composite shippers serves India cold-chain expansion under FSSAI temperature integrity mandates.
- Transit Packaging:Mechanical protection and stack strength requirements favor corrugated composite and rigid formats for e-commerce and industrial distribution channels.
- Retail Display:Shelf differentiation and graphics flexibility drive specification for composite containers and formed structures in specialty coffee and nutrition segments.
- Medical Storage:Sterile barrier integrity and temperature stability requirements apply to pharmaceutical distribution and clinical supply chains.
Food Preservation absorbs the broadest converter capacity. Medical Storage carries the most stringent validation protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Germany and the United States while consumption spreads across developed and emerging economies with divergent cold-chain maturity. The EU Packaging and Packaging Waste Regulation drives investment toward paper-plastic hybrid lines in Northern Europe. Asian markets pull demand through pharmaceutical serialization mandates and dairy distribution expansion.
Germany
Fresh produce distributors pilot nanocellulose barrier coatings for leafy greens, displacing conventional polyethylene extrusion. REACH authorization requirements for per- and polyfluoroalkyl substances force rapid fluorochemical phase-out in bakery packaging. Converter investments concentrate in the Ruhr industrial corridor where paper-plastic hybrid production lines scale under EU recyclability-by-design standards.
United States
Protein and snack brands centralize specification control at headquarters, compressing converter margins through volume concentration. FDA food contact substance notifications govern adhesive and coating chemistries for retort pouch applications. Southeast and Midwest manufacturing corridors anchor new regional distribution hubs that consolidate procurement authority previously dispersed among regional co-manufacturers.
India
FSSAI-mandated temperature integrity requirements for dairy and pharmaceutical distribution create first-mover advantage for vacuum-insulated composite shippers. The PLI scheme for packaging materials incentivizes domestic barrier film production capacity. Maharashtra and Gujarat industrial zones attract converter investments targeting cold-chain infrastructure gaps in protein and vaccine distribution networks.
China
GB standards for food contact materials and dual carbon goals constrain adhesive chemistry selection and push mono-material-compatible barrier development. Converter dependence on primary aluminum creates input cost volatility that forces metallized polymer substitution in high-barrier applications. Yangtze River Delta packaging clusters scale digital printing convergence for regional snack brand customization.
Japan
METI guidance on sustainable packaging accelerates compostable barrier film qualification for food service channels. JIS standards create divergent certification requirements that fragment export-ready product development for pharmaceutical blister formats. Kanto region converters integrate active packaging layers with embedded oxygen scavengers for ready-to-eat protein brands serving aging demographics.
Composite Packaging Market Vendor Landscape
Top-tier vendors anchor integrated paperboard and flexible film operations, while mid-cap specialists occupy niche barrier coating and digital printing segments. Tier-two converters compete on regional logistics proximity and custom graphics turnaround. Three archetypes dominate: multinational integrated packaging groups, regional paper-plastic hybrid specialists, and technology-focused barrier coating developers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as converters seek to lock in brand specification control.
Within the integrated multinational tier, Amcor plc and Mondi plc exemplify global flexible film and paper-based barrier positioning respectively. WestRock Company anchors North American corrugated composite demand through integrated paperboard operations. These three represent divergent strategic bets on material substrate dominance as regulatory frameworks fragment across FDA, EU 10/2011, and REACH compliance pathways.
| Leading Market Players |
|---|
| Amcor plc |
| WestRock Company |
| International Paper Co |
| Smurfit Kappa |
| Sonoco Products Company |
| Mondi plc |
| TOPPAN Inc |
| Cosmo Films |
| DS Smith |
| Others |
Supply Flow & Price Mechanics
Aluminum foil input costs transmit directly from Chinese and Russian primary smelters through converter pricing tiers, with metallized polymer substitution compressing margins in mid-tier barrier film segments while premium pharmaceutical laminates retain pricing power through FDA qualification barriers.
Pricing Analysis
Cost-down pressure on standard-grade flexible packaging accelerates because REACH restrictions on isocyanate-based adhesives extend qualification timelines and concentrate compliant supply among certified converters. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical laminates from food-contact films and industrial transit wraps. Certification grade and volume scale drive price differentiation, with private-label snack brands exhibiting highest price sensitivity and medical device manufacturers showing lowest.
Supply Chain Analysis
Dual-sourcing mandates from protein and pharmaceutical brands force converters to qualify secondary adhesive and coating suppliers across Germany, China, and India, extending procurement cycles. Raw material dependencies center on aluminum foil, polyethylene resins, and nanocellulose barrier coatings. Single-source vulnerability concentrates in Chinese primary aluminum, while distribution runs through converter-direct relationships with headquarters-level procurement teams at major food and pharmaceutical brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
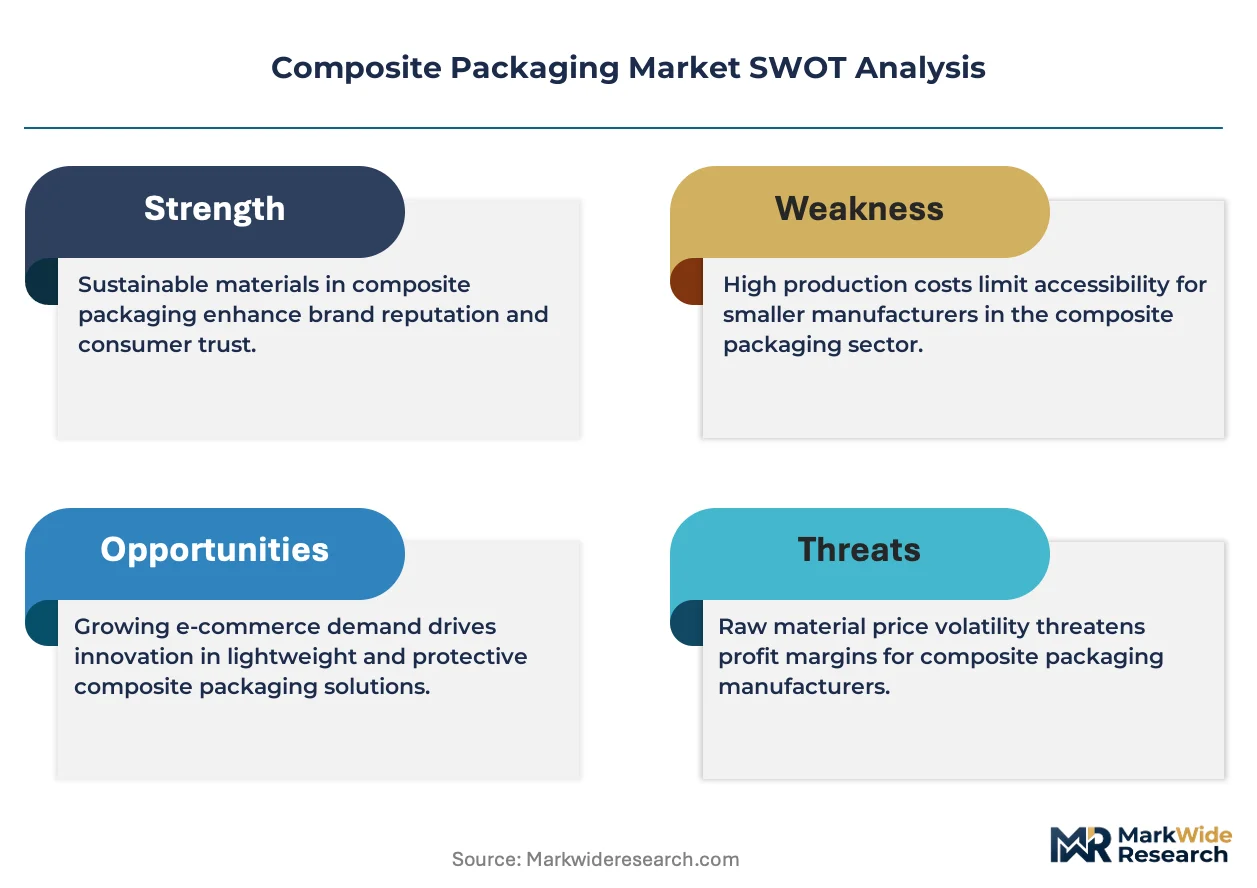
The EU Packaging and Packaging Waste Regulation erects a cost-of-compliance moat that rewards early movers in recyclability-by-design certification while stranding non-compliant inventory.
For Market Incumbents: Acquire paper-plastic hybrid production lines in the Ruhr corridor to consolidate capacity under tightening EU recyclability mandates. Backward integration into nanocellulose coating supply secures input stability as fluorochemical treatments phase out. Defensive positioning against metallized film substitution threats requires accelerated FDA food-contact validation for alternative barrier structures. For New Entrants and Emerging Players: Regional snack brands in the US Southeast and Midwest manufacturing corridors present underserved buyer archetypes with compressed minimum order quantity demands from digital printing convergence. Compostable barrier film certification for food service channels offers penetrable white-space with industrial composting infrastructure concentration. Direct-to-retailer contracting models bypass incumbent converter relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European converters with stranded legacy fluorochemical inventory and REACH compliance gaps in Germany and the Netherlands. Long-term viability hinges on qualification bandwidth for multi-jurisdictional regulatory divergence. The signal to watch is Extended Producer Responsibility fee scaling that accelerates non-recyclable tonnage penalties.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanocellulose Supply | Captures coating input stability as REACH eliminates fluorochemical alternatives in Northern Europe. |
| Paper-Plastic Hybrid Line Expansion | Positions converters for EU recyclability-by-design mandates and EPR fee avoidance. |
| Digital Printing Platform Deployment | Enables lot-level customization for regional snack brands compressing minimum order quantities. |
| Compostable Barrier Film Certification | Opens premium positioning in food service channels with ASTM D6400 and EN 13432 validation. |
| Multi-Jurisdictional Regulatory Qualification | Builds moat against stranded inventory risk across FDA, EU 10/2011, and GB standard divergence. |
Methodological Framework
Trade association filings, customs records, and SEC 10-K disclosures formed the secondary backbone, cross-referenced with primary interviews with converter plant managers, adhesive R&D directors, pharmaceutical packaging procurement leads, and food brand supply chain planners. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Historical trendline analysis tracked material substitution patterns and regulatory compliance cost trajectories across the analysis window. Segmentation modeling incorporated product type, material substrate, end-use vertical, and application context dimensions. CAGRs derived from coupled diffusion-mechanical barrier performance projections and cold-chain infrastructure expansion rates.
Revisions become necessary when aluminum supply disruption, REACH authorization scope expansion, or EPR fee schedule acceleration materialize. Deviation in EU recyclability-by-design enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
North America Single-Use Packaging Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Reel in Box Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
China Packaging Market
Packaging Materials
Cash Management Supplies Packaging Market
Packaging Materials
PCR Packaging Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Tubes and Cores Market
Packaging Materials
Collapsible Tube Packaging Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Packaging Suction Cups Market
Packaging Materials
Direct Thermal Printing Films Market