
 Disposable Egg Trays Market | 2026-2036
Disposable Egg Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Egg Trays Market Outlook
EU F-Gas Regulation is shifting refrigerant and cold-chain packaging standards, raising compliance costs for foam-based tray entrants. Huhtamaki Oyj leverages its molded fiber expertise to dominate European retail channels. Hartmann sustains leadership through captive pulp sourcing and backward integration into recycled paper mills. CDL Omni-Pac anchors its position with specialty barrier coatings that extend shelf stability for premium egg grades.
Disposable egg trays are rigid, compartmentalized containers engineered to cradle individual eggs during transport, retail display, and consumer handling, typically fabricated from molded pulp, expanded polystyrene, or thermoformed PET with cavity counts standardized at 6, 10, or 12 cells. Their primary commercial purpose centers on shock absorption, vertical stacking efficiency, and moisture management to reduce breakage rates in temperature-variable supply chains. Pulp material leads volume due to cost parity and compostability alignment with retailer sustainability mandates, while biodegradable variants represent the fastest-expanding margin pool as food retailers in Northern Europe enforce plastic reduction targets. Eco-friendly type classifications now command shelf-space premiums in German and French hypermarkets where consumer-facing green claims influence purchasing decisions.
The EU Green Deal and REACH frameworks govern chemical content and end-of-life disposal pathways for all packaging placed on European markets, while the FDA maintains sanitary contact surface standards for trays entering US food distribution channels. India's FSSAI enforces food-grade material certifications that restrict recycled content thresholds in direct-contact applications. Stakeholders must monitor how divergent compostability certification schemes between EU member states and US municipal programs reshape export eligibility and capital allocation for new production lines.
Market Dynamics
The EU F-Gas Regulation is compressing foam-based tray margins while accelerating molded fiber capacity investments across Northern European packaging suppliers.
Growth Catalysts
- EU Green Deal packaging mandates:Biodegradable tray procurement is expanding across German food retailers as waste reduction targets tighten compliance windows for plastic alternatives.
- Organized retail penetration:India's tier-one cities are driving volume concentration as modern grocery formats displace traditional wet markets for egg distribution.
- Molded pulp cost parity:Recycled fiber processing advances have eliminated the historical premium against expanded polystyrene in high-volume production runs.
Market Restraints
- Recycled pulp supply concentration:Captive sourcing arrangements by integrated European producers limit independent mill access for new market entrants.
- REACH chemical compliance costs:Barrier coating formulations face extended ECHA registration timelines that delay product launches by 12-18 months.
- Competing reusable systems:Returnable plastic crate networks in Scandinavian retail are capturing institutional volume from disposable formats.
Strategic Opportunities
- India tier-two expansion:Organized retail underpenetration in secondary cities offers first-mover positioning before infrastructure consolidation accelerates.
- Specialty barrier coatings:Shelf-life extension technologies for premium egg grades command pricing premiums in French and German hypermarket channels.
- Compostability certification harmonization:Divergent EU member state schemes create arbitrage potential for producers achieving multi-jurisdictional approvals.
Industry Challenges
- Molded fiber engineering talent scarcity:Wet-forming process expertise concentrates among legacy European equipment suppliers, constraining rapid capacity scaling.
- Multi-standard certification timelines:FDA sanitary contact surface validation for US market entry runs parallel to EU compostability audits, stretching compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Egg Trays Market |
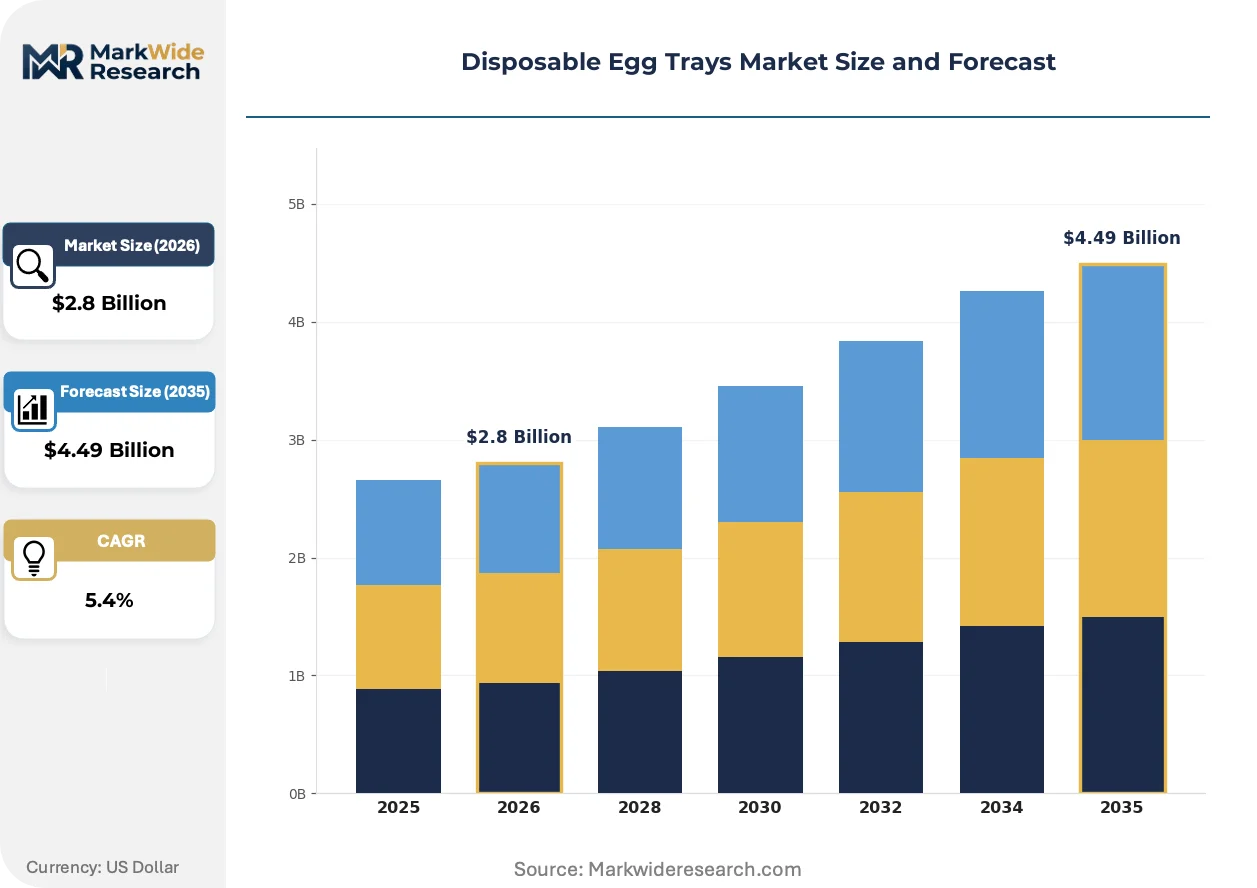
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Pulp, Plastic, Biodegradable, Styrofoam End User: Food Retailers, Restaurants, Egg Producers, Distributors Type: Standard, Stackable, Custom, Eco-friendly Shape: Regular, Carton, Plastic Molded, Special Design |
| Companies Covered | Huhtamaki Oyj, Hartmann, CDL Omni-Pac, Pactiv LLC, Tekni-Plex, Genpak, Dispak UK, Europack, DFM Packaging Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Egg Trays Market Strategic Shifts
Active material science breakthroughs are redefining barrier performance thresholds while regulatory timing compresses product development cycles across major supply basins.
Specialty bio-based barrier coatings are converging with molded fiber substrates to replace polyethylene linings in premium egg packaging. German retailers are piloting these formats for organic egg grades where moisture resistance must match plastic performance. The convergence is compressing the historical performance gap that justified foam retention in temperature-variable supply chains.
REACH chemical restriction expansions are forcing reformulation of conventional sizing agents used in pulp molding. ECHA's updated candidate list for Substances of Very High Concern now captures several starch-based additives common in food-contact applications. Tray producers serving Dutch and Belgian export markets are accelerating alternative binder qualification to avoid supply disruption.
Direct-store-delivery consolidation is displacing traditional wholesale intermediaries in North American egg distribution. Large integrated producers are capturing retail shelf planning authority that previously rested with regional distributors. The shift is most visible in California and Texas markets where vertical coordination between packers and grocery chains has tightened slotting fee negotiations.
Disposable Egg Trays Market Segmentation
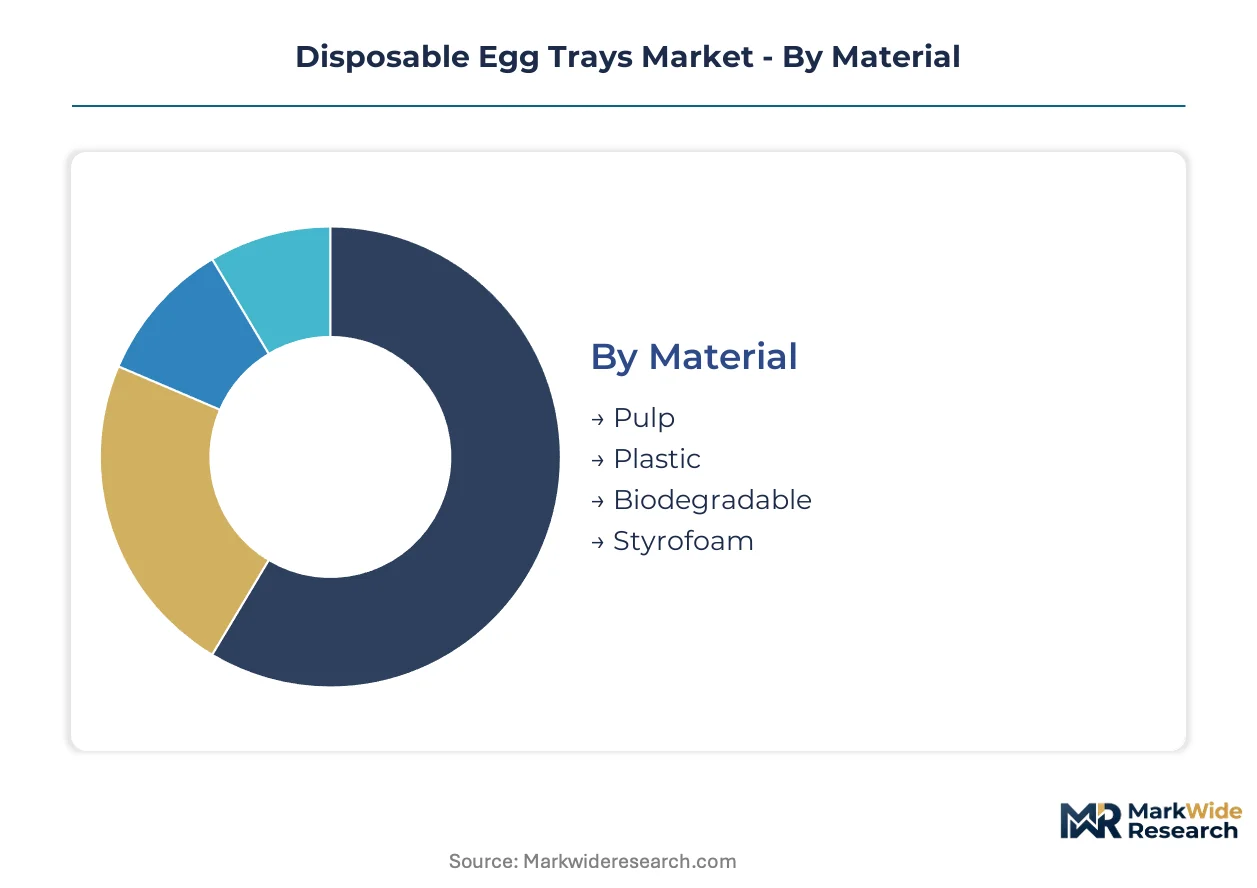
Disposable egg tray procurement patterns diverge sharply between cost-driven institutional buyers and sustainability-focused retail channels. Material selection and end-use application together determine margin structure, shelf-life performance, and compliance burden across temperature-variable supply chains.
Material:
Cost tier separates commodity buyers from premium-positioned retailers seeking certification alignment.
- Pulp:Recycled fiber substrates dominate volume through cost parity with foam and compostability credentials. German and French hypermarkets mandate molded pulp for private-label egg lines under EU Green Deal packaging rules.
- Biodegradable:Bio-based polymers and agricultural waste composites command shelf-space premiums where consumer-facing green claims influence purchasing decisions. Northern European retailers enforce plastic reduction targets that accelerate format conversion.
- Plastic:Thermoformed PET and PP variants retain foothold in temperature-extreme logistics where moisture resistance trumps sustainability mandates.
- Styrofoam:Expanded polystyrene faces margin compression from EU F-Gas Regulation compliance costs and municipal disposal restrictions.
Volume sits with pulp; growth tilts toward biodegradable.
End User:
Application context dictates performance specifications from shock absorption to display aesthetics.
- Food Retailers:Modern grocery formats in India's tier-one cities displace traditional wet markets, driving standardized tray procurement. Slotting fee negotiations favor suppliers with multi-jurisdictional compostability certifications.
- Egg Producers:Large integrated packers in California and Texas capture retail shelf planning authority through direct-store-delivery consolidation. Vertical coordination tightens packaging specification control.
- Distributors:Wholesale intermediaries face displacement as packer-retailer links strengthen, compressing independent tray procurement volumes.
- Restaurants:Foodservice channels prioritize stackability and breakage reduction over sustainability claims, accepting lower unit costs for higher handling tolerance.
Procurement authority concentrates with egg producers; expansion tilts toward food retailers.
Type:
Maturity gradient separates legacy formats from innovation-driven premium positioning.
- Eco-friendly:Specialty barrier coatings and bio-based substrates extend shelf stability for organic egg grades. French retailers pilot these formats where moisture resistance must match plastic performance.
- Stackable:Engineered vertical interlocking reduces logistics cube and retail backroom footprint. Critical for direct-store-delivery networks optimizing trailer utilization.
- Standard:Conventional six-cell and twelve-cell configurations maintain baseline demand across price-sensitive institutional channels.
- Custom:Branded cavity counts and retail-specific dimensions serve private-label programs and promotional pack sizes.
Standard formats anchor volume; premium positioning climbs fastest through eco-friendly variants.
Shape:
Supply concentration among legacy European equipment suppliers constrains rapid format innovation.
- Carton:Clamshell designs with hinged lids dominate retail display for premium egg grades. Closure integrity requirements drive specification tightening.
- Regular:Open-top compartmentalized trays serve bulk institutional distribution with minimal material overhead.
- Plastic Molded:Precision thermoforming enables complex cavity geometries for specialty egg sizes and export packaging.
- Special Design:Ergonomic handling features and tamper-evident closures address foodservice and direct-to-consumer subscription channels.
Regular shapes hold volume share; carton configurations gain fastest in retail-facing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for food processing have concentrated molded fiber capacity near organized retail distribution nodes. These zones attract packaging suppliers serving modern grocery formats with tax-advantaged production bases.
Germany
Biodegradable tray procurement dominates as the EU Green Deal tightens packaging waste rules for food retailers. The F-Gas Regulation compresses foam-based margins while accelerating molded fiber investments. Hamburg and Berlin retail clusters enforce private-label mandates that displace plastic alternatives.
India
Tier-one cities drive volume concentration as modern grocery formats displace traditional wet markets. The FSSAI enforces food-grade material certifications that restrict recycled content thresholds. Maharashtra and Karnataka host the fastest-expanding organized retail infrastructure for egg distribution.
United States
Direct-store-delivery consolidation shifts procurement authority toward large integrated packers. The FDA maintains sanitary contact surface standards for food distribution channels. California and Texas markets exhibit vertical coordination between packers and grocery chains.
France
Premium egg grades command shelf-space premiums for eco-friendly formats in hypermarket channels. REACH chemical compliance costs delay barrier coating product launches through extended ECHA registration timelines. The Île-de-France retail cluster pilots specialty bio-based substrates for organic egg lines.
Netherlands
Compostability certification harmonization creates arbitrage potential for multi-jurisdictional approvals. ECHA's updated candidate list for Substances of Very High Concern captures starch-based additives common in food-contact applications. The Randstad logistics hub concentrates distribution infrastructure for Northern European export markets.
Disposable Egg Trays Market Competitive Environment
European producers anchor the integrated tier; North American specialists hold contract manufacturing positions. The vendor base separates between captive pulp sourcing arrangements and independent mill-dependent fabricators. Three archetypes dominate: backward-integrated pulp owners, specialty coating developers, and scale-driven thermoformers. Competitive moves concentrate on capacity expansion in biodegradable substrates and geographic licensing of barrier technologies.
Among Nordic-based integrated producers, Huhtamaki Oyj and Hartmann exemplify the captive-sourcing archetype through in-house recycled fiber processing. CDL Omni-Pac occupies a position among specialty barrier developers serving premium shelf-life extension requirements. These three anchors represent distinct competitive vectors: fiber integration, coating innovation, and format specialization.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Hartmann |
| CDL Omni-Pac |
| Pactiv LLC |
| Tekni-Plex |
| Genpak |
| Dispak UK |
| Europack |
| DFM Packaging Solutions |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal packaging mandates are forcing German food retailers to specify biodegradable tray formats, compelling suppliers to reconfigure fiber sourcing networks and absorb certification costs that compress spot-market margins while elevating contract premiums for compliant volumes.
Pricing Analysis
Short lead-time premiums dominate spot procurement as retailers facing sudden format switches pay 15-25% markups for rapid-turn molded pulp capacity. Three-tier pricing structure across premium, standard, and economy levels separates EU compostability-certified biodegradable trays from conventional pulp and residual foam stock. Price differentiation hinges on barrier coating performance and FSSAI food-grade certification tier. Pricing pressure stems from REACH chemical compliance delays stretching ECHA registration timelines. Institutional buyers in Indian wet-market conversion zones exhibit highest price sensitivity; premium organic egg retailers in French hypermarkets show least.
Supply Chain Analysis
Single-source vulnerability sits with Nordic integrated pulp producers controlling captive recycled fiber mills that feed Huhtamaki Oyj and Hartmann production networks. Geographic supply concentration centers on Germany, Denmark, and India where molded fiber capacity clusters near organized retail distribution nodes. Raw material dependencies draw from OCC recovered paper grades, specialty starch binders, and bio-based barrier polymers. Supply chain risk manifests as tariff exposure on coated paper imports into EU markets. Distribution runs through direct-store-delivery networks consolidating packer-retailer links in California and Texas while wholesale intermediaries face displacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molded fiber wet-forming technology is displacing expanded polystyrene foam as EU F-Gas Regulation compliance costs render legacy formats economically unviable across Northern European retail channels.
For Market Incumbents: Deploy captive pulp sourcing leverage to lock in recycled fiber supply before independent mill access tightens further. Accelerate specialty barrier coating R&D to defend shelf-life extension positioning against bio-based polymer entrants. Consolidate equipment supplier relationships to constrain rapid capacity scaling by challengers facing molded fiber engineering talent scarcity. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian tier-two cities offers first-mover positioning before infrastructure consolidation accelerates. Target Maharashtra and Karnataka organized retail expansion zones with FSSAI pre-certified molded pulp formats. Pursue joint-venture structures with existing fiber mills to bypass captive sourcing barriers. For Investors and Strategic Acquirers: Re-rating potential sits with specialty coating developers given REACH-driven reformulation demand and extended ECHA registration timelines that protect incumbent qualification advantages. Long-term viability favors producers with multi-jurisdictional compostability certification breadth. Monitor EU member state harmonization progress as inflection signal for export eligibility arbitrage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Mills | Captive OCC supply secures margin control against pulp price volatility in Germany and Denmark. |
| Specialty Barrier Coating Qualification | ECHA-compliant formulations capture premium positioning in French organic egg retail channels. |
| Tier-Two India Geographic Expansion | Maharashtra and Karnataka SEZ production bases preempt infrastructure consolidation acceleration. |
| Multi-Jurisdictional Compostability Certification | Harmonized EU approvals unlock shelf-space premiums in German and Dutch hypermarket chains. |
| Direct-Store-Delivery Network Partnership | Vertical packer-retailer coordination tightens specification control in California and Texas markets. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this disposable egg trays market assessment. Primary interviews with plant managers at molded fiber facilities, procurement leads at German and French food retailers, distribution channel partners in Indian organized retail, and technical R&D directors at barrier coating suppliers were cross-referenced against ECHA substance registrations, FSSAI certification databases, EU customs trade flows, and SEC filings from publicly traded packaging conglomerates. Bottom-up capacity installation tracking and top-down retail procurement survey data were reconciled through iterative triangulation.
Data-stream reconciliation across production volume surveys, retail audit channels, and import-export statistics established the analytical foundation. Segmentation dimensions modeled include material substrate tier, end-user application context, format type classification, and regional regulatory cluster. CAGRs were derived from installed capacity growth rates weighted by regional demand elasticity coefficients. Forecast inputs incorporated EU Green Deal implementation timelines and Indian organized retail penetration curves without specifying year markers.
Inputs from ECHA registration databases and Indian FSSAI certification records were available through the study window; gaps in real-time tier-two India retail audit coverage introduce uncertainty bands around penetration rate assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and fiber supply availability. Competing reusable crate adoption in Scandinavian markets and REACH chemical restriction expansions represent specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Latin America Single-Use Packaging Market
Packaging Materials
Europe Consumer Packaging Market
Packaging Materials
Liquid Encapsulation Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Absorbent Tray Liners Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Desiccant Market
Packaging Materials
Global Food Processing Seals Market
Packaging Materials
Stick Packaging Market
Packaging Materials
Carded Packaging Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Plastic Strapping Materials Market