
 Urinary Protein Reagents Market | 2026-2036
Urinary Protein Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Protein Reagents Market Analytics
Colloidal gold conjugates are rebalancing cost-performance trade-offs in lateral flow protein detection assays. Siemens Healthineers AG leverages its embedded installed base of urinalysis analyzers to sustain recurring reagent revenue streams. Bio-Rad Laboratories, Inc. specializes in high-sensitivity immunoassay formulations that anchor its position in reference laboratory segments. Thermo Fisher Scientific Inc. controls broad distribution channels that extend its reach into academic and contract research settings.
Urinary protein reagents comprise buffered chemical formulations, chromogenic substrates, and calibrated antibody conjugates designed to detect and quantify albumin, total protein, or specific protein markers in urine specimens through photometric or immunochemical endpoints. These reagents enable early detection of renal dysfunction, diabetic nephropathy progression, and pre-eclampsia risk stratification in both centralized laboratories and near-patient environments. Dipstick formulations retain volume leadership in point-of-care settings due to minimal equipment requirements and rapid turnaround, while immunoassay platforms capture expanding share in clinical laboratories where quantitative precision drives reimbursement alignment. Fluorescent detection technologies are gaining fastest adoption among research institutes pursuing lower limit-of-quantification for microalbumin screening protocols.
The FDA's in vitro diagnostic regulatory framework, alongside CLIA complexity categorization standards, shapes product development priorities and market access pathways for reagent manufacturers seeking clinical laboratory placement. EMA's IVDR transition timeline and Japan's PMDA quality management requirements create parallel compliance obligations for multinational suppliers operating across regulated jurisdictions. Stakeholders must monitor evolving precision medicine reimbursement policies that increasingly tie proteinuria testing frequency to value-based kidney care contracts rather than fee-for-service schedules.
Market Dynamics
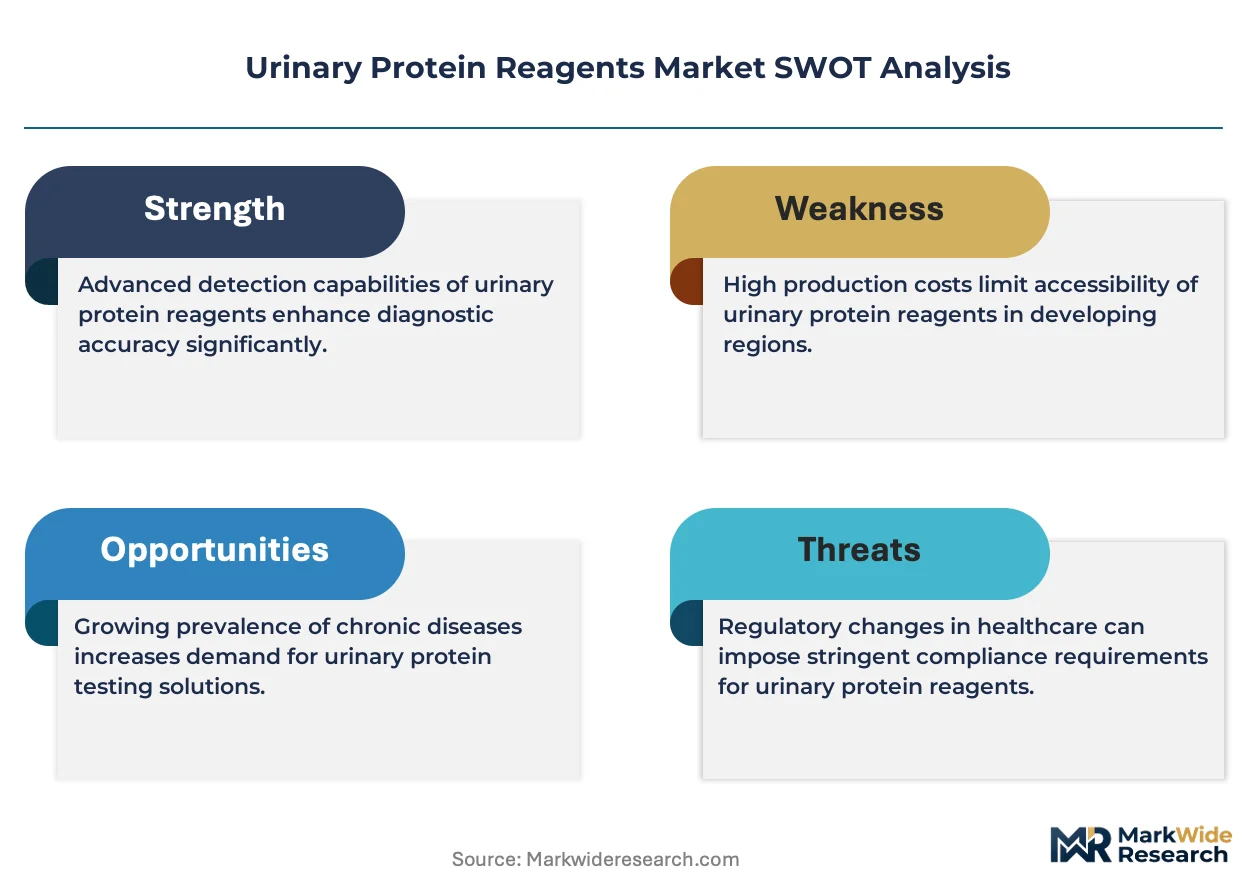
The FDA's harmonization of in vitro diagnostic standards is compressing development timelines for reagent manufacturers while elevating analytical performance requirements across clinical laboratory segments. This regulatory recalibration is forcing simultaneous investment in quality management systems and assay precision improvements.
Growth Catalysts
- CLIA complexity categorization:The FDA's tiered regulatory framework for clinical laboratory tests creates clear commercialization pathways for moderate-complexity protein assays, accelerating placement in hospital-based laboratories.
- Chronic kidney disease monitoring protocols:Expanding clinical guidelines for quantitative proteinuria testing in diabetic patient populations drive recurring reagent consumption in nephrology and endocrinology practices.
- Point-of-care lateral flow technology:Colloidal gold conjugate chemistry enables rapid albumin detection without dedicated instrumentation, penetrating resource-limited settings and physician office laboratories.
Market Restraints
- Antibody raw material concentration:High-affinity monoclonal antibody supply concentrates among a limited set of specialized bioproduction facilities, exposing reagent manufacturers to batch-to-batch variability and allocation constraints.
- EMA IVDR transition compliance burden:The European Union's In Vitro Diagnostic Regulation imposes expanded clinical evidence requirements and notified body involvement, extending time-to-market and certification costs for quantitative immunoassay platforms.
- Photometric endpoint limitations:Traditional chromogenic substrate methods face sensitivity ceilings that restrict detection of microalbumin at early disease stages, creating performance gaps against emerging fluorescent detection alternatives.
Strategic Opportunities
- Near-patient testing expansion:Retail clinic networks and urgent care chains in the United States seek waived-complexity protein assays that reduce laboratory send-out volumes and accelerate clinical decision-making.
- Japan PMDA quality management alignment:Harmonized international standards for in vitro diagnostic manufacturing enable streamlined multi-jurisdiction product registrations, reducing redundant facility audits and documentation.
- Pre-eclampsia risk stratification protocols:Obstetric care guidelines increasingly incorporate serial proteinuria testing for hypertensive disorders of pregnancy, opening dedicated reagent demand in women's health service lines.
Industry Challenges
- Legacy analyzer integration complexity:Open-system reagent formulations must achieve seamless compatibility with embedded urinalysis platforms from multiple manufacturers, requiring extensive analytical validation and software interface development.
- Cross-reactivity elimination:Antibody specificity engineering demands iterative epitope mapping and blocking reagent optimization to eliminate interference from structurally similar urinary proteins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Protein Reagents Market |
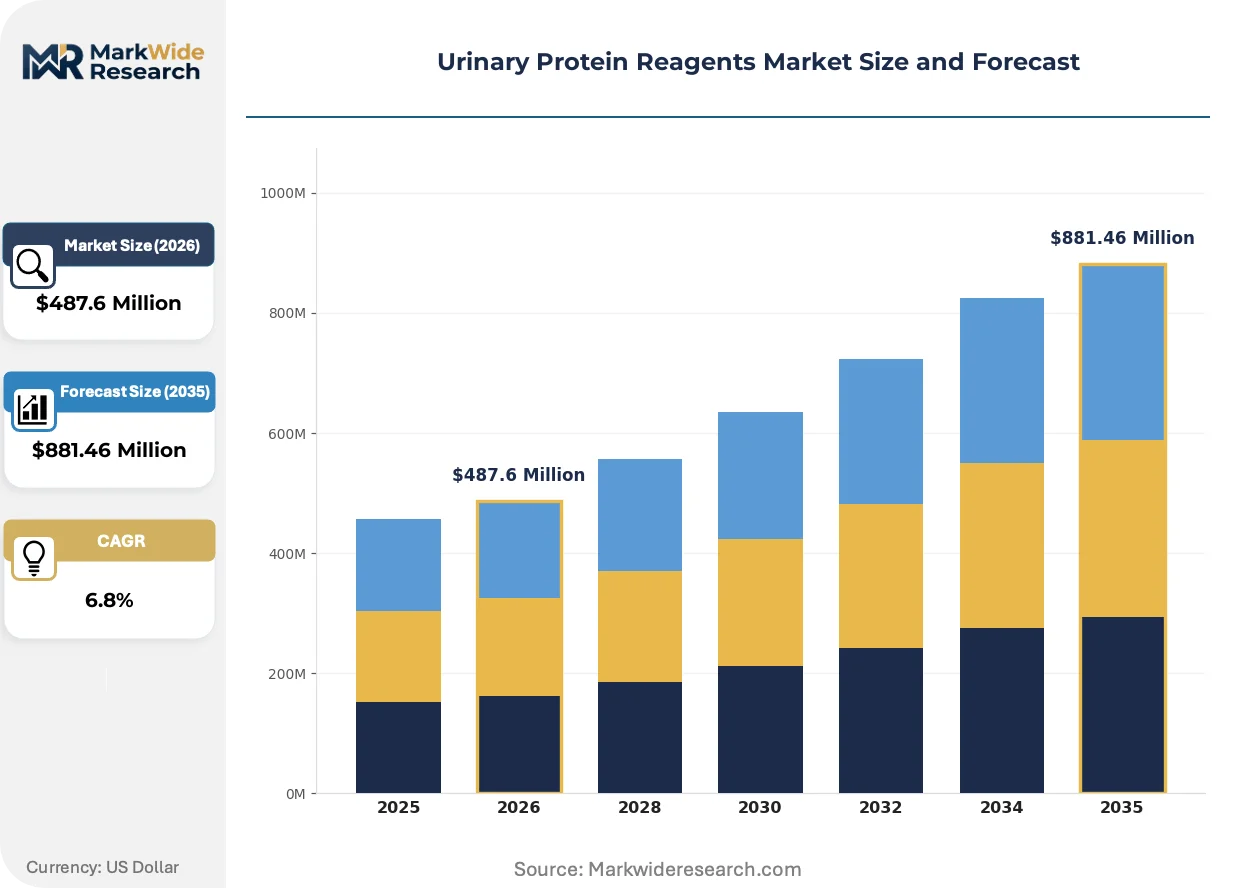
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dipstick, Control Solutions, Test Strips, Software Application: Clinical Laboratories, Home Care, Research Institutes, Diagnostic Centers End User: Hospitals, Point-of-Care Testing, Ambulatory Surgical Centers, Academic Institutions Technology: Colorimetric, Fluorescent, Electrophoresis, Immunoassay |
| Companies Covered | Siemens Healthineers AG, F. Hoffmann-La Roche Ltd, Abbott, Danaher Corporation, Sysmex Corporation, Thermo Fisher Scientific Inc., QuidelOrtho Corporation, Becton, Dickinson and Company, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Protein Reagents Market Evolving Landscape
Fluorescent detection modalities are compressing limit-of-quantification thresholds while regulatory pressure on analytical traceability reshapes quality control protocols across manufacturing operations.
Time-resolved fluorescence immunoassay technology is electrifying microalbumin screening protocols by enabling sub-nanogram-per-milliliter sensitivity without enzymatic amplification steps. Research institutes and specialized reference laboratories are adopting these platforms for early diabetic nephropathy detection studies. This sensitivity threshold compression is displacing conventional turbidimetric methods in protocols where quantitative precision determines reimbursement eligibility.
The FDA's ongoing in vitro diagnostic harmonization initiative mandates standardized reference materials and commutability studies for protein calibration traceability. Manufacturers must now demonstrate metrological linkage to certified reference materials across reagent lots, elevating production quality systems. Clinical laboratories in the United States face expanded proficiency testing requirements that favor suppliers with robust calibration verification programs.
Integrated health networks are consolidating laboratory procurement decisions under centralized supply chain functions, displacing decentralized department-level purchasing. Hospital systems now negotiate multi-year reagent contracts tied to analyzer placement and volume commitments, compressing vendor switching flexibility. This concentration is most visible in United States metropolitan markets where health system mergers have created super-regional laboratory networks.
Urinary Protein Reagents Market Segmentation
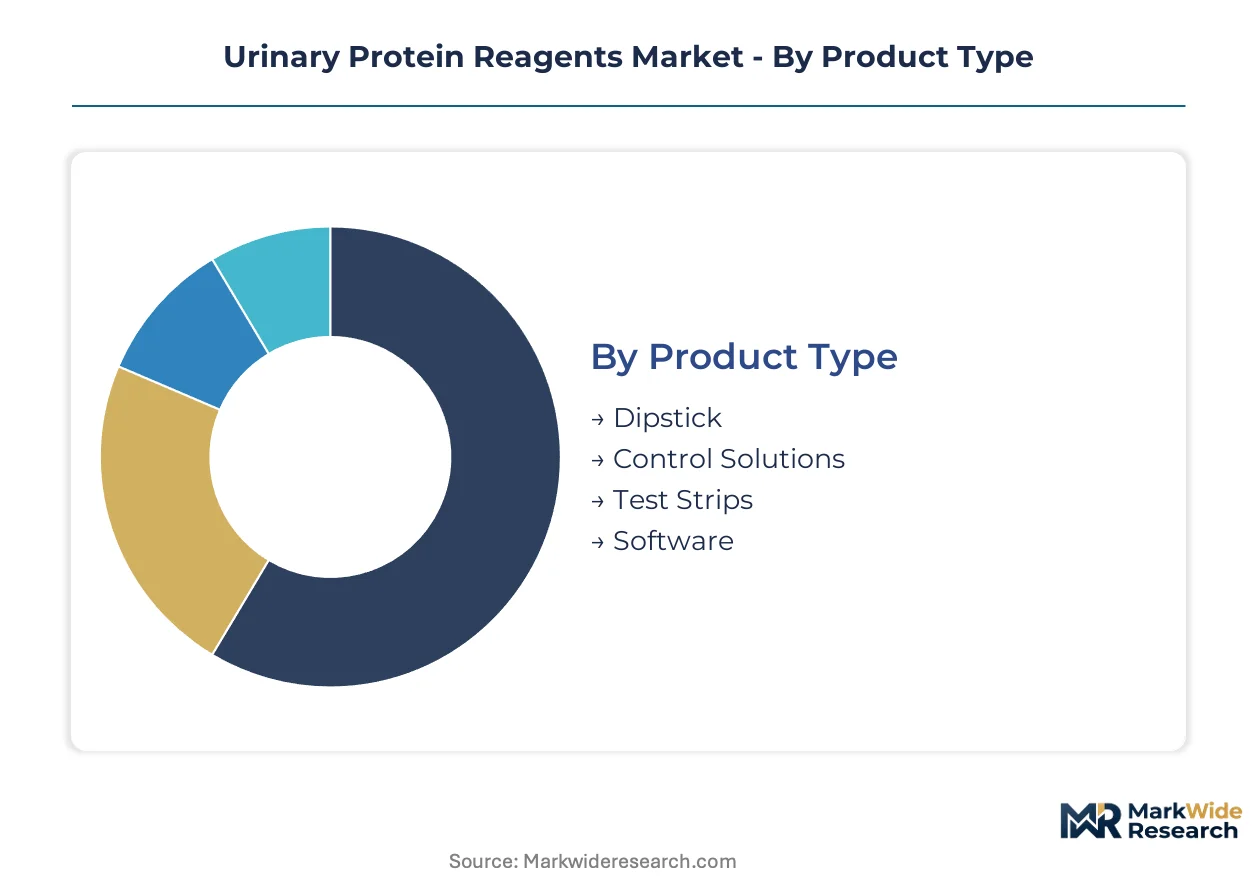
Urinary protein reagents serve distinct performance requirements across testing environments, from rapid qualitative screening to precise quantitative measurement. Segment boundaries reflect trade-offs between analytical sensitivity, equipment requirements, and regulatory complexity that shape procurement decisions in clinical and research settings.
Product Type:
Upgrade cycles in urinalysis instrumentation are rebalancing reagent portfolios as laboratories retire legacy photometric systems and adopt integrated modular platforms.
- Dipstick:Cellulose pads impregnated with buffered tetrabromophenol blue and pH indicators enable rapid visual or semi-quantitative protein detection without instrumentation. Demand concentrates in physician office laboratories across the United States, where waived-complexity classification under CLIA reduces regulatory overhead and accelerates reimbursement.
- Test Strips:Calibrated reagent strips with standardized colorimetric reaction zones pair with handheld readers for quantitative albumin-to-creatinine ratios. Home care segments in Germany and Japan are adopting these systems for diabetic nephropathy monitoring protocols that require frequent testing outside centralized facilities.
- Control Solutions:Stabilized protein matrices with assigned target values verify analyzer performance across reagent lots. Reference laboratories in the United Kingdom require these materials for ISO 15189 accreditation compliance.
- Software:Data management platforms integrate analyzer outputs with laboratory information systems for trend analysis and automated flagging. Academic medical centers in the United States deploy these tools for population health surveillance of chronic kidney disease progression.
Dipstick sits at the top of the volume ranking, with test strips climbing the fastest.
Application:
Cost tier differentiation separates high-throughput automated platforms from resource-limited settings where capital constraints favor manual methods.
- Clinical Laboratories:High-volume automated analyzers process hundreds of samples hourly using turbidimetric or immunoturbidimetric endpoints. Hospital-based laboratories in France and Italy prioritize these systems for integrated chemistry-urinalysis workflows that consolidate staffing and reduce turnaround times.
- Diagnostic Centers:Independent testing facilities perform proteinuria screening for employment physicals and insurance underwriting. These operators in Spain and Poland seek mid-range analyzers that balance throughput with reagent cost per reportable result.
- Research Institutes:Specialized protocols demand ultra-sensitive detection of microalbumin and specific protein isoforms. Investigators at Swedish and Dutch universities are adopting time-resolved fluorescence platforms for longitudinal cohort studies.
- Home Care:Patient-operated systems enable remote monitoring of pregnancy-induced hypertension and diabetic kidney disease. Reimbursement expansion in Japan's long-term care insurance program is accelerating adoption among elderly populations in rural prefectures.
Clinical laboratories command the largest reagent expenditure share, while home care demonstrates the steepest expansion trajectory.
End User:
Customer type segmentation reveals divergent purchasing authority structures, from centralized hospital supply chains to decentralized academic procurement.
- Hospitals:Integrated health networks negotiate multi-year reagent contracts tied to analyzer placement commitments. Systems in the United States Midwest have consolidated purchasing for dozens of affiliated laboratories under single vendor relationships.
- Point-of-Care Testing:Emergency departments and urgent care clinics require waived or moderate-complexity assays with results within minutes. Retail clinic chains in Texas and Florida are standardizing on lateral flow protein tests to reduce laboratory send-out volumes.
- Ambulatory Surgical Centers:Pre-operative proteinuria screening satisfies anesthesia safety protocols. These facilities in California favor single-use dipstick formats that eliminate reagent storage and calibration requirements.
- Academic Institutions:Teaching hospitals and medical schools combine clinical service with research protocols. Institutions in Massachusetts and North Carolina maintain diverse reagent inventories to support both routine diagnostics and experimental assay development.
Hospitals anchor reagent consumption by value, with point-of-care testing gaining share fastest.
Technology:
Maturity curves separate established chromogenic methods from emerging detection modalities that command premium pricing for superior analytical performance.
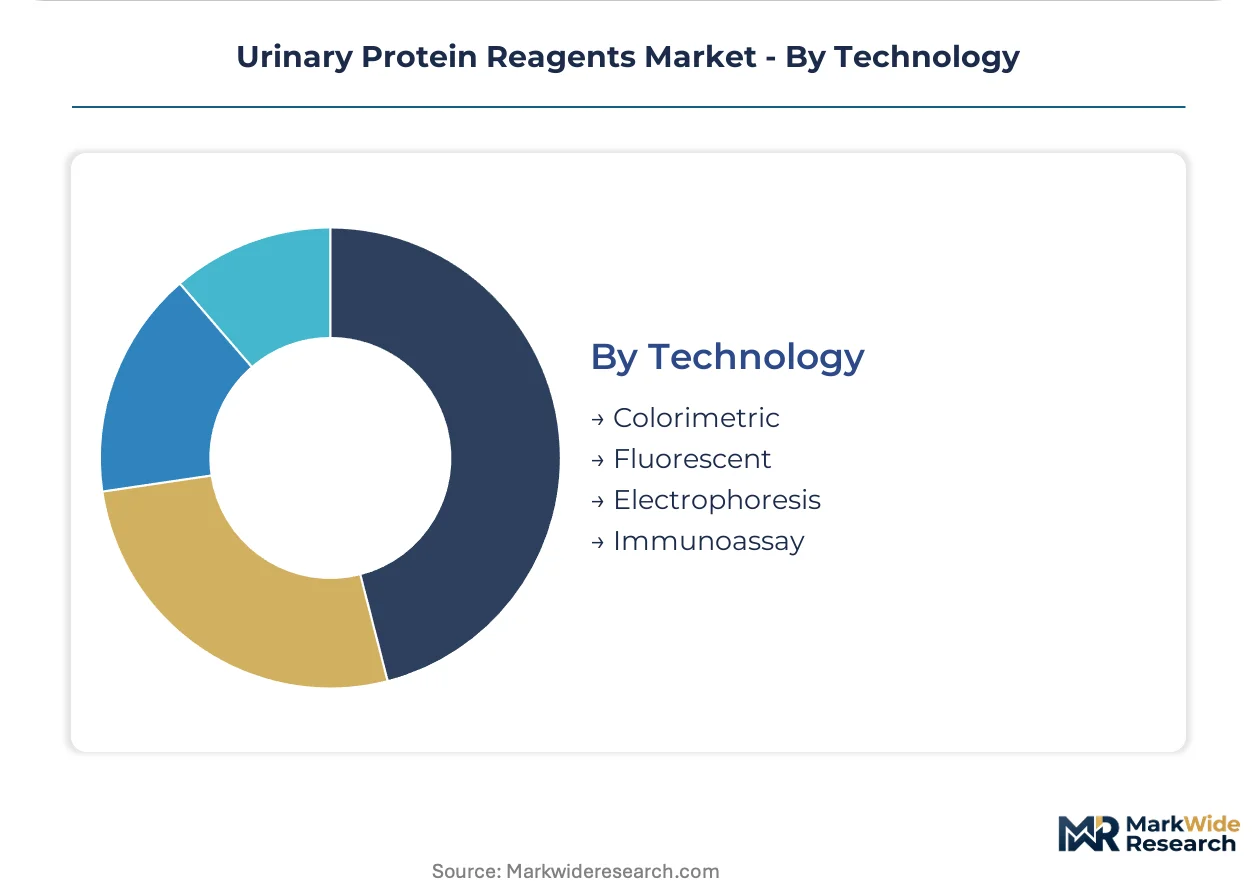
- Immunoassay:Antibody-based quantification of albumin and specific proteins achieves high specificity through epitope recognition. Nephrology reference laboratories in Switzerland and Austria rely on these methods for definitive proteinuria classification that determines treatment eligibility.
- Fluorescent:Time-resolved fluorescence and chemiluminescence detection compress limit-of-quantification below conventional methods. Specialty laboratories in South Korea are adopting these platforms for early diabetic nephropathy screening protocols.
- Colorimetric:Chromogenic substrate reactions with protein-binding dyes remain the workhorse for total protein measurement. Public hospital networks in Brazil and Mexico depend on these cost-effective methods for high-volume screening programs.
- Electrophoresis:Separation techniques identify protein fractions and monoclonal components in urine. Clinical immunology laboratories in Australia use these methods for multiple myeloma workup and Bence Jones protein detection.
Colorimetric methods retain volume leadership, with fluorescent detection expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated health networks in the United States are consolidating laboratory procurement decisions under centralized supply chain functions, creating super-regional purchasing power that reshapes vendor relationships across metropolitan markets.
United States
Hospital system mergers in the Midwest and Southeast have created multi-state laboratory networks negotiating multi-year reagent contracts tied to analyzer placements. FDA harmonization of in vitro diagnostic standards elevates quality benchmarks for manufacturers seeking CLIA-certified laboratory access. Greater Boston academic medical centers deploy data management platforms for population health surveillance of chronic kidney disease progression.
Germany
Home care segments adopt calibrated reagent strips with handheld readers for diabetic nephropathy monitoring protocols requiring frequent testing outside centralized facilities. EMA's IVDR transition imposes expanded clinical evidence requirements and notified body involvement for quantitative immunoassay platforms. Frankfurt and Munich host reference laboratories requiring stabilized protein matrices for ISO 15189 accreditation compliance.
Japan
Reimbursement expansion in long-term care insurance programs accelerates patient-operated system adoption among elderly populations in rural prefectures. PMDA quality management requirements create parallel compliance obligations for multinational suppliers alongside FDA and EMA frameworks. Tokyo and Osaka metropolitan areas concentrate nephrology reference laboratories relying on antibody-based quantification methods.
United Kingdom
Independent testing facilities perform proteinuria screening for employment physicals and insurance underwriting, seeking mid-range analyzers balancing throughput with reagent cost per reportable result. MHRA alignment with IVDR timelines extends certification requirements for quantitative platforms. London and Manchester clinical immunology laboratories use electrophoresis separation techniques for multiple myeloma workup and Bence Jones protein detection.
South Korea
Specialty laboratories adopt time-resolved fluorescence platforms for early diabetic nephropathy screening protocols demanding sub-nanogram-per-milliliter sensitivity. MFDS regulatory pathways shape product development priorities for domestic and multinational reagent manufacturers. Seoul Capital Area research institutes pursue lower limit-of-quantification for microalbumin screening protocols using emerging fluorescent detection technologies.
Urinary Protein Reagents Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and installed base leverage, creating tiered competition where scale advantages meet specialized formulation expertise. The vendor base separates into three strategic archetypes: diversified diagnostics conglomerates with embedded analyzer ecosystems, specialized immunoassay developers serving reference segments, and regional distributors controlling local channel access. Dominant competitive moves include analyzer placement commitments securing multi-year reagent contracts and backward integration into antibody raw material production to reduce supply concentration risk.
Within the diversified conglomerate tier, Siemens Healthineers AG leverages embedded installed bases to sustain recurring revenue streams, while Thermo Fisher Scientific Inc. controls broad distribution channels extending into academic and contract research settings. Bio-Rad Laboratories, Inc. occupies a position exemplifying high-sensitivity immunoassay specialization anchoring reference laboratory segments. These three companies represent the spectrum from scale-driven platform economics to precision-focused formulation expertise.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| F. Hoffmann-La Roche Ltd |
| Abbott |
| Danaher Corporation |
| Sysmex Corporation |
| Thermo Fisher Scientific Inc. |
| QuidelOrtho Corporation |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories, Inc. |
| Others |
Value Network & Pricing Analysis
Fluorescent detection technology migration is simultaneously elevating reagent manufacturing costs and concentrating supply among specialized substrate producers with proprietary conjugate chemistry expertise. This dual pressure compresses margins for mid-tier manufacturers while rewarding integrated suppliers with captive antibody production capabilities.
Pricing Analysis
Monoclonal antibody cost pass-through dominates pricing structures, with high-affinity reagent grades commanding substantial premiums over polyclonal alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from integrated health networks. Price erosion runs through economy-tier dipstick segments as contract manufacturers in India and China expand chromogenic substrate capacity. Hospital procurement committees exhibit lowest price sensitivity for reference-grade immunoassay reagents, while physician office laboratories prioritize per-test cost minimization.
Supply Chain Analysis
Cold-chain logistics costs for antibody raw materials constitute a structural burden, with temperature-controlled freight from specialized bioproduction facilities in the United States, Germany, and Japan driving landed cost premiums. Reagent formulations draw from concentrated sources of high-affinity monoclonal antibodies, chromogenic substrates, and stabilized protein matrices. Single-source vulnerability pervades rare-earth fluorescent dye supply, with limited qualified producers creating allocation risk for time-resolved fluorescence platforms. Distribution runs through authorized distributor networks serving clinical laboratory segments, supplemented by direct procurement relationships for super-regional health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage potential through EMA IVDR compliance cost differentials between established European manufacturers and emerging entrants leveraging notified body capacity in Eastern Europe.
For Market Incumbents: Acquire antibody production assets to secure raw material supply against batch-to-batch variability threats from concentrated bioproduction facilities. Siemens Healthineers and Roche should deepen backward integration into colloidal gold conjugate manufacturing. Consolidate analyzer placement contracts with multi-year reagent exclusivity clauses to defend installed base revenue against open-system competitors.
For New Entrants and Emerging Players: Fluorescent detection sensitivity advantages create entry leverage for specialized immunoassay developers targeting reference laboratory segments underserved by turbidimetric incumbents. Home care testing in Japan and Germany presents the most penetrable white space, with reimbursement expansion enabling patient-operated system adoption. Pursue regulatory pathway efficiency through PMDA quality management alignment to accelerate multi-jurisdiction product registrations.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with strong channel control but limited formulation capabilities. Long-term viability favors suppliers with demonstrated calibration traceability programs and ISO 15189-compliant quality systems. Watch FDA harmonization timeline acceleration as the inflection signal for consolidation pressure on mid-tier manufacturers lacking metrological linkage infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Antibody Production Backward Integration | Captive supply of high-affinity monoclonal reagents reduces batch variability exposure from limited bioproduction facilities. |
| Fluorescent Detection Platform Launch | Time-resolved fluorescence sensitivity compression displaces turbidimetric methods in reimbursement-sensitive reference protocols. |
| EMA IVDR Notified Body Partnership | Streamlined certification pathways accelerate quantitative immunoassay platform access across European clinical laboratory networks. |
| Home Care Reimbursement Strategy | Japan long-term care insurance program alignment unlocks patient-operated system demand in elderly rural prefectures. |
| Analyzer Placement Commitment Programs | Multi-year reagent contracts tied to embedded instrument bases secure recurring revenue against open-system competition. |
Research Methodology
Bottom-up clinical laboratory and point-of-care testing modeling reconciled against top-down reagent manufacturer production tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at IVD manufacturers, hospital procurement managers at integrated health networks, and biomedical engineers at reference laboratories combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation, and CMS Medicare reimbursement databases. Trade data from customs records and GPO contract repositories provided shipment volume cross-checks against manufacturer-reported reagent consumption.
Historical trendline analysis of analyzer placements and reagent consumption patterns established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, application tier, end-user category, and technology platform dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves adjusted for protocol adoption rates and reimbursement policy shifts. Forecast inputs included CLIA complexity categorization evolution, chronic kidney disease guideline expansion, and fluorescent detection technology substitution curves.
The model holds under stable regulatory harmonization timelines and continued integrated health network consolidation; deviation in FDA enforcement intensity or EMA notified body capacity constraints would shift volume projections. Stakeholders should weight assumptions against their own operating context and regional reimbursement policy trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Influenza Diagnostics Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Global Urinalysis Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Blood Urea Nitrogen Diagnostics Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Neglected Tropical Diseases Diagnosis Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
EMEA Meningitis Diagnostic Testing Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
In Vitro Diagnostics Test Kit Market