
 Global Urinalysis Market | 2026-2036
Global Urinalysis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Urinalysis Market Foresight
The EU Green Deal is broadening sustainability requirements for in vitro diagnostic consumables, compelling manufacturers to reformulate reagents and reduce single-use plastic waste across urinalysis workflows. Siemens Healthineers AG leverages its automated analyzer installed base to sustain recurring reagent revenue streams across European hospital networks. Beckman Coulter Inc. anchors its competitive stance through integrated laboratory informatics that connect urinalysis results with broader clinical chemistry panels. Sysmex Corporation differentiates via flow cytometry-based particle analysis, occupying a premium tier in high-volume reference laboratories.
Urinalysis encompasses the physical, chemical, and microscopic examination of urine to detect metabolic disorders, renal dysfunction, urinary tract infections, and substance use. Automated analyzers now process samples through reflectance photometry and digital microscopy, delivering standardized results within minutes for clinical decision-making. Dipstick tests remain the highest-volume segment due to their low cost and minimal training requirements, though margin pools concentrate in flow cytometers where instrument-reagent bundling locks in long-term contracts. Biosensors represent the fastest-growing technology dimension, as electrochemical detection platforms enable portable, connectivity-enabled devices for decentralized settings.
FDA clearance pathways shape product entry timelines for novel urinalysis platforms in the United States, while the EU MDR and IVDR frameworks impose stricter clinical evidence requirements on manufacturers serving European diagnostic laboratories. Japan's PMDA maintains rigorous post-market surveillance standards that filter out lower-quality consumables from its domestic supply chain. Stakeholders must monitor how evolving reimbursement codes for preventive kidney disease screening in Medicare and comparable national health programs reshape volume distribution between centralized laboratories and point-of-care sites.
Market Dynamics
The EU Green Deal is electrifying sustainability mandates across urinalysis consumables, compelling manufacturers to reformulate reagents and eliminate single-use plastics while point-of-care automation compresses testing turnaround times from hours to minutes.
Growth Catalysts
- Preventive screening mandates:Medicare reimbursement codes for chronic kidney disease surveillance in the United States are expanding testing volumes across primary care networks.
- Flow cytometry platforms:Automated particle analysis technology is displacing manual microscopy in high-throughput reference laboratories, locking in long-term reagent contracts.
- Aging demographics:Germany, Japan, and the United States are experiencing intensified demand for metabolic disorder detection as elderly populations require continuous renal function monitoring.
Market Restraints
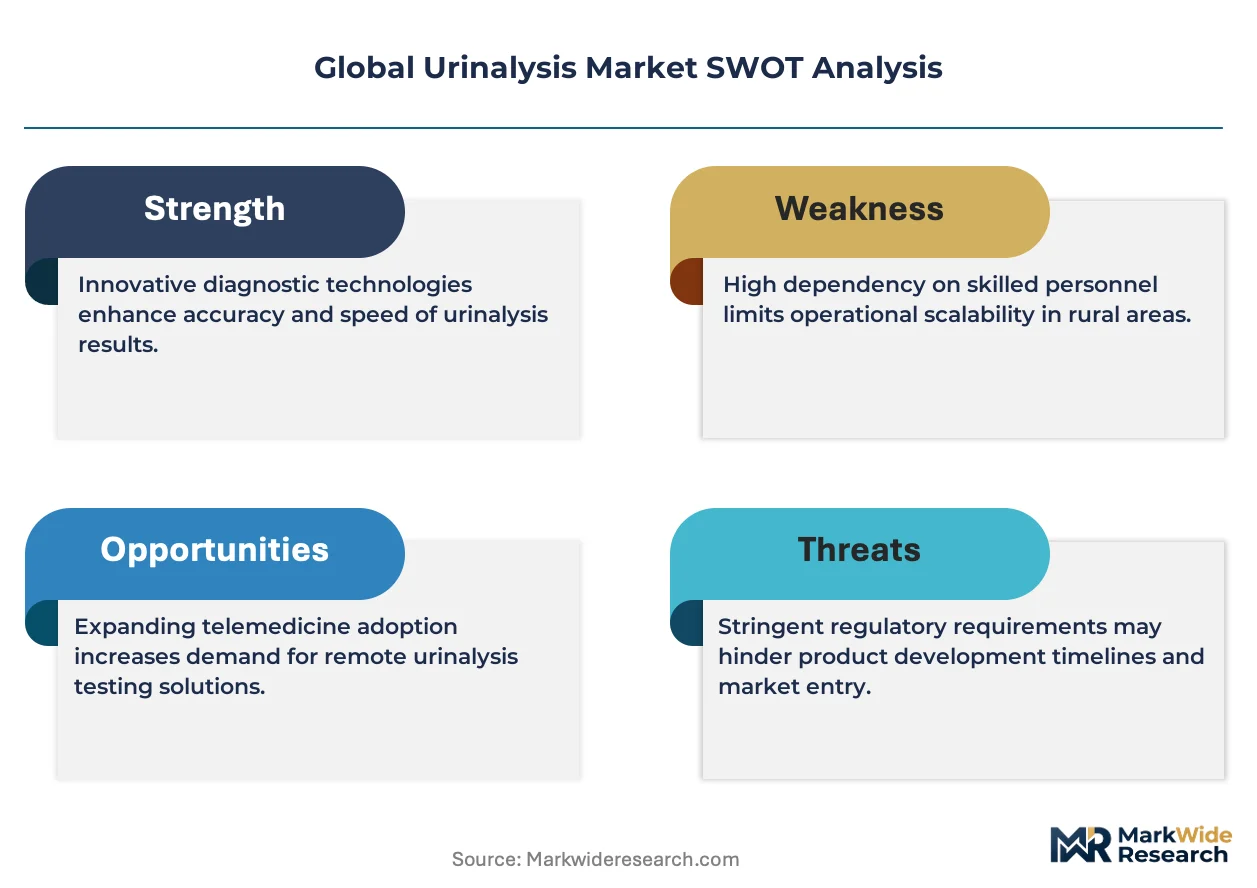
- IVDR compliance costs:The European Union's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements, extending product registration timelines and elevating documentation burdens.
- Reagent supply concentration:Critical enzyme and indicator chemical production clusters in select Asian manufacturing hubs, creating vulnerability to export restrictions or logistics disruptions.
- Dipstick margin compression:Commoditized test strips face pricing pressure from low-cost regional suppliers, constraining profitability in the highest-volume product segment.
Strategic Opportunities
- Decentralized biosensor deployment:Electrochemical detection platforms enabling smartphone-connected home monitoring remain underpenetrated in rural United States health systems.
- EU circular economy integration:The EU Green Deal's sustainable product requirements reward early movers with preferred procurement status in European hospital networks.
- Digital pathology convergence:Integration of artificial intelligence image recognition with automated microscopy is opening premium service tiers in Japanese and German academic medical centers.
Industry Challenges
- Cross-platform interoperability:Laboratory information system integration requires navigating disparate data standards between legacy hospital infrastructure and next-generation analyzers.
- Specialized field service engineering:Maintenance of flow cytometry-based systems demands scarce technical talent capable of calibrating fluidics and optical subsystems simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Urinalysis Market |
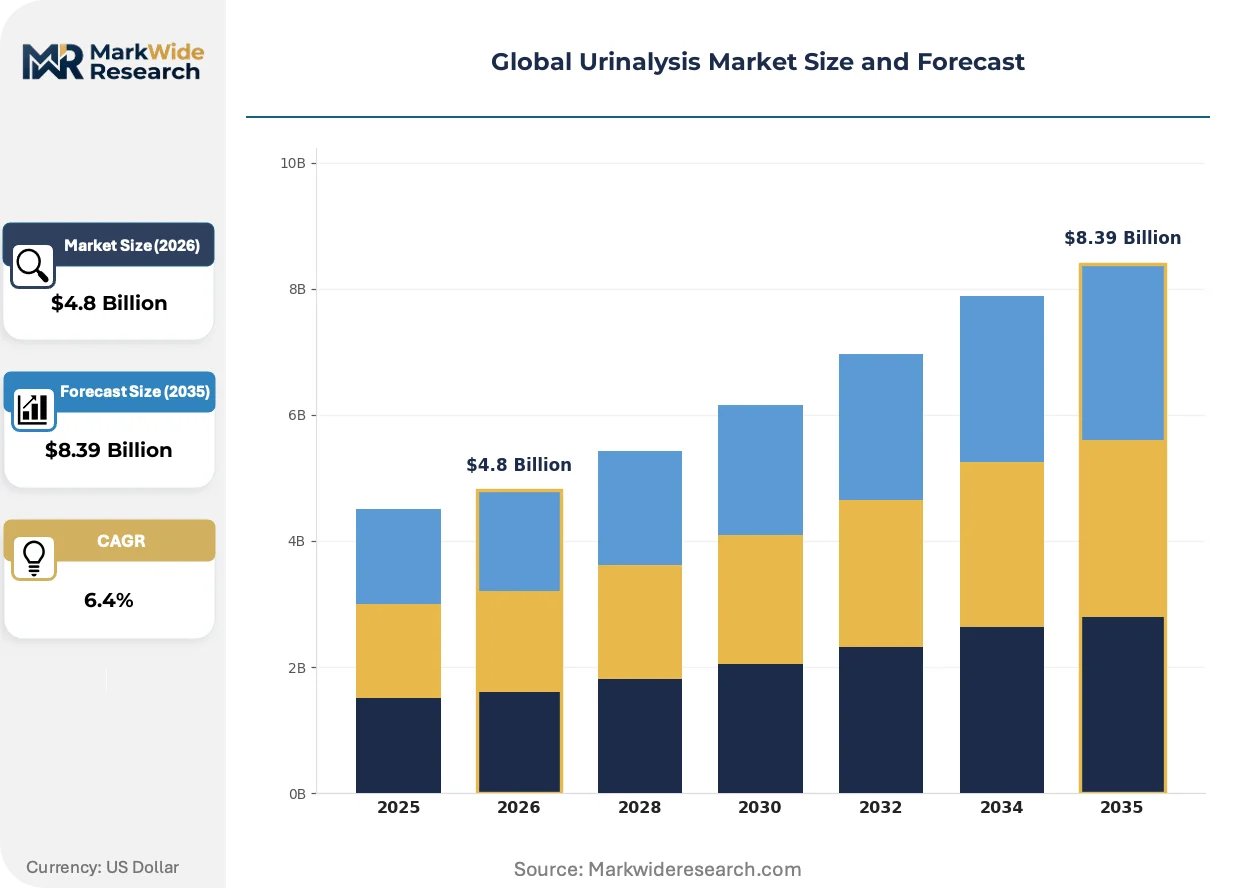
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Dipstick Tests, Microscopic Analyzers, Reagent Strips, Flow Cytometers Application: Urinary Tract Infection Detection, Kidney Disorder Diagnosis, Diabetes Monitoring, Drug Screening, Pregnancy Testing End User: Diagnostic Laboratories, Research Centers, Point-of-Care Facilities, Veterinary Clinics, Blood Banks Technology: Colorimetry, Spectrophotometry, Immunoassay, Biosensors, Microscopy |
| Companies Covered | Siemens Healthineers AG, F. Hoffmann-La Roche Ltd, Cardinal Health Inc., Abbott, Sysmex Corporation, Beckman Coulter Inc., ARKRAY Inc., Thermo Fisher Scientific Inc., QuidelOrtho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Urinalysis Market Shifts & Advancements
Automation architectures and connectivity protocols are converging to transform urinalysis from a batch-processed laboratory service into a real-time diagnostic input embedded across care continuums.
Digital microscopy augmented by convolutional neural networks is electrifying particle classification accuracy, reducing false-positive rates for cast and crystal identification. Mid-sized hospital laboratories in the United States and Germany are adopting these platforms to offset staffing shortages in clinical pathology. The technology is compressing the competitive advantage of centralized reference laboratories by enabling equivalent diagnostic quality at lower specimen transport costs.
The EU MDR and IVDR frameworks are tightening post-market surveillance obligations for urinalysis devices, mandating systematic performance data collection across the product lifecycle. Manufacturers serving European diagnostic laboratories must now maintain expanded clinical evidence portfolios and implement proactive vigilance reporting systems. High-complexity automated analyzers face disproportionate compliance burdens relative to simple dipstick products, reshaping portfolio prioritization decisions.
Consolidated purchasing by integrated delivery networks is displacing fragmented procurement across independent clinical sites, concentrating contract negotiation leverage among fewer buyers. Group purchasing organizations in the United States are unbundling instrument placement from exclusive reagent supply agreements, opening vendor switching opportunities previously locked by capital subsidy arrangements. This behavioral shift is most pronounced in multi-hospital systems pursuing standardized instrument fleets across affiliated outpatient clinics and emergency departments.
Global Urinalysis Market Segmentation
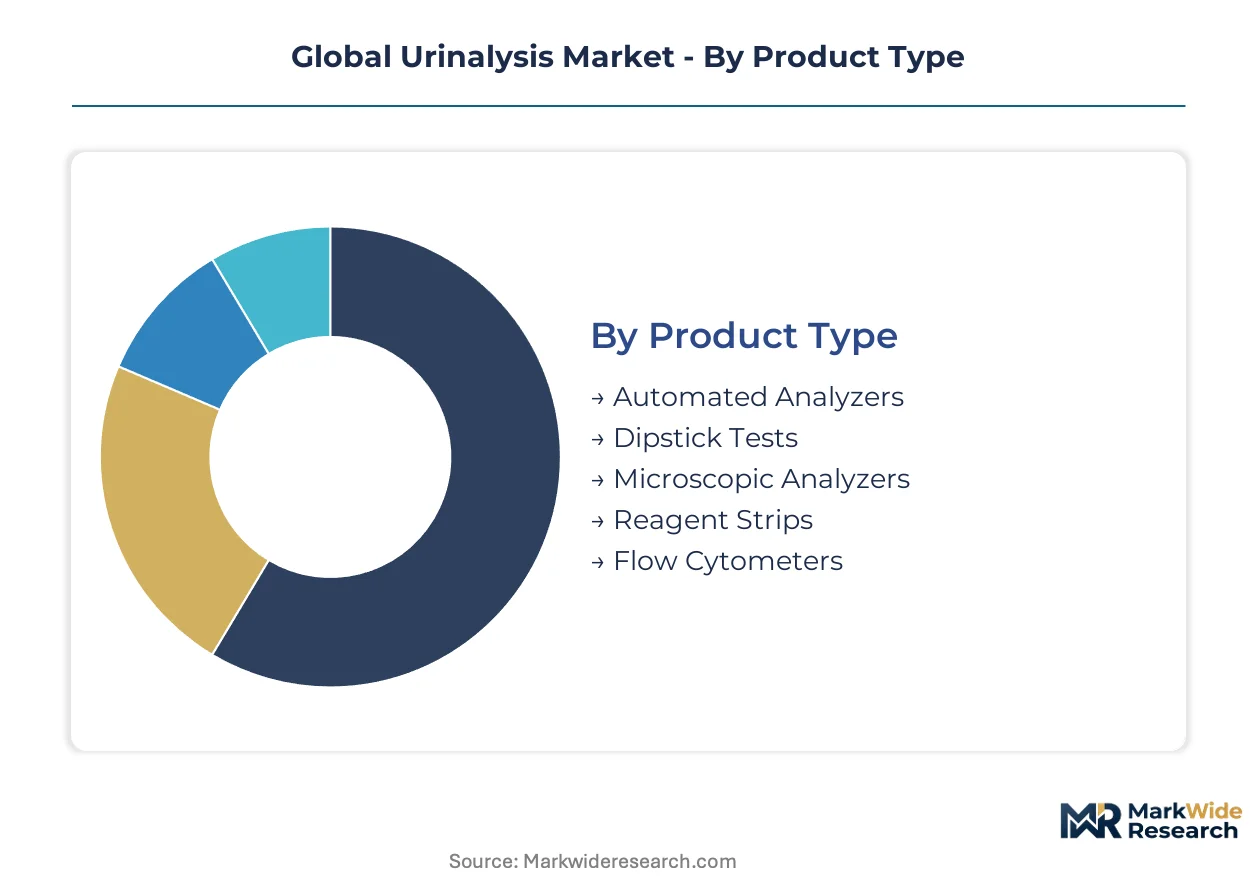
Urinalysis market segmentation reveals divergent capital requirements and margin profiles across product architectures. Technology choices determine whether vendors pursue high-volume consumable models or premium instrument placements with locked-in reagent streams.
Product Type:
Capital intensity varies dramatically across this category, with flow cytometry platforms demanding substantial upfront engineering investment while dipstick manufacturing scales through chemical formulation expertise.
- Automated Analyzers:Integrated systems combine reflectance photometry with digital microscopy for walk-away processing of 100+ samples hourly. Demand concentrates in German and Japanese hospital networks where laboratory staffing costs justify instrumentation expenditure against manual workflow alternatives.
- Flow Cytometers:Fluidics-based particle analysis systems achieve standardized enumeration of formed elements without centrifugation. Academic medical centers in the United States prioritize these platforms for their elimination of inter-operator variability in cast identification.
- Dipstick Tests:Chemically impregnated pads detect glucose, protein, blood, and nitrite through color change reactions. Primary care clinics across India and Brazil deploy these for their minimal training requirements and ambient storage stability.
- Microscopic Analyzers:Digital imaging systems automate sediment examination through motorized stage control and autofocus algorithms. Mid-sized European laboratories adopt these to offset clinical pathology staffing shortages.
- Reagent Strips:Single-use consumables designed for specific chemistry panels or confirmatory testing. Veterinary clinics in Australia and Canada represent an expanding consumption node for species-calibrated formulations.
Automated analyzers absorb the bulk of installed capacity; flow cytometers are expanding most quickly.
Application:
Clinical utility and reimbursement density shape segment prioritization, with chronic disease surveillance programs creating predictable volume basins that justify dedicated workflow investment.
- Kidney Disorder Diagnosis:Albumin-to-creatinine ratio testing and cast identification enable staging of chronic renal impairment. Medicare reimbursement expansion in the United States has intensified screening volumes across primary care networks serving elderly populations.
- Urinary Tract Infection Detection:Nitrite and leukocyte esterase screening combined with reflex culture protocols reduce unnecessary antibiotic prescriptions. German outpatient clinics leverage automated platforms for same-day result turnaround.
- Diabetes Monitoring:Glucose and ketone surveillance supports glycemic control assessment in insulin-dependent patients. Home monitoring adoption in Japan supplements laboratory-based HbA1c programs with real-time metabolic feedback.
- Drug Screening:Immunoassay-based detection of amphetamines, opioids, and cannabinoids serves workplace compliance and forensic toxicology. Employment screening mandates in Saudi Arabia and South Korea sustain demand for high-throughput confirmation workflows.
- Pregnancy Testing:hCG detection through lateral flow or laboratory immunoassay formats. Retail pharmacy distribution in the United Kingdom and France dominates volume, though clinical laboratory confirmation persists for ambiguous results.
Kidney disorder diagnosis commands the deepest reagent consumption per patient; urinary tract infection detection is climbing the fastest as antimicrobial stewardship programs proliferate.
End User:
Procurement sophistication and connectivity requirements stratify this category, with integrated delivery networks imposing standardization mandates that reshape vendor competitive dynamics.
- Diagnostic Laboratories:High-throughput facilities processing 500+ samples daily require middleware integration with laboratory information systems. Centralized reference laboratories in the United States and Germany anchor demand for multi-parameter automated platforms.
- Point-of-Care Facilities:Emergency departments and outpatient clinics prioritize turnaround time over test menu breadth. Biosensor-enabled devices with smartphone connectivity are penetrating rural health systems in Australia and Canada.
- Research Centers:Academic institutions demand flexible analytical capabilities for biomarker discovery and validation studies. Metabolomics applications in Swiss and Dutch universities drive adoption of mass spectrometry-coupled workflows.
- Veterinary Clinics:Companion animal and livestock health monitoring requires species-specific reference ranges. Diagnostic chains in the United Kingdom have consolidated procurement for standardized urinalysis across multi-site practices.
- Blood Banks:Donor health screening protocols incorporate urine analysis for infectious disease markers and substance detection. National transfusion services in Japan maintain rigorous quality standards filtering supplier eligibility.
Diagnostic laboratories absorb the bulk of installed capacity; point-of-care facilities are gaining share fastest as connectivity-enabled devices mature.
Technology:
Intellectual property density and regulatory clearance pathways differentiate competitive moats across detection modalities, with electrochemical platforms attracting venture investment for decentralized applications.
- Biosensors:Electrochemical transducers convert analyte binding into quantifiable current signals without optical components. Smartphone-integrated prototypes are advancing through FDA pre-submission for home kidney function monitoring.
- Spectrophotometry:Wavelength-specific absorbance measurement enables quantitative chemistry analysis with established reference methods. Centralized laboratories in Germany and Switzerland maintain these systems for regulatory compliance traceability.
- Colorimetry:Visual or instrument-read color comparison against calibrated standards. Dipstick manufacturing in China and India leverages mature chemical synthesis infrastructure for cost-optimized indicator production.
- Immunoassay:Antigen-antibody binding detection for specific protein and drug quantification. Confirmation testing workflows in forensic laboratories across the United States and United Kingdom depend on these methods for legal defensibility.
- Microscopy:Brightfield and phase-contrast examination of urinary sediment for formed element identification. Digital pathology integration in Japanese academic centers is automating particle classification through convolutional neural networks.
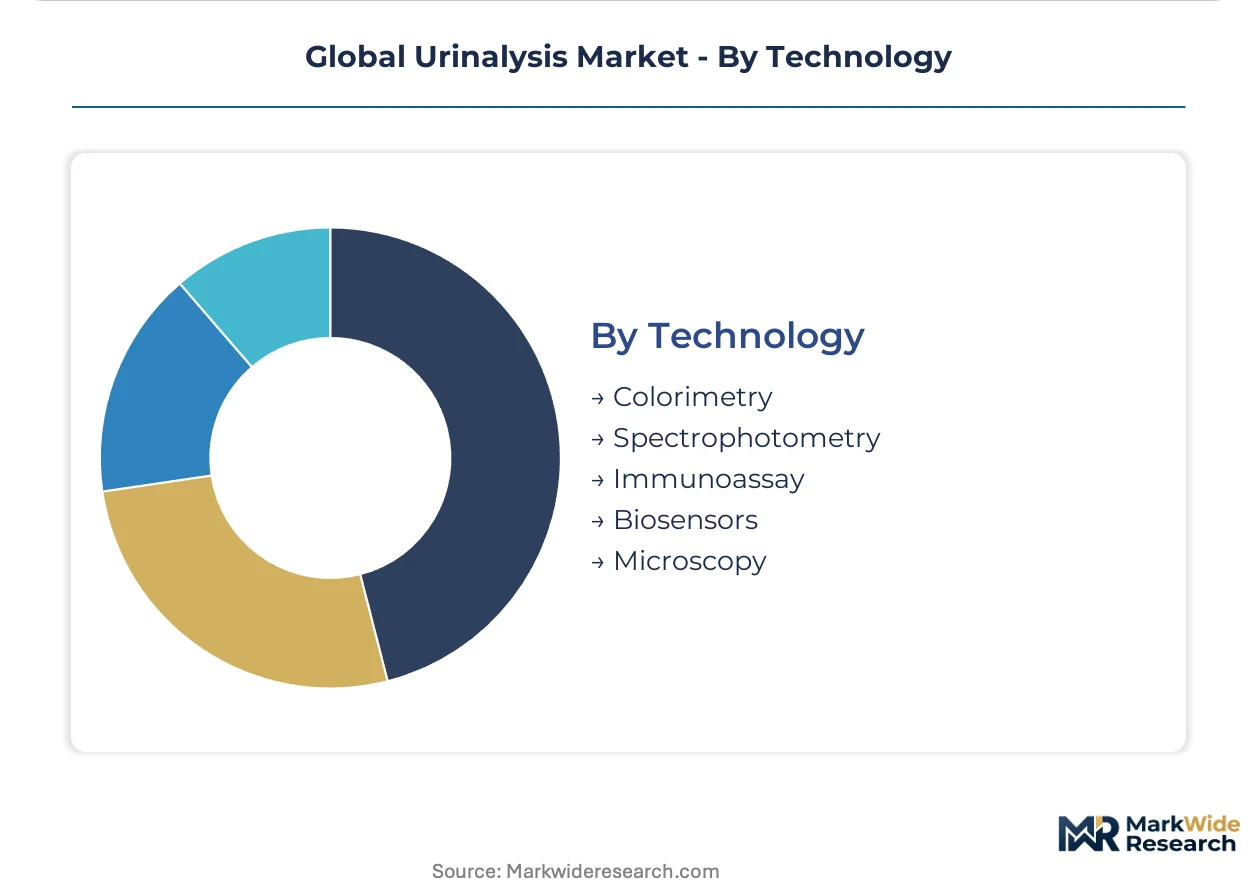
Spectrophotometry anchors the largest installed base; biosensors are expanding most quickly as connectivity and miniaturization converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors the highest density of automated urinalysis manufacturing, with Japanese precision engineering clusters supplying flow cytometry platforms to academic medical centers across Asia-Pacific and North America. Demand concentrates in aging societies with chronic disease surveillance programs.
United States
Medicare reimbursement expansion for chronic kidney disease screening drives primary care testing volumes. FDA clearance pathways shape entry timelines for novel platforms. Boston and San Diego biotechnology corridors host development programs for biosensor-enabled home monitoring devices.
Germany
Laboratory staffing costs justify high-throughput automation in hospital networks across Bavaria and North Rhine-Westphalia. EU IVDR compliance requirements extend product registration timelines. Siemens Healthineers leverages its installed base to sustain recurring reagent revenue across European networks.
Japan
PMDA post-market surveillance standards filter lower-quality consumables from domestic supply chains. Metropolitan Tokyo and Osaka medical centers prioritize flow cytometry for elimination of inter-operator variability. Sysmex Corporation occupies premium positioning in reference laboratories through particle analysis specialization.
China
NMPA regulatory frameworks govern in vitro diagnostic device registration for domestic and imported platforms. Yangtze River Delta manufacturing clusters produce cost-optimized dipstick reagents for export markets. Local procurement policies favor domestic suppliers in tier-two hospital networks.
India
CDSCO regulates diagnostic device quality standards for expanding private laboratory chains. Primary care clinics across Maharashtra and Karnataka deploy dipstick tests for ambient storage stability and minimal training requirements. Diagnostic chains consolidate procurement across multi-site practices.
Global Urinalysis Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with established laboratory informatics integration capabilities. Siemens Healthineers AG, F. Hoffmann-La Roche Ltd, and Abbott exemplify archetypes combining instrumentation with locked-in consumable revenue streams. Strategic moves concentrate on reagent contract bundling and middleware interoperability with hospital laboratory information systems.
Among German-based diversified health technology groups, Siemens Healthineers AG anchors the automated analyzer segment through recurring reagent arrangements. Swiss pharmaceutical and diagnostics conglomerate F. Hoffmann-La Roche Ltd occupies a position linking urinalysis with broader clinical chemistry portfolios. US-based Abbott exemplifies the point-of-care expansion archetype, representing connectivity-enabled platform development for decentralized settings. These three conglomerates sit within a tier where instrument placement economics and exclusive supply agreements determine competitive positioning.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| F. Hoffmann-La Roche Ltd |
| Cardinal Health Inc. |
| Abbott |
| Sysmex Corporation |
| Beckman Coulter Inc. |
| ARKRAY Inc. |
| Thermo Fisher Scientific Inc. |
| QuidelOrtho Corporation |
| Others |
Supply & Pricing Matrix
Polyethylene resin indices and specialty chemical feedstock benchmarks cascade through urinalysis consumable manufacturing, compressing margins on dipstick production while amplifying pricing power for flow cytometry reagents bundled with long-term service contracts. This cost transmission mechanism stratifies the market into three distinct tiers: premium instrument-reagent packages, mid-range automated platforms, and economy dipstick volumes.
Pricing Analysis
Throughput-based pricing anchors the automated analyzer segment, where hospitals negotiate per-sample rates that decline with volume commitment but lock in exclusive reagent supply. Price differentiation separates FDA-cleared platforms from CE-marked alternatives in European procurement, while brand premium sustains Sysmex positioning in Japanese reference laboratories. Pricing pressure stems from low-cost dipstick imports from Chinese manufacturers, eroding standard-tier margins. Primary care clinics in India and Brazil exhibit highest price sensitivity, whereas German hospital networks prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from United States group purchasing organizations and Japanese hospital consortia compel manufacturers to qualify secondary suppliers for critical enzymes and indicator chemicals. Production concentrates in China for dipstick reagents, Germany for precision fluidics components, and Japan for optical subsystems. The supply chain draws from indium tin oxide for biosensor electrodes, rare-earth phosphors for detection chemistry, and medical-grade polymers for consumable housings. Single-source vulnerability concentrates in Asian enzyme production clusters. Distribution runs through regional distribution centers serving integrated delivery networks in North America and hospital procurement cooperatives in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urinalysis market sits in a technology-transition phase where flow cytometry platforms are displacing manual microscopy, forcing incumbents to defend installed bases while new entrants exploit biosensor white space in decentralized settings.
For Market Incumbents: To counter biosensor-enabled point-of-care disruption, Siemens Healthineers and Beckman Coulter should deepen reagent contract bundling with middleware integration that raises switching costs for hospital laboratory information systems. Capacity addition in automated analyzer refurbishment programs extends asset lifecycles in budget-constrained European networks. Certification investment in EU IVDR clinical evidence portfolios filters out lower-tier competitors from premium procurement channels. For New Entrants and Emerging Players: Launch via connectivity-enabled distribution partnerships with rural United States health systems and Australian primary care networks where biosensor penetration remains underdeveloped. Target home kidney function monitoring as the most penetrable application, leveraging smartphone integration to bypass capital-intensive laboratory infrastructure. Pursue FDA pre-submission pathways for electrochemical detection platforms that enable direct-to-consumer deployment. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap reagent specialists with established European hospital network relationships and compliant IVDR documentation in Germany and Switzerland. Long-term viability over a five-to-ten-year window hinges on portfolio exposure to recurring consumable revenue rather than capital equipment placement. Monitor Medicare reimbursement code expansion for chronic kidney disease screening as the critical inflection signal for volume migration toward preventive testing modalities.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Contract Bundling | Instrument-reagent lock-in sustains recurring revenue across Siemens Healthineers' European installed base. |
| EU IVDR Compliance Investment | Clinical evidence portfolios secure preferred procurement status in German hospital networks. |
| Biosensor Platform Development | Electrochemical detection enables smartphone-connected home monitoring for rural United States deployment. |
| Middleware Interoperability Expansion | Laboratory information system integration raises switching costs for Beckman Coulter's analyzer customers. |
| Refurbishment Program Scaling | Asset lifecycle extension captures budget-constrained mid-sized European laboratory demand. |
Research Methodology
Independent corroboration across FDA 510(k) clearance databases, EU MDR/IVDR notified body documentation, and Japanese PMDA post-market surveillance records underwrites the qualitative findings. Primary interviews with clinical laboratory directors, hospital biomedical engineers, GPO contracts managers, and diagnostic reagent procurement officers combined with secondary validation from CMS Medicare reimbursement data, hospital procurement databases, and SEC 10-K filings of listed diagnostic manufacturers. Bottom-up instrument placement modeling and top-down reagent consumption estimates were triangulated against trade flow data from German and Japanese customs authorities.
Rate-of-change decomposition across the analysis window separates volume expansion from mix-shift effects and pricing dynamics. Segmentation dimensions modeled include product architecture, application area, end-user facility type, detection technology, and regional regulatory cluster. CAGRs were derived from instrument installed base projections coupled with per-sample reagent consumption rates. Forecast inputs incorporated Medicare reimbursement code expansion timelines for chronic kidney disease screening and EU Green Deal sustainable procurement mandate implementation schedules.
Regulatory clearance delays, reimbursement policy reversals, and raw material supply disruptions are the dominant revision risks. Deviation in Medicare preventive screening expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Global Antinuclear Antibody Test Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
Global Respiratory Diagnostics Market
Diagnostics
US Tissue Diagnostics Market
Diagnostics
Global Inflammatory Bowel Disease (IBD) Diagnostic Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Blood Culture Media Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market