
 Chlamydia Diagnostics Market | 2026-2036
Chlamydia Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Chlamydia Diagnostics Market Analysis
European IVD contract manufacturers is pivoting toward automated nucleic acid extraction lines to serve chlamydia assay kit demand. Roche Diagnostics leverages its installed base of cobas platforms to sustain molecular test volume in centralized labs. Abbott Laboratories anchors its position through Alinity m integration with sexually transmitted infection screening menus. Hologic Inc. differentiates via Panther system throughput for high-volume reference laboratories.
Chlamydia diagnostics encompasses laboratory and point-of-care methods for detecting Chlamydia trachomatis nucleic acids, antigens, or antibodies in clinical specimens, with NAAT sensitivity exceeding 95% in first-catch urine and vaginal swab matrices. The primary purpose is enabling antibiotic treatment initiation and partner notification to interrupt transmission chains. NAAT-based molecular diagnostics leads product type revenue due to superior analytical sensitivity and FDA-cleared multiplex panel compatibility. Point-of-care delivery mode grows fastest as CLIA-waived instrument footprints shrink and result turnaround compresses to under thirty minutes. Laboratory-based testing retains the deepest margin pools through bundled reimbursement with gonorrhea and trichomoniasis panels.
FDA 510(k) clearance pathways and CLIA complexity categorization shape product development timelines and site eligibility for chlamydia assays in the United States. EMA IVDR transition and Notified Body conformity assessments in Europe are forcing manufacturers to regenerate clinical evidence for legacy molecular diagnostic products. Stakeholders must monitor regulatory divergence between FDA streamlined dual-claim review and EU IVDR Class C technical documentation requirements when prioritizing geographic launch sequencing.
Market Dynamics
CLIA-waived point-of-care regulations in the United States are compressing result turnaround times and redistributing testing volume from centralized laboratories toward physician offices and retail clinics, forcing manufacturers to reconfigure assay formats and instrument footprints.
Growth Catalysts
- NAAT platform miniaturization:Semiconductor-based thermal cycling and microfluidic cartridge integration enable benchtop instruments for mid-volume hospital laboratories previously excluded from molecular diagnostics.
- EMA IVDR Class C pathway:European regulatory clarity on clinical evidence requirements for multiplex STI panels accelerates conformity assessment timelines for manufacturers with established quality management systems.
- Japan's METI infectious disease screening mandates:Routine chlamydia testing requirements for specific demographic cohorts expand insured reimbursement coverage and institutional procurement volumes.
Market Restraints
- Reimbursement compression in US Medicare:Bundled payment rates for STI screening panels limit standalone chlamydia assay pricing flexibility and compress manufacturer margins.
- Polymerase supply concentration:Thermostable DNA polymerase production concentrates among three specialized enzyme suppliers, creating input cost volatility and qualification bottlenecks.
- Sample-to-answer technical limitations:Current point-of-care NAAT platforms exhibit reduced analytical sensitivity with self-collected vaginal swabs compared to laboratory-processed specimens.
Strategic Opportunities
- India's CDSCO diagnostic registration reform:Streamlined import licensing and local manufacturing incentives lower market entry barriers for multinational IVD manufacturers.
- Telehealth-integrated home collection:Remote specimen collection kits with courier logistics partnerships create direct-to-consumer channels bypassing traditional laboratory networks.
- CRISPR-based detection convergence:Guide RNA-programmable nucleic acid recognition combined with smartphone-readable lateral flow reporters enables instrument-free molecular testing.
Industry Challenges
- Cross-training molecular diagnostics technicians:Laboratory workforce shortages in nucleic acid extraction and real-time PCR operation delay instrument installation and validation timelines.
- Legacy LIS integration complexity:Hospital information system interoperability requirements for bidirectional HL7 messaging consume substantial implementation resources and extend sales cycles.
- IVDR technical documentation regeneration:European Notified Body capacity constraints and retrospective clinical performance study requirements create certification backlogs for established assay portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlamydia Diagnostics Market |
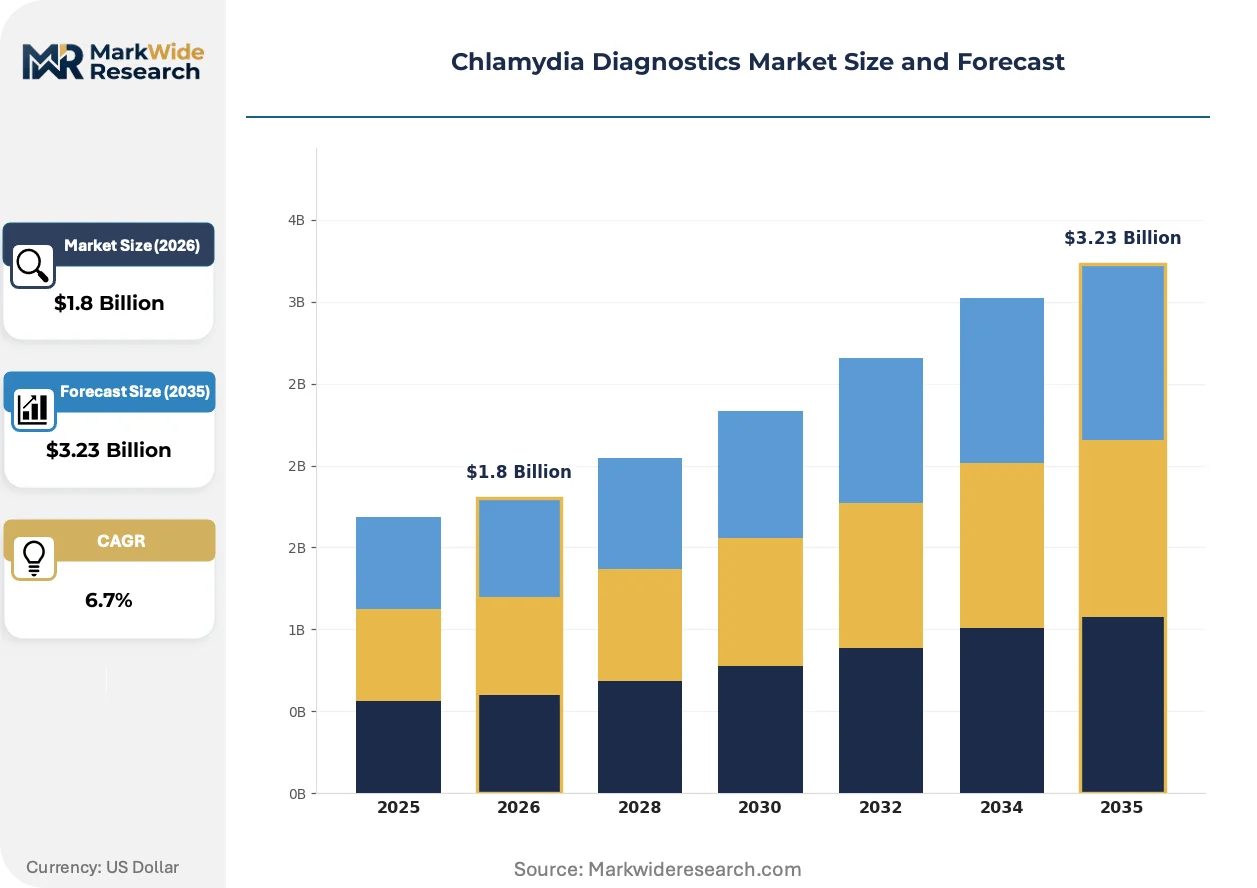
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NAAT, Antigen Test, Serology Test, Culture Test Delivery Mode: Point-of-Care, Laboratory-Based, Home Testing, Telehealth End User: Hospitals, Diagnostic Laboratories, Clinics, Home Users Technology: Molecular Diagnostics, Immunoassays, Culture Techniques, Hybridization |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Hologic Inc., Danaher Corporation, Thermo Fisher Scientific Inc., Becton Dickinson and Company, Siemens Healthineers, bioMérieux SA, QuidelOrtho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlamydia Diagnostics Market Emerging Trajectories
Digital connectivity and assay format flexibility are redrawing competitive boundaries between centralized laboratory systems and distributed point-of-care platforms, with regulatory complexity now a primary determinant of geographic launch sequencing.
Cartridge-based sample-to-answer systems is modularizing molecular diagnostics infrastructure. Mid-volume hospital networks in Germany and Japan are adopting these platforms to retain STI testing in-house rather than outsourcing to reference laboratories. This technology is modularizing the traditional central lab versus send-out decision boundary, enabling site-specific testing economics previously unattainable outside high-throughput settings.
EMA IVDR Class C technical documentation requirements and FDA's streamlined dual-claim review pathway are diverging regulatory investment priorities. Manufacturers must regenerate clinical evidence for legacy products in Europe while pursuing synchronized gonorrhea-chlamydia clearances in the United States. Multinational IVD firms are responding by sequencing European launches behind US approvals to manage conformity assessment resource allocation.
Reference laboratory procurement consolidation is compressing vendor qualification timelines and unbundling after-sales service contracts. Large health system networks in the United States are centralizing STI screening contracts under single-source agreements with throughput guarantees. This pattern is most visible among integrated delivery networks in California and Texas, where laboratory directors prioritize platform standardization over best-of-breed assay performance.
Chlamydia Diagnostics Market Segmentation
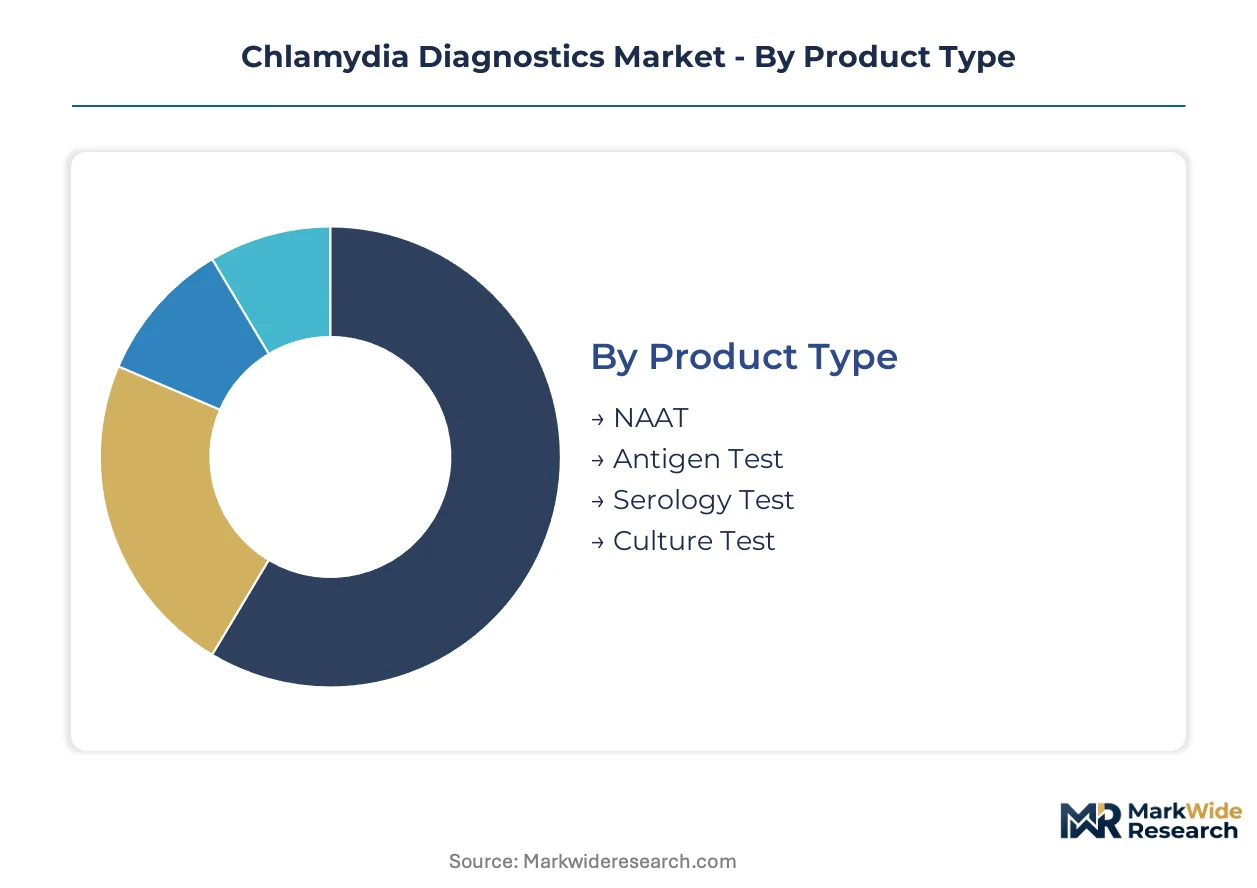
Chlamydia diagnostics segmentation reflects divergent capital requirements across molecular platforms, care settings, and user workflows. Manufacturers configure assay formats and instrument footprints differently for each segment, with reimbursement pathways and regulatory complexity determining viable market entry.
Product Type:
NAAT platforms demand the heaviest upfront investment in thermal cycling infrastructure and polymerase supply chains, while serology and culture methods require lower fixed costs but sacrifice analytical sensitivity.
- NAAT:Nucleic acid amplification technology achieves detection thresholds below 10 copies per reaction through real-time PCR or transcription-mediated amplification. Centralized laboratories in the United States and Germany concentrate procurement of high-throughput systems to meet CLIA and IVDR compliance requirements. The segment absorbs the bulk of installed capacity; Antigen Test is expanding most quickly.
- Antigen Test:Lateral flow immunoassays detect chlamydial lipopolysaccharide antigens in endocervical and urethral specimens without instrumentation. Retail clinic chains favor these for rapid screening in point-of-care settings where result turnaround under 15 minutes outweighs sensitivity trade-offs.
- Serology Test:Antibody detection methods identify past exposure through IgG and IgA seroconversion patterns. Public health surveillance programs utilize these for epidemiological mapping rather than acute case management.
- Culture Test:Cell-based isolation in McCoy or HeLa monolayers retains legal admissibility for forensic sexual assault cases despite 3-7 day turnaround and biosafety containment requirements.
NAAT absorbs the bulk of installed capacity; Antigen Test is expanding most quickly.
Delivery Mode:
Volume concentration varies sharply by setting, with hospital networks driving batch processing economics and decentralized sites demanding single-test flexibility.
- Laboratory-Based:Reference laboratories and hospital core facilities process batched specimens on automated extraction platforms with throughput exceeding 1,000 tests daily. Integrated delivery networks in Texas and California negotiate bundled STI panel contracts that lock in multi-year volume commitments.
- Point-of-Care:CLIA-waived cartridge systems compress result delivery to under 30 minutes in physician offices and urgent care settings. FDA clearance pathways for waived complexity status determine geographic rollout sequencing for manufacturers.
- Home Testing:Self-collection kits with mail-back logistics bypass traditional laboratory networks. Telehealth platforms in the United States partner with courier services to create direct-to-consumer channels outside insurance reimbursement structures.
- Telehealth:Remote consultation workflows integrate symptom assessment with prescription fulfillment for positive cases. This mode climbs fastest as asynchronous provider platforms expand STI screening menus.
Laboratory-Based commands the deepest margin pools; Telehealth climbs fastest.
End User:
Procurement sophistication separates institutional buyers with dedicated laboratory directors from individual consumers prioritizing privacy over clinical integration.
- Diagnostic Laboratories:Commercial reference labs and hospital-affiliated facilities drive standardization through platform consolidation. Large networks extract volume discounts and unbundle service contracts from instrument vendors.
- Hospitals:Inpatient and emergency departments require STAT turnaround for symptomatic patients. Mid-volume facilities increasingly adopt cartridge-based systems to retain testing in-house rather than outsourcing.
- Clinics:Federally qualified health centers and family planning clinics serve high-prevalence populations with constrained budgets. Reimbursement rate disparities between Medicaid and commercial payers shape test menu selection.
- Home Users:Privacy-sensitive individuals and asymptomatic screening populations bypass clinical encounters entirely. Direct-to-consumer marketing restrictions vary by state pharmacy board regulations.
Diagnostic Laboratories anchor procurement volume; Home Users gain share fastest.
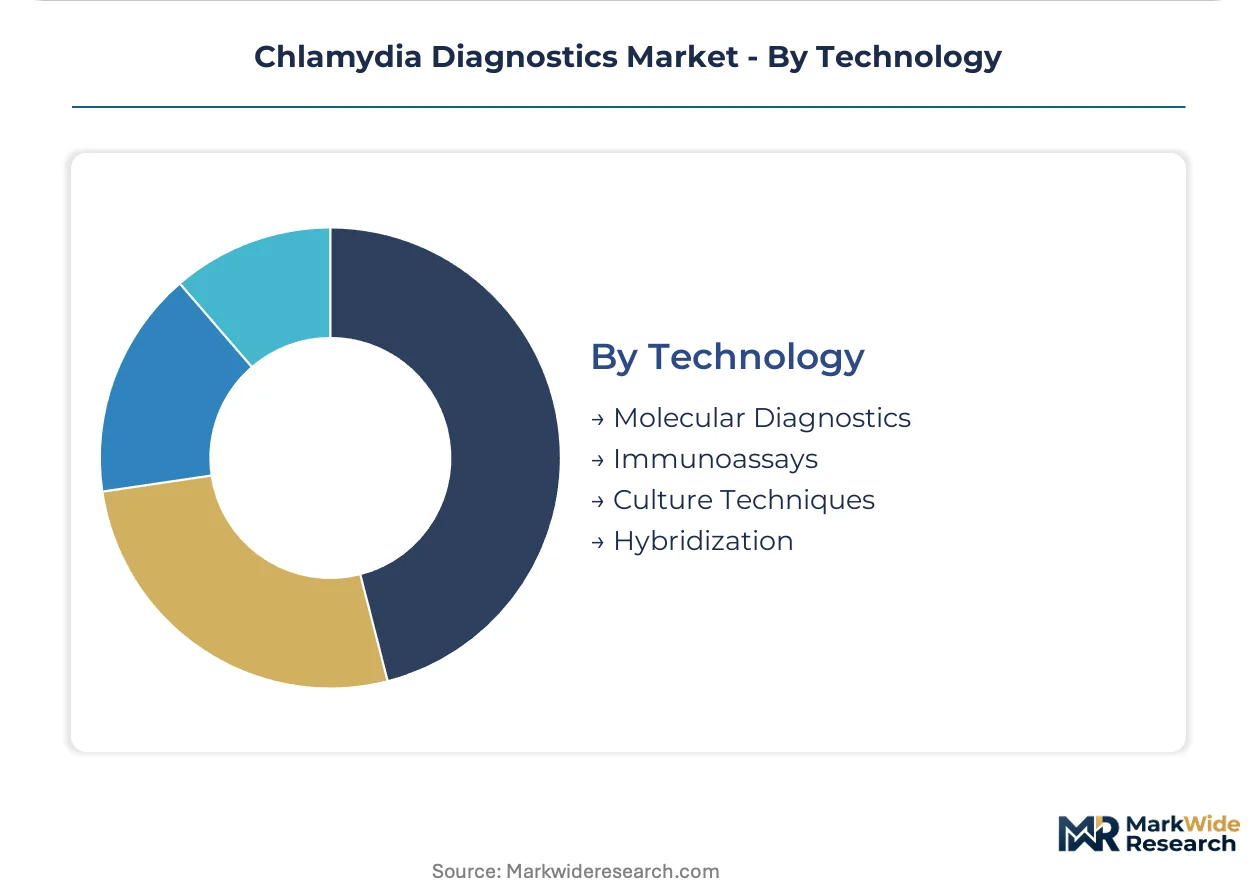
Technology:
Patent estates and reagent supply concentration create divergent margin structures across detection methodologies.
- Molecular Diagnostics:Real-time PCR and isothermal amplification methods dominate revenue through superior analytical performance. Thermostable polymerase supply concentrates among specialized enzyme manufacturers, creating input cost volatility.
- Immunoassays:Enzyme-linked and lateral flow formats serve resource-limited settings without cold chain requirements. Antibody cross-reactivity with other Chlamydia species limits specificity in low-prevalence populations.
- Culture Techniques:Shell vial and cell culture methods retain utility for antimicrobial susceptibility testing and legal evidence standards. Biosafety level 2 containment requirements restrict deployment to specialized facilities.
- Hybridization:DNA probe technologies detect ribosomal RNA targets without amplification, reducing contamination risk. Sensitivity limitations have displaced these from first-line screening protocols.
Molecular Diagnostics captures the largest revenue share; Immunoassays expand most rapidly in point-of-care applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermostable DNA polymerase production concentrates in specialized enzyme suppliers across the United States, Germany, and Japan, anchoring molecular diagnostics manufacturing clusters that feed NAAT platform assembly lines in these markets.
United States
CLIA-waived point-of-care regulations are redistributing testing volume from centralized laboratories toward physician offices and retail clinics. FDA 510(k) clearance pathways shape product development timelines for chlamydia assays. Texas and California integrated delivery networks negotiate bundled STI panel contracts with throughput guarantees.
Germany
Mid-volume hospital networks adopt cartridge-based sample-to-answer systems to retain STI testing in-house rather than outsourcing to reference laboratories. EMA IVDR Class C technical documentation requirements force manufacturers to regenerate clinical evidence for legacy molecular diagnostic products. Bavaria's diagnostic manufacturing corridor hosts automated nucleic acid extraction line expansions.
Japan
METI infectious disease screening mandates expand insured reimbursement coverage for routine chlamydia testing in specific demographic cohorts. PMDA regulatory frameworks align with international standards while maintaining distinct clinical evidence requirements. The Kanto region's hospital networks drive procurement of high-throughput molecular platforms.
India
CDSCO diagnostic registration reforms streamline import licensing and create local manufacturing incentives for multinational IVD manufacturers. BIS quality certification requirements apply to domestically produced assay kits. Maharashtra's pharmaceutical manufacturing zones attract contract diagnostic manufacturers seeking cost-competitive production bases.
United Kingdom
NHS England procurement frameworks consolidate STI screening contracts under standardized molecular platform agreements. MHRA post-Brexit regulatory autonomy maintains alignment with IVDR standards while streamlining UK-specific clearance pathways. London's reference laboratory networks drive demand for multiplex panel compatibility in high-throughput settings.
Chlamydia Diagnostics Market Vendor Landscape
Global majors compete with regional champions across regulatory compliance capabilities and installed platform bases. The market structure concentrates around multinational conglomerates with diversified IVD portfolios and specialized molecular diagnostics pure-plays. Three archetypes dominate: integrated life science conglomerates with broad assay menus, molecular diagnostics specialists with platform-specific expertise, and point-of-care rapid test manufacturers with CLIA-waived product lines. Competitive moves center on strategic partnerships for polymerase supply security and geographic licensing arrangements to bypass IVDR certification bottlenecks.
Among the integrated conglomerates, Roche Diagnostics and Abbott Laboratories occupy positions defined by extensive installed bases of automated platforms. Hologic Inc. exemplifies the molecular diagnostics specialist archetype with system throughput optimization for high-volume reference laboratories. These three companies anchor the competitive structure through differentiated platform strategies rather than direct product substitution.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Hologic Inc. |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| Becton Dickinson and Company |
| Siemens Healthineers |
| bioMérieux SA |
| QuidelOrtho Corporation |
| Others |
Supply Flow & Price Mechanics
EMA IVDR clinical evidence mandates gate both qualified polymerase supply and premium-tier assay pricing access, forcing manufacturers to absorb conformity assessment costs or surrender high-margin European contracts to competitors with pre-validated technical documentation packages. This regulatory filter concentrates pricing power among incumbents with established Notified Body relationships while squeezing mid-tier players into commoditized antigen test segments.
Pricing Analysis
Warranty and service contract unbundling separates instrument procurement from reagent supply agreements, with reference laboratories in Texas and California negotiating multi-year throughput guarantees that lock in below-market per-test rates. Three-tier pricing structure across premium, standard, and economy levels stratifies by CLIA complexity status and multiplex panel capability, with FDA-cleared NAAT systems commanding brand premiums over CE-marked equivalents. Pricing pressure stems from Medicare bundled reimbursement compression, which limits standalone chlamydia assay margin expansion. Federally qualified health centers exhibit highest price sensitivity due to Medicaid rate disparities, while integrated delivery networks prioritize platform standardization over unit cost.
Supply Chain Analysis
Reverse logistics for cartridge-based systems encompasses instrument refurbishment, failed test recovery protocols, and expired reagent return flows from CLIA-waived sites lacking cold chain infrastructure. Thermostable DNA polymerase production concentrates in the United States, Germany, and Japan, with enzyme supply anchored to three specialized manufacturers whose qualification timelines create input bottlenecks. Chlamydia diagnostics draws from semiconductor-based thermal cycling components, microfluidic cartridge substrates, and nucleic acid extraction chemistry. Single-source vulnerability in polymerase supply exposes manufacturers to cost volatility when enzyme batches fail release specifications. Distribution runs through diagnostic distributors and direct hospital system contracts, with GPO aggregation consolidating procurement volume among the largest reference laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NAAT platform miniaturization is displacing legacy culture and serology methods across mid-volume hospital settings, compressing the addressable market for non-molecular detection technologies and redistributing competitive advantage toward cartridge-based sample-to-answer specialists.
For Market Incumbents: Deepen backward integration into thermostable polymerase supply through captive enzyme manufacturing or exclusive supply partnerships, insulating against qualification bottlenecks that delay assay launches. Fortify CLIA-waived instrument footprints in retail clinic chains before emerging CRISPR-based competitors achieve comparable sensitivity thresholds, as guide RNA-programmable detection threatens to bypass thermal cycling infrastructure entirely. For New Entrants and Emerging Players: Enter via India's CDSCO streamlined registration pathway, where local manufacturing incentives and import licensing reforms lower capital barriers for multinational assay kit producers. Target telehealth-integrated home collection segments in the United States, where direct-to-consumer channels bypass traditional laboratory network gatekeepers and insurance reimbursement complexity. Pursue courier logistics partnerships as the primary go-to-market mechanism, leveraging asynchronous provider platforms for specimen routing and prescription fulfillment. For Investors and Strategic Acquirers: EMA IVDR Class C certification backlogs clearing for established assay portfolios is the leading indicator that European market entry costs have peaked and consolidation returns will improve. Position for five-to-ten year holding periods centered on molecular diagnostics pure-plays with Panther or cobas platform integration depth, as reference laboratory procurement consolidation favors throughput-optimized system vendors over point-of-care generalists. Monitor PMDA alignment with international clinical evidence standards as the signal for Japanese reimbursement expansion accelerating institutional procurement volumes.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Instrument Miniaturization | Shrinks thermal cycling footprints to under-benchtop dimensions for physician office deployment. |
| Multiplex STI Panel FDA Clearance | Enables bundled gonorrhea-chlamydia-trichomoniasis reimbursement under single CPT codes. |
| Polymerase Supply Security Partnership | Locks in thermostable enzyme allocation through multi-year offtake with specialized manufacturers. |
| Telehealth Logistics Integration | Connects self-collection kit dispatch to courier networks and asynchronous prescription platforms. |
| IVDR Technical Documentation Regeneration | Preserves European market access for legacy NAAT products under Class C conformity pathways. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning laboratory directors, GPO contracts managers, biomedical engineers, and diagnostic distributor executives. FDA 510(k) clearance databases, EMA IVDR submission logs, CMS Medicare reimbursement schedules, and hospital procurement databases supplied validation benchmarks. Bottom-up assay kit volume estimates triangulated against top-down molecular diagnostics platform shipment data.
Data-stream reconciliation across product type, delivery mode, end user, and technology segmentation dimensions stabilized volume and value outputs across the projection horizon. CAGRs derived from installed base expansion rates, test volume per capita trends, and reimbursement pathway evolution. Modeled inputs incorporated CLIA complexity categorization shifts, polymerase supply qualification timelines, and telehealth platform integration velocity without year-specific anchoring.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IVDR Notified Body capacity constraints or polymerase batch failure events. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and reimbursement rate stability. Practitioners should monitor EMA IVDR certification queue lengths and thermostable enzyme spot pricing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Veterinary Diagnostics Market
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Preeclampsia Diagnostics Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Elisa Tests Market
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Europe Lung Cancer Diagnostics Market
Diagnostics
In Vitro Diagnostic (IVD) Reagent Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Netherlands in-Vitro Diagnostics Market
Diagnostics
Europe Antinuclear Antibody Test Market
Diagnostics
Urinary Protein Reagents Market