
 EMEA Meningitis Diagnostic Testing Market | 2026-2036
EMEA Meningitis Diagnostic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Meningitis Diagnostic Testing Market Foresight
The EU In Vitro Diagnostic Regulation is rebalancing the cost-of-entry calculus for manufacturers serving European infectious disease diagnostics. Siemens Healthineers leverages its installed base of molecular platforms to sustain service revenue across German and French hospital networks. bioMérieux anchors its competitive position through specialized blood culture and syndromic panel workflows that dominate reference laboratory procurement in Southern Europe. Abbott competes on point-of-care portability, extending its meningitis antigen detection footprint into African clinic settings where cold-chain logistics challenge centralized lab models.
Meningitis diagnostic testing encompasses laboratory and near-patient methods for detecting bacterial, viral, or fungal pathogens in cerebrospinal fluid, blood, or nasopharyngeal specimens through nucleic acid amplification, immunoassay, or culture-based techniques with turnaround times ranging from fifteen minutes to seventy-two hours. Its primary purpose is enabling rapid therapeutic intervention and public health reporting for a condition with mortality exceeding ten percent when treatment is delayed. PCR-based product types command the largest revenue share due to superior sensitivity for partially treated infections, while LAMP technology within the technology dimension represents the fastest-expanding segment as African ministries of health deploy field-stabilized assays without thermal cycler dependency. The end-user dimension shows diagnostic labs capturing the deepest margin pools through high-throughput batch processing of CSF panels, whereas hospital-based testing gravitates toward integrated STAT workflows.
The European Medicines Agency coordinates pharmacovigilance expectations for companion diagnostic claims, while ECHA oversees reagent substance registrations under REACH that constrain polymerase supply chains, and the EU AI Act introduces conformity obligations for algorithmic interpretation of syndromic panel results. These frameworks collectively elevate documentation burdens but also accelerate substitution of legacy culture methods with standardized molecular protocols. Stakeholders must monitor how African national regulators align with European CE-IVDR mutual recognition to anticipate harmonized tender specifications across Mediterranean and Sub-Saharan procurement corridors.
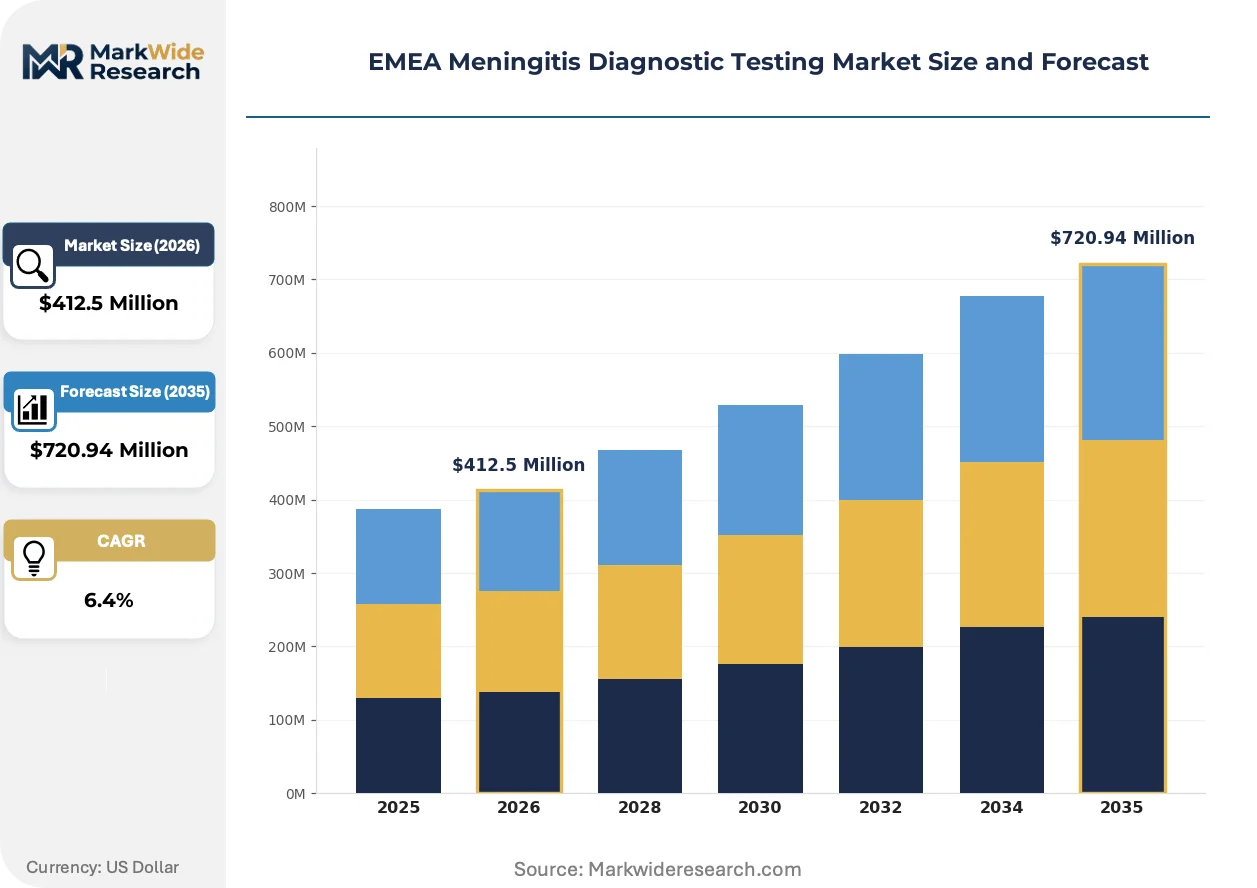
Market Dynamics
The EU In Vitro Diagnostic Regulation is recalibrating conformity assessment pathways for infectious disease assays, compressing legacy culture method margins while elevating molecular platform economics across hospital laboratory networks.
Growth Catalysts
- IVDR Compliance Deadlines:The EU In Vitro Diagnostic Regulation mandates technical documentation upgrades that favor manufacturers with established quality management systems, accelerating consolidation toward CE-IVDR-certified molecular workflows.
- Centralized Laboratory Procurement:Health systems in Germany, France, and the United Kingdom are consolidating purchasing around high-throughput reference laboratories capable of syndromic panel batch processing.
- LAMP Field Deployment:Loop-mediated isothermal amplification technology enables African ministries of health to deploy meningitis diagnostics without thermal cycler infrastructure, bypassing cold-chain constraints in clinic settings.
Market Restraints
- Polymerase Supply Concentration:ECHA oversight of reagent substance registrations under REACH constrains polymerase supply chains, creating input bottlenecks for nucleic acid amplification test manufacturers.
- Notified Body Capacity:Limited EU-designated notified bodies for IVDR conformity assessment extends certification timelines, delaying market entry for new assay submissions.
- Culture Method Persistence:Antimicrobial resistance surveillance networks in Southern Europe still mandate culture-based confirmation, forcing dual-method infrastructure investment.
Strategic Opportunities
- Sub-Saharan Africa Expansion:African national regulators aligning with European CE-IVDR mutual recognition create harmonized tender specifications across Mediterranean and Sub-Saharan procurement corridors.
- Algorithmic Interpretation:The EU AI Act introduces conformity obligations for syndromic panel result interpretation, opening competitive space for validated diagnostic software modules.
- Point-of-Care Channel Development:Portable antigen detection platforms address clinic settings where centralized laboratory infrastructure remains underdeveloped, particularly in East African health districts.
Industry Challenges
- Bioinformatics Talent Scarcity:Syndromic panel deployment requires computational pathology expertise that outpaces European laboratory medicine training pipelines.
- Legacy LIS Integration:Hospital information system interoperability gaps complicate STAT workflow automation for integrated molecular diagnostics.
- Pharmacovigilance Documentation:EMA coordination of companion diagnostic claims elevates post-market surveillance reporting burdens for multiplex assay manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Meningitis Diagnostic Testing Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR, Serology, Culture, Antigen Detection Technology: RT-PCR, NGS, LAMP, ELISA Application: Clinical, Research, Surveillance, Screening End User: Hospitals, Diagnostic Labs, Research Institutes, Clinics |
| Companies Covered | Siemens Healthineers, Bio-Rad Laboratories, bioMérieux, ELITechGroup, Danaher, Abbott, Becton, Dickinson and Company, BioFire Diagnostics, Thermo Fisher Scientific, Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Meningitis Diagnostic Testing Market Shifts & Advancements
Molecular diagnostic platforms are displacing legacy culture methods through sensitivity advantages in partially treated infections, while regulatory frameworks and procurement models reshape competitive positioning across the EMEA corridor.
Multiplex syndromic panels is converging with cloud-based epidemiological surveillance networks, enabling real-time pathogen tracking across hospital networks. French and German reference laboratories are adopting these integrated workflows at accelerated pace. This convergence is compressing the interval between diagnostic result and public health reporting from days to hours.
REACH substance registration requirements for polymerase reagents are forcing manufacturers to requalify supply chains under ECHA oversight. Industrial consequence includes accelerated substitution of European-sourced enzymes with validated alternatives from compliant jurisdictions. Southern European diagnostic labs face the steepest reformulation burdens due to smaller batch purchasing power.
Service unbundling is separating instrument placement from reagent supply contracts, disrupting traditional captive consumable models. Hospital procurement departments in the United Kingdom are negotiating reagent-only tenders for existing molecular platforms. This behavioral shift is most visible in National Health Service consolidation zones where reference laboratory networks command volume leverage.
EMEA Meningitis Diagnostic Testing Market Segmentation
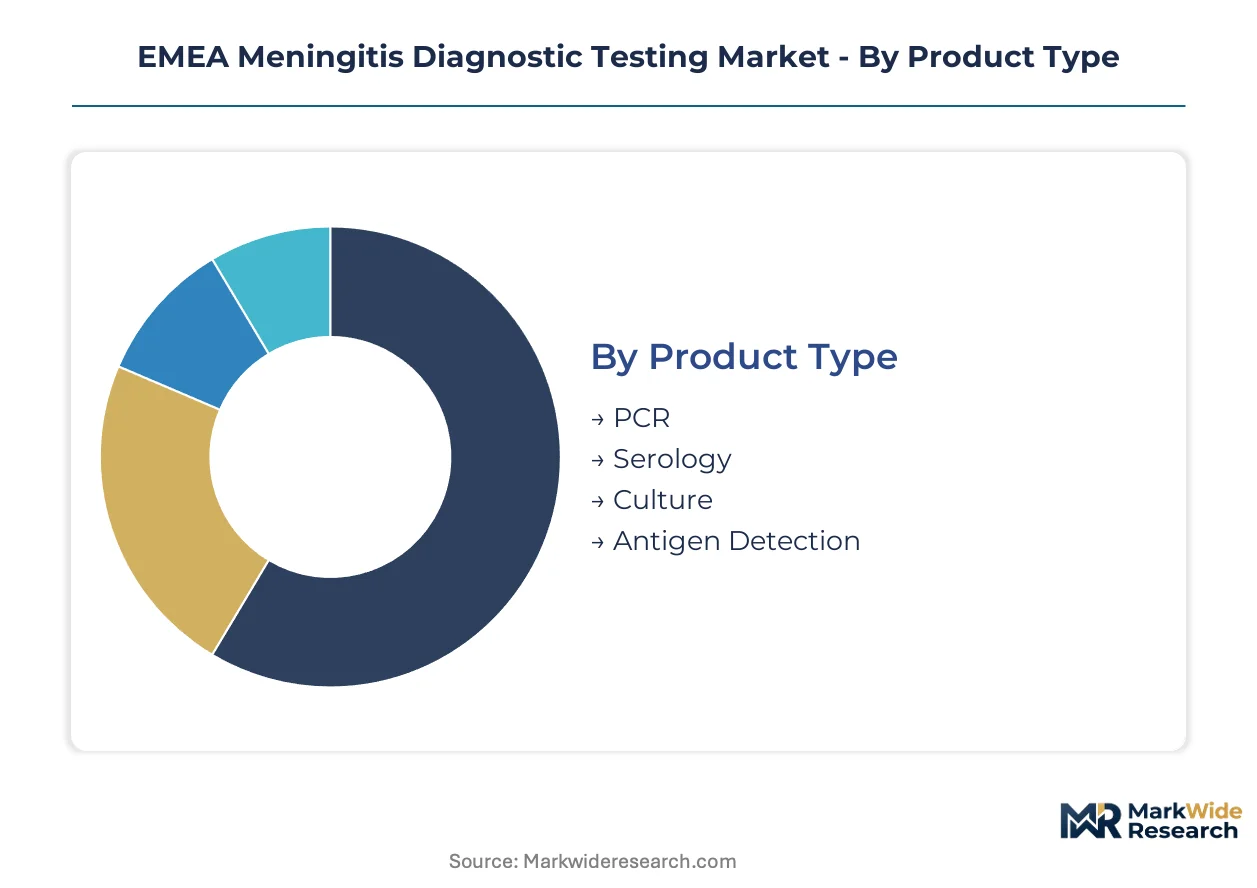
EMEA meningitis diagnostic testing segments reflect divergent infrastructure capabilities across European hospital networks and African field deployment constraints. Procurement patterns split between centralized reference laboratories demanding high-throughput batch processing and clinic settings requiring cold-chain-independent portability.
Product Type:
Hospital laboratories differentiate purchasing by sensitivity requirements for partially treated infections versus cost constraints for screening programs.
- PCR:Nucleic acid amplification platforms detect bacterial and viral pathogens in cerebrospinal fluid with superior sensitivity for antibiotic-pretreated specimens. German and French reference laboratories concentrate procurement here, driven by IVDR-mandated documentation upgrades that favor established molecular workflows.
- Serology:Antibody-based detection methods identify prior exposure and immune response patterns through serum or plasma analysis. Southern European surveillance networks maintain demand for serological confirmation, constrained by antimicrobial resistance monitoring protocols that still mandate complementary testing.
- Culture:Traditional growth-based identification remains necessary for resistance profiling and public health strain archiving.
- Antigen Detection:Rapid immunoassay formats enable point-of-care deployment without laboratory infrastructure.
Volume sits with PCR platforms; growth tilts toward antigen detection formats for decentralized African clinic networks.
Technology:
Platform selection tracks thermal infrastructure availability and turnaround time requirements across end-user settings.
- RT-PCR:Reverse transcription polymerase chain reaction amplifies RNA targets from viral meningitis pathogens with established regulatory pathways under CE-IVDR. United Kingdom hospital networks anchor demand through consolidated National Health Service procurement of syndromic panel workflows.
- LAMP:Loop-mediated isothermal amplification operates without thermal cycler dependency, enabling field-stabilized deployment. East African health ministries drive adoption fastest, bypassing cold-chain logistics that constrain centralized laboratory models in rural districts.
- NGS:Next-generation sequencing supports outbreak investigation and novel pathogen discovery through comprehensive genomic characterization.
- ELISA:Enzyme-linked immunosorbent assay formats provide standardized batch processing for serological screening programs.
Installed base concentrates in RT-PCR; expansion accelerates most steeply for LAMP technology across Sub-Saharan procurement corridors.
Application:
Use case segmentation separates acute therapeutic decision-making from population-level pathogen monitoring.
- Clinical:Diagnostic testing for individual patient management requires rapid turnaround from cerebrospinal fluid or blood specimens. Hospital emergency departments and intensive care units in Germany, France, and the United Kingdom represent the primary demand concentration, shaped by mortality exceeding ten percent when treatment initiation delays.
- Surveillance:Systematic pathogen tracking supports public health response and outbreak containment through mandatory reporting networks. French and German reference laboratories are integrating cloud-based epidemiological platforms, compressing reporting intervals from days to hours.
- Research:Academic and pharmaceutical investigation of novel biomarkers and therapeutic targets.
- Screening:Population-level asymptomatic detection in high-risk settings such as military recruit camps or dormitory outbreaks.
Revenue pools deepest in clinical applications; surveillance represents the steepest expansion trajectory through real-time network integration.
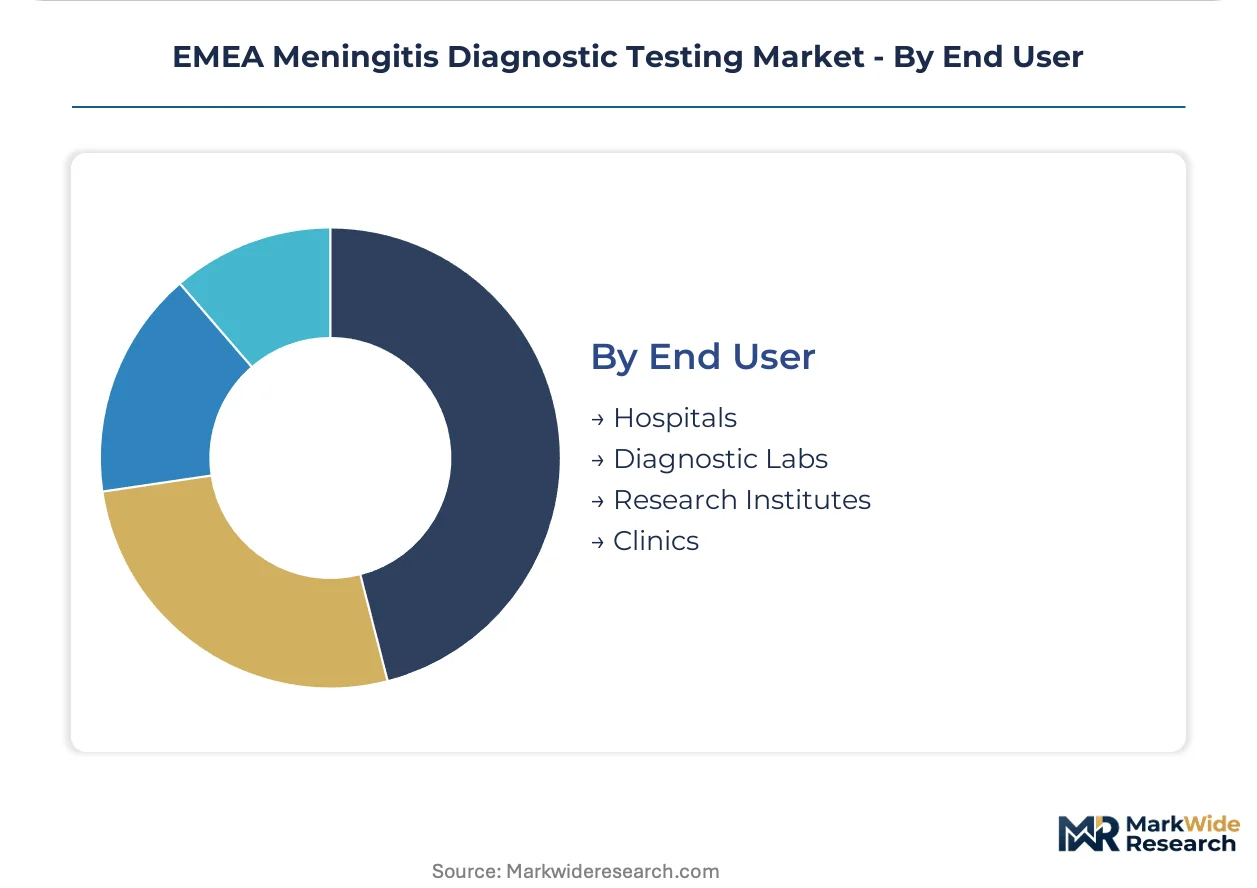
End User:
Facility type determines workflow integration requirements and capital equipment investment capacity.
- Diagnostic Labs:Centralized reference laboratories process high-volume CSF panels with batch efficiency and specialized personnel. Procurement consolidation across German, French, and United Kingdom health systems concentrates purchasing power here, favoring manufacturers with CE-IVDR-certified syndromic menu breadth.
- Clinics:Peripheral healthcare facilities in African districts require portable platforms operable without continuous power or refrigeration. Abbott and similar manufacturers compete on point-of-care antigen detection footprint, addressing settings where laboratory infrastructure remains underdeveloped.
- Hospitals:Acute care facilities demand STAT-integrated workflows for emergency department throughput.
- Research Institutes:Academic and government laboratories pursue method development and validation studies.
Margin capture favors diagnostic laboratories; clinic channel development offers the fastest volume expansion across Mediterranean and Sub-Saharan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health technology parks in Leuven, Belgium, and the Cambridge-MedTech corridor concentrate diagnostic platform development, drawing polymerase supply chains and notified body proximity into specialized zones that reshape procurement economics across European hospital networks.
Germany
Reference laboratory consolidation in North Rhine-Westphalia and Bavaria drives demand for high-throughput PCR batch processing. The national pharmaceutical regulator coordinates pharmacovigilance expectations with EMA guidelines, tightening post-market surveillance for multiplex assay manufacturers. Berlin-Brandenburg health networks are integrating cloud-based epidemiological platforms, compressing pathogen reporting intervals from days to hours.
France
Surveillance mandates from antimicrobial resistance monitoring networks sustain dual-method infrastructure investment alongside molecular adoption. ANSM oversees companion diagnostic claims alignment with EMA frameworks, elevating documentation burdens for syndromic panel developers. The Île-de-France cluster around Paris anchors centralized procurement for hospital laboratory networks, favoring CE-IVDR-certified workflow breadth.
United Kingdom
National Health Service consolidation zones in London and the Midlands negotiate reagent-only tenders for existing molecular platforms, separating instrument placement from consumable supply. MHRA implements IVDR-equivalent conformity pathways post-Brexit, maintaining technical documentation standards that favor established quality management systems. Greater Manchester reference laboratories are adopting integrated STAT workflows for emergency department throughput.
Nigeria
Ministry of health procurement corridors prioritize cold-chain-independent LAMP deployment for district clinic networks. The national pharmaceutical regulator aligns with CE-IVDR mutual recognition frameworks to harmonize tender specifications across West African procurement zones. Lagos and Abuja health districts are field-stabilizing isothermal amplification assays without thermal cycler infrastructure.
South Africa
Academic hospital networks in Gauteng and Western Cape maintain research-grade NGS capacity for outbreak investigation and novel pathogen discovery. SAHPRA oversees IVD registration pathways that reference European technical documentation standards, streamlining market entry for CE-IVDR-certified manufacturers. The Cape Town biomedical cluster anchors genomic surveillance integration with national public health reporting systems.
EMEA Meningitis Diagnostic Testing Market Competitive Landscape
European producers anchor one tier through installed base leverage and regulatory certification depth; North American specialists hold position through platform portability and point-of-care channel development. Market structure tilts toward consolidation around manufacturers with established IVDR quality systems, compressing margins for legacy culture method providers. Three archetypes dominate: integrated diagnostic conglomerates with service revenue models, specialized molecular workflow developers, and portable assay specialists targeting decentralized settings. Competitive moves concentrate on reagent unbundling from instrument contracts and African regulatory alignment for tender harmonization.
Among the integrated diagnostic conglomerates, Siemens Healthineers and Danaher exemplify archetypes leveraging installed base scale for sustained service revenue across hospital networks. bioMérieux occupies a position within the specialized molecular workflow tier, anchoring competitive standing through reference laboratory relationships. Abbott represents the portable assay specialist archetype, with its geographic name signaling North American origin and its corporate structure reflecting publicly traded scale. These three companies illustrate how regulatory certification depth, workflow integration, and field-deployment portability segment competitive positioning across the EMEA corridor.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Bio-Rad Laboratories |
| bioMérieux |
| ELITechGroup |
| Danaher |
| Abbott |
| Becton, Dickinson and Company |
| BioFire Diagnostics |
| Thermo Fisher Scientific |
| Others |
Supply & Pricing Matrix
Centralized laboratory procurement consolidation across German, French, and United Kingdom health systems is compressing reagent pricing power and forcing manufacturers toward unbundled service contracts that separate instrument placement from consumable supply.
Pricing Analysis
Short lead-time premiums for CE-IVDR-certified syndromic panels command pricing separation from spot inventory of legacy culture media. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and thermal infrastructure requirements. Cost compression in economy-tier antigen detection formats is intensifying because African ministries of health prioritize cold-chain-independent portability over sensitivity specifications. Clinic networks in East African districts exhibit the highest price sensitivity, while reference laboratories in Germany and France prioritize workflow integration over unit cost.
Supply Chain Analysis
Reverse-logistics flows for thermal cycler refurbishment and polymerase reagent returns concentrate service revenue recovery in Germany, the United States, and Japan. Polymerase enzyme supply draws from REACH-registered substance manufacturers under ECHA oversight, with nucleic acid amplification test production anchored in European and North American certified facilities. Single-source vulnerability in notified body capacity for IVDR conformity assessment extends certification timelines and constrains new assay market entry. Distribution runs through hospital procurement consortiums in consolidated European health systems and ministry of health tender corridors in Sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molecular diagnostic platforms are displacing legacy culture methods across EMEA hospital networks, creating asymmetric reward structures for manufacturers with established CE-IVDR quality systems and syndromic panel breadth.
For Market Incumbents: Cement installed base leverage through reagent-only contract extensions that lock United Kingdom National Health Service consolidation zones into consumable dependencies. Prioritize backward integration into polymerase supply chains to mitigate ECHA REACH registration bottlenecks. Defend against portable assay specialists by embedding STAT workflow automation in German and French emergency department networks.
For New Entrants and Emerging Players: The price-point gap between premium PCR batch-processing systems and economy-tier African clinic deployments creates white-space entry at mid-tier LAMP field platforms. Target East African health districts where thermal cycler infrastructure remains undeveloped and ministry procurement favors cold-chain independence. Pursue CE-IVDR mutual recognition alignment with Nigerian and South African regulators to unlock harmonized tender access across Mediterranean and Sub-Saharan corridors.
For Investors and Strategic Acquirers: The window for entry favors specialized molecular workflow developers with reference laboratory relationships and algorithmic interpretation software modules. Long-term viability hinges on regulatory certification depth rather than point-of-care portability alone. Watch for IVDR notified body capacity expansion as the signal indicating accelerated new assay approval timelines and reduced certification backlog risk.
| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Pathway | EMA-coordinated pharmacovigilance documentation accelerates multiplex assay market access across European hospital networks. |
| Hospital System Partnership | Integrated STAT workflow agreements with German reference laboratories lock in high-throughput batch processing volume. |
| Software Companion Development | EU AI Act-compliant algorithmic interpretation modules open competitive differentiation for syndromic panel result reporting. |
| Geographic Expansion | CE-IVDR mutual recognition alignment with African national regulators harmonizes tender specifications across procurement corridors. |
| Reimbursement Strategy | Public health surveillance network integration in France and Germany compresses reporting intervals and secures mandated testing volume. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced with primary interviews across laboratory directors, hospital procurement managers, biomedical engineers, and ministry of health officials. Bottom-up triangulation combined instrument shipment tracking, reagent import documentation, and reference laboratory capital expenditure disclosures with top-down validation against EMA pharmacovigilance reports and notified body certification databases.
Data-stream reconciliation across product type, technology platform, application use case, and end-user facility tier generated volume and value outputs throughout the forecast period. CAGRs were derived from segmented growth trajectory modeling that weighted IVDR compliance deadlines, LAMP field deployment acceleration, and procurement consolidation patterns. Industry-specific inputs included polymerase supply chain registration status under ECHA REACH and cloud-based epidemiological surveillance network adoption rates in French and German health systems.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in real-time African clinic deployment metrics introduce uncertainty bands around LAMP adoption trajectories. Forecasts reflect assumptions regarding notified body capacity expansion and CE-IVDR mutual recognition alignment timelines. Material deviation in IVDR certification backlog resolution or polymerase supply chain requalification under REACH warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Viral Antigens Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Creatinine Test Market
Diagnostics
China in Vitro Diagnostics Market
Diagnostics
Liver Function Tests Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
India Molecular Diagnostic Controls Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Europe Antinuclear Antibody Test Market
Diagnostics
Global Urinalysis Market
Diagnostics
North America Syndromic Multiplex Diagnostic Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
Fertility Testing Devices Market