
 Concrete Sealer Market | 2026-2036
Concrete Sealer Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Sealer Market Analysis
Aftermarket service revenue from reapplication and maintenance programs is fragmenting across regional applicator networks as original sealer warranties expire. PPG Industries leverages its architectural coatings distribution infrastructure to capture recurring specification cycles. Sika AG anchors its position through integrated waterproofing-to-sealer system bundling for infrastructure projects. BASF SE competes on silane-siloxane chemistry depth, sustaining technical credibility with engineering firms.
Concrete sealer denotes a protective treatment applied to cured concrete substrates to reduce permeability, resist chloride ingress, and prevent surface degradation from moisture, chemicals, or freeze-thaw cycling; formulations typically achieve 2–10 mils dry-film thickness with active solids content ranging from 5% to 40% depending on carrier chemistry and penetration depth requirements. Penetrating sealers command premium positioning in infrastructure and marine exposure zones where vapor transmission preservation matters. Film-forming acrylic and epoxy categories dominate residential and commercial aesthetic applications where color enhancement and gloss retention drive selection. Water-based technology lines are gaining specification share in California and Northeastern states where VOC thresholds have tightened below 100 g/L.
EPA VOC regulations under 40 CFR Part 59, California Air Resources Board Suggested Control Measures, and ASTM C309 moisture-retention standards collectively constrain solvent-based formulation options while elevating compliance costs for regional manufacturers. OSHA silica exposure rules during surface preparation further shape contractor workflow economics and product selection criteria. Stakeholders must monitor evolving state-level low-VOC adoption timelines and position chemistry portfolios to avoid stranded asset risk in restrictive jurisdictions.
Market Dynamics
EPA VOC regulations under 40 CFR Part 59 are compressing solvent-based formulation margins while accelerating water-based chemistry R&D cycles across domestic manufacturing footprints.
Growth Catalysts
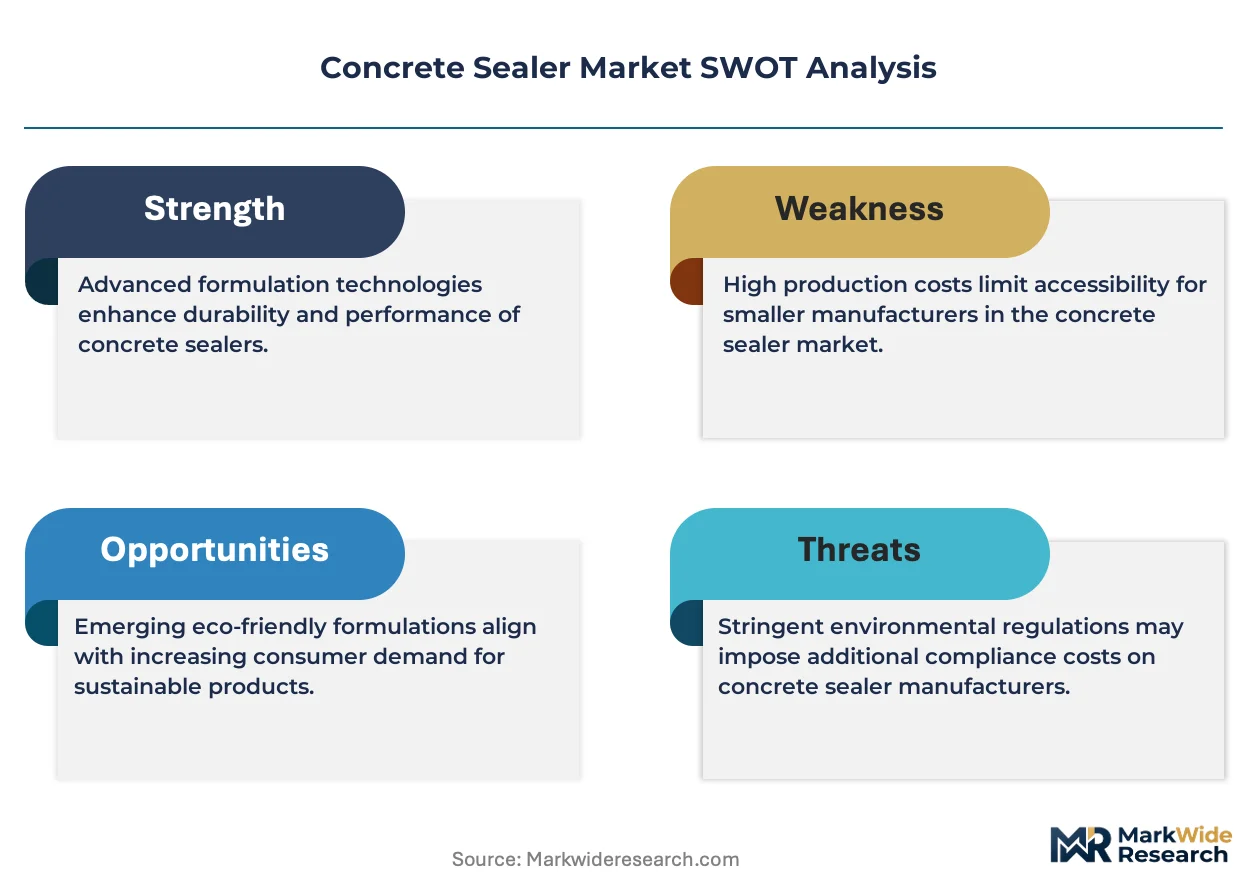
- Infrastructure spending concentration:Texas, California, and Florida account for disproportionate specification volume as DOT agencies prioritize chloride-resistant treatments for bridge decks and coastal structures.
- Silane-siloxane chemistry maturation:Penetrating sealer performance now matches film-forming alternatives on key durability metrics, unlocking specification in marine exposure zones previously reserved for epoxy systems.
- OSHA silica rule compliance:Surface preparation workflow changes are favoring low-dust application methods that pair naturally with water-based sealer technologies, creating bundled specification pull-through.
Market Restraints
- Petrochemical feedstock volatility:Acrylic resin and epoxy precursor costs fluctuate with crude oil indices, compressing formulation margin stability for domestic producers.
- Regional manufacturing concentration:Active solids production clusters in the Gulf Coast expose supply continuity to hurricane-season disruption patterns.
- California CARB SCM thresholds:Sub-100 g/L VOC mandates in the largest state economy strand solvent-based inventory and force parallel SKU maintenance.
Strategic Opportunities
- Reapplication service bundling:Expiring 5-10 year original warranties on infrastructure sealers create recurring revenue capture potential for applicator networks with maintenance program infrastructure.
- Data center construction surge:Hyperscale facility slabs require vapor-suppressing treatments that penetrating silane-siloxane formulations deliver without interfering with flooring adhesion.
- State low-VOC adoption waves:Northeastern states following California's regulatory trajectory will force chemistry transitions that favor early water-based portfolio movers.
Industry Challenges
- Applicator certification fragmentation:Manufacturer-specific training programs lack cross-credential recognition, constraining labor mobility and inflating project mobilization costs.
- ASTM C309 test protocol delays:Moisture-retention standard updates lag behind formulation innovation, creating specification ambiguity for high-performance penetrating products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Sealer Market |
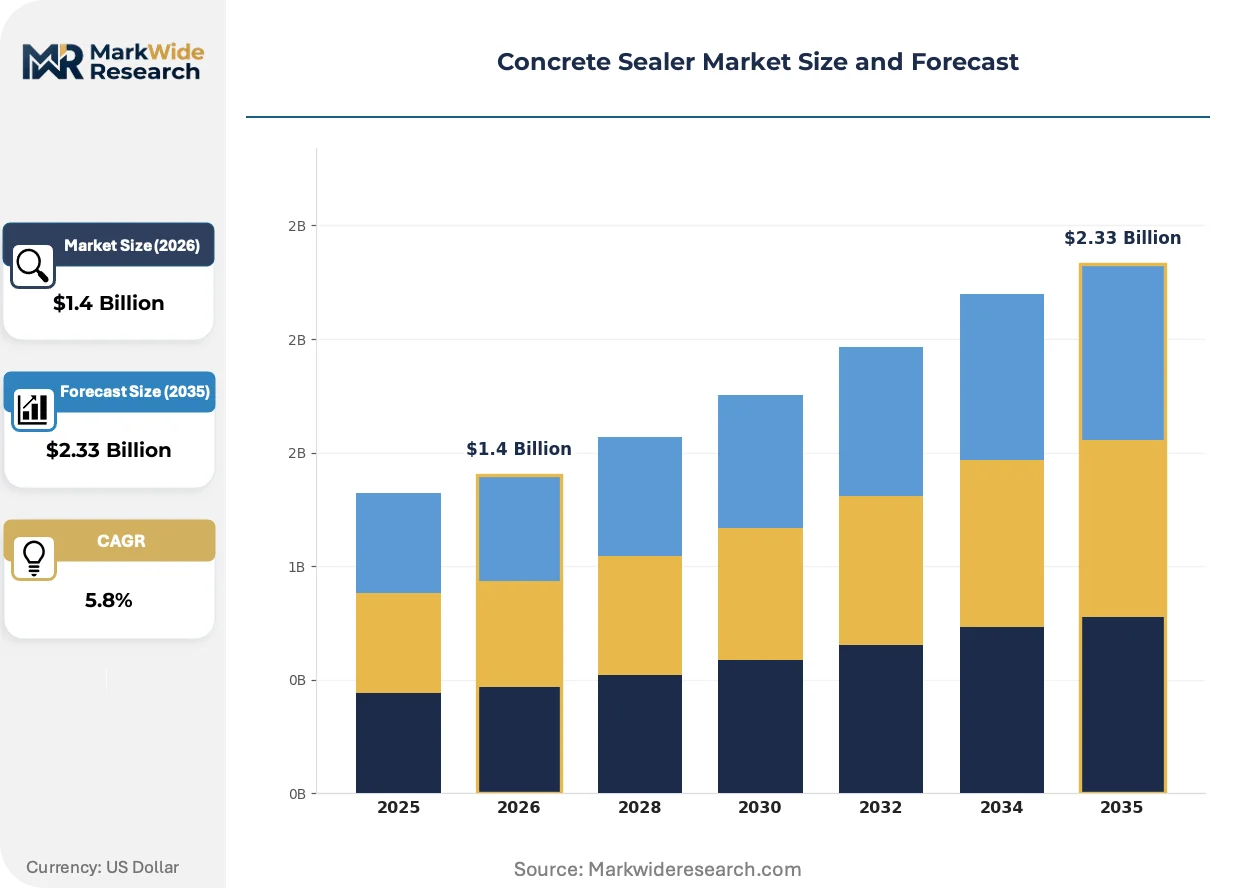
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Penetrating Sealers, Film-Forming Sealers, Epoxy Sealers, Acrylic Sealers Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, DIY Consumers, Government, Architects Technology: Water-Based, Solvent-Based, Polyurethane, Silane-Siloxane |
| Companies Covered | PPG Industries Inc., Mapei S.P.A., BASF SE, Prosoco Inc., Arkema, Sika AG, Evonik Industries AG, Laticrete International Inc., RPM International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Sealer Market Emerging Trajectories
Formulation chemistry is bifurcating into high-performance penetrating systems for infrastructure and aesthetic film-forming lines for commercial architecture, with water-based carriers capturing specification share in regulated jurisdictions.
Silane-siloxane hybrid chemistry is collapsing the performance gap between penetrating and film-forming sealers. State DOT engineers now specify these treatments for bridge decks previously requiring epoxy overlays. The technology is collapsing premium pricing power for traditional epoxy suppliers in infrastructure verticals.
California Air Resources Board Suggested Control Measures are forcing reformulation cycles below 100 g/L VOC thresholds. Solvent-based product lines face stranded asset risk in the largest state economy. Manufacturers with water-based capacity expansions in the Midwest and Southeast are capturing specification share as northeastern states adopt parallel restrictions.
Facility managers are unbundling sealer procurement from original construction contracts. Standalone maintenance specifications now favor applicator networks with digital inspection documentation capabilities. This pattern concentrates in Florida and Gulf Coast markets where salt-air exposure accelerates reapplication cycles.
Concrete Sealer Market Segmentation
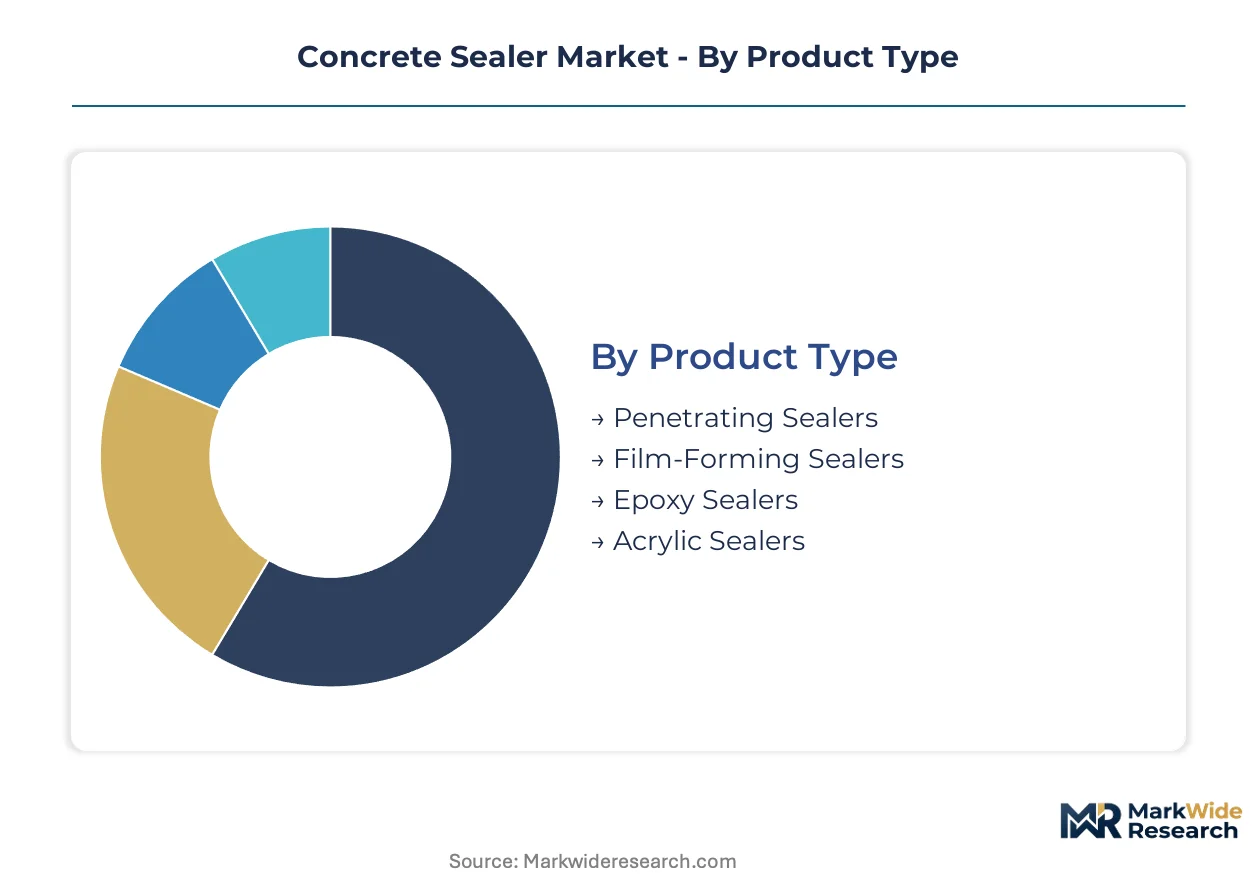
Concrete sealer procurement splits sharply between infrastructure durability specifications and aesthetic commercial requirements. Chemistry selection, carrier technology, and warranty terms vary dramatically across these divides, forcing manufacturers to maintain parallel formulation portfolios.
Product Type:
Formulation chemistry determines penetration depth, vapor transmission rates, and reapplication intervals across exposure conditions.
- Penetrating Sealers:Silane-siloxane active solids penetrate 2–4 millimeters into concrete capillaries, forming hydrophobic barriers without surface film buildup. Texas DOT and Florida DOT specifications for bridge deck chloride protection now favor these treatments over epoxy overlays, collapsing the traditional performance-premium gap.
- Film-Forming Sealers:Acrylic and epoxy surface films deliver 2–10 mils dry thickness with color enhancement and gloss retention. Commercial architecture in California and Florida drives specification where aesthetic finish trumps vapor transmission preservation.
- Epoxy Sealers:Two-part thermoset systems provide maximum chemical resistance for industrial containment slabs and manufacturing floors.
- Acrylic Sealers:Single-component emulsions dominate residential driveway and patio applications where cost sensitivity limits chemistry investment.
Penetrating formulations command the established base in infrastructure verticals. The steepest expansion runs through silane-siloxane hybrids displacing epoxy in marine exposure specifications.
Application:
Project scale and warranty liability exposure shape procurement channel selection and formulation tier specification.
- Infrastructure:State DOT agencies specify 10–20 year performance warranties for bridge decks, parking structures, and coastal marine installations. Silane-siloxane penetration depth requirements now match epoxy overlay durability metrics at lower lifecycle cost.
- Commercial:Retail, hospitality, and office construction prioritize gloss retention and color enhancement for visible concrete surfaces. Water-based acrylics gain share in California and Northeastern states where VOC thresholds constrain solvent-based alternatives.
- Residential:Driveway, patio, and basement applications favor DIY-accessible formulations with simplified surface preparation requirements.
- Industrial:Manufacturing floors and chemical containment areas specify epoxy and polyurethane systems for maximum abrasion and spill resistance.
Infrastructure applications anchor manufacturer technical credibility. Commercial verticals generate the fastest volume climb as construction activity concentrates in Texas, California, and Florida.
End User:
Procurement authority and technical specification control fragment across project delivery models.
- Contractors:Commercial and infrastructure applicators select sealers based on spray equipment compatibility, cure time, and manufacturer warranty backing. OSHA silica rule compliance has shifted preference toward low-dust surface preparation methods that pair with water-based technologies.
- Architects:Design professionals specify sealer chemistry in construction documents, particularly for visible concrete in commercial and institutional projects. Digital specification platforms now embed maintenance interval data into BIM workflows.
- Government:State DOT and federal agency procurement runs through qualified product lists with pre-approved chemistry categories and active solids minimums.
- DIY Consumers:Retail channel purchasers prioritize one-coat coverage claims and simplified application instructions for residential maintenance projects.
Contractor networks control the recurring reapplication revenue base. Architect specification influence is climbing fastest as digital tools embed lifecycle cost analysis into early design phases.
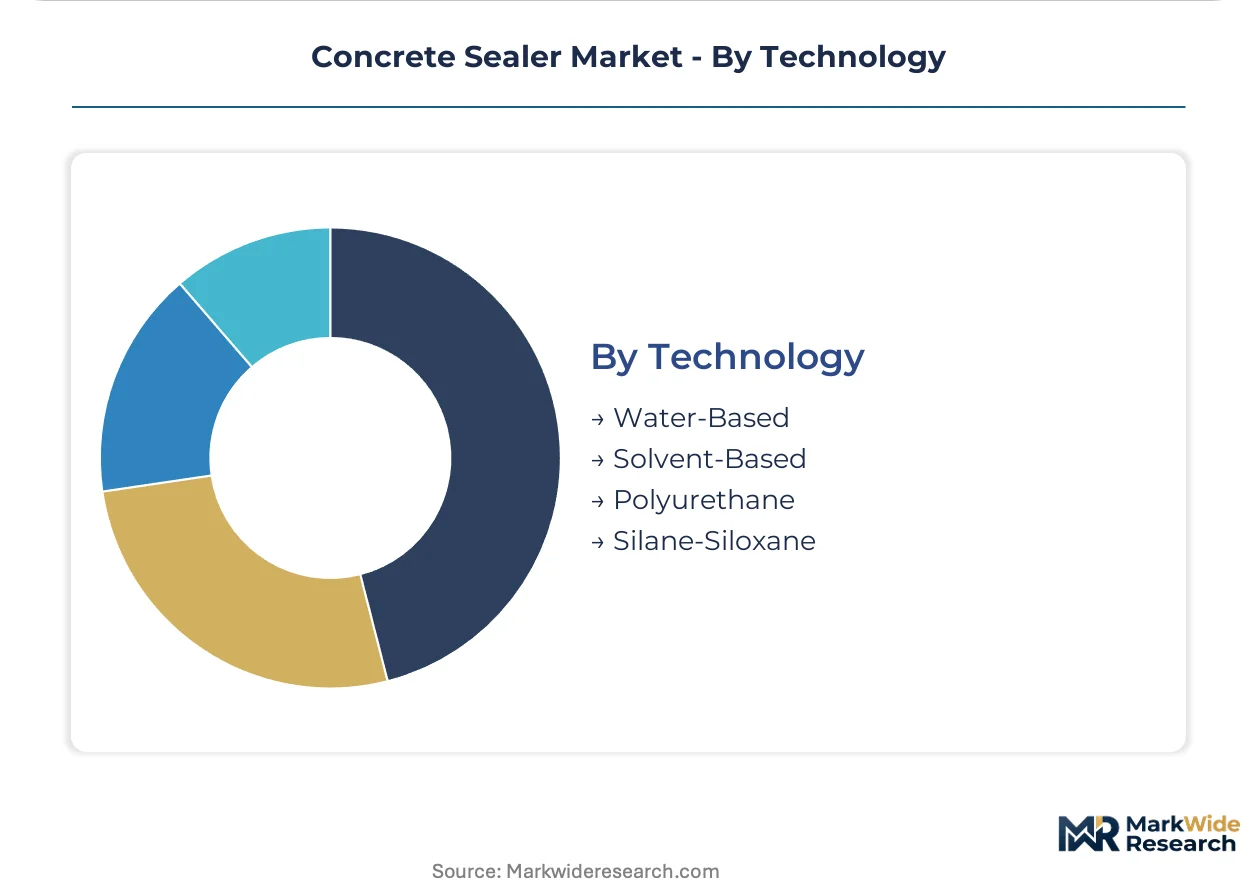
Technology:
Carrier chemistry and active solids formulation determine VOC compliance, penetration performance, and regional manufacturing viability.
- Silane-Siloxane:Hybrid penetrating chemistry achieves hydrophobic performance at 5–15% active solids concentration, enabling water-based delivery systems that satisfy California CARB sub-100 g/L mandates. State DOT engineers now specify these treatments for bridge decks previously requiring solvent-borne epoxy.
- Water-Based:Acrylic and polyurethane emulsions deliver VOC compliance below regulatory thresholds in California and Northeastern states. Surface preparation workflow changes under OSHA silica rules favor low-dust application methods compatible with water-based technologies.
- Solvent-Based:Traditional carriers provide faster cure times and deeper penetration in unregulated jurisdictions, but face stranded asset risk as state-level low-VOC adoption spreads.
- Polyurethane:Aliphatic and aromatic systems deliver maximum UV stability and abrasion resistance for high-traffic commercial floors.
Water-based lines secure the regulatory-compliant installed base. Silane-siloxane penetration is gaining share fastest as performance validation collapses the infrastructure specification barrier against epoxy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Infrastructure buyers in Texas and Florida prioritize lifecycle durability over unit cost, while residential markets in California and the Northeast trade performance for VOC compliance. Emerging construction economies show the steepest cost elasticity, driving specification of lower-solids formulations.
United States
Bridge deck rehabilitation and data center slab construction anchor demand in Texas, California, and Florida. EPA 40 CFR Part 59 VOC regulations and state-level CARB mandates force chemistry transitions below 100 g/L thresholds. Houston-Galveston petrochemical corridors supply active solids precursors, though hurricane-season disruption risk concentrates inventory management challenges along the Gulf Coast.
Germany
Industrial flooring renovation and commercial warehouse construction sustain specification volume for high-performance penetrating systems. REACH chemical registration requirements constrain solvent-based formulation imports while elevating compliance costs for non-EU suppliers. The Rhine-Ruhr industrial belt concentrates applicator networks serving manufacturing facility maintenance programs.
China
High-speed rail viaduct maintenance and coastal infrastructure corrosion protection drive silane-siloxane penetration. MIIT industrial standards and provincial environmental bureaus enforce VOC emission controls in Yangtze River Delta manufacturing zones. Shanghai-Pudong construction chemical clusters dominate domestic formulation capacity, with state-owned enterprises controlling specification for transportation infrastructure.
India
Metro rail expansion and commercial real estate development in Mumbai, Delhi-NCR, and Bangalore generate specification pull for chloride-resistant treatments. BIS certification requirements and state pollution control board mandates create compliance fragmentation across jurisdictions. Gujarat chemical manufacturing corridors supply acrylic resin feedstocks, though quality inconsistency constrains premium infrastructure adoption.
United Arab Emirates
Coastal marine exposure and hyperscale data center construction favor vapor-suppressing penetrating formulations. MOHAP chemical product registration and municipal green building codes elevate water-based specification share. Dubai Industrial City manufacturing zones host regional formulation facilities serving Gulf Cooperation Council infrastructure projects.
Concrete Sealer Market Vendor Landscape
Capability concentration sits with specialized chemistry developers; scale advantage sits with diversified coatings conglomerates. The market structures around three tiers: integrated construction chemical multinationals with waterproofing-to-sealer system bundling, regional formulators with applicator network relationships, and commodity resin suppliers competing on feedstock access. Strategic moves center on water-based capacity expansion in regulatory-constrained jurisdictions and maintenance service program integration to capture reapplication revenue.
Within the diversified coatings tier, PPG Industries Inc. and RPM International Inc. occupy positions anchored by architectural distribution infrastructure. BASF SE and Sika AG exemplify integrated construction chemical specialists with technical specification influence over engineering firm procurement. Evonik Industries AG represents the active solids chemistry depth archetype, supplying silane-siloxane precursors to downstream formulators. These anchors illustrate how competitive positioning splits between formulation-to-application integration and specialty chemical supply control.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| Mapei S.P.A. |
| BASF SE |
| Prosoco Inc. |
| Arkema |
| Sika AG |
| Evonik Industries AG |
| Laticrete International Inc. |
| RPM International Inc. |
| Others |
Supply Flow & Price Mechanics
Houston-Galveston petrochemical corridors concentrate active solids precursor capacity, concentrating pricing power among Gulf Coast formulators while exposing downstream buyers to hurricane-season disruption premiums. Regional manufacturers leverage this geographic chokepoint to defend formulation margins even as water-based chemistry transitions compress solvent-based product profitability.
Pricing Analysis
Reapplication service contracts and extended warranty programs now generate the dominant lifetime value capture for applicator networks with maintenance infrastructure. Three-tier pricing structure across premium silane-siloxane systems, standard water-based acrylics, and economy solvent-based lines differentiates by active solids concentration and certification grade. Cost compression in solvent-based tiers is intensifying because California CARB sub-100 g/L mandates strand inventory in the largest state economy. DIY residential buyers exhibit the highest price sensitivity, while infrastructure DOT procurement prioritizes lifecycle durability over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for silane-siloxane precursor imports. Active solids production draws from the United States Gulf Coast, Germany's Rhine-Ruhr industrial belt, and China's Yangtze River Delta manufacturing zones. Acrylic resin and epoxy precursor feedstocks hinge on crude oil index volatility, creating margin instability for domestic producers. Distribution runs through manufacturer-direct specification channels for infrastructure projects and regional distributor networks for commercial and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among state DOT agencies and hyperscale data center developers, consolidating procurement volume and elevating specification leverage over formulation suppliers.
For Market Incumbents: Build switching-cost moats through integrated waterproofing-to-sealer system bundling that locks infrastructure projects into recurring maintenance contracts. Defend against water-based chemistry transitions by expanding Midwest and Southeast manufacturing capacity ahead of northeastern state low-VOC adoption waves. Prioritize applicator certification program proliferation to constrain labor mobility and protect specification pull-through. For New Entrants and Emerging Players: India's metro rail expansion corridors offer the most penetrable geographic entry point for chloride-resistant penetrating formulations. Target state pollution control board compliance fragmentation as a regulatory arbitrage opportunity. Pursue joint venture structures with Gujarat chemical manufacturing clusters to secure acrylic resin feedstock access without capital-intensive greenfield investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors silane-siloxane chemistry specialists with validated DOT specification records. Long-term viability rests on water-based portfolio depth as regulatory adoption spreads. Acquisition targets should demonstrate active solids R&D capabilities and established applicator network relationships. Monitor state-level low-VOC mandate adoption timelines as the primary inflection indicator for stranded solvent-based asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Capacity Expansion | California CARB compliance positions manufacturers for northeastern state adoption waves. |
| Reapplication Service Program Integration | Expiring DOT warranties create recurring revenue capture for applicator networks with digital inspection capabilities. |
| Silane-Siloxane Chemistry R&D Investment | Performance validation against epoxy overlays unlocks infrastructure specification previously reserved for thermoset systems. |
| Applicator Network Certification Proliferation | Manufacturer-specific training constraints protect specification pull-through and inflate competitor project mobilization costs. |
| Backward Integration into Active Solids Precursors | Gulf Coast petrochemical corridor proximity secures supply continuity against hurricane-season disruption patterns. |
Methodological Framework
The analysis maps penetrating sealer, film-forming acrylic, and epoxy formulation sub-sectors, each validated through plant managers, DOT specification engineers, commercial contractor procurement leads, and distribution channel partners. Primary interview intelligence triangulates against customs and trade data, American Chemistry Council sector reports, SEC 10-K filings, and state DOT qualified product list databases. Bottom-up volume modeling and top-down value reconciliation ensure cross-validation across the analysis window.
Fixed assumptions include EPA 40 CFR Part 59 VOC regulatory thresholds and ASTM C309 moisture-retention standards, while varying infrastructure spending allocation across Texas, California, and Florida. Segmentation dimensions span formulation chemistry, carrier technology, application vertical, and end-user procurement authority. CAGRs derive from historical specification volume trajectories and projected DOT rehabilitation cycle timing, with petrochemical feedstock cost indices and state-level regulatory adoption curves as primary forecast inputs.
Practitioners should monitor California CARB enforcement intensity and northeastern state SCM adoption timelines for early signals of chemistry portfolio obsolescence. Forecasts reflect these documented assumptions alongside OSHA silica rule implementation pace and hurricane-season supply disruption frequency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Bollard Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Moisture Resistant Gypsum Board Market
Building & Construction Materials
Global Anchors and Grouts Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Drinking Water Pipe Repair Market